
 United States Sports and Energy Drinks Market | 2026-2036
United States Sports and Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sports and Energy Drinks Market Intelligence
Subscription-based replenishment programs is rebalancing how brands secure recurring revenue beyond single-unit impulse purchases. PepsiCo, Inc. leverages its direct-to-consumer platform to lock in monthly delivery cohorts. Monster Beverage Corporation anchors its growth through convenience store exclusivity agreements that reduce shelf-space competition. Red Bull GmbH differentiates by embedding event sponsorship rights into its retail distribution contracts.
United States sports and energy drinks comprise functional beverages formulated with carbohydrates, electrolytes, caffeine, taurine, B-vitamins, and amino acids, manufactured through aseptic cold-fill or hot-fill processing to preserve active ingredient stability, designed primarily to enhance athletic performance, mental alertness, or recovery. Isotonic formulations and energy shots capture divergent growth trajectories, with isotonic drinks benefiting from post-workout recovery positioning while energy shots extract premium pricing from on-the-go consumption occasions. Supermarkets and online retail represent contrasting margin architectures, as supermarkets demand slotting fees that compress profits whereas online channels enable first-party data collection for personalized reorder prompts.
The FDA oversees caffeine disclosure thresholds and novel ingredient safety assessments, while the USDA regulates organic certification claims for plant-based energy formulations, and state-level bottle deposit laws in California and New York shape packaging format decisions. These overlapping frameworks elevate compliance costs for new entrants but also create defensible moats for established operators with regulatory affairs infrastructure. Stakeholders must monitor how the FDA's anticipated caffeine concentration caps could force reformulation of existing SKUs before competitors preemptively launch compliant alternatives.
Market Dynamics
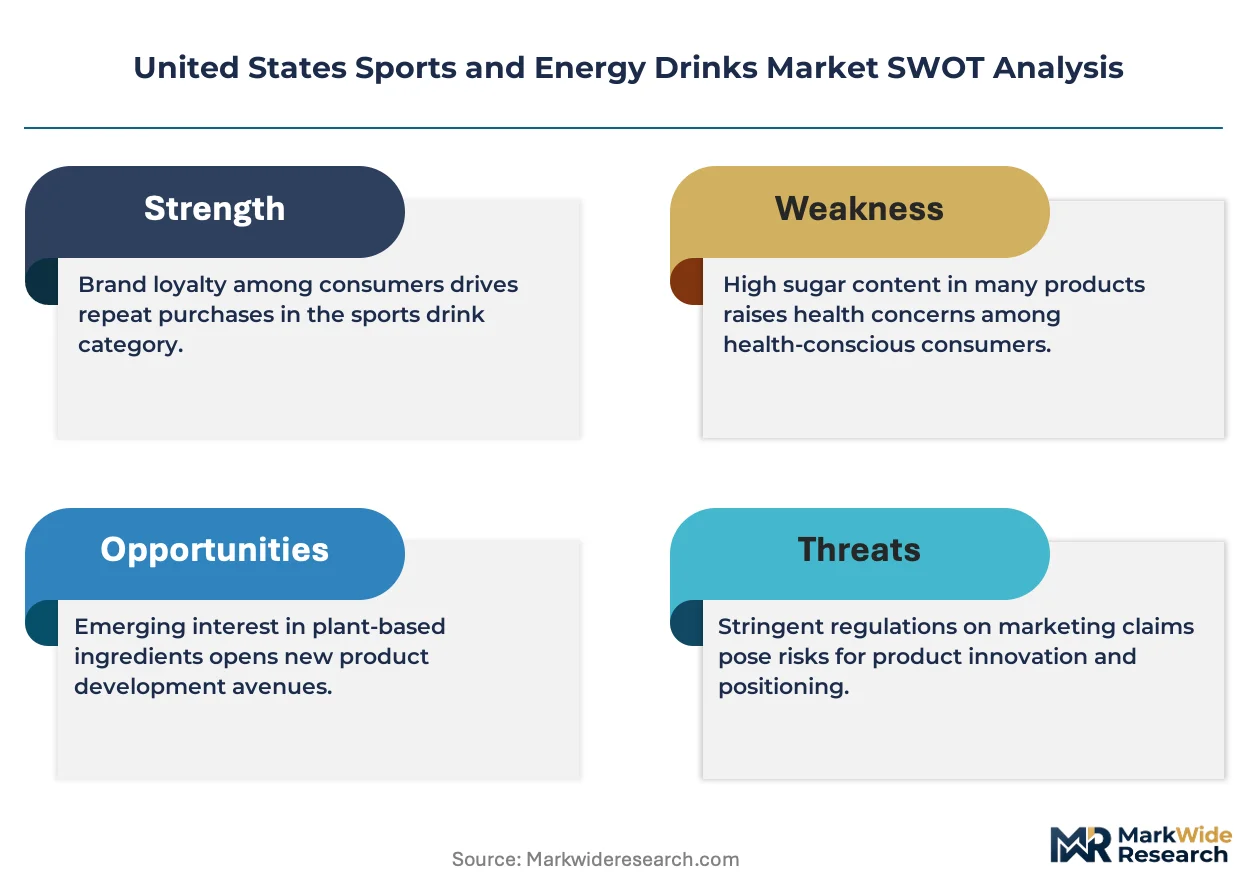
Fitness culture normalization and FDA caffeine disclosure pressure are compressing formulation cycles while expanding functional ingredient portfolios. Brands now balance performance claims against evolving labeling mandates.
Growth Catalysts
- Electrolyte-enhanced recovery positioning:Post-workout hydration protocols in collegiate athletics and CrossFit affiliates are normalizing isotonic consumption beyond traditional sports use.
- California bottle deposit infrastructure:State-level redemption systems incentivize aluminum can formats that reduce per-unit shipping costs and enable single-serve premium pricing.
- USDA organic certification pathway:Plant-based energy formulations leveraging certified organic claims capture shelf-space premiums in natural grocery channels.
Market Restraints
- Caffeine input cost volatility:Synthetic caffeine supply concentrates in Chinese pharmaceutical intermediaries, exposing margins to export tariff fluctuations and currency swings.
- Aseptic cold-fill equipment scarcity:Limited domestic manufacturers of sterile bottling lines extend facility commissioning timelines and elevate capital barriers for new entrants.
- FDA novel ingredient pre-market scrutiny:GRAS self-affirmation pathways for adaptogenic additives face intensifying safety data requirements that delay launch schedules.
Strategic Opportunities
- Texas convenience store channel depth:Exurban Dallas-Fort Worth and Houston corridors exhibit underpenetrated energy shot placement relative to metropolitan California benchmarks.
- Direct-to-consumer subscription mechanics:First-party data capture enables personalized replenishment algorithms that reduce customer acquisition costs versus retail slotting fee structures.
- Dual carbon goals convergence:Renewable energy procurement for manufacturing facilities aligns with retailer ESG scorecard requirements and unlocks preferred vendor status.
Industry Challenges
- Flavor chemist talent scarcity:Masking bitterness from functional additives (taurine, B-vitamins) requires specialized formulation expertise concentrated in legacy beverage conglomerates.
- Legacy ERP integration friction:Subscription platform rollout demands real-time inventory synchronization with co-packer networks that operate on batch-scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sports and Energy Drinks Market |
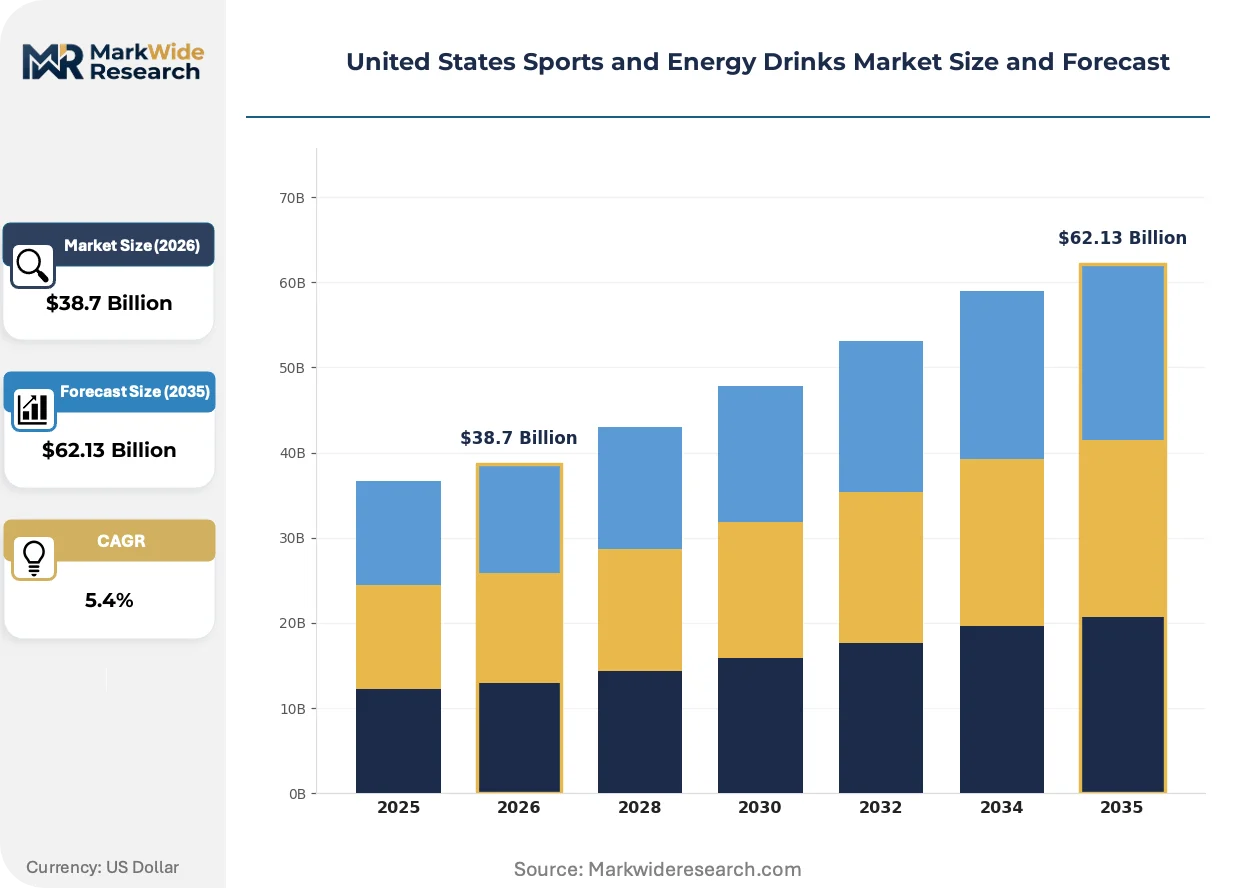
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypertonic, Energy Shots, Protein Drinks Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Customer Type: Athletes, Fitness Enthusiasts, Casual Consumers, College Students Packaging Type: Cans, Bottles, Pouches, Multi-Packs |
| Companies Covered | PepsiCo, Inc., The Coca-Cola Company, Red Bull GmbH, Monster Beverage Corporation, Rockstar Energy Inc., National Beverage Corp., Keurig Dr Pepper Inc., Living Essentials LLC, AriZona Beverages USA, LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sports and Energy Drinks Market Strategic Shifts & Innovations
Formulation transparency and processing technology are compressing development timelines while expanding permissible ingredient claims. Three forces are restructuring competitive positioning.
Microencapsulation technology is integrating fat-soluble vitamins and adaptogens into aqueous bases without emulsion separation. Functional beverage startups and contract manufacturers are adopting this process to reduce stability testing duration. The technology is enabling cleaner label claims that previously required synthetic stabilizers.
The FDA's anticipated caffeine concentration caps are forcing preemptive reformulation of existing energy drink SKUs ahead of formal rulemaking. Portfolio managers are diluting caffeine loads and compensating with amino acid blends to preserve perceptual efficacy. California and New York retail buyers are already requesting compliant documentation for shelf resets.
Subscription replenishment models are displacing impulse-driven convenience store purchasing among core fitness demographics. Direct-to-consumer platforms capture consumption velocity data that enables predictive reorder prompts before stockout. This behavioral shift concentrates most visibly in metropolitan gym corridors where delivery logistics achieve same-day feasibility.
United States Sports and Energy Drinks Market Segmentation
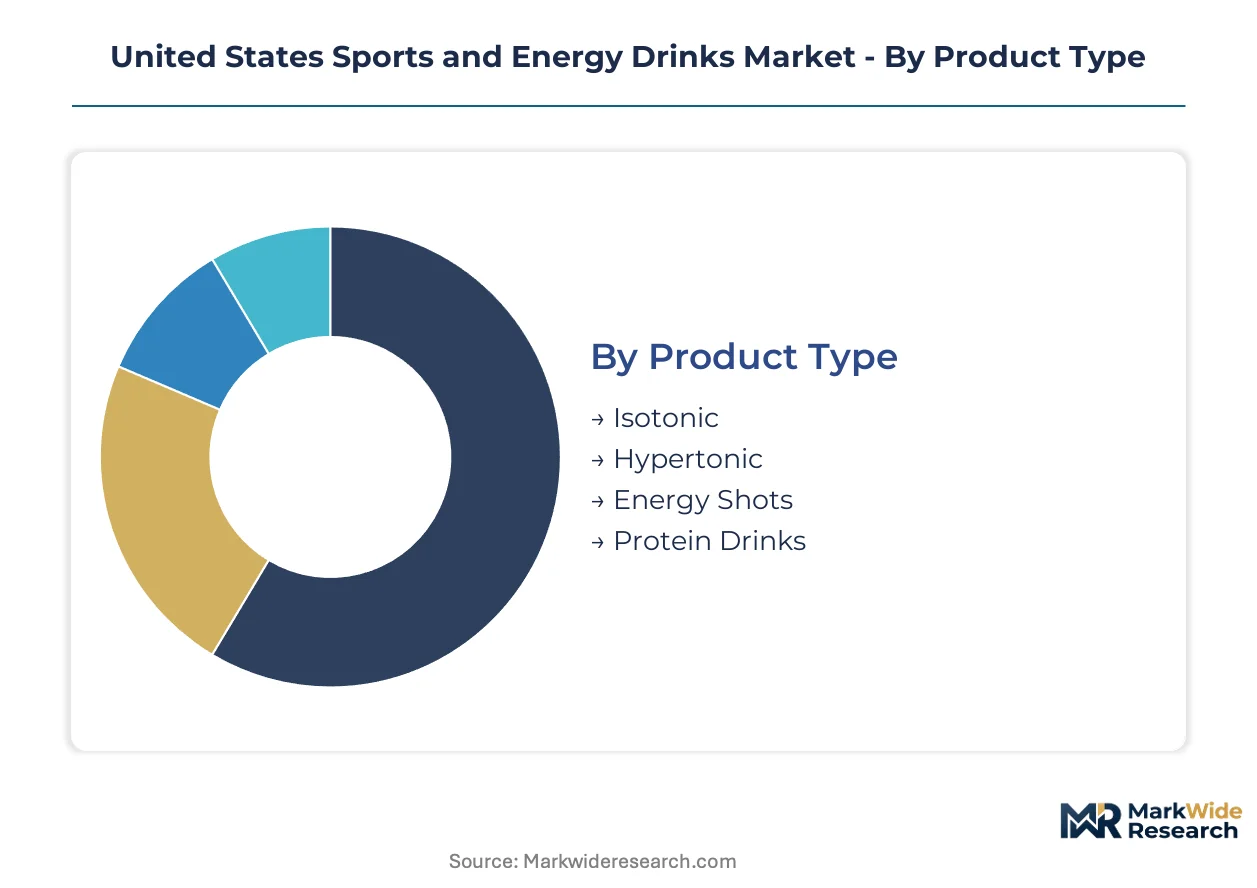
Segmentation in the United States sports and energy drinks market reveals how formulation specifications, channel economics, and consumption occasions create distinct margin profiles. Each dimension carries unique regulatory burdens and capital requirements that shape competitive entry barriers.
Product Type:
FDA caffeine disclosure thresholds and USDA organic certification pathways impose divergent compliance costs across functional beverage categories.
- Isotonic:Electrolyte-balanced formulations with 6-8% carbohydrate concentration mirror plasma osmolality for rapid gastric emptying. Collegiate athletic programs and CrossFit affiliates in California and Texas concentrate procurement, driven by post-workout recovery protocols that normalize consumption beyond competitive sports.
- Energy Shots:Concentrated 2-3 ounce servings deliver 100-200mg caffeine with amino acid blends in shelf-stable formats. Exurban Dallas-Fort Worth corridors show underpenetrated placement relative to California benchmarks, creating whitespace for convenience store exclusivity agreements.
- Hypertonic:Higher solute concentration exceeds plasma osmolality, delaying absorption but extending energy release for endurance applications.
- Protein Drinks:Whey or plant-based isolates target muscle protein synthesis windows with 20-30g protein per serving.
Leading the category by volume: Isotonic. Growing fastest: Energy Shots.
Distribution Channel:
Channel selection determines working capital intensity and customer data ownership, with direct-to-consumer platforms capturing lifetime value unavailable through third-party retail.
- Convenience Stores:Impulse-driven single-serve purchases generate highest velocity in Texas and California fuel station networks. Slotting fees and exclusivity agreements compress margins but lock out competitor shelf space.
- Online Retail:Subscription replenishment mechanics enable predictive reorder algorithms and first-party data capture. Metropolitan gym corridors achieve same-day delivery feasibility that reduces stockout-driven churn.
- Supermarkets:Multi-pack formats and seasonal promotional cycles demand inventory forecasting sophistication.
- Specialty Stores:Natural grocery channels reward USDA organic certification with shelf-space premiums and educated consumer demographics.
Dominating by transaction velocity: Convenience Stores. Expanding most quickly: Online Retail.
Customer Type:
Usage occasion and consumption frequency separate high-loyalty fitness segments from price-sensitive casual purchasers.
- Fitness Enthusiasts:Weekly gym attendance drives habitual isotonic consumption with brand stickiness from personalized subscription programs. This cohort shows highest willingness to pay for electrolyte-enhanced and adaptogen-fortified variants.
- College Students:Cram session and social consumption occasions favor energy shots and value-priced multi-packs. Campus proximity to convenience stores shapes brand trial and early habit formation.
- Athletes:Institutional procurement through collegiate and professional programs demands batch-tested certification for banned substance compliance.
- Casual Consumers:Occasional functional beverage use responds to promotional pricing and flavor innovation rather than performance claims.
Highest lifetime value concentration: Fitness Enthusiasts. Steepest expansion trajectory: College Students.
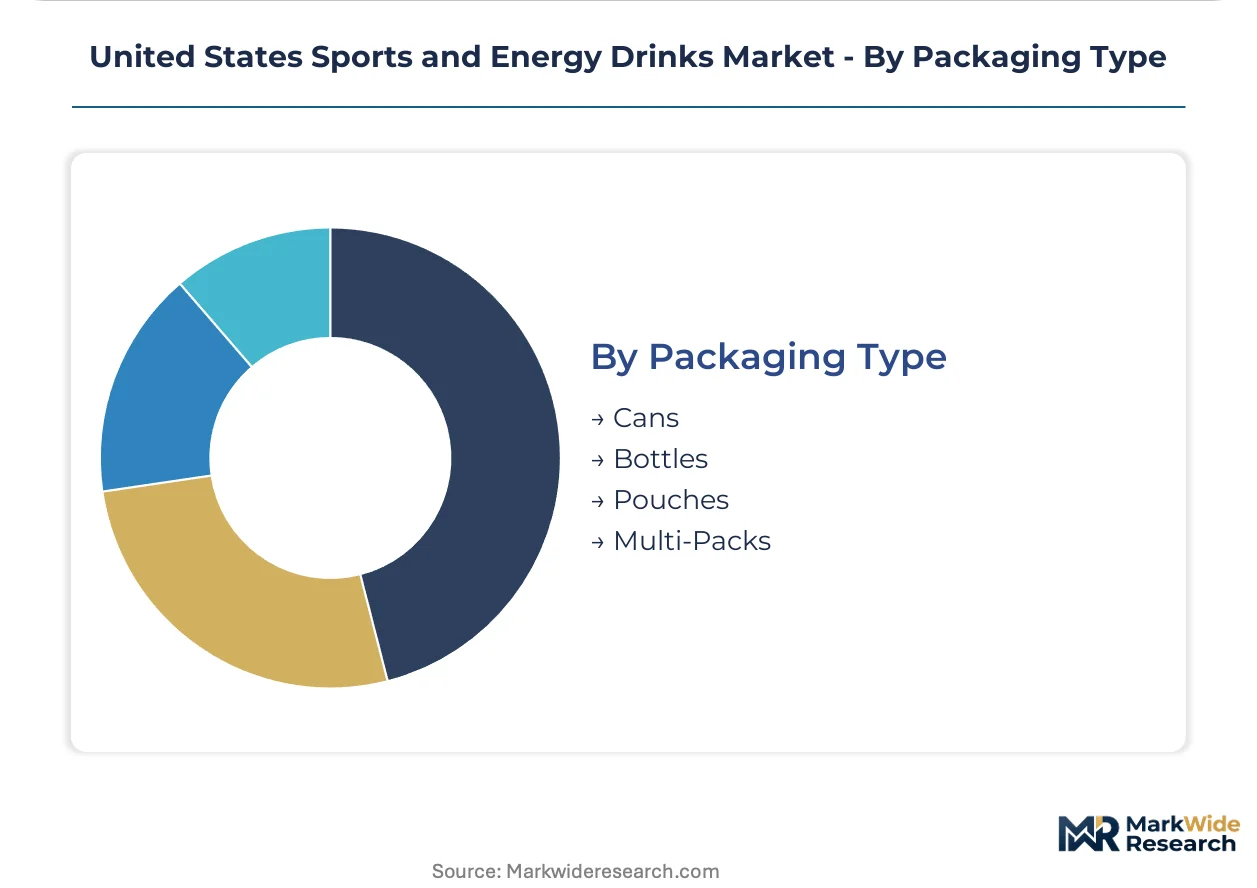
Packaging Type:
Format decisions interact with state-level bottle deposit laws and shipping economics to determine regional profitability.
- Cans:Aluminum formats align with California and New York redemption systems that reduce per-unit shipping costs and enable single-serve premium pricing. Aseptic cold-fill compatibility preserves active ingredient stability without synthetic stabilizers.
- Bottles:PET and glass variants accommodate larger volume isotonic formats for gym and home consumption occasions.
- Pouches:Flexible packaging reduces shipping cube for outdoor and military applications where weight matters.
- Multi-Packs:Bundled units capture pantry-loading behavior and reduce per-transaction customer acquisition costs for subscription platforms.
Preferred by volume: Cans. Gaining share fastest: Multi-Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing capacity clusters near major consumption corridors, while formulation R&D concentrates in states with dense fitness demographics and favorable regulatory environments. Production logistics favor co-packer networks distributed across Sun Belt states to minimize freight costs to convenience store channels.
California
CrossFit affiliates and collegiate athletic programs in Los Angeles and San Francisco metro areas drive isotonic procurement volumes. The state's bottle deposit redemption system incentivizes aluminum can formats that reduce shipping cube. San Diego and Orange County host contract manufacturing clusters serving organic-certified energy formulations.
Texas
Exurban Dallas-Fort Worth and Houston corridors exhibit underpenetrated energy shot placement relative to national benchmarks. Convenience store exclusivity agreements lock in shelf space across fuel station networks. Austin's fitness culture normalizes subscription replenishment models among tech-sector professionals.
New York
Metropolitan gym density supports same-day delivery feasibility for direct-to-consumer platforms. The state's bottle deposit infrastructure shapes packaging format decisions for national brands. Buffalo and Rochester manufacturing nodes supply aluminum can production for Northeast distribution.
Florida
Retiree and tourist demographics create distinct consumption occasions favoring low-caffeine functional beverages. Miami-Dade and Broward counties concentrate Latin American brand trial and import distribution. Tampa and Orlando host co-packer facilities serving southeastern convenience store chains.
Illinois
Chicago's logistics hub status anchors Midwest distribution networks for national brands. Collegiate athletics procurement through Big Ten institutions drives batch-tested certification requirements. Rockford and Peoria manufacturing corridors supply PET bottle formats for multi-pack supermarket channels.
United States Sports and Energy Drinks Market Key Industry Players
Top-tier vendors anchor mass-market shelf space through convenience store exclusivity agreements, while mid-tier specialists occupy natural grocery and direct-to-consumer channels. The vendor base stratifies across three archetypes: diversified beverage conglomerates with regulatory affairs infrastructure, pure-play energy specialists with event sponsorship assets, and plant-based startups leveraging USDA organic certification. Dominant competitive moves include portfolio diversification into functional hydration and strategic partnerships with subscription platform providers.
Within the diversified beverage conglomerate tier, PepsiCo, Inc. and The Coca-Cola Company represent archetypal scale advantages in slotting fee negotiations and co-packer network access. Monster Beverage Corporation and Red Bull GmbH occupy positions as pure-play specialists with embedded distribution contracts and sponsorship-derived brand equity. Among mid-tier participants, Keurig Dr Pepper Inc. and National Beverage Corp. exemplify regional channel depth strategies that defend against national brand encroachment.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| The Coca-Cola Company |
| Red Bull GmbH |
| Monster Beverage Corporation |
| Rockstar Energy Inc. |
| National Beverage Corp. |
| Keurig Dr Pepper Inc. |
| Living Essentials LLC |
| AriZona Beverages USA, LLC |
| Others |
Cost & Logistics Intelligence
Fitness enthusiasts concentrated in California and Texas metro corridors anchor the dominant subscription-plus-impulse hybrid pricing model, where direct-to-consumer replenishment programs extract lifetime value while convenience store single-serve transactions capture immediate consumption occasions.
Pricing Analysis
Cost-down pressure on standard isotonic tiers accelerates because slotting fee inflation at California and Texas fuel station networks compresses per-unit margins for mass-market SKUs. Three-tier pricing structure across premium electrolyte-enhanced, standard carbohydrate-based, and economy private-label levels separates formulation sophistication from basic hydration. Synthetic caffeine input volatility from Chinese pharmaceutical intermediaries intensifies margin tightening across energy shot portfolios. Casual consumers in exurban corridors exhibit highest price sensitivity, while fitness enthusiasts demonstrate lowest elasticity for personalized subscription offerings.
Supply Chain Analysis
Flavor chemist talent scarcity in legacy beverage conglomerates headquartered in California and New York constrains formulation capacity for masking functional additive bitterness. Domestic manufacturing draws from co-packer networks concentrated in Sun Belt states, with aluminum can production anchored in Buffalo and Rochester facilities and PET bottling clustered near Chicago distribution hubs. Synthetic caffeine sourcing rests on Chinese pharmaceutical intermediaries, creating single-source vulnerability to export tariff fluctuations. Distribution runs through convenience store fuel station networks in Texas and California, supplemented by direct-to-consumer fulfillment centers positioned for same-day delivery feasibility in metropolitan gym corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic cold-fill equipment scarcity among domestic sterile bottling manufacturers props pricing power for established operators with commissioned facility access, constraining new entrant capacity expansion.
For Market Incumbents: Cement exclusivity agreements with convenience store fuel station networks across underpenetrated Texas exurban corridors before emerging entrants secure shelf-space allocations. Deepen backward integration into aluminum can manufacturing through preferred supplier arrangements with Buffalo and Rochester production nodes to defend against packaging cost volatility. For New Entrants and Emerging Players: Specialty natural grocery channel partners in California offer whitespace for USDA organic-certified energy formulations targeting premium shelf-space premiums. Focus initial penetration on collegiate athletic procurement programs in Texas and California demanding batch-tested isotonic certification, leveraging direct-to-consumer subscription mechanics to bypass slotting fee barriers. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with installed aseptic cold-fill capacity and established co-packer relationships in Sun Belt states. Monitor FDA caffeine concentration cap rulemaking progression as inflection indicator for preemptive reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Integration | Predictive reorder algorithms reduce customer acquisition costs versus retail slotting structures. |
| Convenience Store Exclusivity Expansion | Shelf-space agreements in Texas exurban corridors lock out competitor placement. |
| USDA Organic Certification Investment | Natural grocery channel premiums in California reward certified plant-based formulations. |
| Aseptic Cold-Fill Capacity Addition | Sterile bottling line commissioning addresses equipment scarcity constraining new entrants. |
| Direct-to-Consumer Geographic Expansion | Same-day delivery feasibility in metropolitan gym corridors concentrates fitness enthusiast lifetime value. |
Research Approach
SEC 10-K filings, Nielsen retail audit data, and FDA GRAS notification databases formed the secondary backbone, cross-referenced with primary interviews involving beverage brand managers, convenience store category buyers, co-packer operations directors, and regulatory affairs specialists. Bottom-up and top-down triangulation validated volume estimates against channel shipment data and consumption velocity metrics.
Bottom-up modeling aggregated segment-level projections across formulation type, distribution channel, and customer archetype dimensions, while top-down analysis anchored aggregate market trajectories against macroeconomic indicators. CAGRs were derived from normalized growth rate distributions across the projection horizon, with inputs including collegiate athletic procurement cycles, convenience store penetration rates, and subscription platform adoption curves.
Caveats apply where FDA caffeine concentration cap implementation timing or synthetic caffeine tariff escalations could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Low Fat Drinks Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Electrolyte Mixes Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
Apple Cider Vinegar Market
Beverages
GCC Bottled Water Market
Beverages
Beverage Multipacks Market
Beverages
United States and Australia Coconut Water Market
Beverages
Tonic Water Market
Beverages
Bottled Water Processing Market
Beverages
Carbonated Soft Drinks Market
Beverages
Aloe Vera Drinks Market
Beverages
Soft Serves Market
Beverages
North America Yerba Mate Market
Beverages
Semillon Market