
 Apple Cider Vinegar Market | 2026-2036
Apple Cider Vinegar Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Cider Vinegar Market Analysis
USDA Organic certification is rotating market access as non-compliant suppliers lose shelf placement in mainstream retail. Bragg Live Food Products leverages its raw-unfiltered heritage to sustain premium positioning across natural grocery channels. Goli Nutrition competes through gummy format innovation, while The Kraft Heinz Company anchors mass-market volume via distilled vinegar distribution networks.
Apple cider vinegar comprises fermented apple juice containing 4-6% acetic acid by volume, produced through a two-stage fermentation process converting sugars first to alcohol then to acid, functioning primarily as a food preservative, digestive aid, and cleaning agent. The organic product type commands margin premiums as health enthusiasts reject distilled variants stripped of mother culture. Application demand tilts toward dietary supplements as beverage manufacturers infuse functional shots with raw unfiltered stock.
FDA labeling oversight and USDA National Organic Program standards govern acetic acid declarations and fermentation method claims, while state-level cottage food laws patchwork small-producer compliance burdens. The EU Organic Regulation shapes export eligibility for North American bottlers seeking European health retail placement. Stakeholders must monitor emerging probiotic classification debates that could reclassify raw vinegar as a supplement rather than a food.
Market Dynamics
USDA National Organic Program enforcement is squeezing shelf access for non-compliant suppliers, forcing a two-tier market split between certified raw-unfiltered stock and commodity distilled vinegar. This regulatory pressure concentrates procurement power among bottlers with verified fermentation documentation.
Growth Catalysts
- Functional beverage infusion:Health shot manufacturers are expanding raw unfiltered vinegar procurement for digestive wellness positioning. This pulls volume through natural grocery channels.
- EU Organic Regulation alignment:North American exporters are retrofitting facilities to meet European health retail eligibility requirements, opening cross-border placement.
- Preservative substitution:Clean-label food manufacturers are replacing synthetic additives with acetic acid-rich vinegar in sauces and dressings.
Market Restraints
- Apple supply concentration:Washington State and Michigan orchards dominate raw material sourcing, creating weather-driven price volatility for juice concentrate.
- Mother culture instability:Unpasteurized variants require cold-chain logistics that inflate distribution costs versus shelf-stable distilled alternatives.
- Acetic acid content caps:FDA labeling thresholds restrict potency claims, capping functional positioning for supplement-grade products.
Strategic Opportunities
- Probiotic reclassification pathway:Raw vinegar containing live cultures could shift from food to supplement classification, unlocking pharmacy channel placement.
- Direct-to-consumer subscription:Wellness platforms are bypassing retail slotting fees through recurring shipment models for tonic and gummy formats.
- Sustainable packaging mandates:California's recycled content requirements are accelerating glass-to-aluminum transitions for functional beverage lines.
Industry Challenges
- Organic certification backlog:USDA-accredited bodies face 14-18 month approval queues, delaying new supplier market entry.
- Fermentation specialist scarcity:Master vinegar makers with mother culture maintenance expertise command premium wages that strain mid-tier operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Cider Vinegar Market |
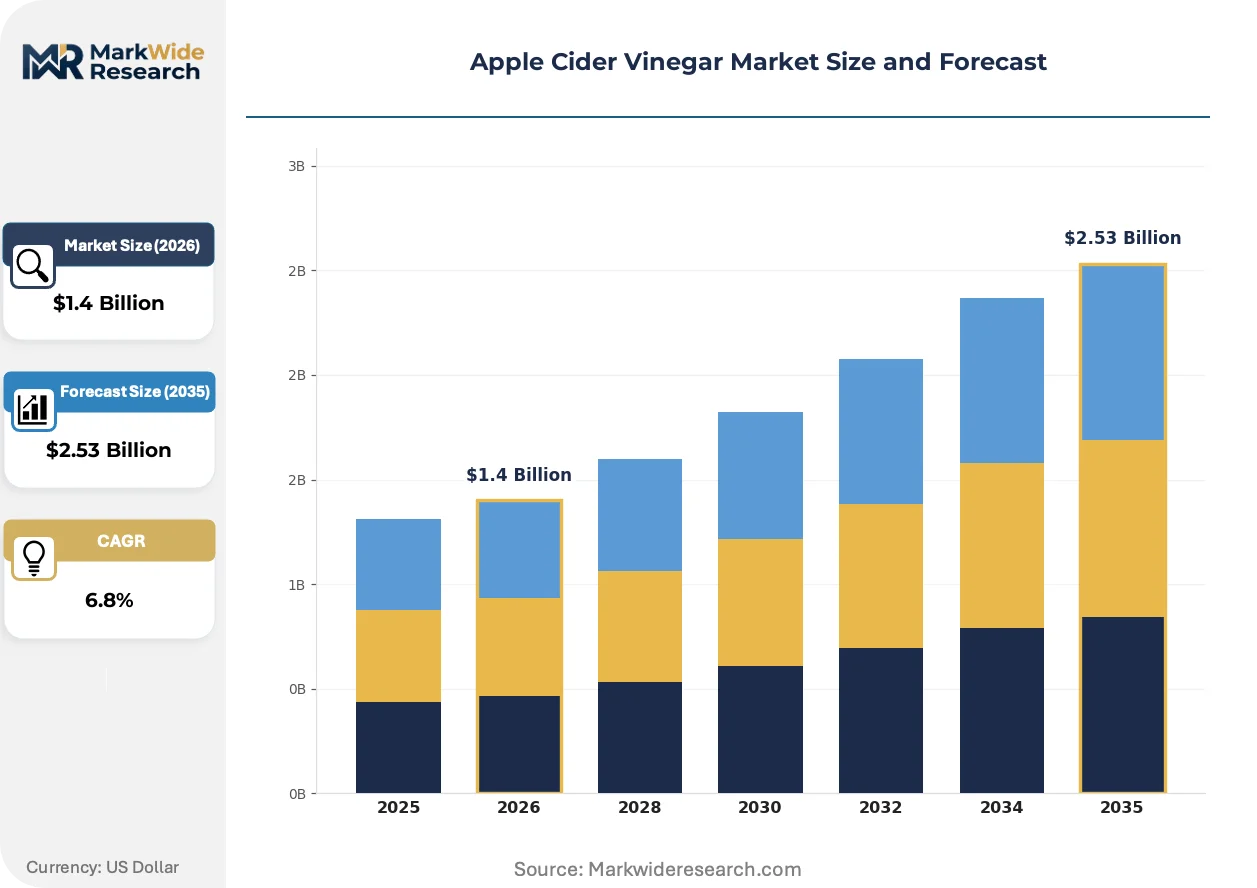
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Raw, Distilled, Unfiltered Application: Food Preservation, Dietary Supplement, Household Cleaning, Hair Care Packaging Type: Glass Bottle, Plastic Bottle, Bulk Container, Sachets End User: Retail Consumers, Food Service Providers, Health Enthusiasts, Beverage Manufacturers |
| Companies Covered | NOW Health Group, Dynamic Health Laboratories, Bragg Live Food Products, Goli Nutrition, Nature's Way Products, The Kraft Heinz Company, Lakewood Juices, Spectrum Organic Products, Eden Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Cider Vinegar Market Emerging Trajectories
Product format innovation and regulatory recalibration are fragmenting the traditional vinegar category into distinct wellness, culinary, and household verticals with divergent supply chain requirements.
Freeze-dried vinegar powder is decomposing liquid logistics constraints for supplement manufacturers. Capsule and gummy formulators are adopting this input to bypass stability issues with aqueous acetic acid. This conversion technology is compressing the addressable market for bottled tonics in travel and workplace consumption occasions.
USDA tightened its National Organic Program standards for acetic acid fermentation method claims in 2024. Bottlers must now document two-stage fermentation from apple juice rather than industrial alcohol feedstock. Raw-unfiltered specialists with heritage production methods are capturing shelf space as commodity suppliers lose certification.
Health food retailers are unbundling vinegar from general condiment aisles into dedicated digestive wellness sections. This merchandising shift elevates margin expectations and demands clinical-style packaging with probiotic colony-forming unit disclosures. California and New York natural grocery chains are piloting this format ahead of broader rollout.
Apple Cider Vinegar Market Segmentation
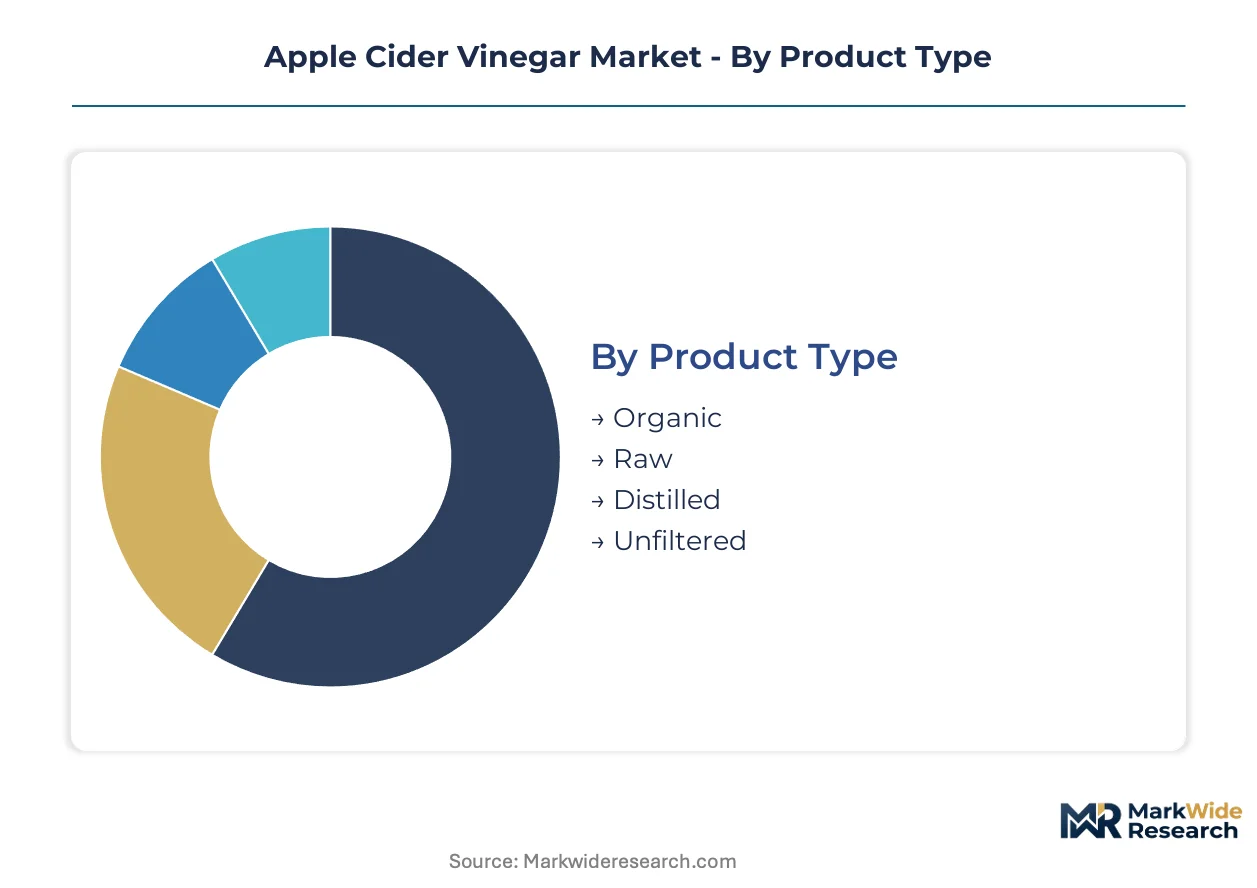
Regulatory bifurcation between certified organic and conventional grades fragments procurement strategies across the apple cider vinegar value chain. Bottlers must align fermentation documentation with USDA National Organic Program standards or accept relegation to commodity channels. This segmentation analysis examines how product certification, application use cases, packaging formats, and end-user requirements reshape competitive positioning.
Product Type:
USDA National Organic Program enforcement separates certified stock from distilled alternatives through fermentation documentation requirements.
- Organic:Two-stage fermentation from apple juice base meets USDA NOP standards for acetic acid claims. Washington State orchards supply concentrate to certified bottlers seeking natural grocery placement. Established volume favors Organic; emerging adoption favors Raw.
- Raw:Unpasteurized liquid retains mother culture with live acetic acid bacteria, requiring cold-chain logistics that inflate distribution costs. Health food retailers in California and New York pilot dedicated digestive wellness sections for this stock. Established volume favors Organic; emerging adoption favors Raw.
- Distilled:Heat-treated and filtered for neutral flavor profile, anchoring mass-market condiment aisles through shelf-stable logistics.
- Unfiltered:Cloudy appearance from retained sediment appeals to heritage positioning without full raw certification compliance.
Established volume favors Organic; emerging adoption favors Raw.
Application:
Functional beverage manufacturers are pulling volume from traditional culinary channels into wellness-positioned consumption occasions.
- Dietary Supplement:Freeze-dried powder and gummy formats bypass aqueous stability constraints for travel and workplace consumption. Capsule formulators adopt this input to compress addressable markets for bottled tonics. Supplement applications expand most quickly; Food Preservation retains volume concentration.
- Food Preservation:Acetic acid content delivers clean-label antimicrobial function in sauces, dressings, and pickled products. Clean-label manufacturers replace synthetic additives with vinegar-derived acidification. Supplement applications expand most quickly; Food Preservation retains volume concentration.
- Household Cleaning:Non-toxic surface treatment positioning leverages acetic acid antimicrobial properties for eco-conscious consumers.
- Hair Care:pH-balancing scalp treatments in premium personal care channels command margin premiums through wellness marketing.
Supplement applications expand most quickly; Food Preservation retains volume concentration.
Packaging Type:
California recycled content mandates accelerate format transitions that alter logistics economics across distribution tiers.
- Glass Bottle:Premium positioning in natural grocery channels supports heritage brand storytelling and mother culture visibility. California requirements are forcing aluminum transitions that threaten this format's dominance in functional beverage lines.
- Plastic Bottle:Lightweight logistics reduce freight costs for mass-market distilled vinegar distribution.
- Bulk Container:Food service and manufacturing procurement favors tote and drum formats for sauce production scale.
- Sachets:Single-serve powder packets target travel and workplace consumption with shelf-stable convenience.
Glass Bottle commands premium positioning; sachet formats are gaining share fastest.
End User:
Direct-to-consumer subscription platforms are bypassing retail slotting fees through recurring shipment models.
- Health Enthusiasts:Wellness platforms deliver tonic and gummy formats through subscription models that capture lifetime value. This segment drives raw-unfiltered procurement growth and probiotic reclassification advocacy.
- Beverage Manufacturers:Functional shot producers expand raw vinegar procurement for digestive wellness positioning in natural channels.
- Retail Consumers:Supermarket and natural grocery channels split between commodity distilled and premium certified stock.
- Food Service Providers:Commercial kitchens source bulk formats for back-of-house sauce and dressing production.
Retail Consumers anchor volume scale; Health Enthusiasts drive margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA National Organic Program enforcement is rotating shelf access across developed markets, while EU Organic Regulation alignment opens cross-border placement for certified bottlers. Washington State orchards anchor raw material sourcing, creating geographic concentration that shapes regional procurement strategies.
United States
California and New York natural grocery chains pilot dedicated digestive wellness sections for raw-unfiltered stock. FDA labeling oversight governs acetic acid declarations and fermentation method claims. Washington State and Michigan orchards dominate juice concentrate supply, with weather-driven price volatility rippling through bottler procurement.
Canada
Health Canada and PMRA standards govern antimicrobial claims for household cleaning applications. Provincial organic regulations patchwork compliance burdens for small producers entering retail channels. Ontario and British Columbia health food retailers expand shelf space for certified organic variants as consumer wellness spending rises.
Germany
EMA and EFSA standards shape supplement-grade classification debates for probiotic-containing vinegars. EU Organic Regulation enforcement tightens import eligibility for North American exporters. Bavaria and Baden-Württemberg natural food distributors retrofit facilities to meet documentation requirements for raw-unfiltered stock placement.
United Kingdom
FSSAI-aligned import standards and post-Brexit regulatory divergence create dual compliance tracks for bottlers. London and Southeast England health retailers unbundle vinegar from condiment aisles into dedicated wellness sections. Clean-label food manufacturers in the Midlands replace synthetic additives with acetic acid-rich vinegar in sauce production.
Australia
TGA classification pathways could reclassify raw vinegar containing live cultures from food to supplement. New South Wales and Victoria wellness platforms bypass retail slotting fees through direct-to-consumer subscription models for tonic formats. Sustainable packaging mandates accelerate glass-to-aluminum transitions for functional beverage lines.
Apple Cider Vinegar Market Vendor Landscape
Player mix skews toward heritage specialists and mass-market conglomerates with divergent fermentation documentation capabilities. Three tiers emerge: certified organic raw-unfiltered bottlers commanding natural grocery premiums, distilled vinegar producers anchoring supermarket volume, and functional format innovators capturing supplement channel growth. Dominant competitive moves include M&A to secure mother culture expertise and capacity expansion to meet EU Organic Regulation export eligibility.
Within the heritage specialist tier, Bragg Live Food Products exemplifies raw-unfiltered positioning through multi-generational fermentation documentation. Goli Nutrition occupies the format innovation vector with gummy delivery systems that bypass aqueous stability constraints. The Kraft Heinz Company anchors the mass-market tier through distilled vinegar distribution networks that prioritize shelf-stable logistics over live culture retention.
| Leading Market Players |
|---|
| NOW Health Group |
| Dynamic Health Laboratories |
| Bragg Live Food Products |
| Goli Nutrition |
| Nature's Way Products |
| The Kraft Heinz Company |
| Lakewood Juices |
| Spectrum Organic Products |
| Eden Foods |
| Others |
Supply Flow & Price Mechanics
Cold-chain capacity utilization rates in raw-unfiltered distribution create scale thresholds that separate premium bottlers from commodity producers, concentrating pricing power among USDA-certified operators while forcing smaller distillers toward neutral-flavor mass-market positioning.
Pricing Analysis
Certification level creates the primary spread between organic raw-unfiltered stock and distilled alternatives, with USDA NOP documentation commanding shelf placement premiums in natural grocery channels. Three-tier pricing structure separates heritage mother-culture bottlers from mid-tier unfiltered suppliers and economy distilled producers. Cost compression in commodity tiers is intensifying because Washington State apple concentrate volatility feeds through to juice feedstock costs. Mass-market retail consumers show highest price sensitivity, while health enthusiasts absorb premiums for live-culture subscription formats.
Supply Chain Analysis
Port congestion on Pacific Northwest routes inflates inbound logistics costs for European glass bottle imports used in premium functional beverage lines. Washington State and Michigan orchards anchor apple juice concentrate supply, with Chinese malic acid and domestic yeast cultures completing fermentation inputs. Single-source vulnerability concentrates in Washington orchard weather exposure. Distribution runs through natural grocery channel slotting fees for certified stock, while mass-market distilled variants leverage supermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern this market as wellness subscription infrastructure displaces traditional retail slotting, with interoperability between direct-to-consumer fulfillment and mother-culture cold-chain logistics determining competitive survival.
For Market Incumbents: Compound certification documentation advantages by acquiring fermentation specialist talent pools before USDA accreditation backlogs worsen. Secure backward integration into Washington orchard contracts to neutralize weather-driven feedstock volatility. Channel control through exclusive natural grocery placement agreements defends against gummy-format substitutes eroding liquid tonic volumes. For New Entrants and Emerging Players: USDA-accredited organic fast-track programs open shelf access in California and New York pilot wellness sections before national rollout. Target freeze-dried powder applications for travel and workplace consumption where aqueous stability constraints exclude incumbent liquid specialists. Direct-to-consumer subscription launch bypasses retail slotting fee barriers while capturing recurring revenue conversion. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among wellness platform operators with captive mother-culture supply agreements. Long-term viability over the medium-term projection horizon rests on fermentation documentation assets that survive regulatory tightening. Acquisition target archetype: mid-tier bottlers with USDA NOP certification but underutilized cold-chain capacity. Signal to watch is probiotic reclassification rulings that would unlock pharmacy channel placement premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Mother Culture Facility Certification | USDA NOP documentation unlocks natural grocery shelf placement against commodity competitors. |
| Freeze-Dried Powder Capacity Addition | Supplement format expansion captures travel and workplace consumption outside liquid logistics constraints. |
| Direct-to-Consumer Subscription Launch | Recurring shipment models bypass California retailer slotting fees while building lifetime value capture. |
| EU Organic Regulation Alignment | Retrofitted fermentation documentation opens Bavaria and Baden-Württemberg health retail placement. |
| Sustainable Packaging Transition | Aluminum format adoption meets California recycled content mandates for functional beverage lines. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with fermentation specialists, natural grocery category buyers, wellness platform operators, and USDA accreditation body representatives. Secondary validation drew from FDA labeling guidance documents, USDA National Organic Program standards, EU Organic Regulation filings, and customs trade data on apple concentrate flows. Bottom-up volume triangulation against top-down value estimates tested segmentation assumptions across product certification tiers.
Across the analysis window, forecast outputs reflect modeled interactions between regulatory enforcement phases, format substitution elasticities, and channel shift parameters. Segmentation dimensions span certification grade, application use case, packaging format, and end-user archetype with regional regulatory cluster overlays. CAGRs derive from weighted average growth contributions across these segments, with apple supply volatility and probiotic classification debates treated as scenario inputs.
Underlying assumptions cover stable USDA NOP enforcement continuity, with deviation risk concentrated in fermentation specialist wage inflation and mother culture reclassification rulings. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Gluten Free Beverages Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Sports and Energy Drinks Market
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
Plant Based Beverages Market
Beverages
Fruit Juice Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
NFC JUICE Market
Beverages
North America Dairy Beverages Market
Beverages
Ginger Ale Market
Beverages
GCC Coconut Water Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Nitro-Infused Cola Market
Beverages
Ready to Drink Shakes Market
Beverages
India Soy Beverages Market