
 Middle East and Africa Fruits and Vegetable Juice Market | 2026-2036
Middle East and Africa Fruits and Vegetable Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Fruits and Vegetable Juice Market Insights
South African citrus processors and Egyptian mango concentrate producers is recalibrating regional supply chains after drought cycles reduced raw material availability. PepsiCo Inc. leverages its bottling partnerships across North Africa to sustain shelf presence in fragmented traditional trade. Almarai Company anchors the Gulf states with integrated dairy-and-juice distribution networks that dominate modern retail cooler space. Aujan Coca-Cola Beverages Co competes through licensed production of international brands adapted to local sweetness preferences.
Middle East and Africa fruits and vegetable juice encompasses beverages extracted from fresh or processed produce, typically standardized to specific brix levels between 11 and 14 degrees for nectars and 100% juice concentrations for premium positioning, serving refreshment, nutrition, and ingredient-supply functions across retail and food manufacturing. Fresh juice commands the highest per-unit margins but faces spoilage constraints that limit geographic reach from production points. Concentrated juice extends shelf stability and reduces logistics costs, making it the backbone of intra-regional trade from Egypt and South Africa into Gulf markets. Online retail is expanding fastest among distribution channels, though supermarkets and hypermarkets still capture the majority of volume through promotional bundling and chilled-display investments.
Saudi Arabia's SFDA mandates nutritional labeling disclosures that manufacturers must navigate to maintain market access, while South Africa's Department of Health enforces sugar tax tiers that push reformulation toward reduced-sugar and vegetable-blend recipes. The UAE's Ministry of Industry and Advanced Technology applies GCC-standard import certifications that filter out non-compliant concentrate shipments from unregistered overseas plants. Stakeholders must monitor how Egypt's food safety authority tightens pesticide residue thresholds for exported citrus, as this will determine which local processors qualify for Gulf supply contracts.
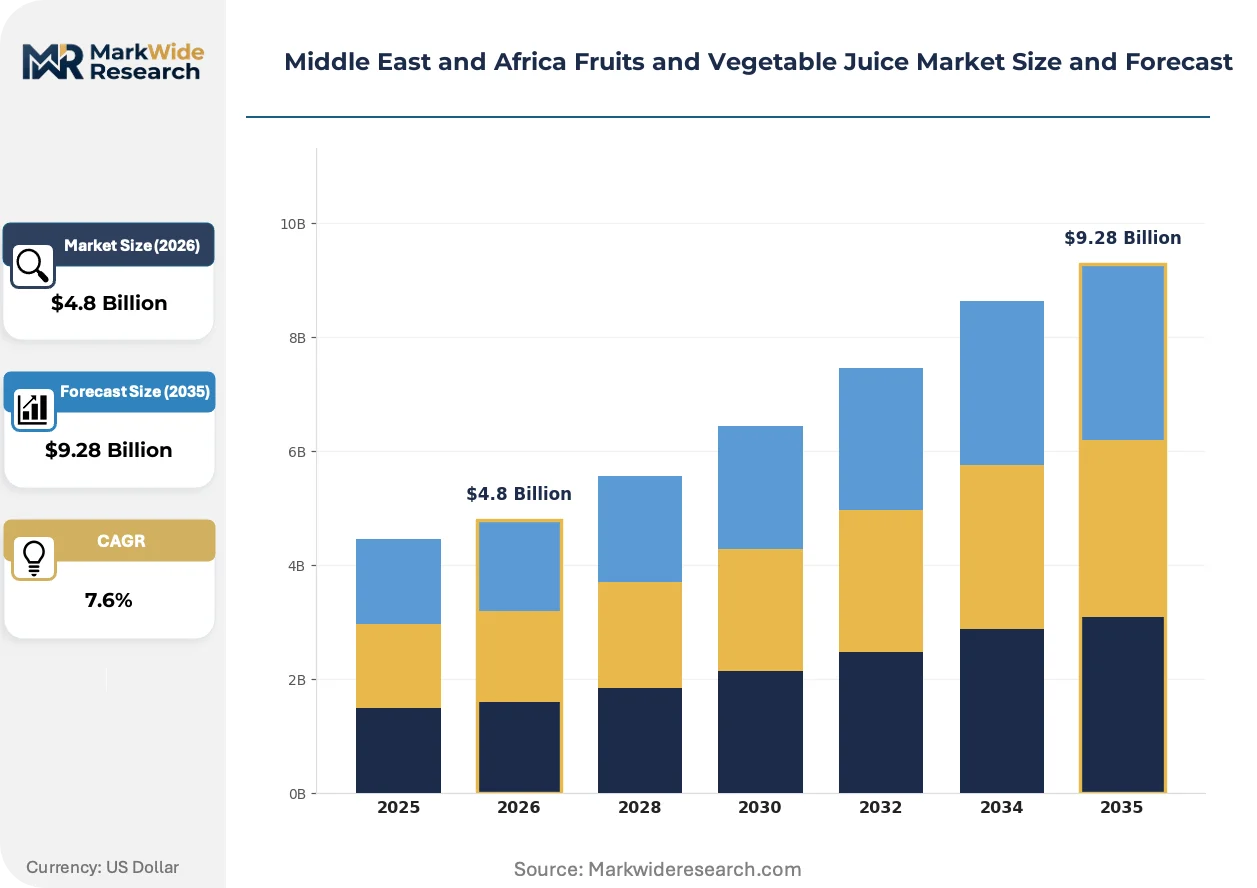
Market Dynamics
Saudi Arabia's SFDA sugar-content labeling mandates are compressing formulation cycles across manufacturers, forcing rapid reformulation of existing portfolios while Gulf retail chains demand cleaner-label alternatives from suppliers.
Growth Catalysts
- SFDA Nutritional Disclosure Rules:Saudi Arabia's mandatory front-of-pack sugar warnings are accelerating manufacturer investment in reduced-sugar recipes and natural sweetener alternatives.
- Urban Household Health Migration:Young families in Dubai and Riyadh are displacing carbonated soft drinks with vegetable-blend juices at breakfast and meal occasions.
- Concentrate Logistics Efficiency:Egyptian citrus and South African mango processors are extending Gulf market reach through aseptic concentrate shipments that reduce refrigerated transport costs.
Market Restraints
- Raw Material Volatility:Drought cycles in South Africa's Western Cape and Egypt's Nile Delta are compressing citrus and mango harvest volumes, elevating concentrate input costs.
- Spoilage Constraints on Fresh:Non-pasteurized juice faces 72-hour shelf limits that restrict geographic distribution radius from production points, capping margin expansion.
- Sugar Tax Tier Compression:South Africa's Department of Health levy structure is forcing price repositioning that squeezes mid-tier nectar profitability.
Strategic Opportunities
- UAE Food Service Channel:Dubai's tourism-driven hotel and restaurant sectors are absorbing premium chilled juice volumes at per-unit margins above retail benchmarks.
- Online Retail Infrastructure:Direct-to-consumer platforms are bypassing traditional trade fragmentation, enabling subscription models for functional vegetable blends.
- MOHAP Import Certification Alignment:UAE's streamlined GCC-standard approvals are creating first-mover advantage for Egyptian processors meeting tightened pesticide residue protocols.
Industry Challenges
- Cold Chain Integrity Gaps:Last-mile refrigerated distribution in Nigeria and Kenya lacks temperature monitoring, elevating spoilage rates for chilled premium products.
- Reformulation Timeline Compression:Manufacturers must execute sugar-reduction transitions within 18-month windows to maintain SFDA compliance without losing shelf placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Fruits and Vegetable Juice Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Juice, Concentrated Juice, Puree, Nectars Distribution Channel: Online Retail, Supermarkets, Hypermarkets, Food Service End User: Households, Restaurants, Cafes, Food Manufacturers Packaging Type: Bottles, Cartons, Cans, Pouches |
| Companies Covered | PepsiCo Inc., Aujan Coca-Cola Beverages Co, Almarai Company, Capri Sun Group Holding AG, Al Rawabi Co, Al Rabie Saudi Foods Co., Del Monte Foods, Inc., Marmum Dairy Farm LLC, The Coca-Cola Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Fruits and Vegetable Juice Market Trends and Innovations
Formulation science and distribution infrastructure are converging to reshape how juice products reach Middle East and Africa consumers, with regulatory pressure and channel evolution operating as twin accelerants of change.
HPP treatment is overtaking traditional thermal pasteurization for premium juice lines in UAE and Saudi retail. The technology preserves enzyme activity and fresh flavor profiles that Gulf consumers associate with quality. Hotel and café buyers in Dubai are specifying HPP-processed products for their chilled display cases, compressing the competitive window for conventional pasteurized alternatives.
South Africa's sugar tax tier structure is forcing measurable recipe reformulation across the manufacturing base. The Department of Health levy applies escalating rates based on sugar content per 100ml, pushing producers toward vegetable-dominant blends and natural sweetener systems. Mid-market nectar brands are most exposed, with many repositioning toward tomato-carrot blends to drop below taxable thresholds.
Young urban households are displacing carbonated beverages with functional juice consumption at morning and post-workout occasions. This behavioral pivot is most visible in Riyadh and Jeddah, where gym chains and corporate cafeterias are expanding chilled juice cooler space. Retailers are responding with promotional bundling of multi-serve vegetable blends that target weekly household replenishment cycles rather than impulse single-serve purchases.
Middle East and Africa Fruits and Vegetable Juice Market Segmentation
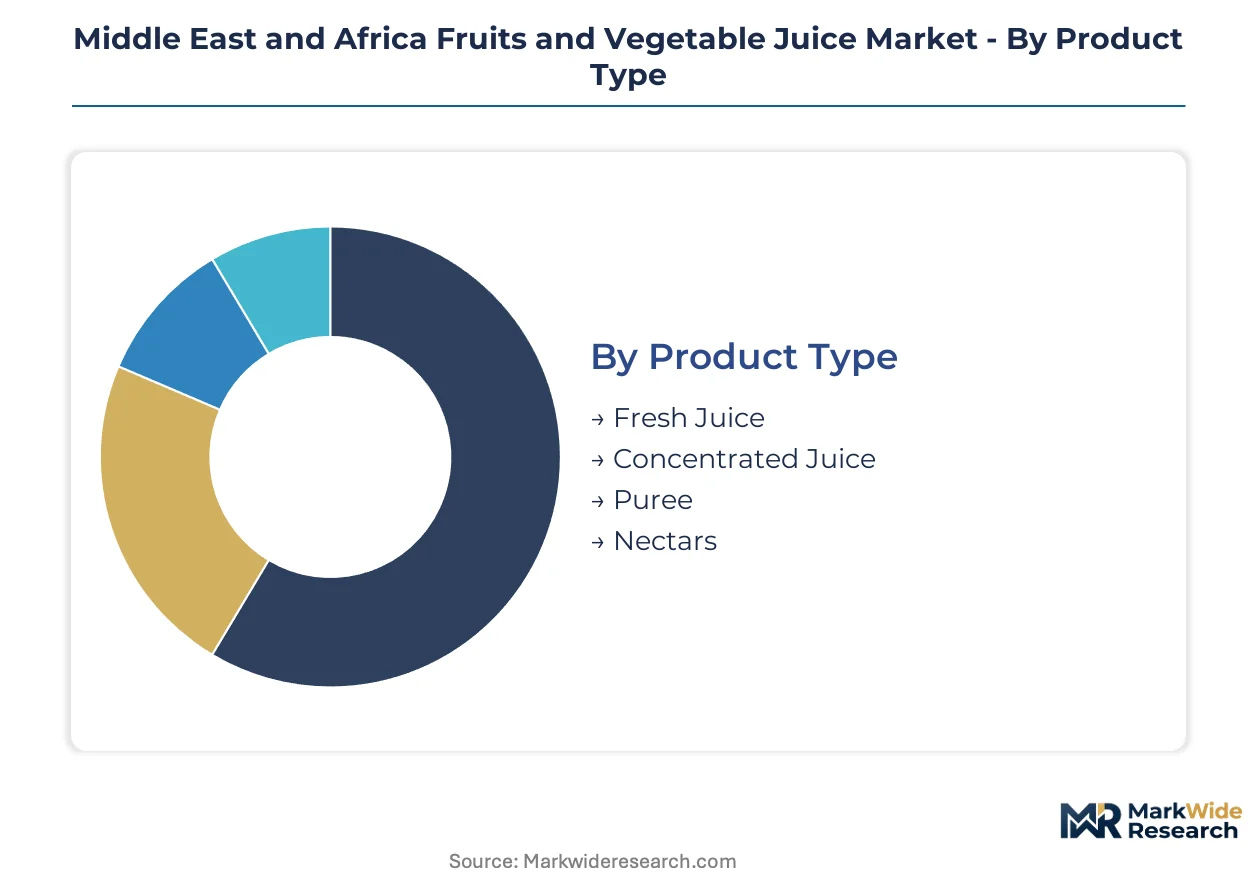
Segmentation in the Middle East and Africa fruits and vegetable juice market reveals how regulatory compliance costs, channel infrastructure gaps, and end-use application requirements fragment commercial opportunities across distinct product-positioning tiers.
Product Type:
SFDA sugar-content disclosure rules and MOHAP import certifications apply differentially across product types, with concentrate shipments facing stricter pesticide residue documentation than domestically processed fresh lines.
- Fresh Juice:Non-pasteurized extraction retains enzyme activity and vitamin density prized by UAE hotel buyers. Dubai's food service sector absorbs premium volumes despite 72-hour shelf limits that restrict distribution radius from production points. Cold chain investments determine market access.
- Concentrated Juice:Aseptic processing at 65-70 brix enables Egyptian citrus and South African mango processors to supply Gulf markets without refrigerated transport. SFDA labeling mandates now require sugar-content disclosure on reconstituted products, elevating compliance costs for Egyptian exporters.
- Puree:Thick, unfiltered pulp base serves ingredient-supply contracts to Riyadh-based dairy-juice blenders and Nigerian beverage manufacturers seeking texture differentiation.
- Nectars:Diluted formulations between 25-50% juice content dominate Saudi and South African mass retail, exposed to sugar tax tier compression in Johannesburg and Cape Town.
Concentrated Juice sits at the top of the volume ranking, with Fresh Juice climbing the fastest as HPP treatment expands shelf stability in UAE and Saudi retail.
Distribution Channel:
Channel selection dictates margin structure and working capital intensity, with direct-to-consumer platforms capturing subscription economics while traditional trade absorbs promotional discounting.
- Online Retail:Direct-to-consumer platforms bypass fragmented traditional trade in Nigeria and Kenya, enabling subscription models for functional vegetable blends. Last-mile cold chain gaps limit fresh juice penetration outside Gulf urban cores.
- Supermarkets:Chilled display investments by Carrefour UAE and Lulu Hypermarket anchor volume for premium juice lines, with promotional bundling driving household replenishment cycles.
- Hypermarkets:Bulk-format concentrate and multi-serve nectar SKUs target price-sensitive Riyadh and Jeddah households, competing with private-label alternatives.
- Food Service:Dubai's tourism-driven hotel and restaurant sectors absorb premium chilled juice at per-unit margins exceeding retail benchmarks. HPP-processed products command specification preference from café buyers.
Supermarkets generate the highest absolute volume, with Online Retail expanding most quickly as logistics infrastructure matures in Gulf Cooperation Council corridors.
End User:
End-use concentration shapes formulation priorities, with food manufacturers prioritizing concentrate cost stability while household buyers respond to front-of-pack health signaling.
- Households:Young urban families in Dubai and Riyadh displace carbonated soft drinks with vegetable-blend juices at breakfast occasions, driving demand for reduced-sugar recipes.
- Restaurants:UAE hospitality procurement specifies HPP-processed chilled juices for brand differentiation, compressing competitive windows for conventional pasteurized alternatives.
- Cafes:Gym-adjacent and corporate cafeteria locations in Saudi Arabia expand cooler space for functional juice consumption at post-workout occasions.
- Food Manufacturers:Egyptian and South African processors supply concentrate inputs to regional dairy-juice blenders and beverage co-packers seeking cost-efficient fruit bases.
Households dominate consumption volume, with Food Manufacturers gaining share fastest as Gulf dairy-juice integration deepens concentrate procurement.
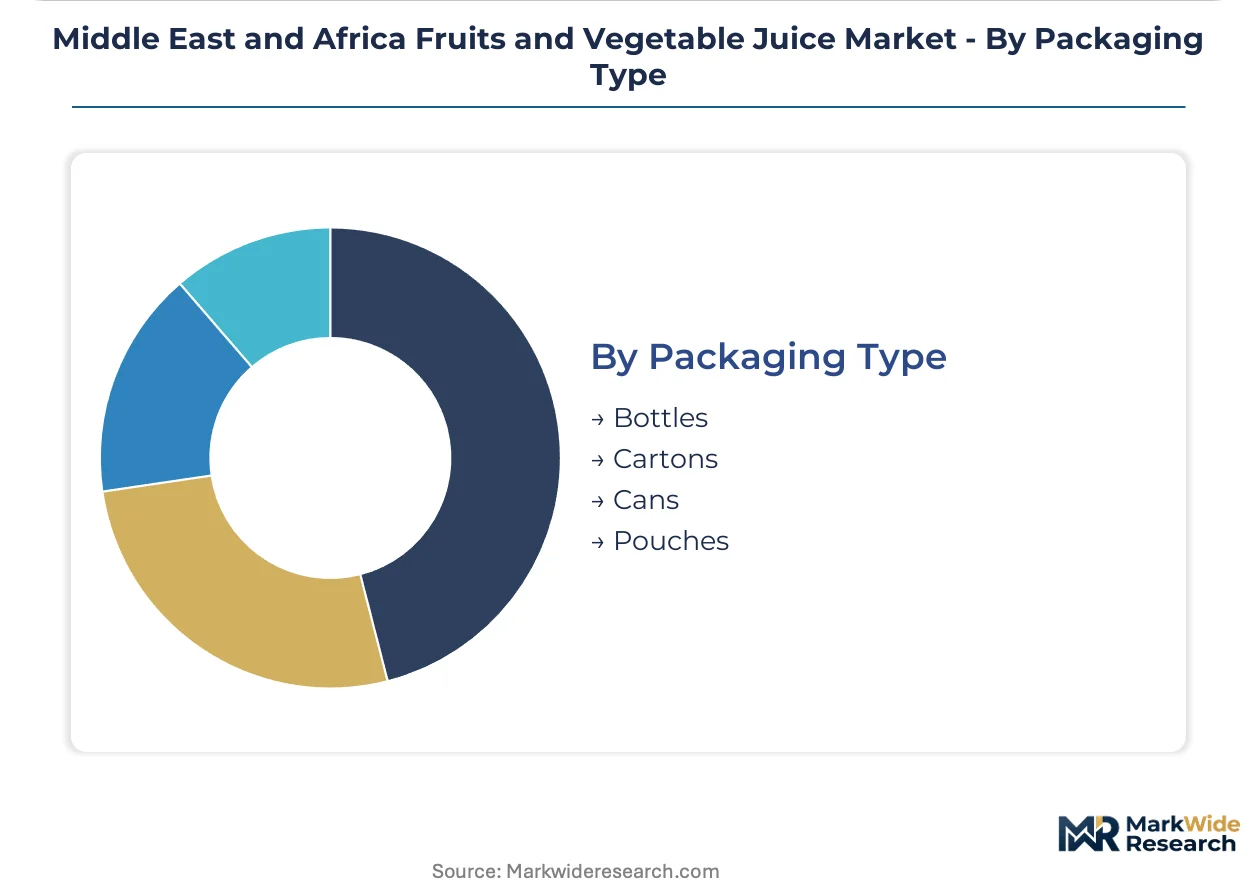
Packaging Type:
Packaging selection balances shelf stability, logistics cube efficiency, and Gulf retail channel requirements for chilled-display aesthetics.
- Bottles:PET and glass formats dominate premium chilled juice in UAE and Saudi supermarkets, with transparent presentation supporting clean-label positioning. Higher logistics costs versus aseptic cartons constrain regional distribution.
- Cartons:Aseptic brick packs anchor Egyptian and South African concentrate exports into Gulf markets, minimizing refrigerated transport requirements.
- Cans:Aluminum formats serve South African nectar segments facing sugar tax pressure, with smaller can sizes enabling portion-controlled pricing.
- Pouches:Flexible formats penetrate Nigerian and Kenyan traditional trade with lower unit economics, though temperature monitoring gaps elevate spoilage risk.
Cartons lead volume throughput, with Bottles commanding the steepest expansion trajectory as HPP-treated premium lines proliferate in Gulf retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands premium juice volumes through SFDA-enforced labeling standards, while South Africa's sugar tax tiers compress mid-market nectar profitability through reformulation mandates.
Saudi Arabia
Riyadh and Jeddah households displace carbonated soft drinks with vegetable-blend juices at breakfast and post-workout occasions. SFDA mandates front-of-pack sugar warnings that accelerate manufacturer investment in reduced-sugar recipes and natural sweetener alternatives. The Eastern Province hosts concentrate reconstitution facilities serving domestic retail and Gulf export corridors.
United Arab Emirates
Dubai's tourism-driven hotel and restaurant sectors absorb premium chilled juice at per-unit margins exceeding retail benchmarks. MOHAP applies GCC-standard import certifications that filter non-compliant concentrate shipments from unregistered overseas plants. Abu Dhabi-based dairy-juice blenders deepen concentrate procurement from Egyptian citrus processors meeting tightened pesticide residue protocols.
Egypt
Nile Delta citrus processors recalibrate regional supply chains after drought cycles reduced raw material availability. The country's food safety authority tightens pesticide residue thresholds for exported citrus, determining which local processors qualify for Gulf supply contracts. Alexandria and Cairo industrial zones anchor aseptic concentrate production for intra-regional trade.
South Africa
Western Cape citrus processors face compressed harvest volumes from drought cycles, elevating concentrate input costs. The Department of Health enforces sugar tax tiers that push reformulation toward reduced-sugar and vegetable-blend recipes. Johannesburg and Cape Town mass retail channels absorb promotional discounting on repositioned tomato-carrot nectar blends.
Nigeria
Lagos and Abuja urban households drive demand for functional juice consumption through gym chains and corporate cafeterias expanding chilled cooler space. Last-mile refrigerated distribution lacks temperature monitoring, elevating spoilage rates for chilled premium products. Flexible pouch formats penetrate traditional trade with lower unit economics despite temperature monitoring gaps.
Middle East and Africa Fruits and Vegetable Juice Market Competitive Landscape
Gulf-based integrated dairy-juice operators anchor one tier; North African bottling specialists and international licensed producers hold complementary positions. The market structures around three archetypes: vertically integrated Gulf conglomerates controlling modern retail cooler space, Egyptian and South African concentrate exporters leveraging aseptic logistics efficiency, and multinational beverage licensors adapting global brands to local sweetness preferences. Competitive moves concentrate on portfolio diversification into reduced-sugar recipes and strategic partnerships with food service channels.
Within the multinational licensor tier, PepsiCo Inc. and The Coca-Cola Company occupy positions sustained through bottling partnerships across North Africa. Almarai Company exemplifies the Gulf-integrated archetype through dairy-juice distribution networks dominating Saudi and UAE modern retail. Aujan Coca-Cola Beverages Co represents the licensed production model, adapting international brand formulations to regional taste profiles.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Aujan Coca-Cola Beverages Co |
| Almarai Company |
| Capri Sun Group Holding AG |
| Al Rawabi Co |
| Al Rabie Saudi Foods Co. |
| Del Monte Foods, Inc. |
| Marmum Dairy Farm LLC |
| The Coca-Cola Company |
| Others |
Pricing and Supply Chain Analysis
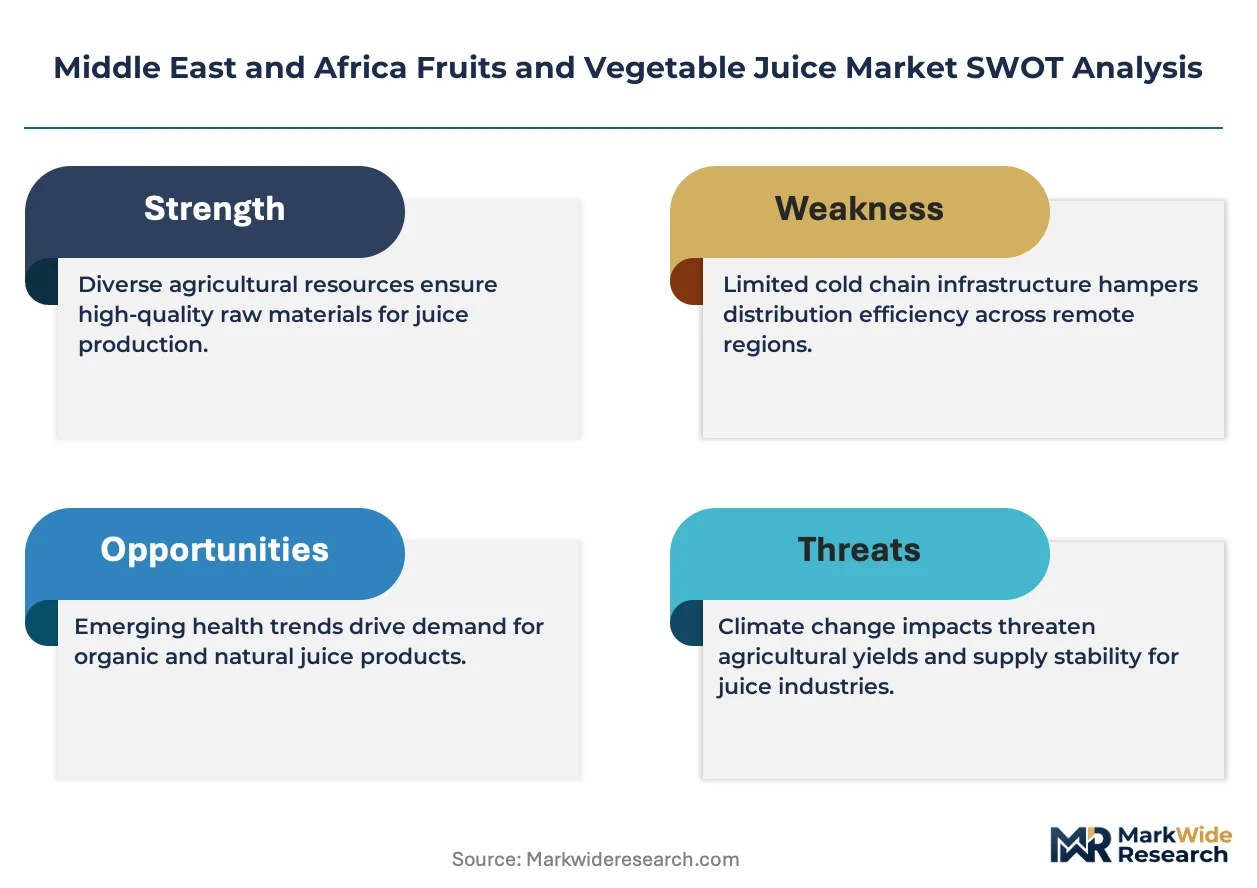
SFDA-mandated front-of-pack sugar warnings are compressing manufacturer margins and forcing rapid reformulation investments, which in turn elevates procurement costs for natural sweetener alternatives and cold-chain compliant packaging across Gulf supply networks.
Pricing Analysis
Retailer markup layers in UAE and Saudi supermarkets absorb 25-35 percent of final shelf price, with Carrefour and Lulu Hypermarket extracting promotional participation fees that squeeze mid-tier nectar profitability. Three-tier pricing structure across premium, standard, and economy levels stratifies around HPP processing certification, with Dubai hotel buyers paying steep premiums for enzyme-retained freshness. Pricing pressure stems from South Africa's sugar tax tier compression, which forces tomato-carrot blend repositioning at lower price points. Price-sensitive mass retail households in Riyadh and Jeddah trade down to private-label concentrates, while food service procurement shows minimal elasticity for HPP-specified chilled lines.
Supply Chain Analysis
Refrigerated freight costs from Egypt's Alexandria port to Jeddah run 40-50 percent above ambient container rates, making aseptic concentrate shipments the economically dominant mode for Nile Delta citrus processors. Supply concentrates in Egypt, South Africa, and Saudi Arabia, with Western Cape mango and Eastern Province reconstitution facilities anchoring regional flow. Raw material dependencies center on citrus brix levels, mango pulp density, and natural sweetener feedstocks from stevia and monk fruit suppliers. Single-source vulnerability haunts Egyptian exporters facing tightened pesticide residue thresholds that could disqualify Gulf contract eligibility. Distribution runs through integrated dairy-juice networks in Saudi Arabia and licensed bottling partnerships across North Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa fruits and vegetable juice market compounds steadily as regulatory disclosure mandates permanently elevate formulation investment cycles and premium positioning thresholds.
For Market Incumbents: Anchor shelf position through backward integration into Egyptian citrus concentrate supply and HPP processing capacity additions in Dubai industrial zones. Almarai-style dairy-juice network control defends against licensed bottler encroachment, while SFDA compliance certification investments lock out smaller reformulation-lagged competitors. For New Entrants and Emerging Players: Subscription-direct households in Lagos and Abuja represent the most penetrable buyer archetype, bypassing fragmented Nigerian traditional trade through cold-chain subscription logistics. Functional vegetable blends for gym-adjacent consumption occasions offer white-space positioning, with MOHAP import certification alignment enabling first-mover Egyptian processor partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap Egyptian concentrate exporters possessing validated pesticide residue protocols and aseptic production assets. Long-term viability hinges on Gulf dairy-juice integration depth and SFDA compliance infrastructure. Watch Egyptian food safety authority enforcement consistency as the signal for which processors secure durable Gulf supply contracts.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Processing Capacity Expansion | Enzyme-retained freshness commands Dubai hotel procurement specifications at premium margins. |
| Backward Integration into Concentrate Supply | Egyptian citrus processor partnerships secure Gulf market access amid tightening residue protocols. |
| Reduced-Sugar Recipe Reformulation | SFDA compliance maintains Saudi shelf placement against sugar-warning disclosure mandates. |
| Direct-to-Consumer Subscription Launch | Bypasses Nigerian traditional trade fragmentation for functional vegetable blend penetration. |
| MOHAP Import Certification Alignment | Streamlined UAE approvals create first-mover advantage for compliant Egyptian exporters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with juice category managers at Gulf retailers, procurement leads at Dubai hotel groups, Egyptian citrus processor operations directors, and South African Department of Health regulatory officials with secondary validation from SFDA labeling guidance documents, MOHAP import certification protocols, Nielsen retail audit data for UAE and Saudi supermarket channels, and customs records of Egyptian concentrate shipments. Bottom-up volume modeling and top-down value triangulation cross-verified segment outputs.
Comparable-period anchoring tied projection assumptions to historical consumption patterns across the analysis window, with segmentation modeling spanning product type, distribution channel, end-user application, and packaging format dimensions. CAGRs derived from trend extrapolation of urban household health migration rates, regulatory compliance cost trajectories, and cold-chain infrastructure investment flows. Industry-specific inputs incorporated drought cycle impact assessments on South African and Egyptian raw material availability.
Underlying measurement precision varies by segment; fresh juice and HPP-processed lines carry tighter precision than traditional nectars given spoilage constraint documentation. Forecasts reflect assumptions about SFDA enforcement consistency, Egyptian pesticide residue protocol stability, and Gulf tourism recovery trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Vegetable Juice Market
Beverages
Flavored Powder Drinks Market
Beverages
North America Juices Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
Beverage Premix Market
Beverages
Packaged Milkshake Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Sparkling Soda Market
Beverages
Sparkling Water Machine Market
Beverages
Hot Beverages Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
GCC Bottled Water Market
Beverages
Birch Water Market
Beverages
Aloe Vera Drinks Market
Beverages
Europe Bottled Water Market
Beverages
Soy Drinks Market