
 Plant-Based Chorizo Market | 2026-2036
Plant-Based Chorizo Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Chorizo Market Analytics
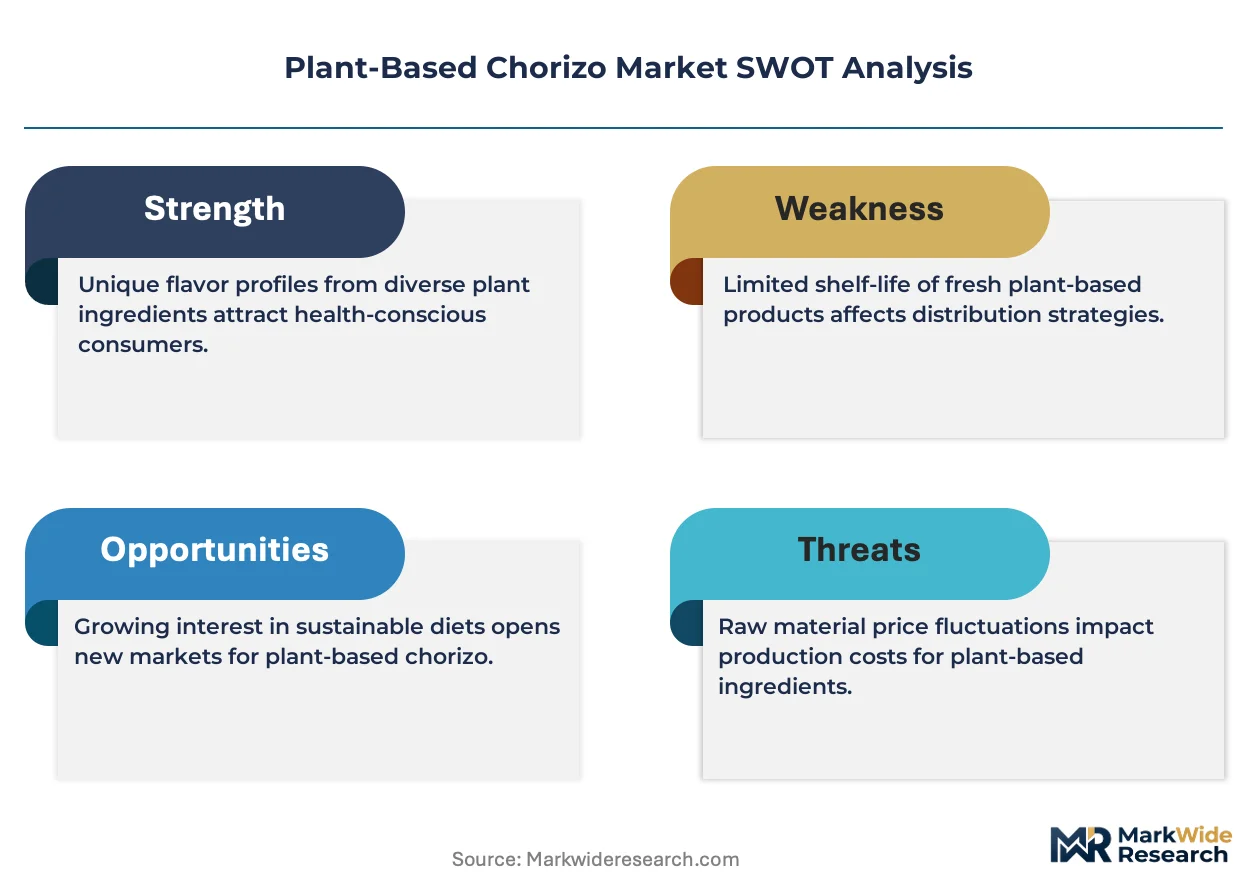
The capital-intensity divergence between large-scale extrusion specialists and craft fermenters is reorganizing competitive tiers in plant-based chorizo. Beyond Meat leverages industrial extrusion infrastructure to anchor North American retail distribution at price parity with conventional pork chorizo. Impossible Foods sustains heme-protein R&D intensity that differentiates its fat-mimicry and seared-crust performance in food service applications. Abbot's Butcher specializes in whole-food ingredient decks that occupy premium shelf space in specialty grocers.
Plant-based chorizo denotes a seasoned, cured-style sausage analog manufactured through high-moisture extrusion or fermentation of proteins and fats, typically achieving 14-18% fat content and 2,500-4,000 Scoville heat units to replicate Spanish or Mexican chorizo profiles. Its primary commercial purpose is substituting for animal chorizo in prepared foods, retail cases, and food service lines without requiring recipe reformulation by end kitchens. The ingredient source dimension reveals pea protein formulations leading volume due to allergen-friendly positioning, while soy protein retains cost advantages in food service channels. Distribution through food service is accelerating fastest as Latin-themed fast-casual chains integrate crumble formats into permanent menu architecture.
The U.S. FDA and USDA-FSIS share jurisdiction over plant-based meat labeling, with ongoing rulemaking on "meat" and "chorizo" descriptor restrictions shaping package claims and retail placement. The EU EFSA and national regulators under the EU Green Deal's Farm to Fork strategy are tightening carbon-footprint disclosure requirements that favor regional pea and fava supply chains over imported soy. Stakeholders must monitor whether emerging mycelium and precision-fermentation fat technologies displace extrusion as the dominant texturization platform before the next wave of capital deployment locks in manufacturing footprints.
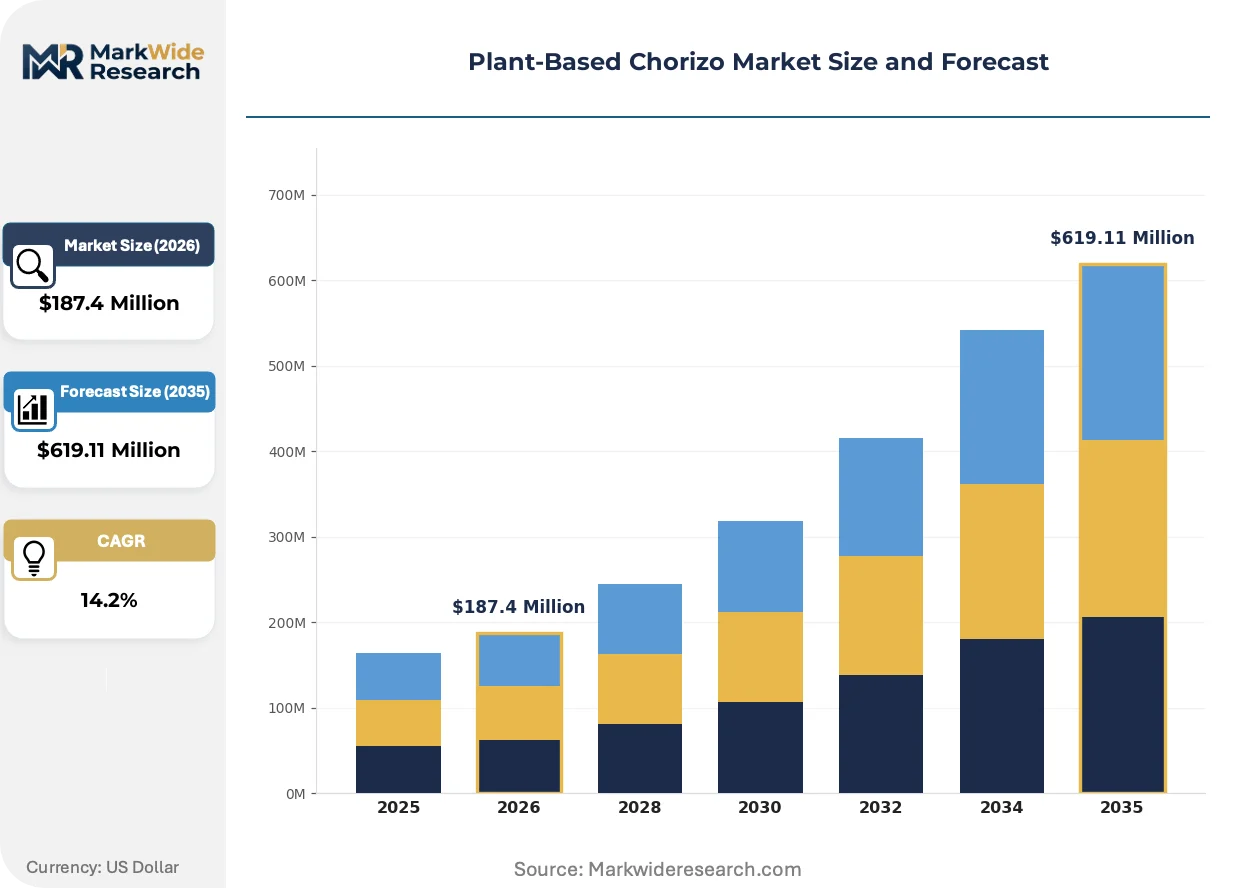
Market Dynamics
High-moisture extrusion infrastructure is concentrating manufacturing capacity among capital-heavy processors, locking in pea-protein supply contracts and squeezing mid-scale fermenters from food service procurement channels.
Growth Catalysts
- California food service procurement:Latin-inspired fast-casual chains in Los Angeles and San Diego are embedding plant-based chorizo crumbles into permanent menu architecture, creating steady institutional demand.
- EU Green Deal carbon disclosure:The Farm to Fork strategy tightens footprint transparency requirements, favoring regional pea and fava supply chains over carbon-intensive imported soy.
- Heme-protein R&D maturation:Precision fermentation of soy leghemoglobin is improving fat-mimicry and seared-crust performance in food service applications without animal inputs.
Market Restraints
- Pea protein supply concentration:North American and Canadian pea processing capacity is controlled by a handful of ingredient suppliers, creating input price volatility for mid-tier manufacturers.
- FDA-USDA labeling friction:Shared jurisdiction over "chorizo" descriptor claims is delaying package approvals and forcing conservative retail placement strategies.
- Conventional pork price parity pressure:Commodity pork chorizo maintains cost advantages in price-sensitive food service channels, limiting penetration in contract feeding operations.
Strategic Opportunities
- Mycelium fat technology convergence:Precision-fermentation lipids combined with extruded protein matrices could displace established texturization platforms before next-wave capital deployment.
- European quick-service restaurant procurement:Spanish and German pizza chains are accelerating trials of plant-based sausage formats as EU deforestation regulations tighten pork supply scrutiny.
- Specialty grocer premium positioning:Whole-food ingredient decks with clean-label certification are capturing shelf space in high-margin retail channels underserved by industrial extrusion products.
Industry Challenges
- High-moisture extrusion capex barriers:Industrial-scale twin-screw systems require substantial capital commitment, freezing out craft fermenters from food service volume contracts.
- Cross-jurisdictional certification timelines:Dual FDA-USDA approval pathways for novel heme ingredients are extending time-to-market for next-generation fat technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Chorizo Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw, Cooked, Frozen, Ready-to-Eat Texture: Crumble, Slice, Dice, Ground Ingredient Source: Pea Protein, Soy Protein, Wheat Gluten, Lentils Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Food Service |
| Companies Covered | Beyond Meat, Impossible Foods, Lightlife Foods, Tofurkey, Field Roast, No Evil, RollinGreens, Abbot's Butcher, Blue Tribe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Chorizo Market Evolving Landscape
Texturization platforms and regulatory disclosure frameworks are actively reorganizing competitive tiers, with fermentation-based fats and carbon-accounting mandates creating divergent pathways for scale and premium positioning.
Mycelium-derived lipid systems are miniaturizing production footprints for specialized fat precursors, enabling regional craft producers to bypass capital-intensive extrusion infrastructure. California and Netherlands-based food tech firms are adopting these systems at pilot scale. The technology is miniaturizing the minimum viable manufacturing scale, compressing barriers to entry for localized chorizo production.
The EU EFSA is tightening carbon-footprint disclosure requirements under the Farm to Fork strategy, forcing ingredient sourcing transparency across plant-based meat supply chains. Manufacturers must now document regional pea and fava provenance versus imported soy. German and Spanish retail channels are responding by prioritizing EU-sourced protein formulations in procurement specifications.
Food service buyers are consolidating protein procurement around crumble formats that require zero kitchen retraining, displacing whole-link sausage analogs in Latin-themed fast-casual concepts. California's Chipotle-scale chains are leading this specification shift. The behavior is most visible in Los Angeles and San Diego metro areas where labor-cost pressures favor drop-in ingredient substitutions.
Plant-Based Chorizo Market Segmentation
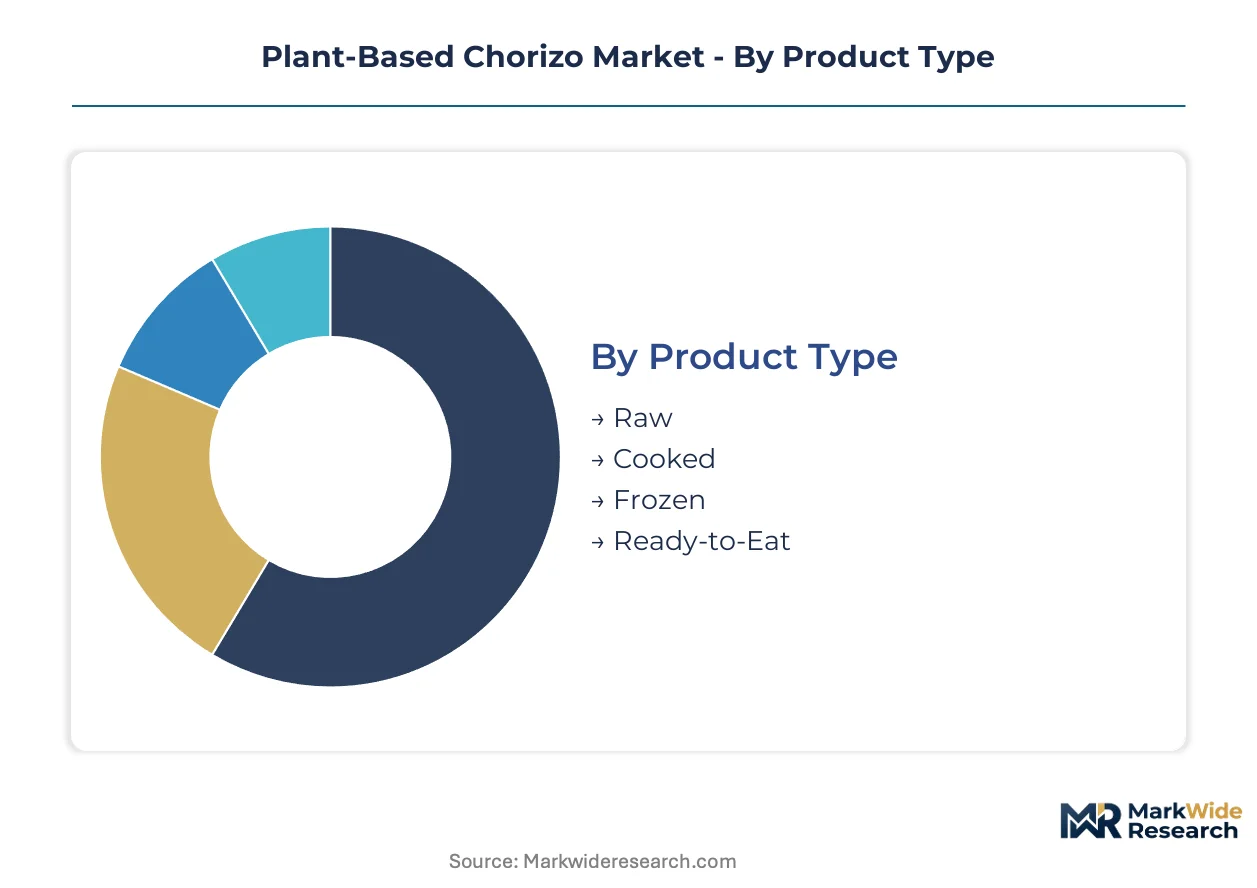
Segmentation in plant-based chorizo reveals where substitution pressure concentrates and which formats command premium positioning. Manufacturers align R&D and capacity investments to the texture-distribution intersections showing strongest food service pull.
Product Type:
Substitution pressure from conventional pork chorizo intensifies most acutely in formats requiring minimal kitchen retraining, driving divergence between raw and value-added segments.
- Raw:Unseasoned or lightly seasoned base requiring end-kitchen spice application and cooking. Los Angeles fast-casual chains favor raw crumbles for menu flexibility and labor-cost control.
- Cooked:Fully thermally processed products with stabilized emulsions and fixed moisture content. Food service buyers in San Diego specify cooked formats to reduce cross-contamination protocols and holding-time variability.
- Frozen:Blast-chilled products with extended shelf stability through cryogenic or mechanical freezing. Retail distribution in California and Texas prioritizes frozen for inventory rotation efficiency.
- Ready-to-Eat:Shelf-stable or refrigerated products requiring zero preparation. Convenience-oriented channels in Germany and Spain trial these for grab-and-go retail placement.
Raw retains volume leadership; Ready-to-Eat holds the steepest expansion curve.
Texture:
Cost tier stratification separates premium whole-muscle formats from economy ground applications, with mid-tier crumble formats capturing food service procurement consolidation.
- Crumble:Fragmented particulate structure optimized for pizza topping, bowl assembly, and taco filling. California Chipotle-scale chains specify 4-6mm particle size for even heat distribution and sauce adhesion.
- Slice:Sheet or plank formats mimicking cured chorizo rounds for charcuterie and sandwich applications. Specialty grocers in Netherlands and Germany stock slice formats for premium deli cases.
- Dice:Cuboidal cuts for paella, stew, and rice-bowl integration. Spanish food service distributors trial dice formats for traditional recipe compatibility.
- Ground:Fine comminuted texture for sauce incorporation and stuffing applications. Economy retail positioning in US Midwest and Southern states favors ground for price-sensitive household penetration.
Crumble dominates procurement volume; Slice commands the highest margin tier.
Ingredient Source:
Application requirements dictate protein selection, with allergen positioning and carbon disclosure mandates reshaping sourcing strategies across commercial segments.
- Pea Protein:Isolated or concentrated Pisum sativum proteins processed through wet or dry fractionation. EU Green Deal carbon-footprint requirements favor regional European pea cultivation over imported alternatives.
- Soy Protein:Textured or isolate forms from Glycine max with established cost structures. Food service channels in North America retain soy for price parity with commodity pork chorizo.
- Wheat Gluten:Vital wheat gluten providing elastic, chewy texture profiles. German and Spanish manufacturers explore gluten-based formulations for clean-label positioning in domestic retail.
- Lentils:Whole or fractionated Lens culinaris proteins with fiber-retained nutritional claims. Netherlands-based food tech firms pilot lentil chorizo for differentiated whole-food ingredient decks.
Pea Protein leads volume in EU and North American retail; Lentils gain share fastest in specialty channels.
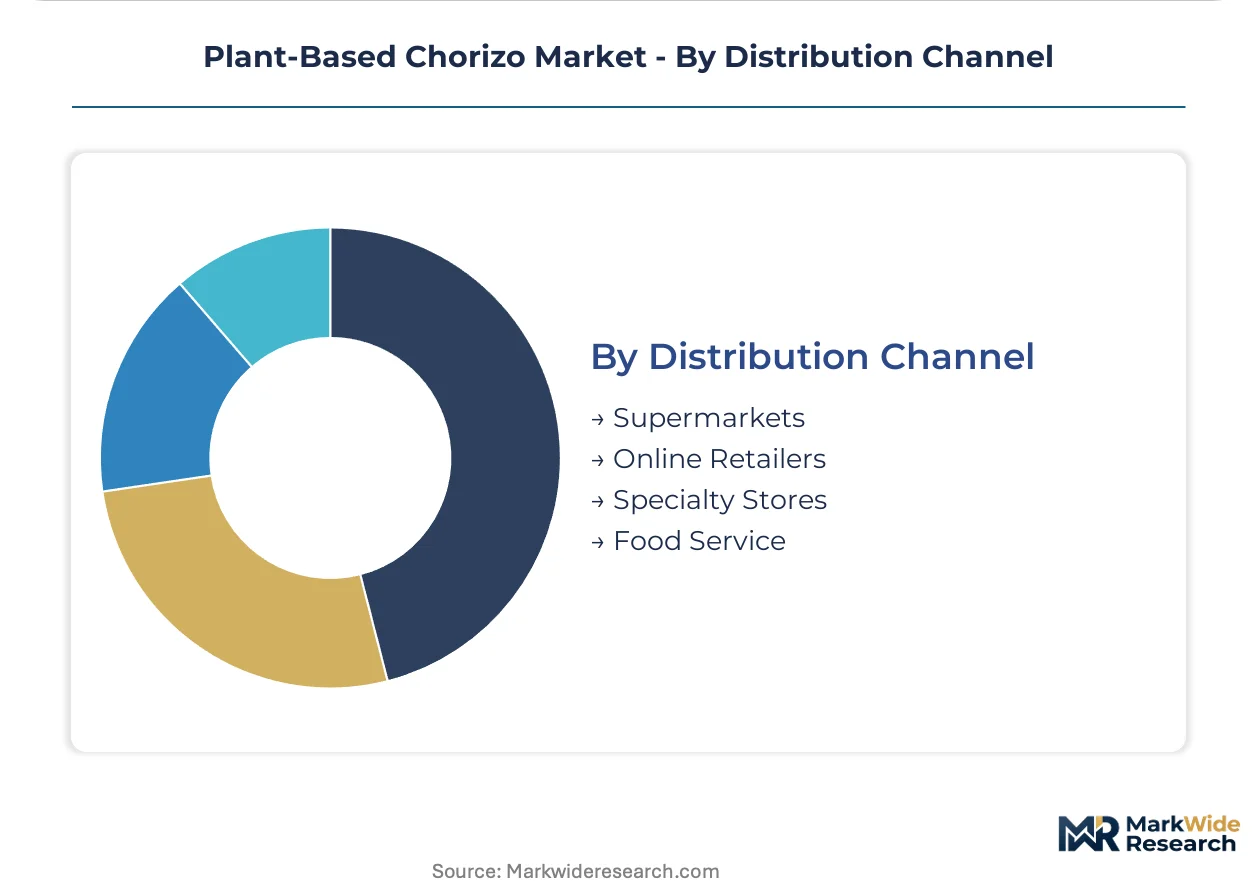
Distribution Channel:
Customer type fragmentation separates institutional procurement from household purchase occasions, with channel-specific packaging and certification requirements driving format divergence.
- Supermarkets:Mass-market retail with refrigerated and frozen case placement. California's Safeway-Albertsons network and Germany's REWE Group dominate volume movement through promotional cycling.
- Online Retailers:Direct-to-consumer and third-party platform distribution with cold-chain logistics. Frozen and shelf-stable formats concentrate here due to shipping constraints and subscription-model adoption.
- Specialty Stores:Natural, organic, and ethnic grocers with curated assortment and educated staff. Whole-food ingredient decks with clean-label certification capture shelf space in this channel.
- Food Service:B2B supply to restaurants, cafeterias, and institutional kitchens. Latin-themed fast-casual chains in Los Angeles and San Diego embed plant-based chorizo crumbles into permanent menu architecture here.
Food Service accelerates fastest; Supermarkets retain absolute volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in plant-based chorizo reveal the United States as a net technology exporter while Germany and Spain balance regional sourcing with ingredient imports. Trade flows concentrate protein isolates from Canada and European pea processors toward manufacturing hubs in California and the Netherlands.
United States
Los Angeles and San Diego fast-casual chains drive procurement consolidation around crumble formats, embedding plant-based chorizo into permanent Latin-inspired menu architecture. The FDA and USDA-FSIS share jurisdiction over "chorizo" labeling claims, delaying package approvals and forcing conservative retail placement strategies. California's food service sector leads national adoption, with Chipotle-scale operators specifying 4-6mm particle sizes for even heat distribution.
Germany
Spanish and German pizza chains accelerate trials of plant-based sausage formats as EU deforestation regulations tighten pork supply scrutiny. The EU EFSA carbon-footprint disclosure requirements under the Farm to Fork strategy favor regional pea and fava supply chains over imported soy. Berlin and Hamburg retail channels prioritize EU-sourced protein formulations in procurement specifications, responding to transparency mandates.
Spain
Traditional recipe compatibility drives demand for dice formats in paella and stew applications, with food service distributors piloting cuboidal cuts. ANSM-equivalent national regulators enforce strict clean-label certification for shelf-stable products entering grab-and-go retail placement. Madrid and Barcelona manufacturing clusters experiment with lentil-based formulations for differentiated whole-food ingredient decks in specialty channels.
Netherlands
Food tech firms in Amsterdam and Rotterdam pilot mycelium-derived lipid systems to miniaturize production footprints for specialized fat precursors. The EU Green Deal's carbon-accounting framework pressures manufacturers to document regional versus imported protein provenance. Eindhoven-region extrusion specialists face competition from craft fermenters bypassing capital-intensive infrastructure through precision-fermentation platforms.
Canada
Alberta and Saskatchewan pea processing capacity supplies North American manufacturers, though concentration among handful of ingredient suppliers creates input price volatility. Health Canada reviews novel heme ingredients under extended timelines, extending time-to-market for next-generation fat technologies. Toronto and Vancouver food service buyers balance allergen-friendly pea formulations against soy's cost advantages in contract feeding operations.
Plant-Based Chorizo Market Competitive Landscape
Concentration sits with large-scale extrusion specialists who anchor retail distribution through industrial infrastructure and pea-protein supply contracts. Mid-scale fermenters face squeeze from food service procurement channels favoring volume guarantees. Three archetypes dominate: capital-heavy extrusion processors, heme-protein R&D specialists, and whole-food craft producers occupying premium shelf space. Competitive moves center on manufacturing footprint expansion and strategic partnerships with Latin-themed fast-casual chains.
Within the industrial extrusion tier, Beyond Meat exemplifies scale-driven positioning through North American retail penetration at price parity with conventional pork chorizo. Impossible Foods occupies the heme-technology archetype, with precision-fermentation R&D intensity differentiating fat-mimicry performance in food service applications. Abbot's Butcher represents the whole-food craft segment, capturing specialty grocer shelf space through clean-label certification and premium ingredient decks.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Lightlife Foods |
| Tofurkey |
| Field Roast |
| No Evil |
| RollinGreens |
| Abbot's Butcher |
| Blue Tribe |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's Farm to Fork carbon-footprint disclosure regime gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to document regional pea provenance for premium positioning while soy-based formulations compete on cost in undifferentiated food service channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across food service procurement, with pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation stems from EU EFSA carbon-accounting compliance and clean-label certification status. Cost compression in the economy tier is intensifying because conventional pork chorizo maintains commodity pricing advantages in price-sensitive contract feeding operations. Quick-service restaurant chains exhibit highest price sensitivity, while specialty grocers accepting whole-food ingredient decks show least.
Supply Chain Analysis
Inventory lead times stretch 8-12 weeks for North American pea protein isolates as Alberta and Saskatchewan processing capacity concentrates among limited suppliers. Geographic supply concentration centers on Canada, the Netherlands, and Germany for protein fractionation infrastructure. Raw material dependencies rest on pea and fava cultivation, precision-fermentation lipid precursors, and high-moisture extrusion equipment. Single-source vulnerability in Canadian pea processing creates input price volatility. Distribution runs through food service broadliners and specialty distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as Latin-inspired fast-casual chains embed plant-based chorizo crumbles into permanent menu architecture, creating institutional demand tailwinds before mainstream household penetration accelerates.
For Market Incumbents: Consolidate pea-protein supply contracts through backward integration into Alberta and Saskatchewan processing capacity to defend against emerging mycelium-fat fermenters. Lock in multi-year food service volume agreements with California Chipotle-scale operators before precision-fermentation platforms achieve cost parity. Prioritize FDA-USDA dual jurisdiction labeling clearance to secure retail shelf placement ahead of rulemaking uncertainty.
For New Entrants and Emerging Players: EU EFSA carbon-footprint certification fast-tracks access to German and Spanish retail channels prioritizing regional provenance claims. White-space concentrates in lentil-based whole-food formulations for Netherlands specialty grocers and dice-format traditional recipe compatibility in Spanish paella applications. Go-to-market through food service distributors serving Latin-themed fast-casual chains avoids direct retail slotting fee barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from large CPG parent companies divesting underperforming plant-based meat divisions amid portfolio rationalization. Long-term viability hinges on manufacturing technology flexibility across extrusion and fermentation platforms. Monitor mycelium-derived lipid pilot scale achievements as inflection indicator for next-wave capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Processing | Captures margin from Alberta and Saskatchewan supply concentration. |
| Food Service Volume Contracting | Locks in California Latin-themed fast-casual procurement before fermentation competition. |
| EU Carbon-Footprint Certification | Opens German REWE and Spanish retail channels under Farm to Fork mandates. |
| Mycelium Lipid Pilot Scale-Up | Validates precision-fermentation fat technology before extrusion capital deployment. |
| FDA-USDA Labeling Clearance | Secures retail placement ahead of shared jurisdiction descriptor restrictions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA labeling guidance documents, EU EFSA carbon-footprint disclosure frameworks, and food service procurement databases. Primary interviews engaged R&D directors at extrusion specialists, procurement managers at Latin-themed fast-casual chains, category buyers at German REWE and California Safeway-Albertsons networks, and regulatory affairs leads navigating dual FDA-USDA jurisdiction. Secondary sources included customs records tracking Canadian pea protein exports, SEC filings from publicly traded plant-based meat manufacturers, and EU Farm to Fork strategy implementation reports. Bottom-up volume modeling triangulated against top-down market sizing across ingredient source and distribution channel dimensions.
Segmentation dimensions modeled encompass product type, texture format, ingredient source, and distribution channel across the analysis window. The analytical framework projects volume and value through demand-side adoption curves in food service versus retail channels and supply-side capacity constraints in extrusion infrastructure. CAGRs derived from segment-level growth rate blending weighted by base-year share. Industry-specific forecast inputs include heme-protein R&D maturation timelines and EU deforestation regulation enforcement phases affecting pork supply scrutiny.
Underlying assumptions cover sustained food service procurement consolidation, regulatory clarity on labeling descriptors, and carbon-accounting framework stability, with deviation risk concentrated in FDA-USDA rulemaking delays and mycelium-fat technology breakthrough timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Australia Plant Protein Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Vegan Meals Market
Plant Based Food
Plant-Based Waters Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
North America Tofu Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
China Pea Protein Market