
 Asia-Pacific Energy Drink Market | 2026-2036
Asia-Pacific Energy Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Energy Drink Market Outlook
Subscription-based replenishment models for powdered energy drink sachets is pivoting how brands secure recurring revenue in the Asia-Pacific region. Red Bull GmbH leverages its motorsport-linked brand equity to sustain premium positioning across Southeast Asian convenience channels. Monster Beverage Corporation anchors shelf presence through exclusive cold-storage partnerships with major retail chains in Japan and South Korea. Eastroc Beverage(Group) Co., Ltd. dominates the domestic Chinese market through deep distribution into lower-tier city vending networks.
An energy drink is a caffeinated functional beverage typically formulated with taurine, B-vitamins, and herbal extracts, manufactured through hot-fill or aseptic processing to preserve active compounds across ambient supply chains. Its primary commercial purpose is to deliver acute mental alertness and physical stamina for consumers facing extended work hours or intensive recreational activity. Carbonated variants occupy the largest revenue share due to established palate familiarity, while sugar-free formulations capture the fastest expansion as reformulation investments respond to diabetes-prevention campaigns across the region. Ready-to-drink cans lead volume throughput, though energy shots concentrate margin pools through pharmacy and gym-channel placement at elevated unit prices.
Food safety regulators in China enforce GB standards for caffeine disclosure and additive limits, while India's FSSAI mandates progressively stricter labeling for sugar content and recommended serving sizes. Japan's PMDA and METI coordinate on functional food claims, creating a dual-track compliance environment where substantiated benefit statements unlock pharmacy distribution. Stakeholders must monitor evolving caffeine caps and sugar-tax proposals across multiple Asia-Pacific jurisdictions to anticipate reformulation costs and channel requalification requirements.
Market Dynamics
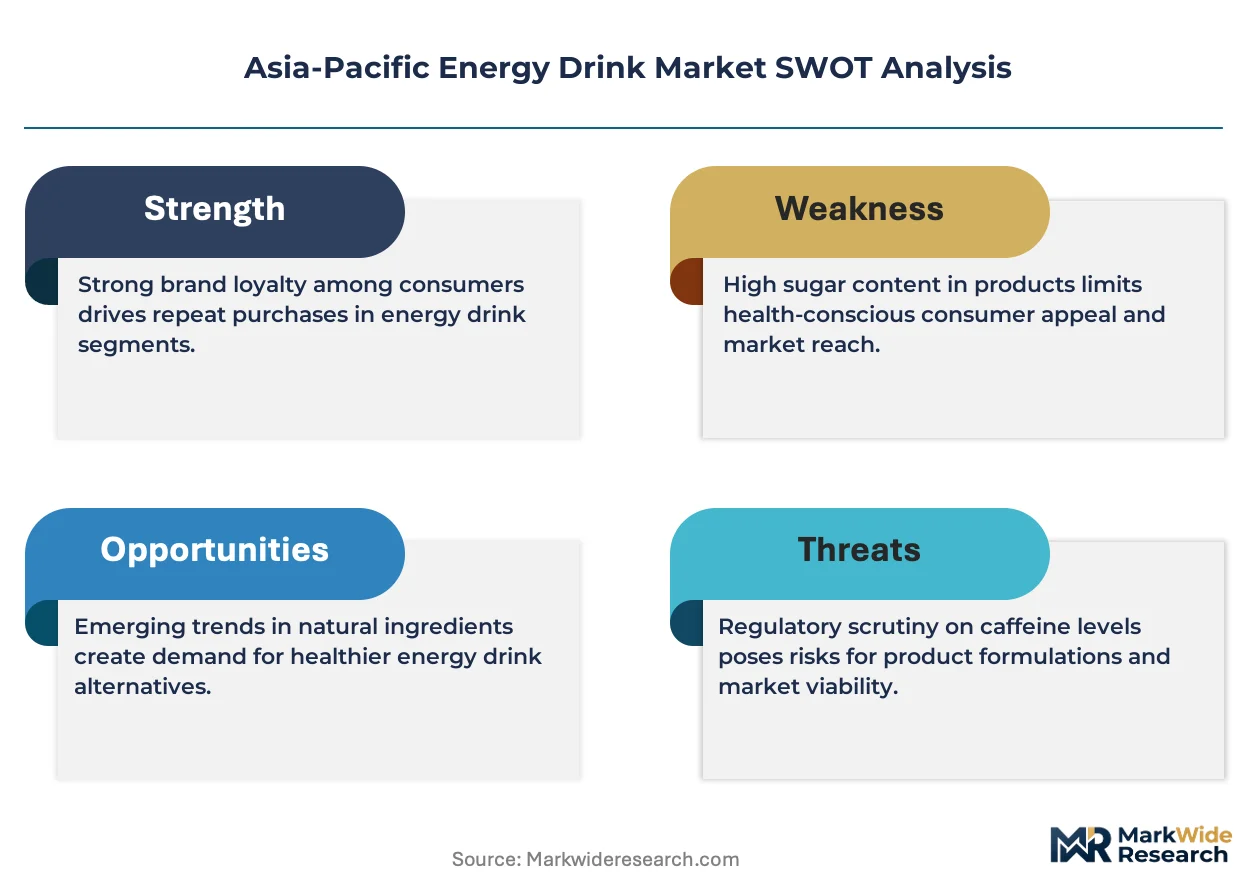
GB standards for caffeine disclosure and sugar-tax proposals across Asia-Pacific jurisdictions are forcing simultaneous reformulation and channel requalification, compressing margin structures while opening pharmacy-grade positioning for compliant brands.
Growth Catalysts
- Urban work-hour extension:Young professionals in Shanghai, Mumbai, and Jakarta face 50+ hour work weeks, creating sustained demand for acute alertness solutions.
- FSSAI sugar labeling mandates:India's progressive disclosure requirements accelerate consumer migration toward reduced-sugar portfolios.
- PMDA functional claims pathway:Substantiated benefit statements unlock pharmacy distribution in Japan, commanding 40% price premiums over convenience channels.
Market Restraints
- Taurine supply concentration:Synthetic taurine production clusters in Chinese chemical hubs, exposing formulators to input volatility and dual-use export controls.
- Cold-storage infrastructure gaps:Ambient-stable formulations dominate Southeast Asian rural distribution due to unreliable refrigerated last-mile networks.
- Caffeine caps under review:Multiple national food safety regulators are evaluating maximum per-serving limits that would obsolete current 300mg+ formulations.
Strategic Opportunities
- Vietnam and Philippines underpenetration:Per-capita consumption in these markets sits at one-third of Thai levels, offering whitespace for powdered sachet subscription models.
- Gym-channel energy shots:Pharmacy and fitness-center placement at elevated unit economics captures margin pools outside commoditized retail.
- PLI scheme alignment:India's production-linked incentive framework for food processing supports localized aseptic manufacturing investments.
Industry Challenges
- Reformulation cadence compression:Simultaneous caffeine disclosure, sugar reduction, and clean-label demands strain R&D bandwidth across product lines.
- Dual-track compliance costs:Brands operating across China GB standards, Japan PMDA functional claims, and India FSSAI labeling face fragmented certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Energy Drink Market |
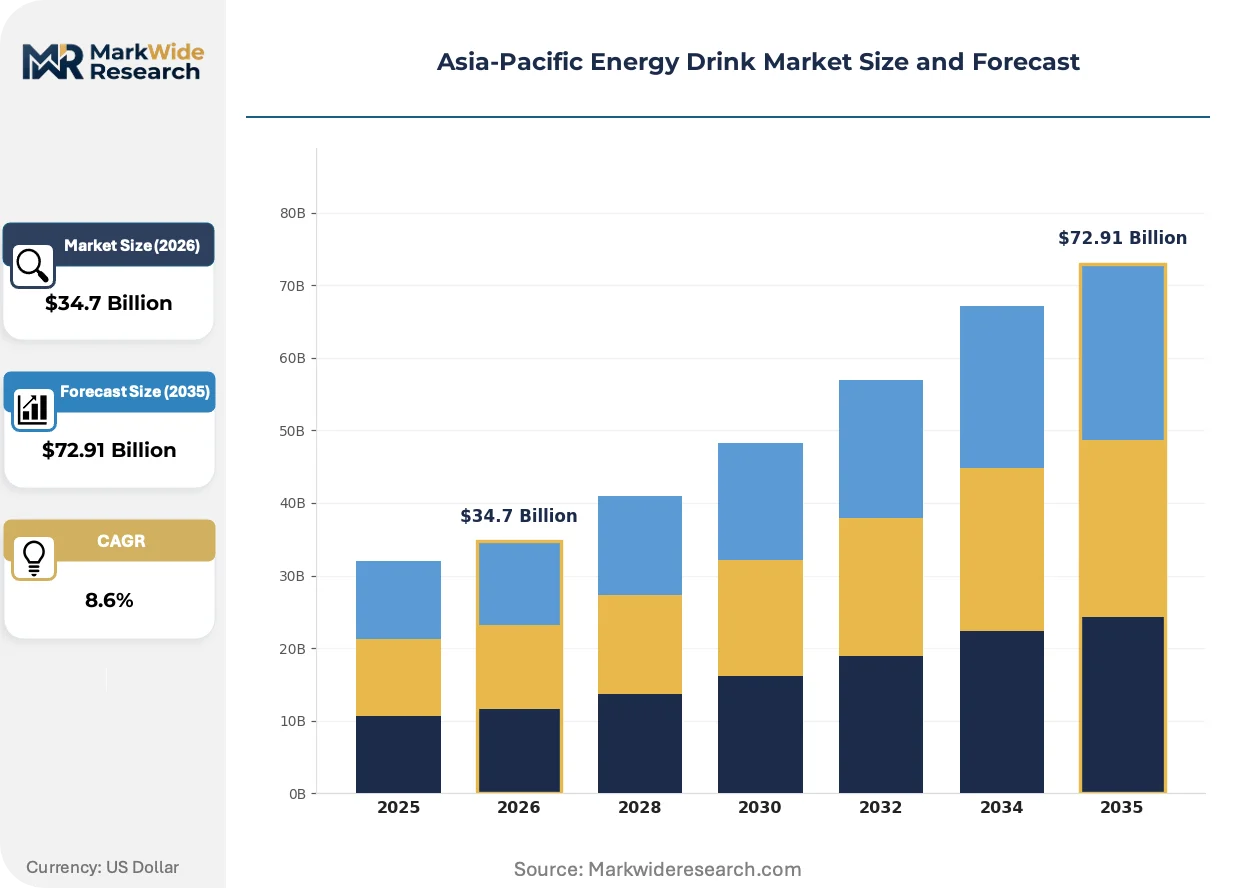
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Carbonated, Non-Carbonated, Sugar-Free, Herbal Form: Ready-to-Drink, Powdered, Liquid Concentrate, Energy Shots Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Vending Machines Consumer Age Group: Teens, Young Adults, Middle-Aged Adults, Seniors |
| Companies Covered | Red Bull GmbH, Monster Beverage Corporation, Eastroc Beverage(Group) Co., Ltd., Fujian Dali Food Group Co., Ltd., T.C. Pharmaceutical Industries Company Limited, Osotspa Co., Ltd., Otsuka Pharmaceutical Co., Ltd., Suntory Holdings Limited, Rockstar, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Energy Drink Market Strategic Shifts
Sugar-reduction technologies and alternative sweetener systems are actively displacing conventional sucrose formulations, while regulatory convergence on caffeine transparency reshapes competitive positioning across the region.
Microencapsulation of caffeine with delayed-release polymers is converging with natural sweetener systems to preserve sensory profiles under reduced-sugar mandates. Sports nutrition buyers in South Korea and Australia are adopting these hybrid formulations at twice the rate of conventional energy drink consumers. This convergence is compressing the reformulation cycle from 18 months to 8 months for brands seeking pharmacy-channel qualification.
China's SAMR has tightened GB 2760 enforcement for food additive limits, requiring batch-level testing documentation for imported energy drink concentrates. The industrial consequence is supplier consolidation toward integrated manufacturers with in-house analytical laboratories. Japanese and South Korean importers are responding by qualifying domestic aseptic processing partners to bypass documentation bottlenecks.
Subscription-based replenishment for powdered sachets is displacing impulse-driven single-can purchases in tier-one Chinese cities and Indian metropolitan corridors. Direct-to-consumer platforms and corporate pantry programs are capturing recurring revenue streams that convenience channels cannot match. This shift is most visible among technology sector employees in Bangalore and Shenzhen, where workplace consumption normalizes bulk purchasing.
Asia-Pacific Energy Drink Market Segmentation
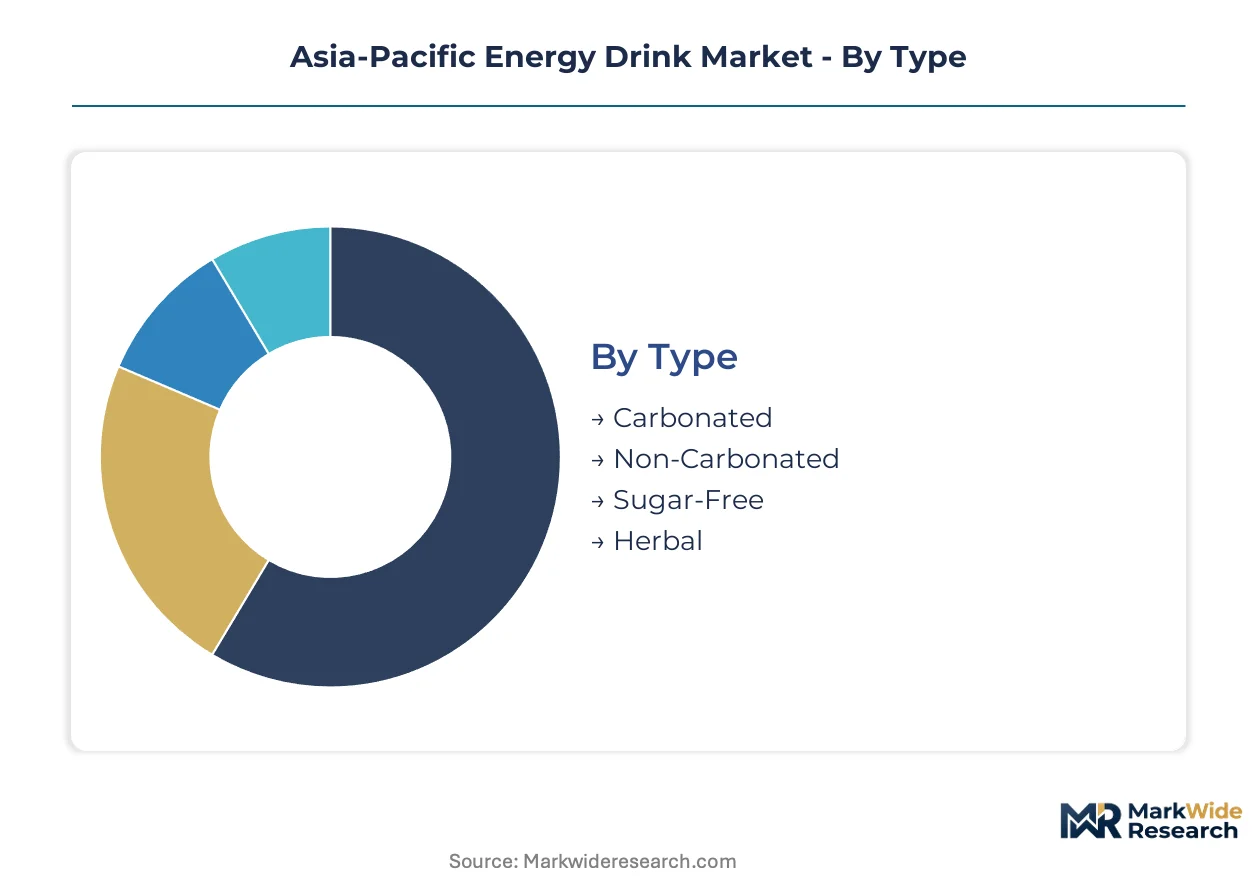
Energy drink segmentation in the Asia-Pacific region reflects divergent consumption rituals across work, fitness, and social contexts. Formulation choices and channel strategies must align with distinct age-cohort behaviors and urban infrastructure realities.
Type:
Upgrade cycles in beverage preference track regulatory pressure on sugar content and caffeine transparency mandates from China's SAMR and India's FSSAI.
- Carbonated:Established formulations dominate shelf presence through palate familiarity and ambient-stable supply chains. Demand concentrates in Southeast Asian convenience channels where refrigeration gaps persist; carbonation masks bitterness from standard caffeine loads.
- Sugar-Free:Reformulated with erythritol and stevia systems to meet FSSAI disclosure requirements and anticipated sugar-tax regimes. Adoption accelerates in Shanghai and Mumbai among diabetes-conscious professionals; pharmacy-channel placement commands premium positioning.
- Non-Carbonated:Smoother mouthfeel appeals to extended consumption occasions; Japanese PMDA functional claims favor still formats for substantiated benefit delivery.
- Herbal:Ginseng and guarana extracts target senior consumers in South Korea and traditional medicine-influenced segments; batch-level testing under GB 2760 raises compliance costs for imported botanical concentrates.
Volume placements concentrate in Carbonated; the faster expansion belongs to Sugar-Free.
Form:
Cost tier differentiation separates mass-market cans from margin-rich concentrates and subscription-driven powders.
- Ready-to-Drink:Aluminum can formats anchor retail throughput through cold-storage partnerships with Japanese and South Korean chains. China's tier-one cities and India's western urban corridors drive replenishment velocity; vending network density in lower-tier Chinese cities sustains Eastroc's domestic dominance.
- Energy Shots:Concentrated 50-60ml formats deliver 200mg+ caffeine doses for gym and pharmacy channels. Placement in Tokyo fitness centers and Bangalore corporate campuses captures unit economics three times standard retail; PMDA substantiation unlocks pharmacy distribution premiums.
- Powdered:Sachet formats enable subscription replenishment models in Shenzhen and Bangalore tech corridors; direct-to-consumer platforms bypass convenience channel limitations.
- Liquid Concentrate:Bulk dispensing for foodservice and workplace pantry programs; aseptic processing investments under India's PLI scheme support localized manufacturing.
Revenue concentration sits with Ready-to-Drink; Energy Shots deliver the steepest margin expansion trajectory.
Distribution Channel:
Channel selection determines margin capture versus volume scale across metropolitan and rural geographies.
- Convenience Stores:24-hour access aligns with extended work hours in Jakarta, Manila, and Bangkok; exclusive cold-storage agreements with Lawson and 7-Eleven chains in Japan and South Korea lock in premium placement.
- Online Retail:Subscription platforms capture recurring revenue from Bangalore and Shenzhen technology sector employees; bulk sachet purchases displace impulse single-can buying.
- Supermarkets:Multi-pack promotions drive household stockpiling; shelf-space competition intensifies as sugar-free portfolios expand.
- Vending Machines:Ambient-stable carbonated formats dominate Southeast Asian rural penetration where refrigerated last-mile networks remain unreliable.
Transaction volume concentrates in Convenience Stores; Online Retail is climbing the fastest as workplace consumption normalizes bulk purchasing.
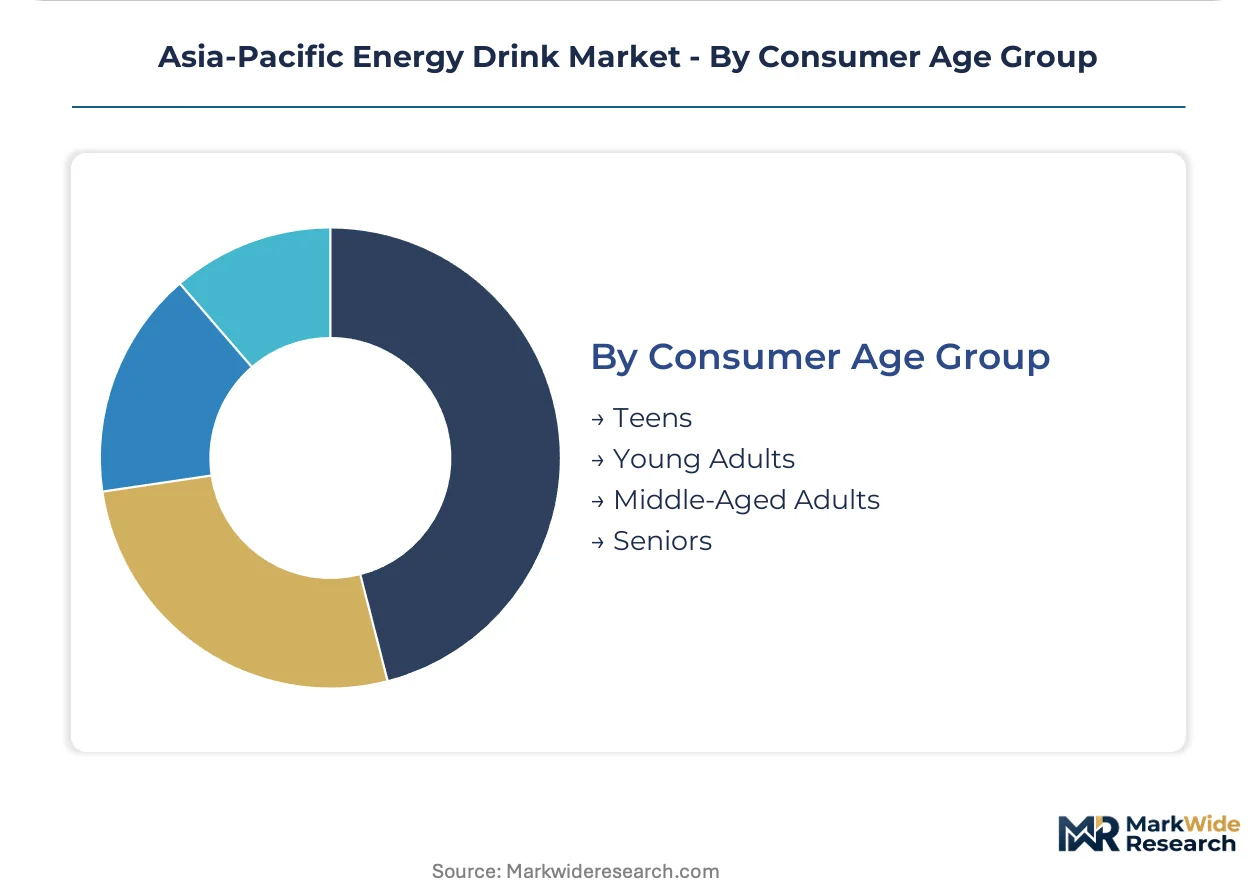
Consumer Age Group:
Maturity-stage segmentation maps formulation intensity to physiological tolerance and consumption occasion.
- Young Adults:18-35 cohort in Shanghai, Mumbai, and Jakarta faces 50+ hour work weeks; highest per-capita consumption drives demand for acute alertness solutions across all form factors.
- Middle-Aged Adults:Sugar-free migration accelerates among 36-55 professionals managing metabolic health; pharmacy-channel preference emerges in Japan and South Korea.
- Teens:Regulatory scrutiny on caffeine caps targets this segment; school proximity sales restrictions expand across Australian states and Indian jurisdictions.
- Seniors:Herbal and reduced-caffeine formulations gain traction in traditional medicine markets; South Korean ginseng-infused variants lead regional development.
Consumption intensity peaks with Young Adults; Middle-Aged Adults are gaining share fastest as reformulation investments target health-positioned migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates production capacity for taurine and aseptic processing equipment while India and Southeast Asian markets absorb the majority of finished volume. This production-consumption divide shapes logistics networks and regulatory compliance strategies across the region.
China
Shanghai and Shenzhen technology corridors drive subscription-based powdered sachet adoption among 50+ hour work-week professionals. SAMR enforces GB 2760 batch-level testing for imported concentrates, consolidating supplier relationships toward integrated manufacturers with in-house analytical laboratories. Eastroc Beverage dominates lower-tier city vending networks through deep distribution infrastructure.
India
Mumbai and Bangalore metropolitan areas anchor demand for sugar-free formulations as diabetes-prevention campaigns accelerate consumer migration. FSSAI mandates progressively stricter sugar content labeling and recommended serving sizes, compressing reformulation timelines. The PLI scheme for food processing supports localized aseptic manufacturing investments in western urban corridors.
Japan
Tokyo and Osaka fitness centers command 40% price premiums for pharmacy-channel energy shots with PMDA-substantiated functional claims. METI coordinates with PMDA on dual-track compliance where benefit statements unlock specialized distribution. Cold-storage partnerships with Lawson and 7-Eleven chains lock in premium retail placement for carbonated variants.
South Korea
Seoul Capital Area professionals adopt microencapsulated caffeine formulations at twice the rate of conventional energy drink consumers. MFDS alignment with functional food standards creates pathway for pharmacy-grade positioning. Busan-Ulsan industrial clusters support domestic aseptic processing partnerships that bypass Chinese import documentation bottlenecks.
Vietnam
Ho Chi Minh City and Hanoi present whitespace opportunity with per-capita consumption at one-third of Thai levels. Ambient-stable formulations dominate rural distribution where refrigerated last-mile networks remain unreliable. Powdered sachet subscription models target underpenetrated urban professional segments.
Asia-Pacific Energy Drink Market Competitive Environment
Capital-heavy producers with captive manufacturing assets compete with asset-light brand licensors across formulation and distribution. The vendor base separates into three tiers: integrated beverage conglomerates controlling upstream chemical synthesis, regional specialists with deep vending network penetration, and international licensors relying on third-party co-manufacturing. Dominant competitive moves include exclusive cold-storage retail partnerships and backward integration into taurine synthesis capacity.
Among integrated Asia-Pacific producers, Eastroc Beverage(Group) Co., Ltd. and Fujian Dali Food Group Co., Ltd. exemplify the domestic Chinese archetype with manufacturing-forward positioning and lower-tier distribution control. Osotspa Co., Ltd. represents the Southeast Asian specialist model with concentrated market presence in Thailand and adjacent markets. Red Bull GmbH and Monster Beverage Corporation occupy the multinational licensor tier, leveraging brand equity and motorsport-linked marketing without direct production ownership.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Monster Beverage Corporation |
| Eastroc Beverage(Group) Co., Ltd. |
| Fujian Dali Food Group Co., Ltd. |
| T.C. Pharmaceutical Industries Company Limited |
| Osotspa Co., Ltd. |
| Otsuka Pharmaceutical Co., Ltd. |
| Suntory Holdings Limited |
| Rockstar, Inc. |
| Others |
Value Chain & Pricing Dynamics
Microencapsulation of caffeine with delayed-release polymers is compressing reformulation cycles from 18 months to 8 months while simultaneously concentrating supplier relationships toward integrated manufacturers with in-house analytical laboratories in China and South Korea. This production-method transition simultaneously elevates compliance costs for smaller formulators and reshapes margin structures across pharmacy-grade versus convenience-channel positioning.
Pricing Analysis
Margin tightening in sugar-free tiers reflects simultaneous FSSAI disclosure mandates and anticipated sugar-tax regimes across India and Southeast Asian markets. Three-tier pricing structure across pharmacy-grade, premium retail, and mass-market economy levels separates PMDA-substantiated functional claims from standard convenience placement. Price differentiation traces to certification grade and cold-storage partnership exclusivity. Corporate pantry buyers in Bangalore and Shenzhen technology corridors exhibit lowest price sensitivity; rural Southeast Asian vending consumers face highest cost compression.
Supply Chain Analysis
Taurine supply rests on Chinese chemical hub concentration, with synthetic production clusters exposing formulators to input volatility and dual-use export control exposure. Raw material dependencies span caffeine alkaloid extraction, erythritol sweetener systems, and aseptic packaging films. Single-source vulnerability concentrates in taurine synthesis capacity. Distribution runs through ambient-stable carbonated formats for Southeast Asian rural penetration, with refrigerated last-mile networks anchoring premium placement in Japanese and South Korean convenience chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sugar-reduction technologies and alternative sweetener systems are displacing conventional sucrose formulations, with microencapsulated caffeine delivery replacing standard load formulations across pharmacy-channel qualification pathways.
For Market Incumbents: Acquire captive taurine synthesis capacity to neutralize Chinese chemical hub concentration risk and input volatility exposure. Deepen cold-storage partnership exclusivity with Lawson and 7-Eleven chains in Japan and South Korea to defend shelf position against emerging entrants. Invest in in-house analytical laboratories to meet SAMR batch-level testing documentation requirements and compress supplier qualification timelines. For New Entrants and Emerging Players: Pharmacy channel partnerships unlock 40% price premiums over convenience placement through PMDA functional claims substantiation. Vietnam and Philippines whitespace offers powdered sachet subscription entry with per-capita consumption at one-third of Thai levels. Corporate pantry direct-to-consumer platforms in Shenzhen and Bangalore technology corridors provide lowest customer acquisition cost versus retail shelf competition. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated beverage conglomerates with upstream chemical synthesis control and deep lower-tier distribution networks. Long-term viability favors producers with backward integration into taurine capacity and aseptic processing assets under India's PLI scheme alignment. Watch FSSAI caffeine cap evaluations as inflection trigger for reformulation cost acceleration and portfolio obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Taurine Synthesis | Captive supply of critical input neutralizes Chinese hub concentration and export control exposure. |
| PMDA Functional Claims Substantiation | Pharmacy-channel qualification unlocks premium pricing and specialized distribution in Japanese market. |
| Powdered Sachet Subscription Launch | Direct-to-consumer replenishment captures recurring revenue from Bangalore and Shenzhen technology employees. |
| Aseptic Processing Investment under PLI | Localized manufacturing bypasses SAMR import documentation bottlenecks for Indian market entry. |
| Cold-Storage Partnership Exclusivity | Lawson and 7-Eleven agreements lock in premium retail placement against competitor shelf displacement. |
Study Parameters
Document review covered customs and trade records, FSSAI regulatory filings, and PMDA functional claims databases, complemented by interviews with brand managers at integrated beverage producers, category buyers at Japanese and South Korean retail chains, formulation R&D directors, and supply planners at aseptic processing facilities. Secondary validation drew from SAMR GB standard enforcement notices, MFDS functional food alignment guidelines, and Nielsen retail audit data across metropolitan corridors. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segmentation outputs reflect discrete modeling across carbonated, sugar-free, non-carbonated, and herbal type categories; ready-to-drink, energy shot, powdered, and liquid concentrate form factors; convenience store, online retail, supermarket, and vending machine channels; and young adult, middle-aged adult, teen, and senior age cohorts. CAGRs were derived from regression analysis of historical consumption velocity against regulatory event timing and urban work-hour extension patterns. Forecast inputs incorporated diabetes-prevention campaign intensity and pharmacy-channel expansion trajectories.
Several conditions sit outside the modeled scope, including abrupt caffeine cap implementation timelines, sugar-tax rate finalization, and taurine export control escalation. Forecasts reflect documented assumptions on regulatory convergence pace and urban infrastructure development. Supply disruption from Chinese chemical hub consolidation and PMDA claims rejection rates warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Europe Coconut Water Market
Beverages
United States Soy Beverages Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Europe Bottled Water Market
Beverages
Peanut Oil Market
Beverages
Low Fat Drinks Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Smoothies Market
Beverages
Rose Floral Water Market
Beverages
Global Fruit Juice Concentrate Market
Beverages
Tonic Water Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Double Valve Moka Pots Market
Beverages
US Bubble Tea Market