
 Bottled Water Processing Market | 2026-2036
Bottled Water Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Water Processing Market Intelligence
The bundling of purified and mineral water into large-format multi-packs for retail chains is expanding buyer choice and influencing purchasing patterns. This configuration shift favors large-scale producers with sophisticated logistics capabilities. Nestlé leverages its global brand portfolio and distribution network to capture share in premium segments. GEA Group Aktiengesellschaft specializes in providing integrated processing lines and engineering services. Niagara Bottling competes on volume and operational efficiency, primarily serving private-label retail clients in the United States.
Bottled water processing encompasses the multi-stage treatment of source water to produce a safe, stable, and commercially viable packaged beverage. The process often involves filtration to reduce turbidity and remove particulates, followed by purification to lower total dissolved solids (TDS) below 500 parts per million. Purified Water represents the largest product type by volume, driven by its lower input costs. In terms of technology, Reverse Osmosis is the most widely adopted method for purification, while Ultraviolet Treatment serves as a critical final sterilization step before bottling.
Regulatory frameworks establish the core operational and quality standards for the industry. In the United States, the FDA sets contaminant limits and labeling rules for bottled water. The European Union's directives, enforced by bodies like the EFSA, define specific criteria for natural mineral and spring waters. In India, the Bureau of Indian Standards (BIS) mandates certification for all processed water sold. Navigating evolving regulations on plastic packaging and water source sustainability is a primary strategic challenge for all market participants.
Market Dynamics
The dual pressure of meeting stringent purification standards, such as those set by the FDA and EFSA, and managing water source sustainability is the central force shaping the bottled water processing market's technological and operational priorities.
Growth Catalysts
- Technology Advancement:Innovations in Reverse Osmosis membrane technology are improving water recovery rates and reducing energy consumption, making high-purity water production more economically viable for producers.
- Urbanization in India:Rapid urban growth and public concern over the quality of municipal water supplies in India create persistent demand for water processed under Bureau of Indian Standards (BIS) certification.
- Hospitality Sector Demand:Hotels and restaurants require a consistent, safe supply of processed water for drinking and food preparation, driving bulk and multi-pack sales formats from commercial processors.
Market Restraints
- Packaging Cost Volatility:The price of PET resin, a primary input for bottles, is subject to fluctuations in global oil markets, creating margin pressure for processors, especially in the volume-driven private-label segment.
- Water Source Scarcity:Increasing competition for water resources and local community opposition to large-scale water extraction can restrict access to source water, creating significant operational and reputational risk.
- Regulatory Friction on Plastics:Evolving regulations in jurisdictions like the European Union that mandate recycled content or ban certain single-use plastics add significant compliance costs and supply chain complexity.
Strategic Opportunities
- Functional Water Development:There is an opportunity to develop and market enhanced waters with added minerals, electrolytes, or specific pH levels, targeting health-conscious consumers in developed markets.
- DTC Subscription Models:Bypassing traditional retail, direct-to-consumer subscription services for large-format water dispensers and refills offer a recurring revenue stream and direct customer relationship.
- Sustainable Packaging Innovation:Investment in alternative packaging such as aluminum cans, glass bottles, or biodegradable plastics can create brand differentiation and appeal to environmentally conscious market segments.
Industry Challenges
- Capital Expenditure for Automation:Upgrading to fully automated processing and bottling lines to improve efficiency and hygiene requires substantial capital investment, posing a barrier for smaller, regional operators.
- Navigating Certification Labyrinths:Securing and maintaining necessary certifications, such as the BIS license in India or NSF certification in the US, involves lengthy and complex validation processes that can delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Water Processing Market |
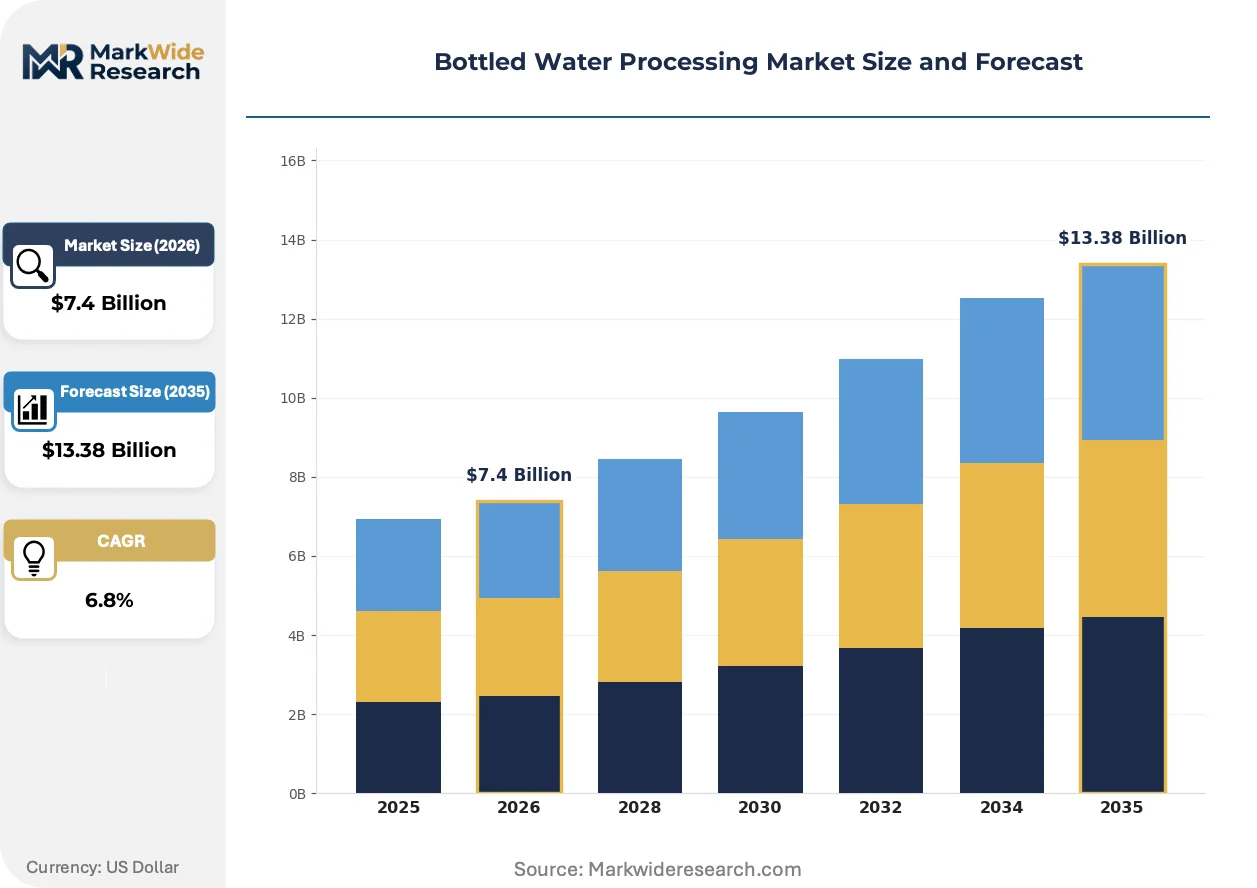
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Water, Mineral Water, Purified Water, Sparkling Water, Distilled Water Processing Technology: Reverse Osmosis, Ultraviolet Treatment, Ozonation, Filtration, Carbonation Packaging Type: Plastic Bottles, Glass Bottles, Cartons, Cans, Pouches End User: Retail Chains, Hospitality Sector, Food Service Providers, Fitness Centers, Educational Institutions |
| Companies Covered | Nestlé, PepsiCo, DuPont, BlueTriton Brands, Danone, GEA Group Aktiengesellschaft, The Coca-Cola Company, Niagara Bottling, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Water Processing Market Strategic Shifts & Innovations
Advanced purification methods and digital traceability are defining the next phase of market evolution. This shift responds to a dual mandate from consumers and regulators for products that are both exceptionally pure and transparently sourced, moving beyond basic safety compliance.
Next-generation Reverse Osmosis systems feature advanced membrane chemistry that significantly boosts contaminant rejection while lowering operational pressures. Large-scale producers targeting premium purified water segments are rapidly adopting these systems to enhance efficiency. This high-tech requirement is consolidating market power with larger firms that can afford the capital outlay, raising barriers to entry.
The European Union’s directives on natural mineral waters and spring waters impose strict criteria on source protection and bottling at the source. This regulation ensures a clear quality and origin distinction, preventing commingling or extensive treatment beyond minor filtration. Consequently, brands marketing products as "natural mineral water" in the EU face higher operational and compliance burdens compared to purified water producers.
Consumer demand for source transparency is fundamentally altering product labeling and marketing strategies. Opaque branding is yielding to packaging that includes QR codes or website links detailing water analysis reports, source location, and the specific purification process used. This trend is most pronounced in the premium and functional water categories across North America and Europe.
Bottled Water Processing Market Segmentation
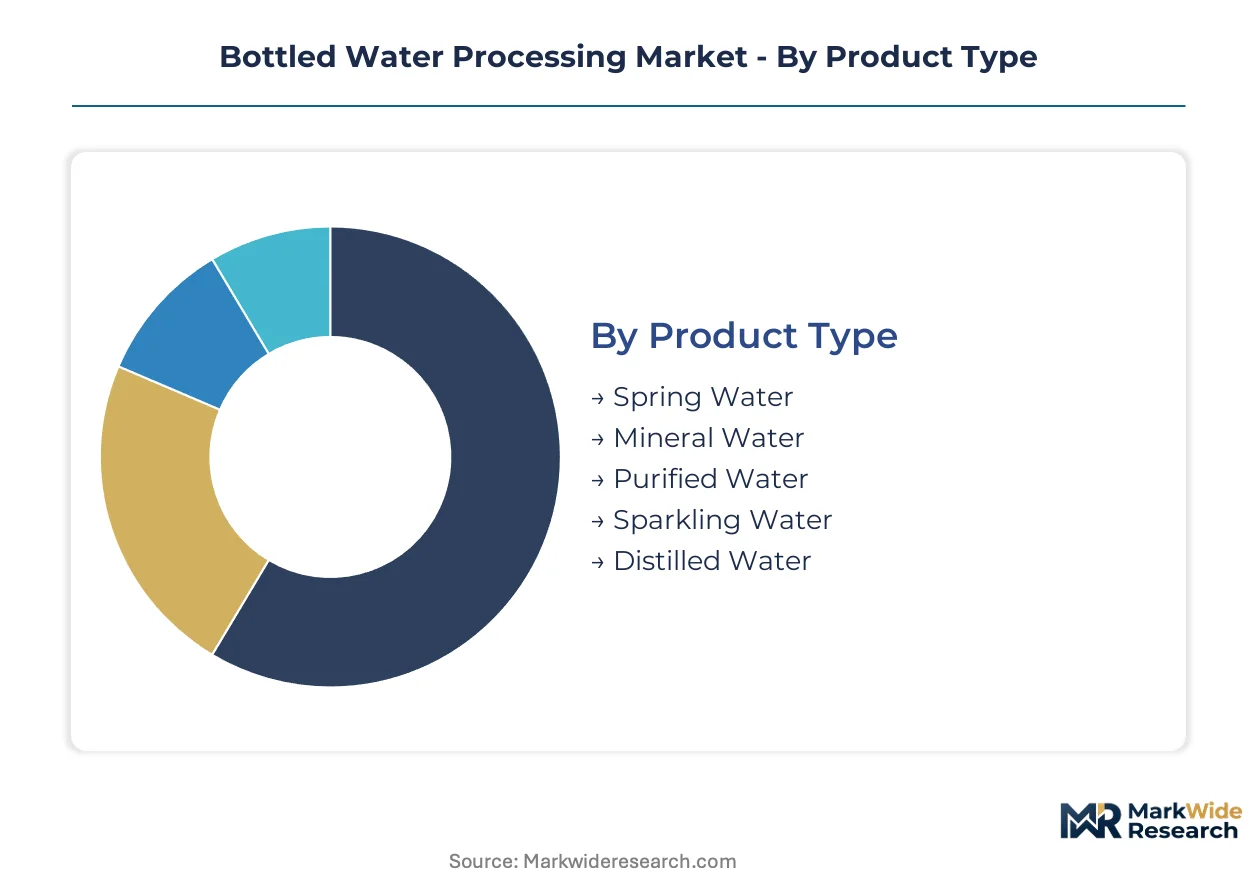
Understanding the bottled water processing market through segmentation reveals critical demand drivers and technological preferences across diverse consumer bases. This analysis highlights how product attributes, processing methods, packaging choices, and end-user requirements shape competitive strategies for market participants.
Product Type:
Product type segmentation distinguishes between naturally sourced waters requiring minimal treatment and those undergoing extensive purification processes.
- Purified Water:Undergoes multi-stage treatment, often including reverse osmosis and distillation, to remove impurities and dissolved solids. Demand concentrates in India and other urbanizing regions due to concerns over municipal water quality and lower input costs.
- Mineral Water:Originates from underground sources, protected from pollution, and characterized by constant mineral composition. European consumers drive demand for natural mineral water, valuing its inherent mineral content and strict origin regulations.
- Spring Water:Sourced from an underground formation from which water flows naturally to the surface, requiring minimal processing.
- Sparkling Water:Contains dissolved carbon dioxide, either naturally occurring or artificially added, appealing to consumers seeking effervescence.
- Distilled Water:Produced by boiling water and condensing the steam, effectively removing all minerals and impurities for specialized uses.
Volume placements concentrate in Purified Water; the faster expansion belongs to the premium segments like Mineral Water.
Processing Technology:
Processing technologies are differentiated by their primary function in water treatment, ranging from particulate removal to microbiological sterilization.
- Reverse Osmosis:Employs semi-permeable membranes to remove dissolved solids, ions, and larger molecules from water, enhancing purification efficiency. Large-scale producers globally adopt advanced RO systems to achieve high purity standards and reduce operational energy.
- Ultraviolet Treatment:Utilizes UV light to disinfect water by inactivating bacteria, viruses, and other microorganisms without chemical addition. This method serves as a critical final sterilization step before bottling across numerous facilities, ensuring product safety.
- Ozonation:Involves injecting ozone gas into water for disinfection and oxidation of organic contaminants, leaving no chemical residues.
- Filtration:Removes suspended solids, sediment, and larger particulates from source water using various media, serving as a pre-treatment step.
- Carbonation:Introduces carbon dioxide into water to create effervescence, a key process for sparkling water products.
Efficiency gains are primarily driven by Reverse Osmosis advancements, while Ultraviolet Treatment ensures final product safety.
Packaging Type:
Packaging types reflect a balance between cost efficiency, consumer convenience, and environmental considerations across different market segments.
- Plastic Bottles:Dominate the market due to their low cost, light weight, and durability, facilitating widespread distribution. Regulatory friction on single-use plastics in Europe is prompting innovation towards recycled content and alternative materials.
- Glass Bottles:Offer a premium aesthetic and are perceived as more sustainable due to recyclability, appealing to health-conscious consumers in developed markets. This packaging type supports brand differentiation in high-end hospitality and retail chains.
- Cartons:Provide an alternative to plastic, often used for larger format water or flavored water, appealing to environmentally aware consumers.
- Cans:Gaining traction for their recyclability and portability, especially in functional water and sparkling water segments in North America.
- Pouches:Offer a low-cost, lightweight solution for bulk water or emergency relief, particularly in developing regions.
The majority of processed water is distributed in Plastic Bottles, though Cans are gaining traction due to sustainability mandates and consumer preferences.
End User:
End-user segmentation highlights distinct demand characteristics, from bulk consumption requirements to individual retail purchases.
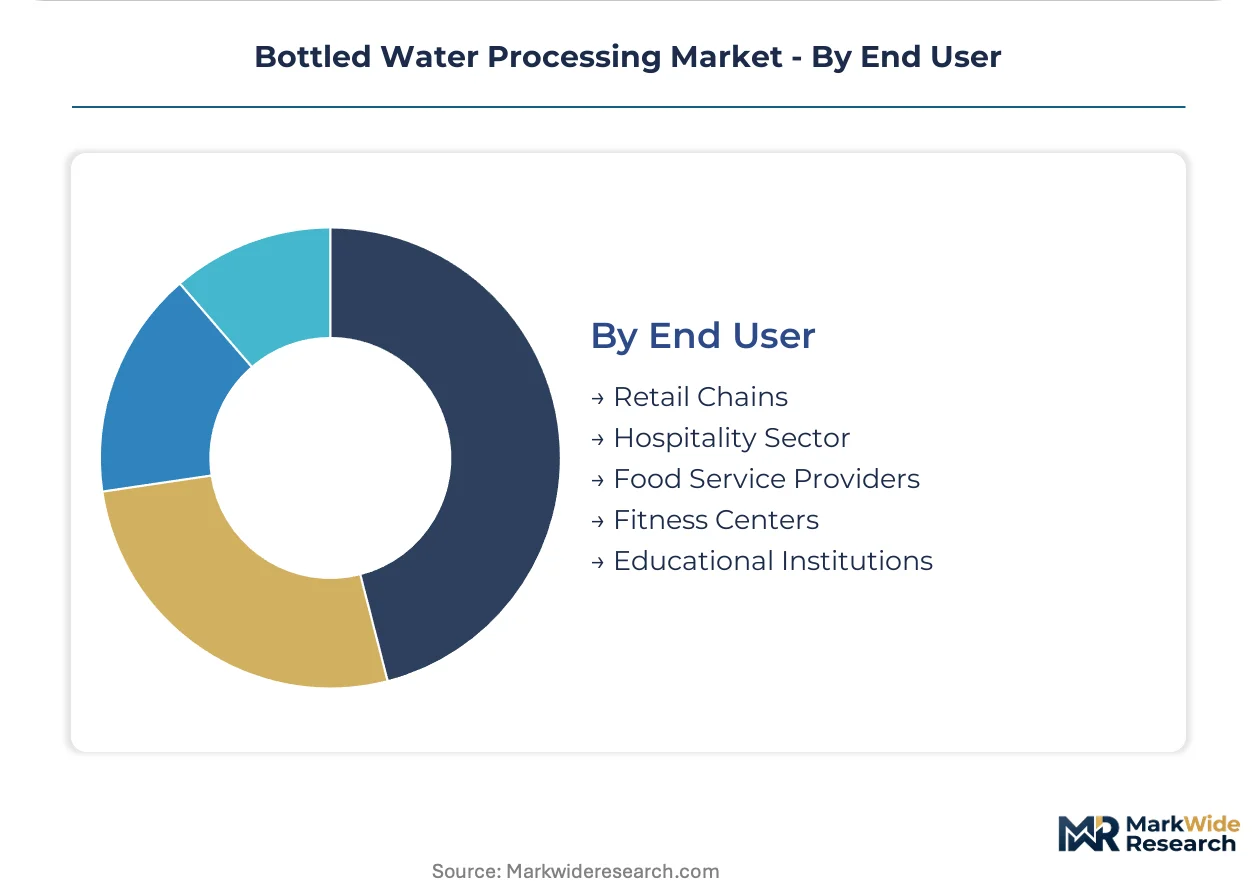
- Retail Chains:Represent the largest distribution channel, demanding multi-pack formats and private-label options for mass consumer access. Niagara Bottling primarily serves this segment in the United States, focusing on operational efficiency.
- Hospitality Sector:Requires consistent, high-quality processed water for guest consumption and food preparation, driving bulk and premium bottled water sales. Hotels and restaurants prioritize reliable supply and brand reputation for their clientele.
- Food Service Providers:Utilize processed water for cooking, beverage preparation, and customer consumption in various dining establishments.
- Fitness Centers:Offer bottled water as a convenience product to members, often featuring enhanced or functional water varieties.
- Educational Institutions:Provide processed water through vending machines or bulk dispensers, addressing student and staff hydration needs.
High volume procurement characterizes Retail Chains, while the Hospitality Sector prioritizes consistent quality and brand alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentration in India, driven by rapid urbanization and concerns over municipal water quality, establishes a key focus area for bottled water processing investments. This dynamic creates a robust environment for producers meeting local standards. Market participants also navigate diverse regulatory landscapes across other major economies, influencing operational strategies and product offerings.
India
Urban growth and public health concerns drive persistent demand for processed water across India. The Bureau of Indian Standards (BIS) mandates certification for all processed water sold, ensuring consumer safety and quality. Processing facilities in the Delhi-NCR region and Maharashtra are expanding to meet this significant and growing consumer need.
United States
Retail chains and the hospitality sector in the United States demand large volumes of purified and spring water. The FDA establishes stringent contaminant limits and labeling regulations for all bottled water products. Major bottling operations in California and the Southeast focus on high-volume production for national distribution and private-label clients.
Germany
German consumers seek premium mineral and sparkling waters, valuing natural origin and specific mineral profiles. European Union directives, enforced by the EFSA, impose strict criteria on natural mineral water sources and processing. Specialized producers in Bavaria and the Rhine-Ruhr region focus on high-quality bottling and sustainable sourcing practices.
China
Rapid urbanization and a growing middle class in China stimulate demand for purified and processed bottled water. China's national food safety standards regulate bottled water production and quality, ensuring consumer protection. Large-scale bottling plants in the Yangtze River Delta and Pearl River Delta serve metropolitan areas with extensive distribution networks.
France
French consumers prioritize natural mineral and spring waters, often associated with specific regional sources and brand heritage. European Union regulations mandate strict source protection and minimal processing for natural mineral waters. Bottling facilities in the Auvergne-Rhône-Alpes region capitalize on protected natural springs for premium product lines.
Bottled Water Processing Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure in bottled water processing. Global beverage companies leverage existing distribution and brand equity, targeting diverse consumer segments. Specialized industrial engineering firms provide integrated processing lines and advanced purification technologies. Strategic partnerships and capacity expansion are dominant competitive moves across the industry.
Global brand portfolio holders, such as Nestlé, leverage extensive distribution networks and a diverse brand portfolio to capture premium segment share across diverse geographies. This approach allows them to address various consumer preferences and market demands. GEA Group Aktiengesellschaft represents the specialized industrial engineering archetype, providing integrated processing lines and advanced engineering services to large-scale producers worldwide, emphasizing purification efficiency. Niagara Bottling anchors the high-volume private-label segment in the United States, focusing on operational efficiency and volume-driven strategies primarily for retail chains, ensuring broad market access.
| Leading Market Players |
|---|
| Nestlé |
| PepsiCo |
| DuPont |
| BlueTriton Brands |
| Danone |
| GEA Group Aktiengesellschaft |
| The Coca-Cola Company |
| Niagara Bottling |
| Alfa Laval |
| Others |
Cost & Logistics Intelligence
The regulatory distinction between natural mineral water and extensively processed purified water drives a clear divergence in both pricing and supply chain configurations. This bifurcation separates premium, source-dependent products from volume-driven, cost-optimized offerings.
Pricing Analysis
Lead-time-driven pricing for specialized components and long-term contracts for bulk volumes characterize the market. The dominant pricing model is per-unit transactional, with long-term offtake agreements common for large-volume buyers. Price differentiation stems from the quality grade of the water, specific certification levels (e.g., BIS, EFSA), and brand premium. Pricing pressure stems from packaging cost volatility, especially in the private-label segment. Retail chains purchasing private-label products represent the most price-sensitive buyers, while premium hospitality clients are less sensitive.
Supply Chain Analysis
PET resin supply for plastic bottles relies heavily on global oil markets, creating significant input cost dependencies. Geographic supply concentration for processing facilities exists in India for high-volume purified water and in Germany and France for natural mineral waters. Key raw material dependencies include source water, PET resin, and specialized membranes for Reverse Osmosis. Packaging cost volatility and water source scarcity represent structural supply chain risks. Distribution runs primarily through established retail chains and direct commercial contracts with the hospitality sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, where stringent regulations like the EU directives for natural mineral waters create a significant barrier-to-entry moat for compliant players.
For Market Incumbents:Hedge against PET resin price volatility by diversifying packaging materials, investing in aluminum can lines, or securing long-term contracts. Consolidate regional water sources through strategic acquisitions to mitigate scarcity risks and ensure consistent supply. Invest in advanced Reverse Osmosis membrane technology to improve water recovery rates and reduce energy consumption, enhancing operational efficiency. This proactive approach mitigates threats from evolving plastic regulations and increasing competition for water resources.
For New Entrants and Emerging Players:Health-conscious consumers seeking enhanced waters represent an underserved buyer archetype. Target niche markets with functional water products offering added minerals or specific pH levels, leveraging sustainable packaging like glass bottles or aluminum cans. A direct-to-consumer subscription model for large-format water dispensers offers a unique go-to-market angle. The premium functional water segment in developed markets presents the most penetrable opportunity.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized technology providers, particularly those innovating in Reverse Osmosis and UV treatment, given the continuous demand for purification efficiency. The long-term viability of this market rests on fundamental hydration needs and increasing quality expectations. Focus on acquiring firms with proprietary purification technologies or secure access to high-quality water sources. Success in sustainable packaging innovation is a key signal to watch for future growth inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced RO System Deployment | Enhances purification efficiency and reduces energy consumption for large producers. |
| Sustainable Packaging Innovation | Attracts environmentally conscious consumers and mitigates regulatory risks. |
| Direct-to-Consumer Channel Development | Builds recurring revenue streams and direct customer relationships. |
| Water Source Acquisition/Protection | Secures long-term raw material access and mitigates scarcity risks. |
| Functional Water Portfolio Expansion | Captures premium segment growth from health-conscious consumers. |
Research Approach
FDA regulations, EFSA directives, and BIS standards formed the secondary backbone for market sizing and trend identification. Primary interviews with plant managers, R&D directors, procurement leads for PET resin, and retail category buyers provided critical qualitative insights. This approach combined bottom-up data aggregation with top-down market validation.
A bottom-up analytical lens aggregated segment data, validated by top-down market sizing across the analysis window. Segmentation dimensions modeled included product type (purified, mineral), processing technology (RO, UV), packaging type (plastic, glass), end-user (retail, hospitality), and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected growth drivers. Urbanization rates in India and PET resin price forecasts served as key forecast inputs.
Revisions become necessary when significant shifts in global oil prices, new plastic packaging regulations, or major water scarcity events materialize. Forecasts reflect current regulatory environments and technological development trajectories. Geopolitical stability affecting supply chains and consumer shifts towards tap water alternatives are triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Drinking Water Market
Beverages
United States Smoothie Market
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
Rose Floral Water Market
Beverages
Milk Tea Powder Market
Beverages
Whole Grain Drinks Market
Beverages
India Bottled Water Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Sparkling Water Machine Market
Beverages
Plant Based Beverages Market
Beverages
Gluten Free Beverages Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Fermented Foods and Beverages Market
Beverages
Adaptogenic Beverages Market
Beverages
Chocolate Powdered Drinks Market
Beverages
United States Soy Beverages Market