
 GCC Bottled Water Market | 2026-2036
GCC Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Bottled Water Market Intelligence
Multi-source procurement among Gulf retailers is broadening supplier rosters beyond traditional incumbents. Danone S.A. leverages its European filtration expertise to compete in premium mineral water segments. Nestlé S.A. anchors volume through deep distribution into Saudi Arabian hypermarkets. Masafi LLC dominates Emirati shelf space with localized sourcing from Hajar Mountain aquifers.
GCC bottled water comprises packaged drinking water treated through reverse osmosis, ultraviolet sterilization, or ozone disinfection to meet portability and safety standards for consumer consumption, with total dissolved solids typically ranging below 500 ppm for still variants and carbonation levels of 3-4 volumes for sparkling products. Still water occupies the largest volume share across household and office channels, while flavored water represents the fastest-expanding margin pool as health-conscious consumers shift from sugar-sweetened beverages. Plastic bottles sustain dominant packaging economics, though glass bottles command premium positioning in hotel and restaurant segments where presentation drives selection.
Saudi Arabia's Saudi Food and Drug Authority and the UAE's Emirates Authority for Standardization and Metrology enforce mineral content labeling and microbiological safety thresholds that determine market access for both domestic producers and imports. The Gulf Standardization Organization's regional harmonization of bottled water specifications reduces cross-border compliance friction among member states. Stakeholders must monitor desalination cost volatility and municipal water tariff reforms that could alter the price gap between bottled and tap alternatives.
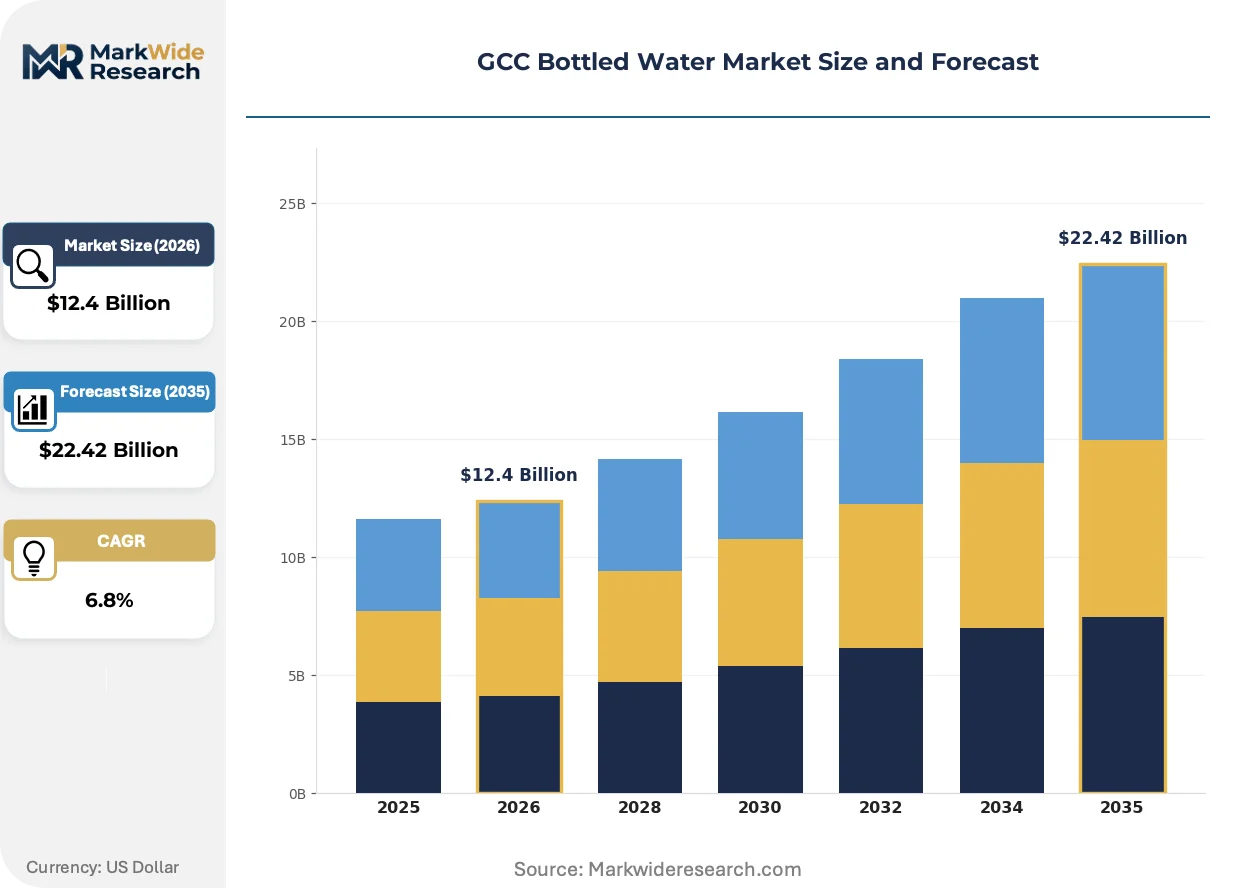
Market Dynamics
Desalination cost volatility and municipal water tariff reforms are compressing the price gap between bottled and tap alternatives across Gulf Cooperation Council states, forcing producers to defend margin positions through packaging differentiation and channel specialization.
Growth Catalysts
- Hospitality procurement expansion:Saudi Arabia's luxury hotel sector is expanding volume commitments for premium still and sparkling variants, with procurement teams specifying glass presentation formats for foodservice channels.
- SFDA labeling mandates:Saudi Food and Drug Authority mineral content disclosure rules are elevating consumer transparency expectations and rewarding compliant domestic producers with retail shelf access.
- Reverse osmosis advancement:Energy recovery device improvements in membrane filtration are reducing unit production costs for packaged drinking water treated from municipal desalination sources.
Market Restraints
- Feedwater cost volatility:Natural gas price swings directly impact desalination operating costs, compressing bottler margins when municipal tariffs remain fixed by government decree.
- Single-source aquifer dependence:Emirati producers relying on Hajar Mountain groundwater face volume constraints during drought cycles that limit premium mineral water output expansion.
- Plastic packaging taxation risk:Circular economy policy discussions across Gulf Standardization Organization member states threaten to impose levies on polyethylene terephthalate bottle formats that dominate mass-market economics.
Strategic Opportunities
- Flavored water white space:Health-conscious consumers in Kuwait and Bahrain are shifting from sugar-sweetened beverages, creating margin expansion potential for zero-calorie infused variants positioned between still water and soft drinks.
- Ozone-UV hybrid sterilization:Convergence of ultraviolet and ozone disinfection technologies enables extended shelf life without chemical residual taste, opening export qualification to stricter import jurisdictions.
- Office direct-delivery channels:Corporate hydration contracts bypassing hypermarket retail are capturing recurring revenue streams with lower customer acquisition costs in Riyadh and Dubai commercial districts.
Industry Challenges
- Microbiological testing capacity:Gulf Standardization Organization harmonized standards require expanded laboratory certification that outpaces qualified technician availability in Oman and Qatar.
- Legacy distribution reconfiguration:Transition from wholesale-centric models to e-commerce fulfillment requires cold-chain infrastructure investment that strains mid-tier producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Bottled Water Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Still Water, Sparkling Water, Flavored Water, Mineral Water Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Hotels End User: Households, Offices, Restaurants, Sports Facilities |
| Companies Covered | Danone S.A., Almarai Company, Nestlé S.A., Mai Dubai LLC, The Coca-Cola Company, PepsiCo Inc., Masafi LLC, Crystal Mineral Water and Refreshments LLC, Agthia Group PJSC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Bottled Water Market Strategic Shifts & Innovations
Active packaging technologies and regulatory disclosure requirements are converging to reshape competitive positioning across still, sparkling, and flavored water segments, with differentiation increasingly anchored in provenance verification rather than price alone.
Smart bottle caps with near-field communication tags are rewriting how consumers interact with product origin data. Premium hotel chains and airline lounges across the UAE are piloting these formats to authenticate Hajar Mountain aquifer sourcing. The technology is compressing the information advantage previously held by established brands with legacy consumer trust.
Emirates Authority for Standardization and Metrology tightened bottled water quality protocols in 2024, mandating expanded heavy metal testing and real-time production monitoring. Domestic UAE producers face compliance capital expenditure requirements that favor scaled operators with existing laboratory infrastructure. Smaller importers are responding by consolidating shipment volumes to amortize testing costs across larger batch qualifications.
Subscription-based home and office delivery is displacing supermarket bulk purchasing among dual-income households in Saudi Arabia's Eastern Province. Direct-to-consumer platforms are capturing recurring revenue with scheduled replenishment algorithms that reduce price sensitivity. This behavioral pivot is most visible in Dammam's residential compounds where expatriate populations prioritize convenience over per-unit cost optimization.
GCC Bottled Water Market Segmentation
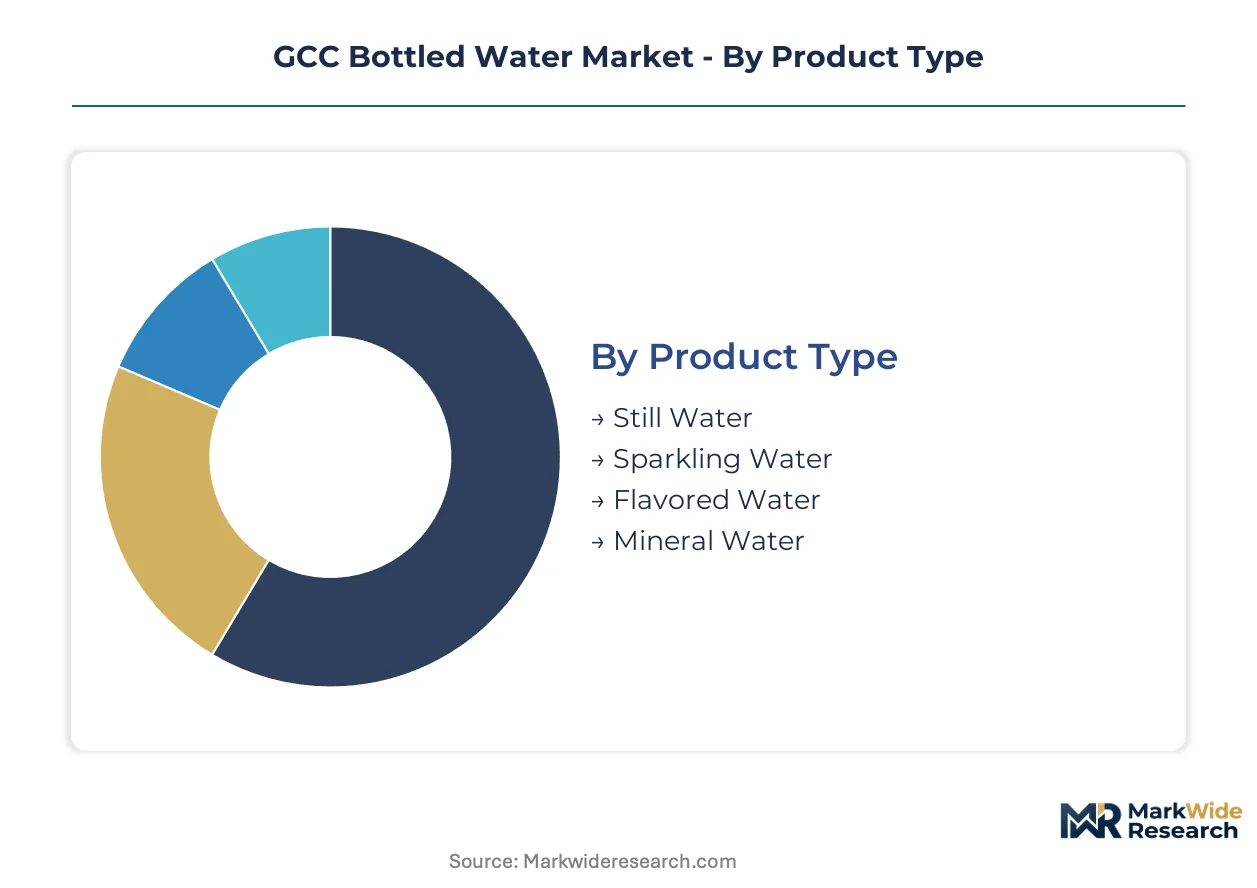
GCC bottled water producers calibrate portfolio depth against channel-specific requirements, with product formulation and packaging format decisions locked in by end-use consumption context. Segmentation discipline separates volume-driven commodity plays from margin-accretive premium positioning across Saudi Arabia and UAE markets.
Product Type:
Standardization dominates at the commodity tier while premium tiers demand provenance differentiation and carbonation engineering.
- Still Water:Reverse osmosis and UV-ozone treated variants with total dissolved solids below 500 ppm anchor household and office consumption. Procurement teams across Saudi Arabia's Eastern Province specify bulk formats for residential compounds where expatriate populations prioritize hydration convenience.
- Mineral Water:Naturally sourced from Hajar Mountain aquifers with stable mineral profiles, commanding shelf space in UAE luxury retail. Emirates Authority for Standardization and Metrology labeling mandates elevate transparency requirements that favor established domestic producers with laboratory infrastructure.
- Sparkling Water:Carbonation levels of 3-4 volumes serve foodservice presentation requirements in Riyadh-Dammam corridor hotels.
- Flavored Water:Zero-calorie infused variants capture health-conscious consumers shifting from sugar-sweetened beverages in Kuwait and Bahrain.
Most installed capacity flows through Still Water. Expansion is steepest in Flavored Water.
Packaging Type:
Unit economics and channel aesthetics dictate material selection, with cost-per-liter optimization clashing against premium presentation requirements.
- Plastic Bottles:Polyethylene terephthalate formats sustain mass-market economics across Saudi Arabian hypermarkets. Circular economy policy discussions threaten future levy impositions that would compress margins for unrecycled formats.
- Glass Bottles:Premium positioning in UAE hotel and restaurant segments where presentation drives selection, with procurement teams mandating glass for foodservice channels.
- Tetra Packs:Lightweight rectangular formats suit office direct-delivery channels with space-constrained storage.
- Pouches:Flexible formats target single-serve convenience in sports facility vending.
Plastic Bottles carry the heaviest volume throughput. Glass Bottles are gaining share fastest in hospitality procurement.
Distribution Channel:
Channel control determines pricing power and consumer data access, with e-commerce insurgents rewriting replenishment patterns.
- Supermarkets:Saudi Arabian hypermarkets anchor volume for Nestlé and Danone through deep distribution partnerships. Shelf space negotiations favor scaled operators with marketing co-investment capacity.
- Online Retail:Subscription-based platforms with scheduled replenishment algorithms capture recurring revenue from dual-income households in Dammam residential compounds.
- Convenience Stores:Impulse-driven single-serve purchases concentrate in urban UAE corridors with high foot traffic.
- Hotels:Luxury procurement teams specify premium still and sparkling variants with provenance authentication requirements.
Supermarkets process the largest transaction volumes. Online Retail shows the steepest expansion trajectory.
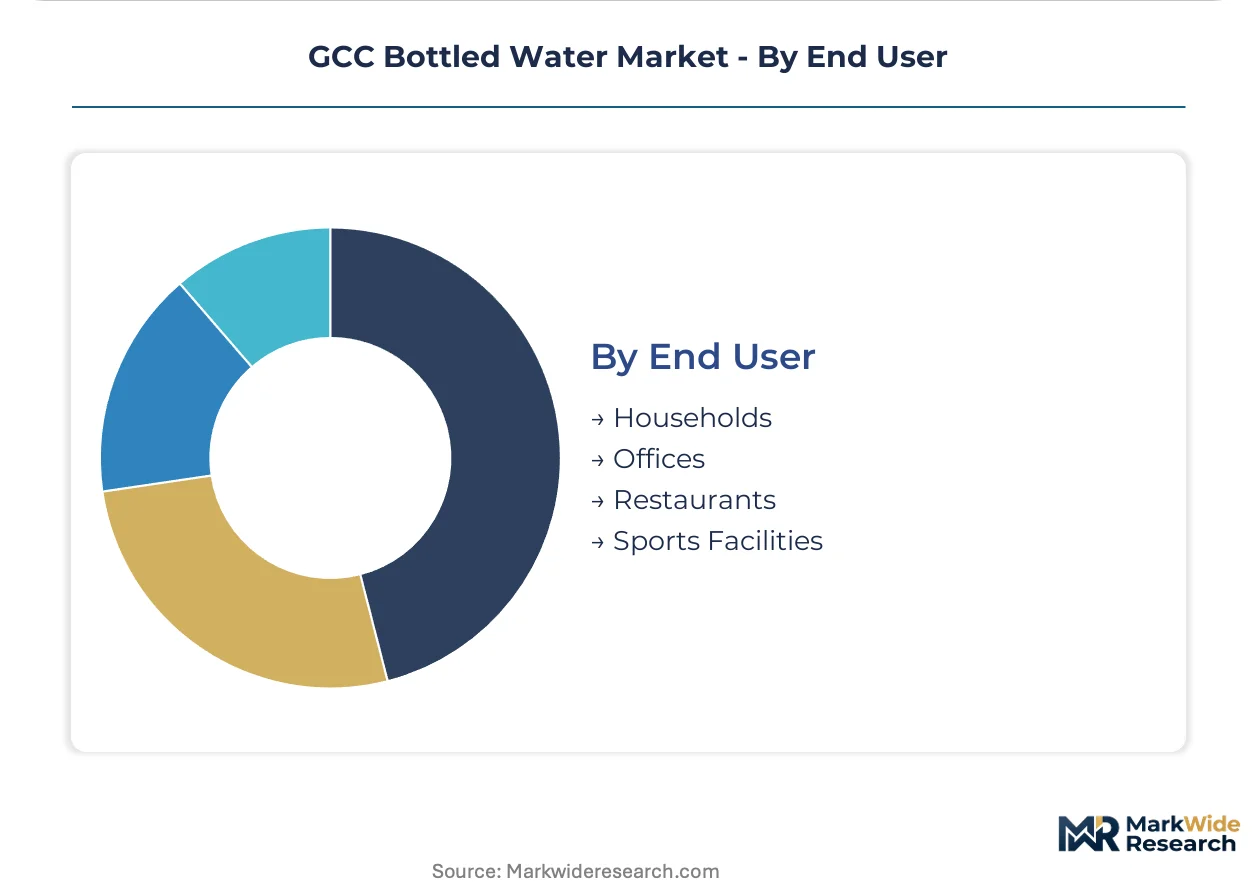
End User:
Consumption context shapes specification requirements, with institutional buyers demanding contractual reliability that household purchasers ignore.
- Households:Bulk purchasing in Saudi Arabia's Riyadh-Dammam corridor concentrates in retail formats, though subscription displacement is visible among convenience-prioritizing segments.
- Offices:Corporate hydration contracts in Dubai and Riyadh commercial districts bypass hypermarket retail with lower customer acquisition costs and recurring revenue structures.
- Restaurants:Foodservice procurement specifies glass presentation formats with mineral content disclosure for menu transparency.
- Sports Facilities:High-turnover hydration demands favor single-serve plastic formats with chilled dispensing infrastructure.
Households absorb the greatest volume share. Offices are climbing the fastest as direct-delivery platforms scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints across Gulf Cooperation Council states as compliance cost differentials between Saudi Arabia and the UAE influence bottler location decisions and cross-border supply routing.
Saudi Arabia
Luxury hospitality procurement and expatriate residential compound demand anchor volume growth in the Riyadh-Dammam corridor. The Saudi Food and Drug Authority enforces mineral content labeling mandates that elevate transparency requirements for retail shelf access. Eastern Province production clusters concentrate reverse osmosis capacity near Jubail desalination infrastructure to minimize feedwater logistics costs.
United Arab Emirates
Premium mineral water positioning and foodservice glass-format specifications drive margin expansion in Dubai and Abu Dhabi hospitality channels. The Emirates Authority for Standardization and Metrology tightened quality protocols in 2024 with expanded heavy metal testing requirements. Hajar Mountain aquifer sourcing in Ras Al Khaimah and Fujairah faces volume constraints during regional drought cycles that limit output expansion.
Kuwait
Health-conscious consumer migration from sugar-sweetened beverages creates flavored water white space for zero-calorie infused variants. The country's national standards body aligns with Gulf Standardization Organization harmonized specifications to reduce import friction. Urban retail corridors in Kuwait City concentrate convenience-driven single-serve purchasing patterns.
Qatar
Corporate direct-delivery contracts and recurring revenue subscription models penetrate Doha's commercial district office buildings. Microbiological testing capacity expansion lags behind Gulf Standardization Organization laboratory certification requirements. Lusail development zone hospitality pre-commitments are specifying premium still and sparkling variants for future hotel inventory.
Bahrain
Cross-border retail arbitrage from Saudi Arabia and UAE imports compresses domestic producer pricing power in Manama supermarket channels. The national food safety regulator maintains equivalence with GCC-wide bottled water specifications to facilitate regional trade. Muharraq and Riffa residential zones show early subscription-platform adoption among dual-income expatriate households.
GCC Bottled Water Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue flavored water and direct-delivery subscription channels to bypass hypermarket shelf space constraints. Market structure consolidates around three archetypes: multinational beverage conglomerates with deep distribution partnerships, regional dairy and food conglomerates leveraging existing cold-chain infrastructure, and specialized mineral water producers with captive aquifer access. Dominant competitive moves include portfolio diversification into zero-calorie infused variants and backward integration into desalination feedwater contracts.
Within the multinational tier, Danone S.A. and Nestlé S.A. represent European filtration expertise and volume-scale distribution archetypes respectively. Masafi LLC anchors Emirati provenance positioning through Hajar Mountain sourcing. Almarai Company exemplifies regional conglomerate diversification into packaged beverages through existing retail channel control. Mai Dubai LLC occupies a position within UAE domestic production capacity expansion.
| Leading Market Players |
|---|
| Danone S.A. |
| Almarai Company |
| Nestlé S.A. |
| Mai Dubai LLC |
| The Coca-Cola Company |
| PepsiCo Inc. |
| Masafi LLC |
| Crystal Mineral Water and Refreshments LLC |
| Agthia Group PJSC |
| Others |
Cost & Logistics Intelligence
Backward integration into desalination feedwater contracts anchors both supply security and margin defense for GCC bottlers facing municipal tariff volatility. This upstream control over primary inputs separates scaled operators from competitors exposed to spot-market feedwater cost swings across Saudi Arabia and the UAE.
Pricing Analysis
Retailer markup compression in Saudi Arabian hypermarkets is forcing producers toward direct-to-consumer subscription models with recurring revenue structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by packaging format and provenance verification, with glass-bottle hospitality specifications commanding the widest spreads. Pricing pressure stems from desalination cost volatility when natural gas prices spike, squeezing bottler margins against fixed municipal tariffs. Household bulk purchasers in residential compounds show highest price sensitivity, while luxury hotel procurement teams prioritize presentation over per-unit cost.
Supply Chain Analysis
Direct-to-office delivery channels bypass traditional wholesale layers, capturing corporate hydration contracts in Riyadh and Dubai commercial districts with lower customer acquisition costs. Geographic supply concentrates in Saudi Arabia, the UAE, and Kuwait, with production clustering near Jubail desalination infrastructure and Hajar Mountain aquifer zones. Raw material dependencies center on polyethylene terephthalate resin, glass container stock, and ozone-UV sterilization equipment. Single-source aquifer vulnerability in Ras Al Khaimah and Fujairah threatens volume continuity during regional drought cycles. Distribution runs through hybrid supermarket-retail and subscription-platform models with diverging margin economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC bottled water functions as a regulatory compounder where Emirates Authority for Standardization and Metrology quality protocol tightening is accelerating compliance capital expenditure and favoring scaled laboratory infrastructure.
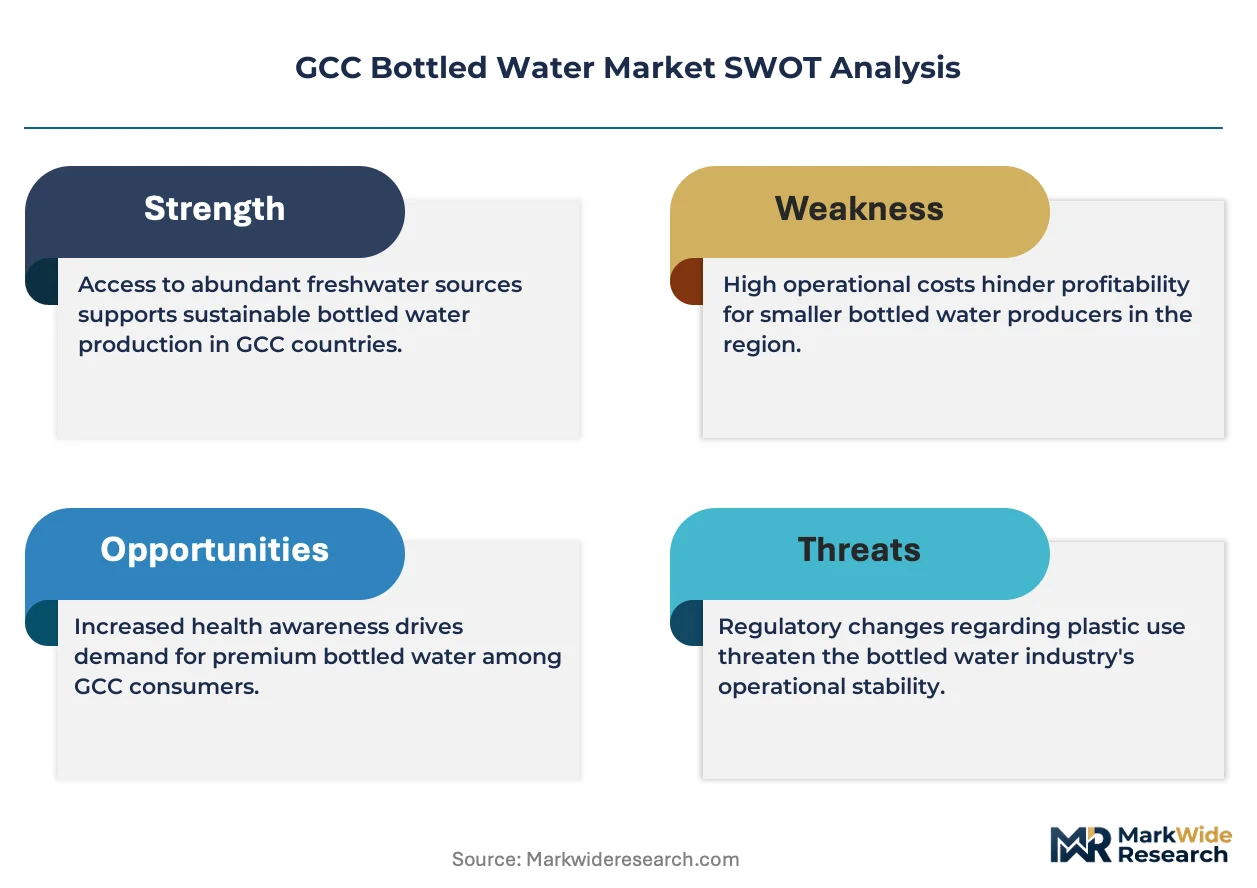
For Market Incumbents: Anticipate feedwater cost volatility by securing long-term desalination offtake agreements before municipal tariff reforms compress margins further. Prioritize laboratory certification expansion to meet Gulf Standardization Organization harmonized standards ahead of smaller competitors. Channel control through direct-delivery platform investment offers defensive positioning against e-commerce insurgents rewriting replenishment patterns. For New Entrants and Emerging Players: Corporate direct-delivery channels represent the most penetrable entry vector, with lower shelf-space barriers than Saudi Arabian hypermarket retail dominated by Nestlé and Danone. Flavored water white space in Kuwait and Bahrain offers margin expansion potential with zero-calorie infused variants positioned between still water and soft drinks. Subscription-platform go-to-market angles with scheduled replenishment algorithms reduce price sensitivity among dual-income expatriate households. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier regional producers with captive aquifer access because Hajar Mountain groundwater scarcity limits new entrant replication and creates defensive moats. Target acquisition archetypes include specialized mineral water producers with existing Emirates Authority for Standardization and Metrology laboratory infrastructure. Watch microbiological testing capacity expansion lag in Oman and Qatar as an inflection signal for compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Desalination Feedwater | Secures primary input cost stability against natural gas price volatility in Saudi Arabia. |
| Ozone-UV Hybrid Sterilization Deployment | Enables extended shelf life qualification for export to stricter import jurisdictions. |
| Direct-to-Office Delivery Platform Launch | Captures recurring corporate revenue with lower customer acquisition costs than retail. |
| Smart Bottle Cap Provenance Authentication | Compresses information advantage of legacy brands in UAE hospitality procurement. |
| Flavored Water Portfolio Extension | Captures health-conscious consumers shifting from sugar-sweetened beverages in Kuwait. |
Research Approach
Direct dialogue with production plant managers, hospitality procurement directors, retail category buyers, and regulatory compliance officers grounded qualitative findings in operational reality. Secondary validation drew from Saudi Food and Drug Authority filings, Emirates Authority for Standardization and Metrology protocols, Gulf Standardization Organization harmonized specifications, and customs trade records. Bottom-up volume triangulation against top-down market sizing anchored forecast reliability.
Segment-level projections across product type, packaging format, distribution channel, and end-user category fed into consolidated market estimates across the analysis window. CAGRs derived from historical trajectory analysis adjusted for regulatory milestone impacts and infrastructure buildout timelines. Forecast inputs incorporated desalination capacity expansion schedules, hospitality pipeline commitments, and municipal water tariff reform discussions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to circular economy policy implementation and plastic packaging taxation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Africa Dairy Based Beverages Market
Beverages
Low Fat Drinks Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Superfood Infused Beverages Market
Beverages
Commercial Drink Mixers Market
Beverages
Growlers Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Extra Virgin Olive Oil Market
Beverages
Crystal Boba Market
Beverages
Premium Bottled Water Market
Beverages
Nitro-Infused Cola Market
Beverages
Cold Pressed Juice Market
Beverages
Fusion Beverages Market
Beverages
Soft Serve Premix Market
Beverages
South America Bottled Water Market