
 Semillon Market | 2026-2036
Semillon Market Size, Share, and Industry Trends Forecast 2026-2036
Semillon Market Analytics
Precision viticulture technology is fragmenting traditional vineyard management into sensor-driven, block-specific farming protocols. Tyrrells leverages generational Hunter Valley expertise to sustain its position in aged Semillon production. Château d'Yquem anchors the ultra-premium Sauternes segment through strict botrytis selection protocols. Pernod Ricard competes across multiple price tiers through diversified brand architecture spanning Old World and New World origins.
Semillon designates a white wine grape variety with naturally high acidity, thin skins, and susceptibility to botrytis cinerea infection that concentrates sugars for dessert wine production. The grape thrives in moderate maritime climates and undergoes both stainless steel fermentation for crisp dry styles and extended oak aging for complex cellar-worthy expressions. Dry Semillon leads volume throughput across export channels, while single varietal bottlings from established Old World appellations command the strongest margin pools. Fortified expressions retain niche positioning in traditional Commonwealth markets, and handpicked harvesting methods dominate premium tier supply chains where berry integrity determines final wine quality.
Australia's Grape and Wine Authority enforces regional labeling integrity standards that shape market access for export-bound Semillon. France's Institut National des Appellations d'Origine governs Sauternes classification hierarchies that directly influence pricing architecture and collector demand. Stakeholders must monitor evolving climate adaptation protocols and water allocation policies across both Australian and French production zones.
Market Dynamics
Precision viticulture is collapsing traditional vineyard block management into sensor-driven protocols, forcing producers to restructure labor allocation and capital deployment around real-time canopy and soil data streams.
Growth Catalysts
- Regional Labeling Integrity:Australia's Grape and Wine Authority enforces strict provenance standards that elevate Hunter Valley Semillon premiums in export markets. This regulatory scaffolding protects price architecture for authenticated bottlings.
- Botrytis Concentration Protocols:Selective harvesting methods for noble rot infection enable ultra-premium dessert wine production. Sauternes classification hierarchies channel collector demand toward verified appellation bottlings.
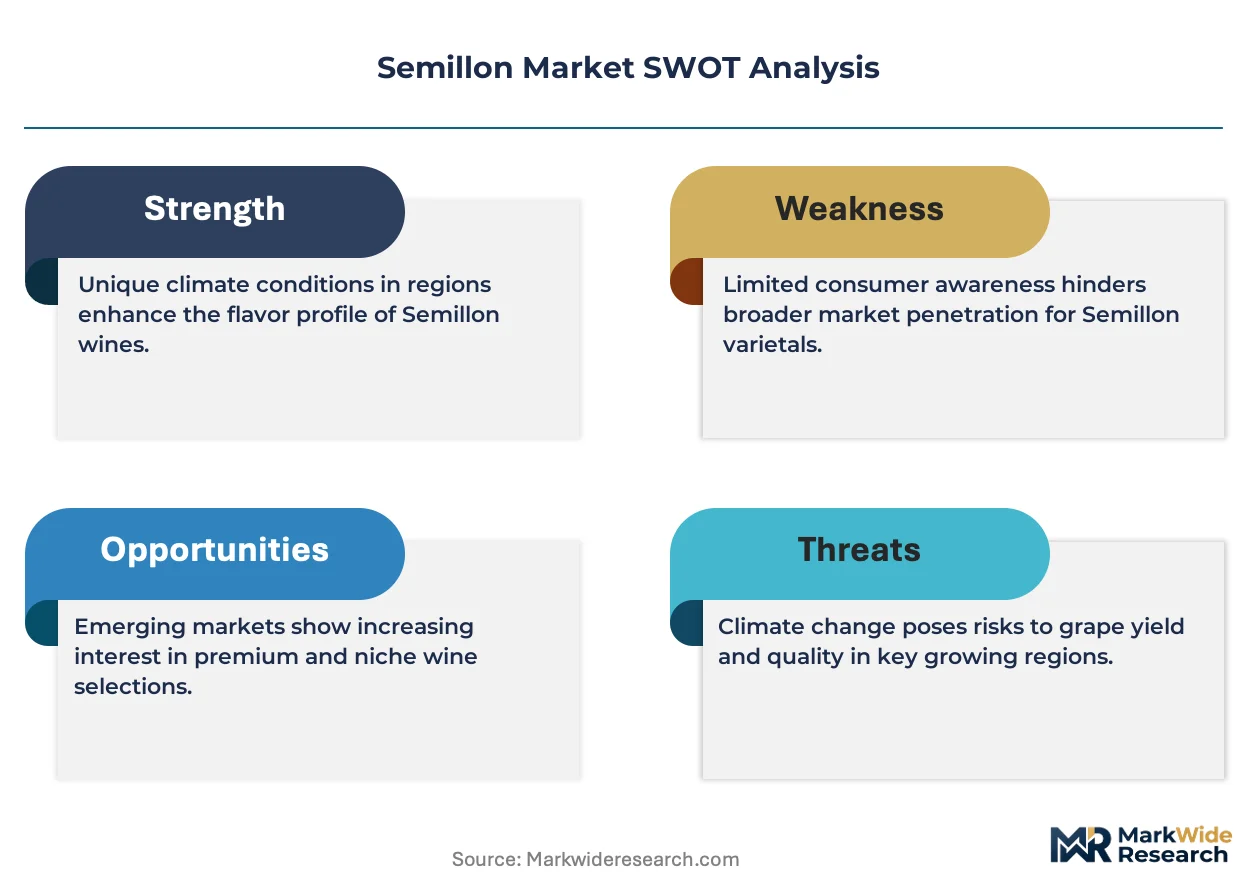
- Maritime Climate Suitability:Moderate coastal conditions in New South Wales and Bordeaux sustain naturally high acidity profiles. These terroir characteristics differentiate Semillon from competing white varieties in sommelier-driven channels.
Market Restraints
- Input Cost Volatility:Oak barrel prices fluctuate with French cooperage supply constraints. Extended aging programs for cellar-worthy styles face margin compression from wood procurement cycles.
- Supply Concentration Risk:Hunter Valley and Sauternes dominate premium tier output. Climate stress in these concentrated zones threatens vintage consistency and volume predictability.
- Substitution Threat:Sauvignon Blanc commands stronger retail recognition and faster inventory turns. Restaurant buyers frequently substitute New Zealand Sauvignon Blanc for by-the-glass Semillon placements.
Strategic Opportunities
- Climate Adaptation Incentives:Water allocation policy reforms in New South Wales reward drought-resistant rootstock adoption. Producers securing early-mover advantages in dry-farming protocols capture sustainable certification premiums.
- Direct-to-Consumer Channels:Winery cellar door visitation and subscription models bypass traditional wholesale markups. Hunter Valley estates with established tourism infrastructure expand margin capture through experiential retail.
- Convergence of Sensor Networks:Satellite imagery integration with ground-based soil moisture probes enables predictive irrigation scheduling. This technology pairing reduces water consumption while preserving berry integrity for premium tiers.
Industry Challenges
- Skilled Viticulture Labor Scarcity:Precision equipment operation and canopy management expertise concentrate among aging specialist cohorts. Succession gaps in Hunter Valley threaten block-specific farming protocol continuity.
- Extended Certification Timelines:Biodynamic and organic conversion periods lock vineyards into multi-year yield penalties. Cash flow strain during transition phases disadvantages smaller estates without balance sheet depth.
- Integration Complexity:Legacy winery management systems resist seamless data ingestion from IoT vineyard sensors. IT infrastructure upgrades demand capital allocation that competes with barrel inventory investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semillon Market |
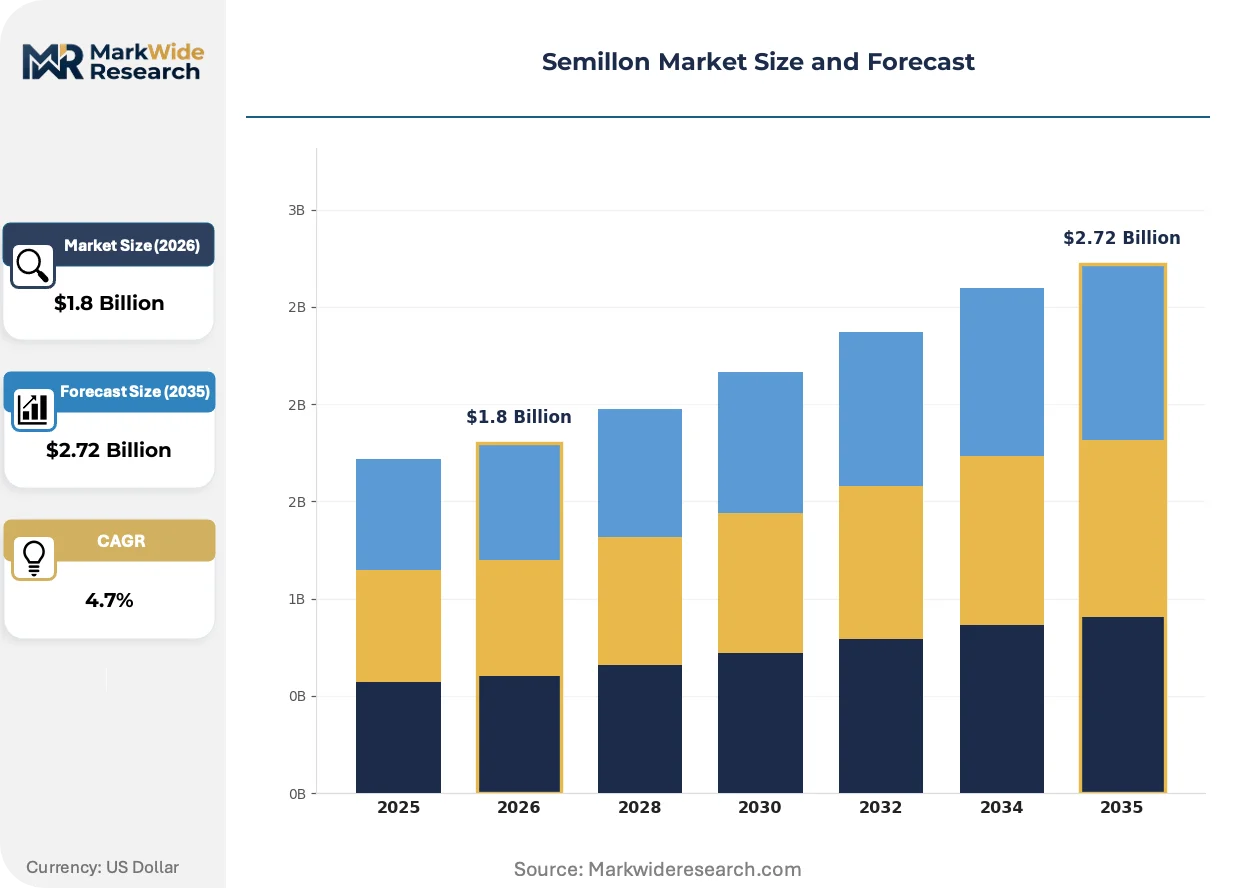
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry, Sweet, Fortified, Sparkling Harvesting Method: Handpicked, Mechanically Harvested, Night Harvest, Selective Picking Wine Style: White Wine, Dessert Wine, Blend, Single Varietal Distribution Channel: Retail, Online, Direct Sales, Export |
| Companies Covered | Brokenwood, Tyrrells, Keith Tulloch, McLeish Estate, Mount Pleasant, Pepper Tree, De Iuliis, Château d'Yquem, Pernod Ricard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semillon Market Evolving Landscape
Winemaking protocol divergence is accelerating between stainless steel freshness and oxidative complexity, with technology investments splitting along stylistic lines rather than converging on universal best practices.
Hyperspectral imaging is collapsing manual berry sorting into automated optical classification workflows. Large-format producers in South Australia deploy these systems for harvest intake triage. The technology compresses labor requirements while elevating consistency in botrytis-affected fruit selection for dessert wine programs.
France's Institut National des Appellations d'Origine tightened Sauternes yield restrictions and harvest timing windows. These constraints reduce eligible vineyard hectares for Grand Cru classification. Producers respond by intensifying vineyard management investment per hectare to maintain bottle output volumes.
Restaurant sommelier programs now favor single-vintage vertical tastings over horizontal regional comparisons. This behavioral pivot elevates producer reputation stickiness over appellation brand equity. The shift concentrates procurement authority with established Hunter Valley and Bordeaux estates that command vertical depth.
Semillon Market Segmentation
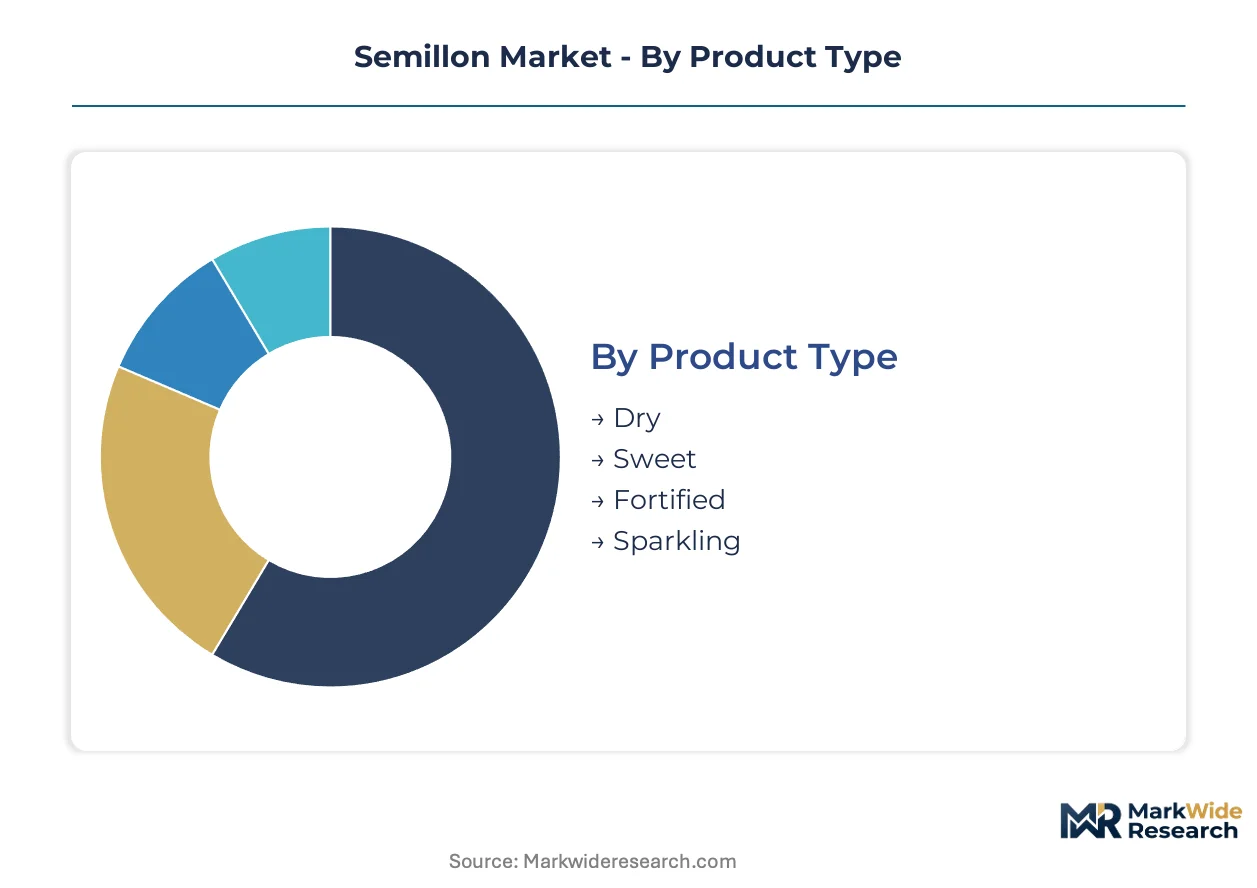
Semillon producers navigate divergent margin structures across stylistic categories, with dry expressions commanding volume throughput while fortified and botrytized styles capture premium pricing. Harvesting protocols and distribution channel selection directly determine final price positioning and market access, particularly for export-bound inventory from Australia's Hunter Valley and France's Sauternes appellations.
Product Type:
Cost tier differentiation separates mass-market volume drivers from cellar-worthy investment-grade bottlings, with production protocols and aging requirements creating distinct capital intensity profiles.
- Dry:Stainless steel fermentation preserves crisp acidity and fresh citrus aromatics. Restaurant by-the-glass programs in Sydney and Melbourne concentrate demand for young, unoaked expressions. Sauvignon Blanc substitution pressure constrains pricing power in retail channels.
- Sweet:Botrytis cinerea infection concentrates sugars through selective berry dehydration. Sauternes classification hierarchies channel collector demand toward verified appellation bottlings with extended cellar potential. Australia's late-harvest Hunter Valley expressions compete at accessible price points.
- Fortified:Spirit addition arrests fermentation, preserving residual sugar at elevated alcohol levels. Commonwealth markets retain niche positioning for aged solera-style releases.
- Sparkling:Traditional method secondary fermentation creates premium positioning. Limited commercial scale concentrates output among specialist producers.
Dry Semillon holds installed capacity. Sweet is rotating up the share rankings.
Harvesting Method:
Application-specific protocols align labor deployment with intended wine style, with premium tiers demanding berry integrity that mechanized systems cannot replicate.
- Handpicked:Manual selection preserves whole-berry condition for delicate skin contact management. Grand Cru Sauternes estates enforce multiple-pass harvesting to isolate optimal botrytis development. Labor scarcity in Bordeaux threatens protocol continuity for aging specialist cohorts.
- Selective Picking:Successive vineyard passes isolate berries at uniform ripeness or infection stages. Tyrrells employs this protocol for aged Hunter Valley Semillon with extended cellar trajectory. Triage labor costs concentrate in premium tier supply chains.
- Night Harvest:Cooler temperatures preserve aromatic compound stability during transport. Large-format South Australian producers deploy this for volume dry wine programs.
- Mechanically Harvested:Shaker systems compress labor requirements for early-drinking commercial styles. Fruit integrity limitations exclude this method from premium tier production.
Handpicked maintains vineyard coverage. Selective picking is climbing the fastest.
Wine Style:
Customer type preferences fragment between sommelier-driven single-varietal advocacy and blend formulations that moderate Semillon's textural weight for mainstream accessibility.
- Single Varietal:Unblended expression showcases terroir-specific aging trajectory. Vertical tasting programs at established Hunter Valley and Bordeaux estates concentrate procurement authority with producers commanding vintage depth. Restaurant sommelier education investments elevate producer reputation stickiness.
- Blend:Sauvignon Blanc or Chardonnay integration moderates acidity and broadens consumer acceptance. Western Australian producers deploy this strategy for faster inventory velocity in export markets.
- Dessert Wine:Noble rot concentration enables ultra-premium positioning. Yield restrictions under France's Institut National des Appellations d'Origine reduce eligible hectares for Grand Cru classification.
- White Wine:Generic dry classification captures commercial volume throughput. Retail shelf placement competes directly with varietally labeled alternatives.
Single varietal holds installed capacity. Blend is rotating up the share rankings.
Distribution Channel:
Geography-specific regulatory frameworks shape market access, with Australia's Grape and Wine Authority labeling integrity standards creating export authentication requirements that channel volume through verified wholesale relationships.
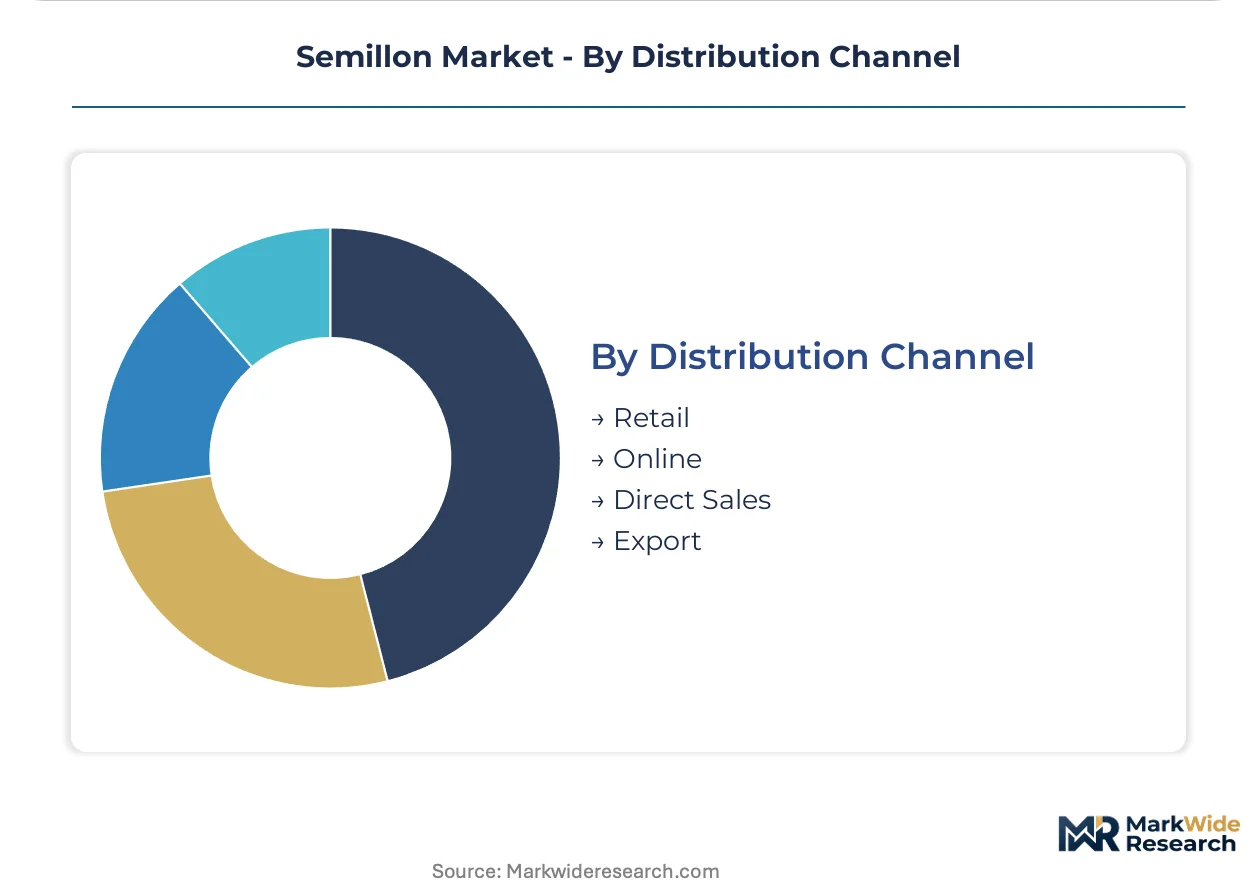
- Export:International shipment concentrates volume for premium Hunter Valley and Sauternes producers. Regional labeling integrity standards elevate authenticated bottling premiums in target markets. Container logistics and temperature-controlled transport add cost layers.
- Direct Sales:Cellar door visitation and subscription models bypass wholesale markups. Hunter Valley estates with established tourism infrastructure expand margin capture through experiential retail. China's cross-border e-commerce channels concentrate growth for authenticated luxury bottlings.
- Retail:Supermarket and independent bottle shop placement drives volume for commercial dry styles. New Zealand Sauvignon Blanc commands stronger recognition and faster turns in this channel.
- Online:Digital platforms enable direct producer-consumer relationships without intermediary markups. Logistics complexity limits penetration for temperature-sensitive inventory.
Export holds installed capacity. Direct sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Restaurant sommeliers and hotel beverage directors in Australia concentrate procurement authority for premium Semillon, while export channels channel authenticated Hunter Valley bottlings toward collectors in Asia and Europe.
Australia
New South Wales Hunter Valley estates supply aged Semillon to Sydney fine-dining establishments and Melbourne hotel channels. Australia's Grape and Wine Authority enforces strict regional labeling integrity standards that authenticate export-bound inventory. Tyrrells and Brokenwood anchor production clusters in Pokolbin and Broke Fordwich sub-regions.
France
Sauternes châteaux direct noble rot dessert wines toward auction houses and private collectors in London and Hong Kong. France's Institut National des Appellations d'Origine governs Grand Cru classification hierarchies that shape pricing architecture. Château d'Yquem exemplifies ultra-premium positioning within the Graves district of Bordeaux.
United States
California sommelier programs and New York City restaurant buyers source dry Semillon for by-the-glass programs and white wine pairings. The Alcohol and Tobacco Tax and Trade Bureau enforces appellation labeling requirements for imported bottlings. Napa Valley and Sonoma producers experiment with small-lot Semillon-Sauvignon Blanc blends.
United Kingdom
London merchant houses and Edinburgh independent retailers curate vertical collections of aged Hunter Valley releases. The Food Standards Agency implements wine labeling regulations that govern allergen declarations and alcohol content. Berry Bros. & Rudd and other historic merchants concentrate distribution authority in Mayfair and City of London precincts.
China
Shanghai and Beijing cross-border e-commerce platforms authenticate luxury Sauternes for emerging collector cohorts. The General Administration of Customs enforces import documentation and tariff classifications for wine shipments. Australian producers leverage direct-to-consumer digital channels to bypass traditional wholesale markups in tier-one cities.
Semillon Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Consolidation concentrates around established Hunter Valley estates with generational vineyard holdings and Sauternes châteaux with classification-protected terroir. Three archetypes dominate: heritage estates with vertical depth, diversified beverage conglomerates spanning multiple price tiers, and specialist producers focused on single-varietal expression. Competitive moves center on direct-to-cellar-door tourism expansion and precision viticulture technology licensing.
Among heritage Australian producers, Tyrrells and Brokenwood exemplify generational Hunter Valley expertise, while Château d'Yquem anchors the ultra-premium Sauternes segment through appellation-protected noble rot protocols. These three occupy positions that channel procurement authority toward authenticated regional bottlings rather than commodity blends.
| Leading Market Players |
|---|
| Brokenwood |
| Tyrrells |
| Keith Tulloch |
| McLeish Estate |
| Mount Pleasant |
| Pepper Tree |
| De Iuliis |
| Château d'Yquem |
| Pernod Ricard |
| Others |
Value Network & Pricing Analysis
French cooperage concentration around Limousin and Allier oak forests anchors margin capture for extended-aging Semillon tiers. Hunter Valley producers face barrel cost indexation that compresses cellar-worthy program returns when stave supply tightens.
Pricing Analysis
Cost-plus contracts with French cooperage houses index to stave lumber futures and Euro exchange movements. Three-tier pricing structure across premium, standard, and economy levels separates Grand Cru Sauternes from village-level Bordeaux and commercial South Australian volume. Pricing pressure stems from Sauvignon Blanc substitution in restaurant by-the-glass programs, eroding Semillon price premiums. Retail buyers exhibit highest price sensitivity, while auction house collectors absorb elevated premiums for vertical depth.
Supply Chain Analysis
Upstream feedstock flows from French oak forests, Australian steel tank fabrication, and Chilean alternative wood sources. Geographic supply concentration centers on France, Australia, and Argentina for premium fruit; China and Italy for glass packaging. Raw material dependencies include oak staves, stainless steel fermentation vessels, and natural cork. Single-source vulnerability runs through Grand Cru Sauternes estate concentration in a narrow Graves corridor. Distribution runs through bonded warehouse networks, direct cellar door visitation, and temperature-controlled container logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semillon market expansion reads as a cellar-door service-attach opportunity. Experiential tourism revenue layers at Hunter Valley estates expand faster than wholesale bottle margins, rewarding hospitality infrastructure investment.
For Market Incumbents: Harden regional labeling integrity through Australia's Grape and Wine Authority certification depth. Lock in generational vineyard lease structures before climate adaptation policy reforms alter water allocation. Vertical integration into cooperage partnerships secures barrel supply against French stave export restrictions.
For New Entrants and Emerging Players: Pursue direct-to-consumer digital channels in China's cross-border e-commerce tier-one cities. White-space concentrates in subscription models bypassing traditional wholesale markups. Target sommelier education investments that elevate producer reputation stickiness over appellation brand equity.
For Investors and Strategic Acquirers: Capital is best deployed toward heritage estates with vertical depth and established tourism infrastructure. Long-term viability favors producers commanding generational vineyard holdings in Hunter Valley sub-regions. Watch climate adaptation protocol adoption rates as inflection indicators for sustainable certification premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Cellar Door Tourism Expansion | Hunter Valley estates capture margin through experiential retail bypassing wholesale markups. |
| Precision Viticulture Licensing | Sensor network technology providers monetize vineyard management protocol subscriptions. |
| Direct-to-Consumer Digital Launch | Cross-border e-commerce platforms authenticate luxury Sauternes for emerging Asian collectors. |
| Cooperage Partnership Integration | French oak stave supply agreements secure barrel inventory for extended-aging programs. |
| Sommelier Education Investment | Vertical tasting program sponsorships concentrate procurement authority with established estates. |
Research Methodology
Cross-validation between vineyard manager interviews and export shipment records anchors the qualitative findings. Primary fieldwork engaged winemakers, sommelier program directors, Australia's Grape and Wine Authority officials, and Bordeaux négociant principals. Secondary sources encompassed Institut National des Appellations d'Origine classification databases, customs export declarations, and regional tourism authority visitation statistics. Bottom-up volume modeling triangulated against top-down value estimates across production tiers.
Calibration against historical vintage variation and climate stress events shaped the projection framework. Segmentation dimensions encompassed wine style, harvesting protocol, distribution channel, and regional appellation cluster. CAGRs derived from vintage volume trends, price index movements, and channel shift velocities. Forecast inputs incorporated water allocation policy scenarios and botrytis infection frequency patterns.
Sensitivities concentrate around climate adaptation timeline acceleration and substitute variety substitution rates. Forecasts reflect documented assumptions regarding regional labeling integrity enforcement continuity. Cross-checking against Australia's Grape and Wine Authority export authentication data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Crystal Boba Market
Beverages
Blenders Market
Beverages
GCC Coconut Water Market
Beverages
Aloe Vera Drinks Market
Beverages
Probiotic Beverage Market
Beverages
Breakfast Drink Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
China Soy Beverages Market
Beverages
Dairy Based Beverages Market
Beverages
Cactus Water Market
Beverages
Asia Pacific Fermented Drinks Market
Beverages
Extra Virgin Olive Oil Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
United States and Australia Coconut Water Market
Beverages
United States Sports and Energy Drinks Market
Beverages
Juice Concentrates Market