
 Soluble Milk Protein Market | 2026-2036
Soluble Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Soluble Milk Protein Market Analytics
Multi-source procurement of whey and casein fractions is shifting toward vertically integrated dairy cooperatives with captive processing capacity. Fonterra Co-operative Group anchors Oceania supply through its farmer-owned collection network. Arla Foods Ingredients leverages membrane filtration investments to sustain European whey protein isolate output. Glanbia plc competes on sports nutrition ingredient specialization across North American and European formulation houses.
Soluble milk protein encompasses water-dispersible dairy fractions—whey protein concentrates at 34-80% protein, isolates exceeding 90% protein, and casein micelles—recovered through ultrafiltration, microfiltration, and ion exchange chromatography before spray drying into functional powders for emulsification, gelation, and nutritional fortification. Whey protein dominates volume due to its superior leucine bioavailability and rapid absorption kinetics favored by sports nutrition formulators. Casein protein occupies slower-digesting overnight recovery applications where sustained amino acid release commands formulation premiums. Milk protein concentrate bridges cost-performance requirements in bakery and processed dairy where intermediate functionality suffices.
EFSA governs nutrition and health claims on protein content across EU member states, while FDA oversees GRAS self-affirmation and food additive petitions for novel dairy protein isolates in the United States. China's SAMR enforces GB standards for imported dairy protein labeling and contaminants, creating compliance thresholds for cross-border suppliers. Stakeholders must monitor evolving front-of-pack protein claim restrictions and carbon footprint disclosure requirements that will reshape sourcing geography and processing technology selection.
Market Dynamics
Membrane filtration technology maturation is compressing processing costs while EFSA protein claim verification tightens label compliance burdens, creating divergent pressure on formulation economics and supplier qualification timelines.
Growth Catalysts
- Sports nutrition RTD expansion:Ready-to-drink protein beverages are capturing shelf space in convenience retail, pulling whey isolate demand from powder formats into liquid stabilization applications requiring superior solubility.
- EU Green Deal carbon accounting:Processors investing in renewable energy-powered spray drying facilities gain preferential access to sustainability-certified procurement contracts from Nordic functional food manufacturers.
- German functional food clustering:Concentrated R&D infrastructure around Munich and Hamburg accelerates co-development partnerships between protein suppliers and finished goods innovators.
Market Restraints
- Skim milk powder price volatility:Whey protein concentrate production remains tethered to cheese manufacturing cycles, exposing margin compression when dairy commodity markets spike.
- Oceania supply concentration:Fonterra's farmer-owned collection network controls critical volume of cross-flow membrane capacity, creating single-source vulnerability for European importers.
- Casein micelle functional limits:Slow-digesting protein applications face formulation constraints in high-acid environments where micellar integrity degrades.
Strategic Opportunities
- Chinese SAMR import pathway:GB standards compliance for dairy protein labeling creates first-mover advantage for processors establishing dedicated China-bound production lines with Mandarin documentation capabilities.
- Cellular agriculture hybrid proteins:Precision fermentation-derived dairy proteins are expanding into blended formulations where conventional and novel sources combine for cost-optimized nutrition profiles.
- Direct-to-brand e-procurement platforms:B2B ingredient marketplaces are disintermediating traditional distributor networks, enabling mid-size sports nutrition brands to source isolates with transparent certificate-of-analysis documentation.
Industry Challenges
- Membrane technician scarcity:Ultrafiltration and microfiltration operation requires specialized dairy engineering expertise that outpaces vocational training program output in key processing regions.
- GRAS petition timelines:FDA novel protein isolate approvals stretch 18-24 months, delaying market entry for innovative fractionation outputs and freezing R&D amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soluble Milk Protein Market |
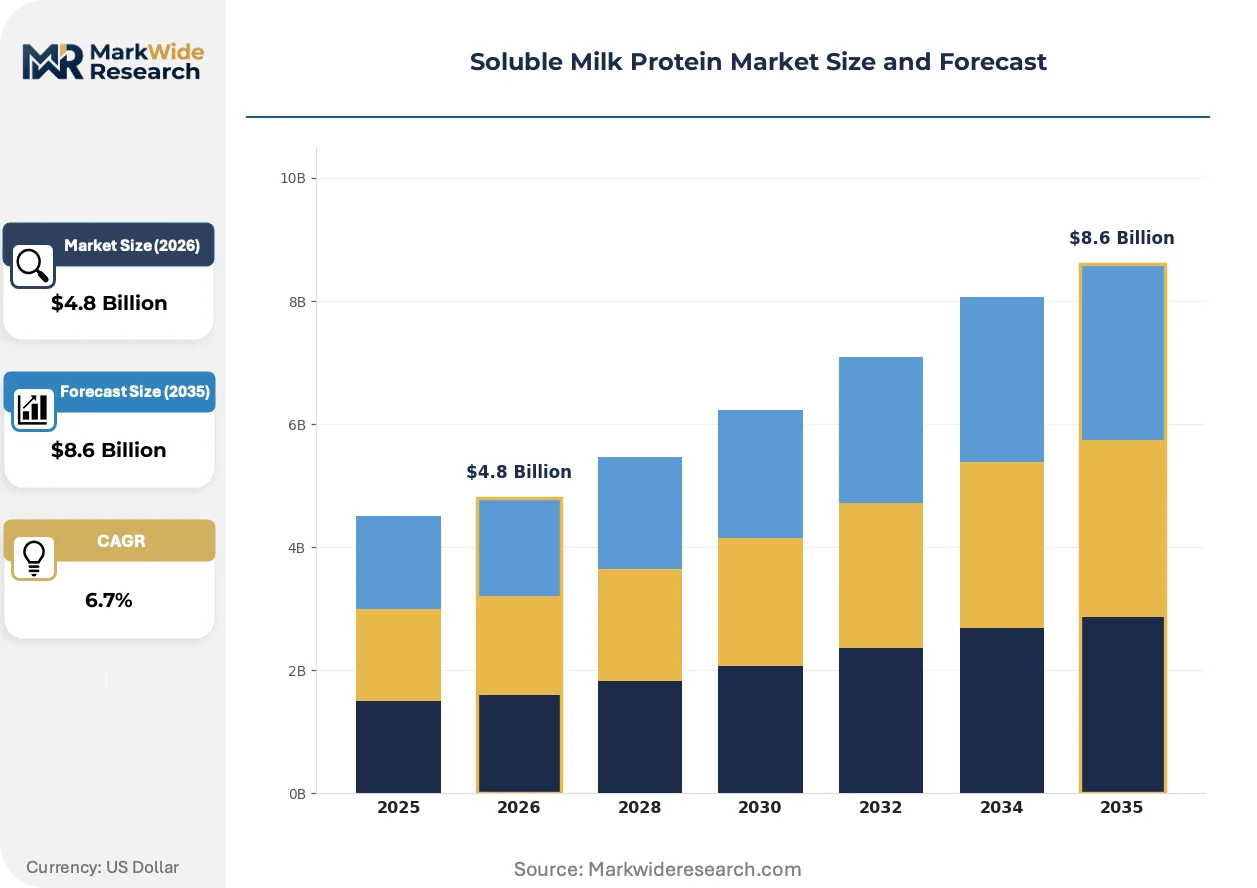
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Milk Protein Concentrate, Milk Protein Isolate Application: Nutritional Supplements, Dairy Products, Bakery Products, Sports Nutrition Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales End User: Hospitality, Fitness Centers, Food Manufacturers, Nutraceuticals |
| Companies Covered | Davisco Foods International, Arla Foods Ingredients, Fonterra Co-operative Group, Glanbia plc, Milk Specialty, Wheyco GmbH, FrieslandCampina Ingredients, Lactalis Ingredients, Dairy Farmers of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soluble Milk Protein Market Evolving Landscape
Processing technology convergence and verification protocol digitization are restructuring how soluble milk proteins move from dairy stream to finished formulation, with implications for cost curves and competitive moats.
Cross-flow ceramic membrane systems are expanding into whey protein fractionation, replacing polymeric spiral-wound elements with superior flux rates and chemical tolerance. Mid-size European processors are retrofitting existing plants with this hardware to capture isolate purity premiums without greenfield capital deployment. The technology is expanding into applications previously reserved for ion exchange chromatography, compressing the cost gap between WPC-80 and WPI-90 grades.
EFSA front-of-pack nutrition labeling mandates are tightening protein content declaration tolerances, forcing reformulation of legacy products that relied on nitrogen-based measurement methods now deemed insufficient. Finished goods manufacturers are responding by demanding third-party amino acid profiling from suppliers, shifting contract specifications toward HPLC-verified leucine content minimums. German and Dutch formulation houses are most affected due to their early adoption of Nutri-Score display requirements.
Long-term supply agreements are displacing spot market purchasing among North American sports nutrition brands seeking price predictability amid dairy commodity swings. Three-year indexed contracts with volume floors and ceiling provisions are replacing quarterly tenders, transferring inventory risk upstream to processors. This pattern is most visible in contract manufacturing organizations serving direct-to-consumer protein brands in Utah and Texas.
Soluble Milk Protein Market Segmentation
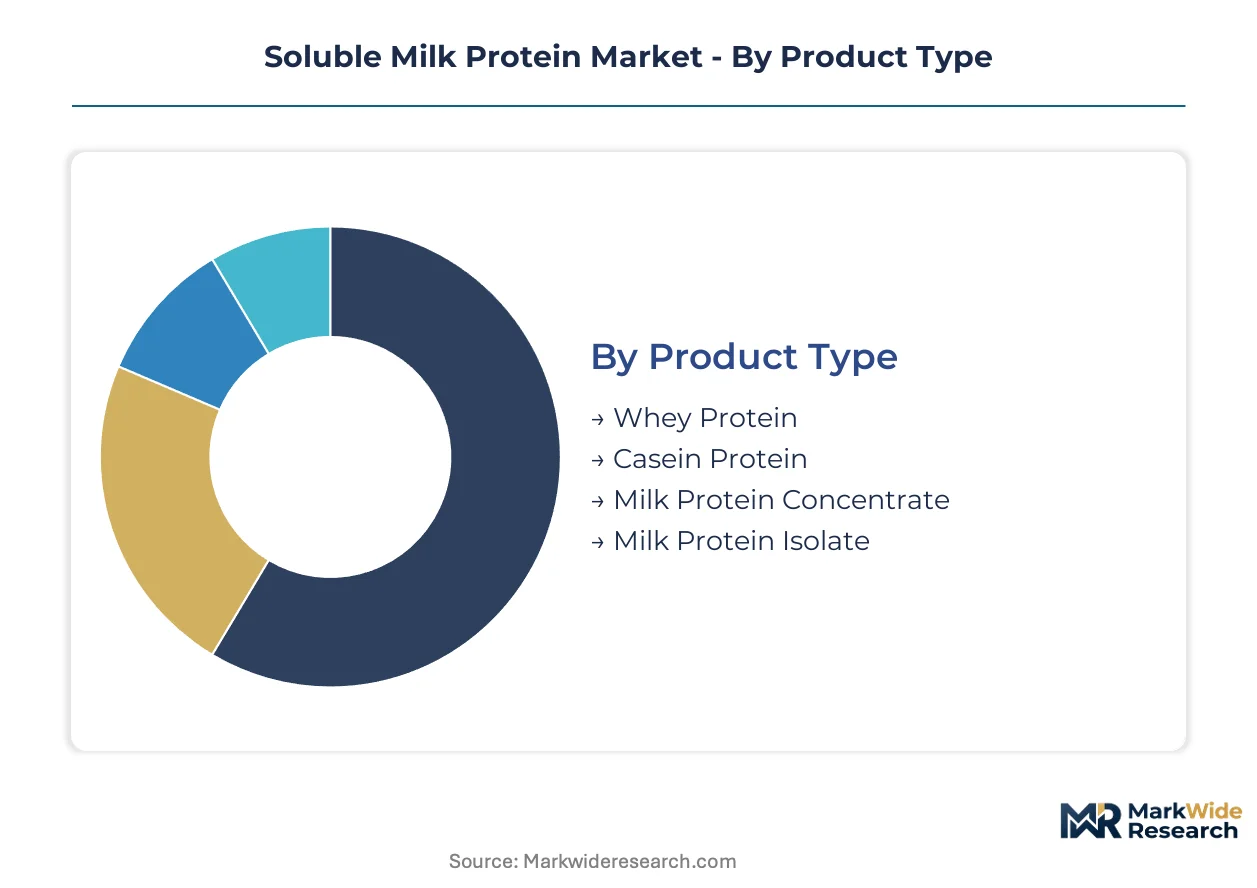
Soluble milk protein procurement patterns diverge sharply across product specifications, with membrane filtration purity grades determining end-use eligibility and pricing power. Application-driven formulation requirements further stratify demand, as sports nutrition brands prioritize leucine bioavailability while bakery manufacturers optimize for emulsification thresholds.
Product Type:
Membrane filtration technology defines the competitive hierarchy, with cross-flow ceramic systems compressing cost curves between concentration grades.
- Whey Protein:Rapidly absorbed fractions with superior leucine density dominate sports nutrition RTD formulations. Demand concentrates in North American contract manufacturing clusters serving direct-to-consumer brands, where EFSA protein claim verification is tightening amino acid profiling requirements.
- Casein Protein:Micellar structures enable sustained amino acid release for overnight recovery applications. German functional food manufacturers command formulation premiums, though high-acid environments degrade micellar integrity and constrain usage.
- Milk Protein Concentrate:Intermediate functionality bridges cost-performance requirements in processed dairy and bakery segments.
- Milk Protein Isolate:Exceeding 90% protein purity, this grade captures premium positioning where label clarity and minimal lactose drive selection.
Whey protein leads on scale; milk protein isolate leads on momentum.
Application:
End-use specifications reshape supplier qualification timelines, with regulatory burden intensity varying across finished goods categories.
- Sports Nutrition:Ready-to-drink protein beverages are displacing powder formats in convenience retail, pulling demand toward liquid-stabilized isolates. German and Dutch formulation houses face accelerated Nutri-Score compliance deadlines.
- Nutritional Supplements:Capsule and tablet applications require spray-dried powders with precise particle size distribution for compression performance.
- Dairy Products:Processed cheese and yogurt fortification utilizes milk protein concentrate for cost-optimized protein enhancement.
- Bakery Products:Emulsification and water-binding properties drive selection, with intermediate WPC grades dominating volume.
Sports nutrition leads on scale; nutritional supplements lead on momentum.
Distribution Channel:
Channel selection reflects buyer scale and certificate-of-analysis documentation requirements, with transparency demands reshaping procurement pathways.
- Direct Sales:Long-term indexed contracts with volume floors are displacing spot purchasing among North American sports nutrition brands seeking dairy commodity price predictability.
- Online Retail:B2B ingredient marketplaces are disintermediating traditional distributor networks for mid-size brands requiring transparent documentation.
- Supermarkets:Mass-market protein powder retail depends on established CPG distributor relationships with consolidated logistics.
- Health Stores:Specialty retail channels prioritize premium isolate grades with front-of-pack sustainability certifications.
Direct sales leads on scale; online retail leads on momentum.
End User:
Customer type determines technical service intensity and co-development partnership potential, with R&D infrastructure proximity influencing supplier selection.
- Food Manufacturers:German functional food clusters around Munich and Hamburg accelerate co-development partnerships between protein suppliers and finished goods innovators.
- Nutraceuticals:GRAS petition timelines stretch market entry for novel fractionation outputs, freezing R&D amortization schedules.
- Fitness Centers:Private-label protein powder programs demand bulk WPC grades with flexible packaging configurations.
- Hospitality:Foodservice applications prioritize cost-optimized concentrates for beverage and dessert fortification.
Food manufacturers lead on scale; nutraceuticals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping soluble milk protein manufacturing geography, with processors migrating toward jurisdictions offering streamlined EFSA-equivalent compliance pathways and renewable energy subsidies that offset spray-drying costs. Production investments concentrate where membrane filtration expertise intersects with sustainability-certified procurement demand.
Germany
Sports nutrition RTD brands in Munich and Hamburg drive whey isolate demand for liquid-stabilized formulations. EFSA front-of-pack Nutri-Score mandates tighten amino acid profiling requirements for protein content claims. The Bavarian functional food cluster accelerates co-development partnerships between membrane filtration specialists and finished goods innovators.
United States
Direct-to-consumer protein brands in Utah and Texas contract for long-term indexed supply agreements with volume floors. FDA GRAS self-affirmation pathways govern novel dairy protein isolate introductions, though petition timelines stretch market entry. North American contract manufacturing organizations consolidate procurement through three-year contracts replacing quarterly spot tenders.
China
GB standards enforcement by SAMR creates compliance thresholds for imported dairy protein labeling and contaminant limits. Yangtze River Delta processors invest in dedicated China-bound production lines with Mandarin documentation capabilities. Precision fermentation-derived dairy proteins enter blended formulations combining conventional and novel sources for cost-optimized nutrition profiles.
New Zealand
Farmer-owned dairy cooperatives anchor Oceania supply through captive cross-flow membrane processing capacity. Fonterra's collection network controls critical whey protein concentrate volumes, creating single-source exposure for European importers. Renewable energy-powered spray drying facilities gain preferential access to sustainability-certified procurement contracts from Nordic manufacturers.
Netherlands
Membrane filtration technology providers in the Randstad region retrofit existing plants with ceramic systems capturing isolate purity premiums. Dutch formulation houses face accelerated EFSA protein claim verification deadlines affecting legacy nitrogen-based measurement methods. Brabant-based processors leverage superior flux rates to compress cost gaps between WPC-80 and WPI-90 grades.
Soluble Milk Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and hybrid protein formulations. The supplier base consolidates around vertically integrated dairy cooperatives with captive processing capacity, while mid-size European processors compete through membrane technology retrofit investments. Three archetypes dominate: farmer-owned cooperatives with collection network control, ingredient specialists with sports nutrition formulation partnerships, and diversified dairy conglomerates with fractionation diversification. Competitive moves center on renewable energy-powered facility investments and long-term procurement contracts with indexed pricing mechanisms.
Among farmer-owned cooperatives, Fonterra Co-operative Group and Dairy Farmers of America exemplify the collection-network archetype, anchoring supply security through upstream farmer relationships. Arla Foods Ingredients and Glanbia plc occupy positions within the ingredient-specialist tier, with the former representing European membrane filtration investment patterns and the latter exemplifying North American sports nutrition formulation partnerships. FrieslandCampina Ingredients and Lactalis Ingredients sit within diversified dairy conglomerates pursuing fractionation portfolio breadth.
| Leading Market Players |
|---|
| Davisco Foods International |
| Arla Foods Ingredients |
| Fonterra Co-operative Group |
| Glanbia plc |
| Milk Specialty |
| Wheyco GmbH |
| FrieslandCampina Ingredients |
| Lactalis Ingredients |
| Dairy Farmers of America |
| Others |
Value Network & Pricing Analysis
Skim milk powder futures on the Global Dairy Trade index cascade through whey protein concentrate production economics, compressing margins for European processors when dairy commodity markets spike while rewarding vertically integrated cooperatives with captive cheese manufacturing streams.
Pricing Analysis
Input-cost pass-through from dairy commodity benchmarks governs whey protein concentrate pricing, with Fonterra's farmer-owned collection network leveraging backward integration into milk supply to buffer margin volatility. Three-tier pricing structure across premium isolate, standard concentrate, and economy-grade fractions reflects membrane filtration purity grades and EFSA amino acid profiling certification levels. Pricing pressure stems from skim milk powder price volatility tethered to cheese manufacturing cycles. Sports nutrition contract manufacturers in North America exhibit highest price sensitivity due to indexed long-term procurement agreements, while German functional food clusters absorb premiums for Nutri-Score-compliant isolates.
Supply Chain Analysis
Direct-to-brand e-procurement channels handle mid-size sports nutrition buyer demand, displacing traditional distributor networks for transparent certificate-of-analysis documentation. Supply concentrates in New Zealand through Fonterra's cross-flow membrane capacity, Germany via Arla Foods Ingredients' filtration investments, and the Netherlands through ceramic system retrofits. Raw material flows draw from fluid milk collection networks, cheese whey streams, and specialized membrane filtration chemicals. Single-source vulnerability pervades European importers dependent on Oceania whey protein concentrate volumes. Distribution runs through long-term indexed contracts with volume floors among North American direct-to-consumer brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soluble milk protein market compounds steadily as sports nutrition RTD expansion pulls demand from powder formats into liquid-stabilized isolates requiring superior solubility performance.
For Market Incumbents: Acquire ceramic membrane filtration assets in the Randstad region to capture isolate purity premiums without greenfield capital deployment. Consolidate procurement relationships with Nordic functional food manufacturers seeking sustainability-certified spray-drying capacity. Precision fermentation-derived dairy proteins threaten conventional fractionation economics; preemptive backward integration into renewable energy-powered facilities defends margin position against carbon-accounting procurement shifts. For New Entrants and Emerging Players: Capture the Chinese SAMR import pathway by establishing dedicated production lines with Mandarin documentation capabilities ahead of GB standards enforcement tightening. Target precision fermentation hybrid protein formulations where conventional and novel sources combine for cost-optimized nutrition profiles. Partner with Yangtze River Delta processors for blended ingredient co-development rather than competing head-to-head with established membrane filtration specialists. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-size European processors retrofitting existing plants with cross-flow ceramic systems to bridge WPC-80 and WPI-90 cost gaps. Five-to-ten-year viability favors ingredient specialists with sports nutrition formulation partnerships over diversified dairy conglomerates lacking fractionation focus. Monitor EFSA front-of-pack protein claim verification deadlines as inflection indicator for amino acid profiling equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Retrofit | Ceramic system upgrades at Dutch plants compress cost curves between whey protein grades. |
| Renewable Energy Transition | Spray-drying facilities powered by New Zealand geothermal gain Nordic sustainability procurement preference. |
| Long-term Supply Agreement | Three-year indexed contracts with volume floors transfer inventory risk to Utah contract manufacturers. |
| Regulatory Compliance Investment | HPLC-verified leucine profiling capabilities secure German Nutri-Score formulation partnerships. |
| Precision Fermentation Partnership | Hybrid protein co-development with Chinese processors blends conventional and novel nutrition sources. |
Research Methodology
Coverage spans Germany, the United States, China, New Zealand, and the Netherlands, with primary inputs from each market triangulated against secondary validation. Interviews with membrane filtration plant managers, sports nutrition procurement leads at contract manufacturing organizations, dairy cooperative technical directors, and EFSA regulatory affairs specialists informed supply-side and demand-side dynamics. Secondary sources include Global Dairy Trade auction data, EFSA nutrition claim guidance documents, SAMR GB standards filings, and SEC 10-K disclosures from listed ingredient specialists. Bottom-up volume modeling from membrane capacity installations reconciles with top-down value estimates from dairy commodity price benchmarks.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon, with CAGRs derived from segment-level demand elasticity and supply capacity expansion schedules. Segmentation dimensions span membrane filtration purity grade, end-use application, buyer scale archetype, and regional regulatory cluster. Forecast inputs incorporate sports nutrition RTD shelf-space expansion rates, EFSA front-of-pack labeling adoption curves, and renewable energy subsidy trajectories affecting spray-drying cost structures.
Skim milk powder price volatility, EFSA protein claim verification timeline extensions, and precision fermentation technology cost curves are the dominant revision risks to base-case assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Reconstituted Milk Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
North America Fluid Milk Market
Dairy Products
Indonesia Whey Protein Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Cheddar Cheese Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Cheese Shreds Market
Dairy Products
Greek Yogurt Market
Dairy Products
Milk Mineral Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Dairy Products Market