
 Dental Braces Market | 2026-2036
Dental Braces Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Braces Market Analysis
Software-enabled treatment planning subscriptions is broadening how orthodontic care gets monetized beyond hardware sales. Align Technology leverages its proprietary digital scanning ecosystem to lock in recurring revenue from orthodontists worldwide. Henry Schein anchors its position through dominant distribution control across North American dental practices. Ormco competes by specializing in advanced self-ligating bracket architectures that reduce chair time for clinicians.
Dental braces are mechanical devices constructed from stainless steel, titanium, ceramic, or medical-grade polymers that apply continuous controlled force to reposition teeth within the alveolar bone over months or years. Manufacturing involves precision injection molding of bracket bases, CNC machining of archwire alloys to exact torque specifications, and laser-welding of attachment points to withstand masticatory loads up to several hundred newtons. Traditional metal brackets occupy the largest volume pool due to cost accessibility and durability in complex malocclusion cases, while clear aligner systems represent the fastest-expanding margin segment as adult patients prioritize aesthetic discretion during treatment. Pediatric applications remain structurally mature with slower growth tied to established referral patterns from general dentists.
FDA regulates dental braces as Class II medical devices requiring 510(k) premarket notification for substantial equivalence, while the EU Medical Device Regulation mandates notified body conformity assessment and CE marking for market access across member states. ISO 13485 quality management standards govern manufacturing consistency for bracket and wire producers exporting to multiple jurisdictions. China's National Medical Products Administration enforces GB standards for biocompatibility testing of intraoral metallic materials. Stakeholders must monitor how regulatory divergence between FDA predicate device pathways and EUDAMED database requirements will reshape competitive entry costs for new aligner and bracket technologies.
Market Dynamics
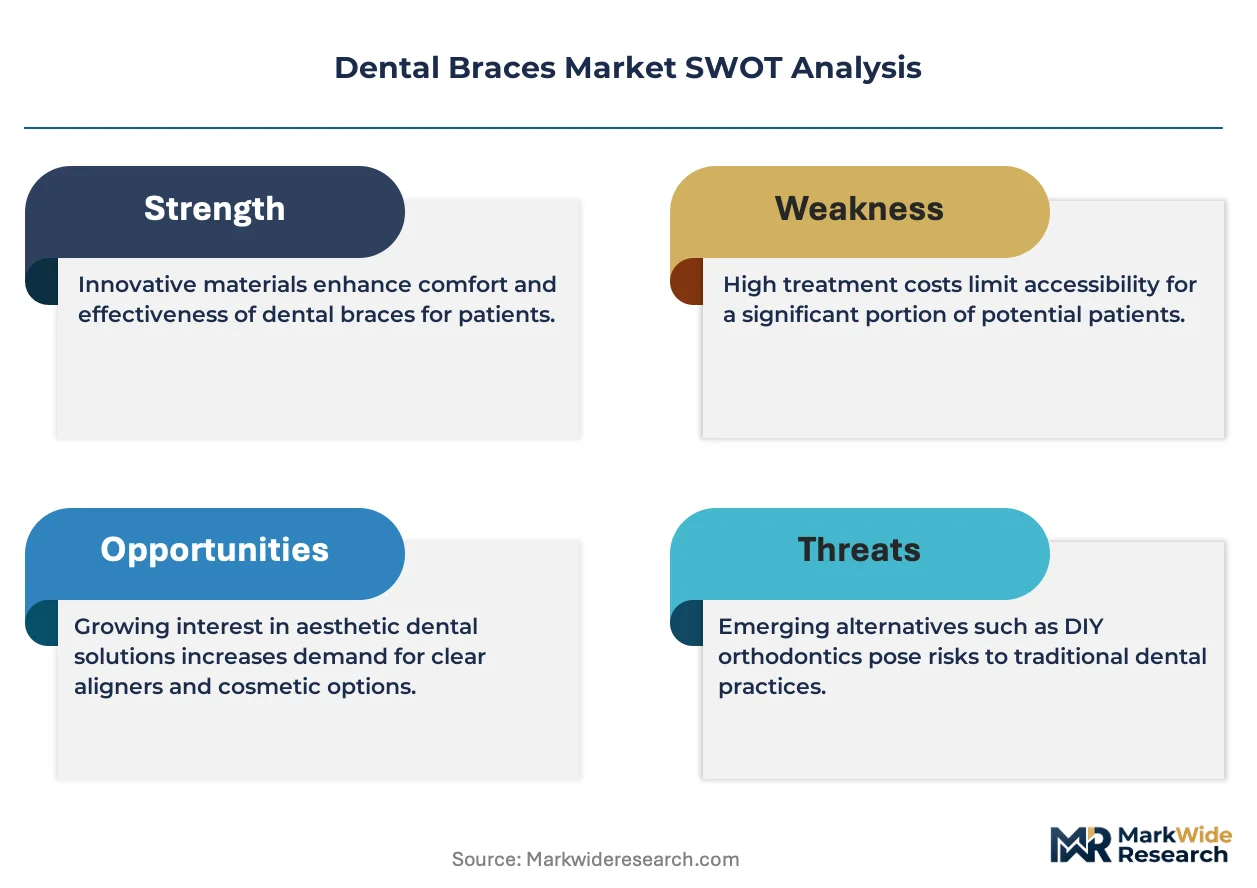
Clear aligner systems are compressing traditional bracket economics by shifting revenue from hardware sales toward recurring software-enabled treatment planning subscriptions that orthodontists pay monthly per active case.
Growth Catalysts
- Teenage Aesthetic Demand:Adolescents and young adults now prioritize discreet orthodontic correction, pulling volume toward transparent polymer aligners and ceramic brackets over stainless steel alternatives.
- FDA 510(k) Pathway:Streamlined premarket notification for substantial equivalence accelerates new aligner system commercialization in the United States, compressing competitive entry timelines.
- Domestic China Manufacturing:Local producers of ceramic and self-ligating systems achieve scale economies that reduce per-unit costs and expand accessibility across tier-two and tier-three cities.
Market Restraints
- Nickel-Titanium Archwire Volatility:Spot prices for nickel and titanium alloys fluctuate with battery-sector demand, squeezing margin predictability for bracket and wire manufacturers.
- EU MDR Compliance Burden:Notified body conformity assessment and EUDAMED database requirements extend certification timelines for bracket producers seeking CE marking across member states.
- Lingual Bracket Substitution:Completely hidden fixed appliances attached to tooth interiors capture patients who reject visible brackets but distrust removable aligner compliance.
Strategic Opportunities
- India Tier-Two Penetration:Orthodontic case rates in secondary Indian cities remain below one-tenth of metropolitan levels, creating whitespace for ceramic bracket distributors.
- AI-Driven Treatment Simulation:Machine learning convergence with intraoral scanning enables predictive outcome visualization that reduces case refinement rates and chair time.
- Remote Monitoring Platforms:Smartphone-based progress tracking creates new subscription revenue streams while reducing in-office appointment frequency for stable aligner patients.
Industry Challenges
- Digital Workflow Integration:Legacy practice management systems lack API compatibility with cloud-based aligner planning portals, forcing manual data re-entry and error risk.
- Orthodontist Training Bottleneck:Clear aligner case complexity exceeds general dentist comfort zones, limiting addressable prescriber base despite platform accessibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Braces Market |
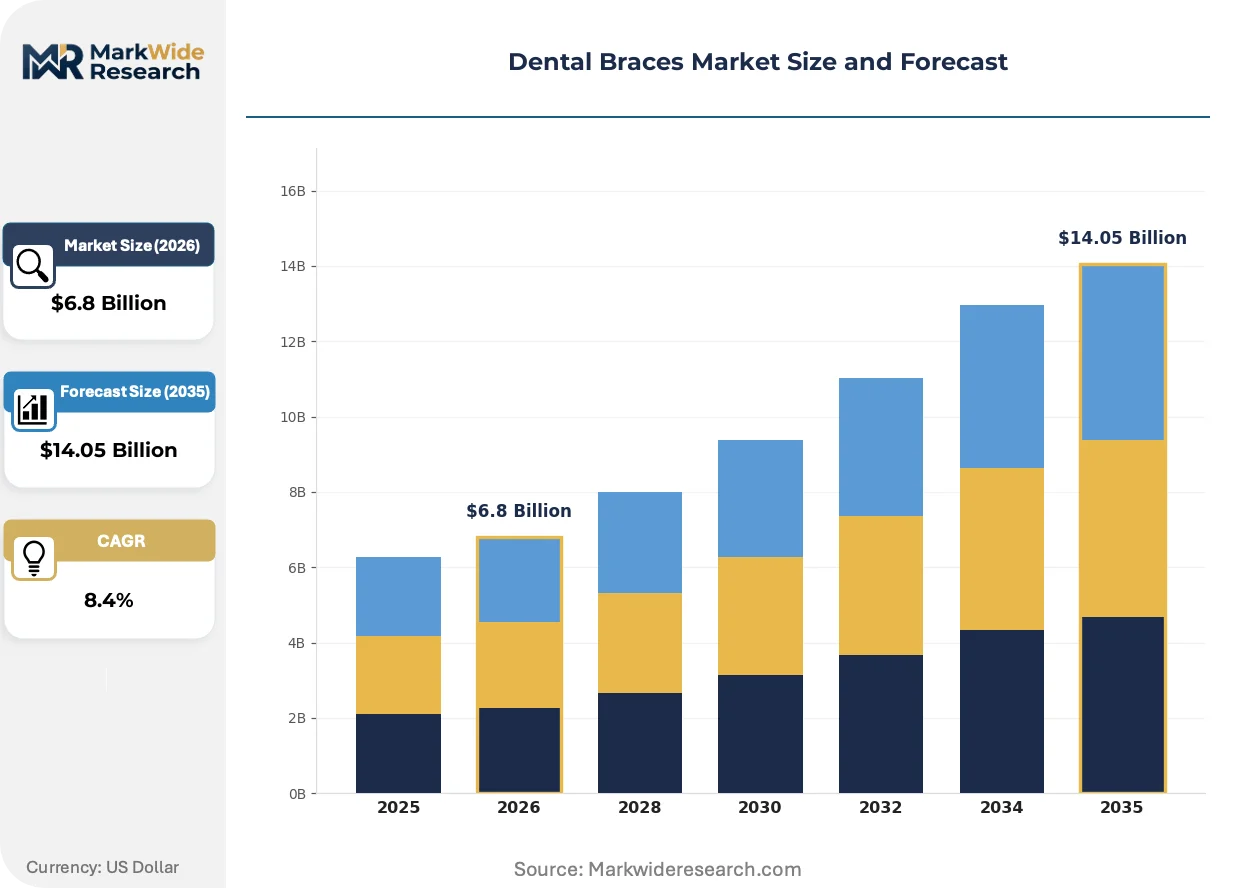
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Metal, Ceramic, Lingual, Invisalign Age Group: Pediatric, Adolescent, Adult, Senior Application: Orthodontic Treatment, Aesthetic Improvement, Dental Alignment, Preventive Care Distribution Channel: Dental Clinics, Hospitals, Online Stores, Orthodontic Practices |
| Companies Covered | American Orthodontics, Dentaurum, 3M Unitek, Align Technology, GC Orthodontics, Henry Schein, Ormco, FORESTADENT, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Braces Market Emerging Trajectories
Orthodontic care delivery is fragmenting across hardware, software, and service layers as digital platforms disintermediate traditional supply relationships between manufacturers and chairside providers.
Intraoral scanning hardware paired with cloud-based treatment planning algorithms is automating the diagnostic and staging workflows that previously required manual plaster model analysis and subjective orthodontist judgment. General dental practices without full-time orthodontic specialists now adopt these systems at accelerating rates, compressing the traditional referral pathway from dentist to orthodontist and capturing margin that specialists previously controlled.
China's NMPA enforcement of updated GB standards for biocompatibility testing of intraoral metallic materials is elevating documentation requirements for imported bracket systems. Domestic Chinese manufacturers gain competitive advantage through streamlined regulatory familiarity, while European and American producers face extended approval timelines that disadvantage premium positioning in the world's largest volume market.
Adult patients now initiate orthodontic consultations through direct-to-consumer aligner platforms before ever visiting a physical practice, reversing the traditional discovery funnel. This channel disintermediation concentrates marketing spend toward social media and tele-dentistry onboarding, with the United States and United Kingdom showing the most pronounced behavioral shift away from dentist-referred specialist consultations.
Dental Braces Market Segmentation
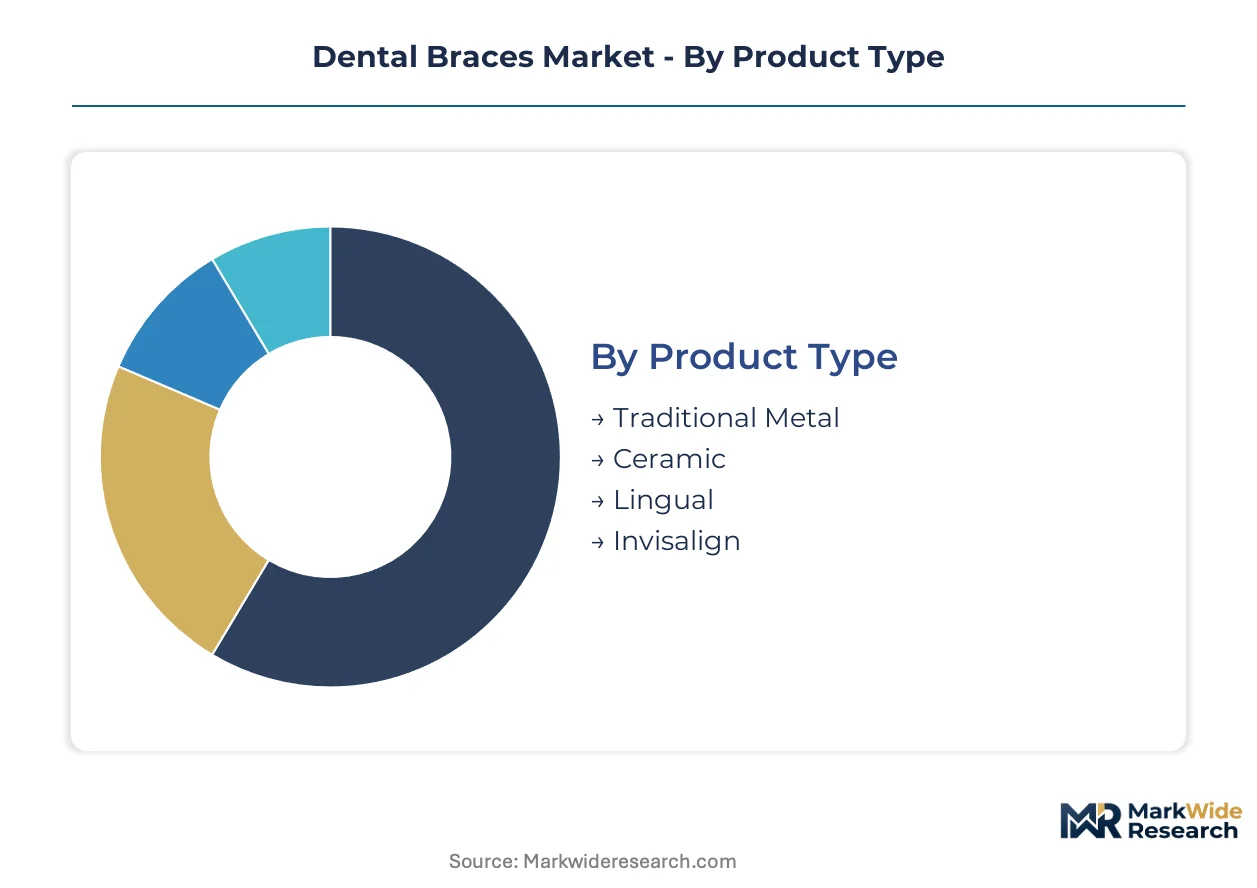
Segmentation in dental braces reveals how manufacturing scale, clinical workflow integration, and patient demographics create divergent margin profiles across hardware and digital platforms. Understanding these splits illuminates where capital equipment investments concentrate versus where subscription software captures recurring revenue.
Product Type:
Manufacturing capacity clusters around metal injection molding facilities in China and precision polymer processing in North America, with clear aligner fabrication requiring fundamentally different capital intensity than bracket-and-wire systems.
- Traditional Metal:Stainless steel brackets with nickel-titanium archwires dominate production volume due to established supply chains and lower per-unit material costs. Demand concentrates in India and Southeast Asia where cost sensitivity shapes clinical recommendations, though nickel price volatility from battery sector competition squeezes margin predictability for wire producers.
- Ceramic:Polycrystalline alumina or zirconia brackets offer aesthetic compromise between metal visibility and aligner cost, manufactured through precision sintering processes with higher scrap rates than metal alternatives. Chinese domestic producers now achieve scale in tier-two cities, displacing premium European imports through GB standards compliance and localized distribution.
- Lingual:Custom-milled brackets bonded to tooth interiors require CAD/CAM personalization and orthodontist certification, limiting addressable prescriber base despite complete aesthetic concealment.
- Invisalign:Thermoplastic aligner systems shift value capture toward software-enabled treatment planning subscriptions, with FDA 510(k) clearances accelerating competitive entry in the United States.
Traditional Metal absorbs the bulk of installed capacity; Invisalign is expanding most quickly.
Age Group:
Patient life stage determines treatment modality preference, reimbursement access, and compliance architecture—with adolescents and adults now driving divergent product development roadmaps.
- Adolescent:Peak orthodontic intervention window aligns with mixed dentition development, with parental payment authority enabling comprehensive fixed appliance selection. Demand concentrates in the United States and Western Europe where early orthodontic screening is standard, though clear aligner adoption among image-conscious teenagers is compressing traditional metal growth.
- Adult:Self-funded aesthetic correction prioritizes removable aligners and ceramic options, with direct-to-consumer platform discovery bypassing traditional dentist referral pathways in the United Kingdom and United States.
- Pediatric:Interceptive treatment for developing malocclusions remains tethered to specialist referral networks with slower volume expansion.
- Senior:Periodontal compromise and implant-restorative coordination limits orthodontic candidacy, representing a niche segment for limited treatment objectives.
Adolescent cases constitute the largest treatment volume; Adult applications are climbing the fastest as aesthetic discretion becomes normalized across age cohorts.
Application:
Clinical purpose shapes hardware selection, treatment duration, and pricing architecture—with functional correction commanding different reimbursement logic than elective aesthetic enhancement.
- Orthodontic Treatment:Comprehensive malocclusion correction using fixed appliances or aligner sequences addresses skeletal and dental discrepancies through biomechanical force application. Demand concentrates in specialist practices across Germany, Japan, and South Korea where orthodontic residency training density supports complex case management.
- Aesthetic Improvement:Limited treatment focused on anterior alignment and smile aesthetics drives aligner volume growth, with patient self-referral through social media discovery reshaping acquisition economics in the United States.
- Dental Alignment:Pre-restorative orthodontic positioning for implant placement or veneer preparation represents a crossover segment between orthodontics and prosthodontics.
- Preventive Care:Early interceptive appliances for arch development and habit correction remain concentrated in pediatric dental practices with established referral relationships.
Orthodontic Treatment retains the deepest clinical infrastructure investment; Aesthetic Improvement is gaining share fastest through platform-enabled patient acquisition.
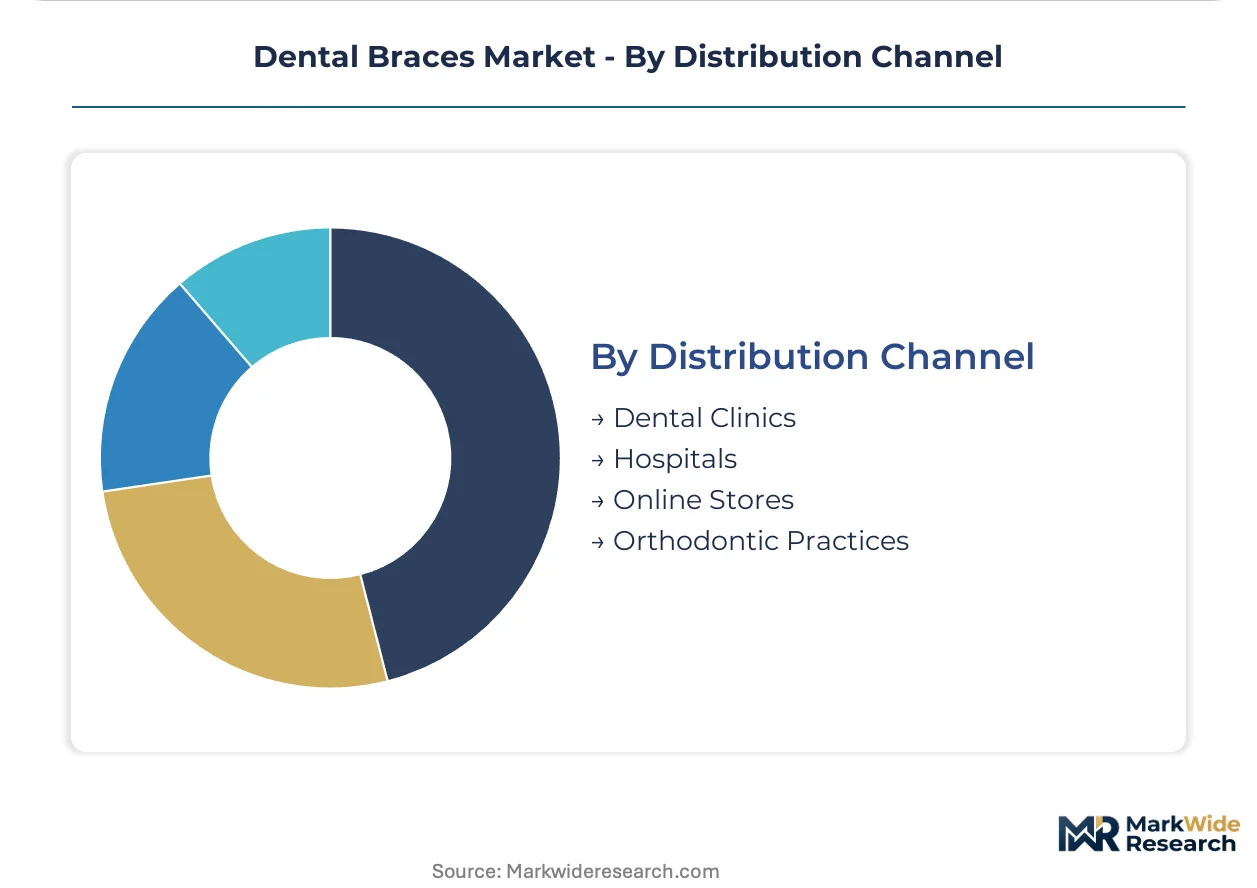
Distribution Channel:
Channel structure reflects regulatory control over prescription authority, with professional-only access for fixed appliances contrasting against emerging direct-to-consumer pathways for aligner systems.
- Dental Clinics:General dental practices with orthodontic service expansion capture margin previously flowing to specialists, particularly in the United States where intraoral scanning enables in-house aligner case management without referral.
- Orthodontic Practices:Specialist-owned facilities retain complex malocclusion and surgical case concentration, with Align Technology's subscription model locking in recurring software revenue from these high-volume providers.
- Hospitals:Craniofacial and cleft palate orthodontic services within academic medical centers handle complex interdisciplinary cases requiring surgical coordination.
- Online Stores:Direct-to-consumer aligner platforms bypass professional gatekeeping entirely, with regulatory scrutiny from the FDA and state dental boards intensifying around tele-dentistry supervision standards.
Dental Clinics represent the broadest channel expansion; Online Stores are scaling fastest despite regulatory friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the world's densest concentration of clear aligner manufacturing infrastructure, with precision polymer processing facilities supplying both domestic Chinese demand and export markets across Southeast Asia.
United States
Teenage aesthetic demand and direct-to-consumer platform adoption pull volume toward transparent aligner systems. FDA 510(k) premarket notification streamlines new product entry, compressing commercialization timelines for domestic innovators. The San Jose-to-San Francisco corridor houses Align Technology's digital scanning ecosystem development.
Germany
Specialist orthodontic residency density supports complex malocclusion case management with premium fixed appliances. EU Medical Device Regulation notified body conformity assessment extends certification timelines for imported bracket systems. The Stuttgart industrial region concentrates precision metalworking for self-ligating bracket architectures.
China
Domestic ceramic and self-ligating system manufacturers achieve scale economies that expand accessibility across tier-two and tier-three cities. National Medical Products Administration enforcement of updated GB standards for biocompatibility testing elevates documentation requirements for imported systems. Zhejiang province hosts the largest cluster of metal injection molding facilities for bracket base production.
India
Orthodontic case rates in secondary cities remain below one-tenth of metropolitan levels, creating whitespace for ceramic bracket distributors. Central Drugs Standard Control Organization regulates dental devices as medical devices requiring import license compliance. Mumbai and Delhi-NCR dominate specialist practice concentration and premium product adoption.
Japan
Aging demographics and periodontal health awareness limit orthodontic candidacy to stable adult cases with specific aesthetic objectives. Ministry of Economy, Trade and Industry promotes domestic manufacturing resilience for critical medical device components. The Osaka-Kobe industrial zone maintains specialized alloy processing for nickel-titanium archwire production.
Dental Braces Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the dental braces landscape. The market structures around three tiers: integrated digital platform operators capturing recurring software revenue, precision hardware manufacturers controlling bracket and wire fabrication, and distribution intermediaries managing channel access to chairside providers. Strategic moves concentrate on backward integration into polymer resin supply and cloud-based treatment planning portal development.
Among US-based platform operators, Align Technology exemplifies the subscription-model archetype through its proprietary digital scanning ecosystem. Henry Schein anchors the distribution tier through its control of North American dental practice supply chains. Ormco occupies a position within the precision hardware segment, specializing in self-ligating bracket architectures that reduce clinical chair time.
| Leading Market Players |
|---|
| American Orthodontics |
| Dentaurum |
| 3M Unitek |
| Align Technology |
| GC Orthodontics |
| Henry Schein |
| Ormco |
| FORESTADENT |
| Dentsply Sirona |
| Others |
Supply Flow & Price Mechanics
Precision polymer processing specialists concentrated in Shenzhen and San Jose drive labor-cost spreads between premium aligner systems and economy metal brackets. These workforce differentials separate subscription-enabled treatment planning from transactional hardware sales across three distinct pricing tiers.
Pricing Analysis
Outcome-based pricing anchored to case refinement rates and chair-time reduction dominates orthodontist-facing revenue models. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared aligner subscriptions from CE-marked ceramic brackets and unbranded metal alternatives. Price differentiation stems from ISO 13485 certification tier and software integration depth. Cost compression in economy metal brackets intensifies because nickel-titanium alloy spot volatility feeds through wire producers. General dental practices in India exhibit highest price sensitivity; specialist orthodontic chains in Germany show least.
Supply Chain Analysis
Skilled technicians for CAD/CAM aligner fabrication concentrate in China's Zhejiang province and North America's precision polymer corridors. Manufacturing gravity centers on China for metal injection molding of bracket bases, Germany for self-ligating architectures, and the United States for thermoplastic aligner forming. Raw material dependencies span nickel-titanium alloys from Japanese smelters, medical-grade polymers from German chemical producers, and zirconia feedstock from Australian mineral processors. Single-source vulnerability concentrates in nickel supply for archwire production. Distribution runs through Henry Schein's North American dental practice network and domestic Chinese distributors penetrating tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental braces market functions as a vertical-integration race where control over intraoral scanning hardware and cloud-based treatment planning portals determines recurring revenue capture. Players pursue backward integration into polymer resin supply to defend margin position against commodity volatility.
For Market Incumbents: Hedge against clear aligner platform disintermediation by deepening captive production of nickel-titanium archwire alloys and ceramic bracket sintering capacity. Lock in orthodontist workflow dependence through API-compatible practice management integrations that resist manual data re-entry. Defend against domestic Chinese manufacturers by accelerating FDA 510(k) clearance pipelines for next-generation self-ligating systems.
For New Entrants and Emerging Players: Direct-to-consumer tele-dentistry platforms offer the most penetrable channel for bypassing traditional dentist referral gatekeeping. Target adult aesthetic patients in secondary Indian cities where orthodontic case rates lag metropolitan levels by an order of magnitude. Pursue white-label manufacturing partnerships with Zhejiang-based metal injection molding facilities to achieve GB standards compliance without capital-intensive facility builds.
For Investors and Strategic Acquirers: Re-rating potential sits with software-enabled platform operators given the shift from hardware sales toward recurring treatment planning subscriptions. Long-term viability favors archetypes with integrated intraoral scanning ecosystems and orthodontist training certification programs. Watch FDA enforcement actions against direct-to-consumer aligner platforms as an inflection indicator for regulatory risk recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined premarket notification compresses commercialization timelines for domestic aligner innovators. |
| Backward Integration into Polymer Resin | Captive supply of medical-grade thermoplastic reduces exposure to German chemical producer pricing volatility. |
| Cloud-Based Treatment Planning Portal | Subscription revenue capture from orthodontists displaces transactional bracket-and-wire hardware margins. |
| GB Standards Compliance Investment | Biocompatibility documentation alignment unlocks China's tier-two and tier-three city expansion. |
| Remote Monitoring Platform Launch | Smartphone-based progress tracking creates new subscription streams while reducing in-office appointment frequency. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance volumes, NMPA registration timelines, and nickel-titanium alloy spot pricing anchored the trend analysis, supplemented by interviews with orthodontists, dental practice managers, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA MAUDE database entries, EUDAMED device registrations, Chinese customs trade data, and SEC 10-K filings from listed dental device manufacturers. Bottom-up patient case volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Input-output matrices modeled demand drivers including adolescent aesthetic preference shifts, adult direct-to-consumer platform adoption, and specialist orthodontist density by metropolitan region. Segmentation dimensions spanned product type, age group, clinical application, and distribution channel complexity. CAGRs derived from curve-fitting historical volume trajectories against projected case initiation rates, with nickel price volatility and EU MDR certification delays as industry-specific forecast inputs.
Caveats apply where nickel-titanium alloy supply disruptions, FDA enforcement against tele-dentistry platforms, or NMPA regulatory tightening could materially shift the outlook. Forecasts reflect assumptions about patient compliance with removable aligner protocols and orthodontist willingness to adopt cloud-based planning tools. A small set of triggers—raw material spot price spikes, notified body capacity constraints, and direct-to-consumer regulatory actions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Turbine Market
Dental Devices
US Dental Splint Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
Dental Handpieces Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Dental Floss Market
Dental Devices
China Dental Devices Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Dental Laboratories Market