
 Knee Hyaluronic Acid Injections Market | 2026-2036
Knee Hyaluronic Acid Injections Market Size, Share, and Industry Trends Forecast 2026-2036
Knee Hyaluronic Acid Injections Market Outlook
Modular injection kits that pair hyaluronic acid with corticosteroid options are realigning purchasing decisions in orthopedic clinics. Sanofi S.A. leverages its European manufacturing footprint to sustain supply continuity across Western markets. Bioventus LLC anchors its position through direct channel control in US ambulatory surgical centers. Seikagaku Corporation differentiates via specialized fermentation-derived sodium hyaluronate technology.
Knee hyaluronic acid injections constitute sterile, non-pyrogenic solutions of high molecular weight sodium hyaluronate or cross-linked derivatives, typically formulated at concentrations between 10 mg/mL and 20 mg/mL for intra-articular delivery to restore synovial fluid viscoelasticity in degenerated knee joints. The primary commercial purpose is symptomatic relief of osteoarthritis pain and functional improvement through mechanical lubrication and shock absorption. Viscosupplementation dominates current revenue pools due to established reimbursement codes and physician familiarity, while combination therapy represents the fastest-expanding segment as clinicians seek dual-mechanism protocols. Intra-articular delivery mode occupies the structural center of value capture, though sports medicine end users are driving interest in refined injection techniques and imaging-guided administration.
The FDA regulates these devices under 510(k) or PMA pathways depending on cross-linking chemistry and indication claims, while the EMA's MDR transition demands enhanced clinical evidence for CE-marked viscosupplements. Japan's PMDA maintains distinct pharmacological classification standards that shape local registration strategies for foreign manufacturers. Stakeholders must monitor evolving payer evidence requirements for combination products versus monotherapy benchmarks across major markets.
Market Dynamics
The FDA's updated guidance on intra-articular biologics is compressing product registration timelines while simultaneously elevating clinical evidence requirements, forcing manufacturers to restructure development pipelines around combination therapy protocols.
Growth Catalysts
- MDR Transition:The European Union's Medical Device Regulation mandates enhanced clinical evidence for CE-marked viscosupplements, accelerating consolidation among manufacturers with robust trial infrastructure.
- Aging Demographics:Japan's super-aged population structure sustains baseline demand for osteoarthritis interventions, with orthopedic clinics expanding injection capacity in Tokyo and Osaka metropolitan clusters.
- Cross-linked Chemistry:Advanced cross-linking technologies extend intra-articular residence time, enabling less frequent dosing schedules that align with value-based care metrics in US ambulatory settings.
Market Restraints
- Fermentation Input Volatility:Sodium hyaluronate derived from bacterial fermentation faces raw material cost fluctuations tied to pharmaceutical-grade glucose supply chains concentrated in Chinese manufacturing zones.
- Reimbursement Compression:US Medicare's ongoing refinement of viscosupplementation coverage policies creates payment uncertainty, particularly for single-injection formulations lacking distinct procedural codes.
- Platelet-Rich Plasma Substitution:Orthobiologic alternatives leveraging autologous blood derivatives capture sports medicine segments seeking regenerative positioning over mechanical lubrication.
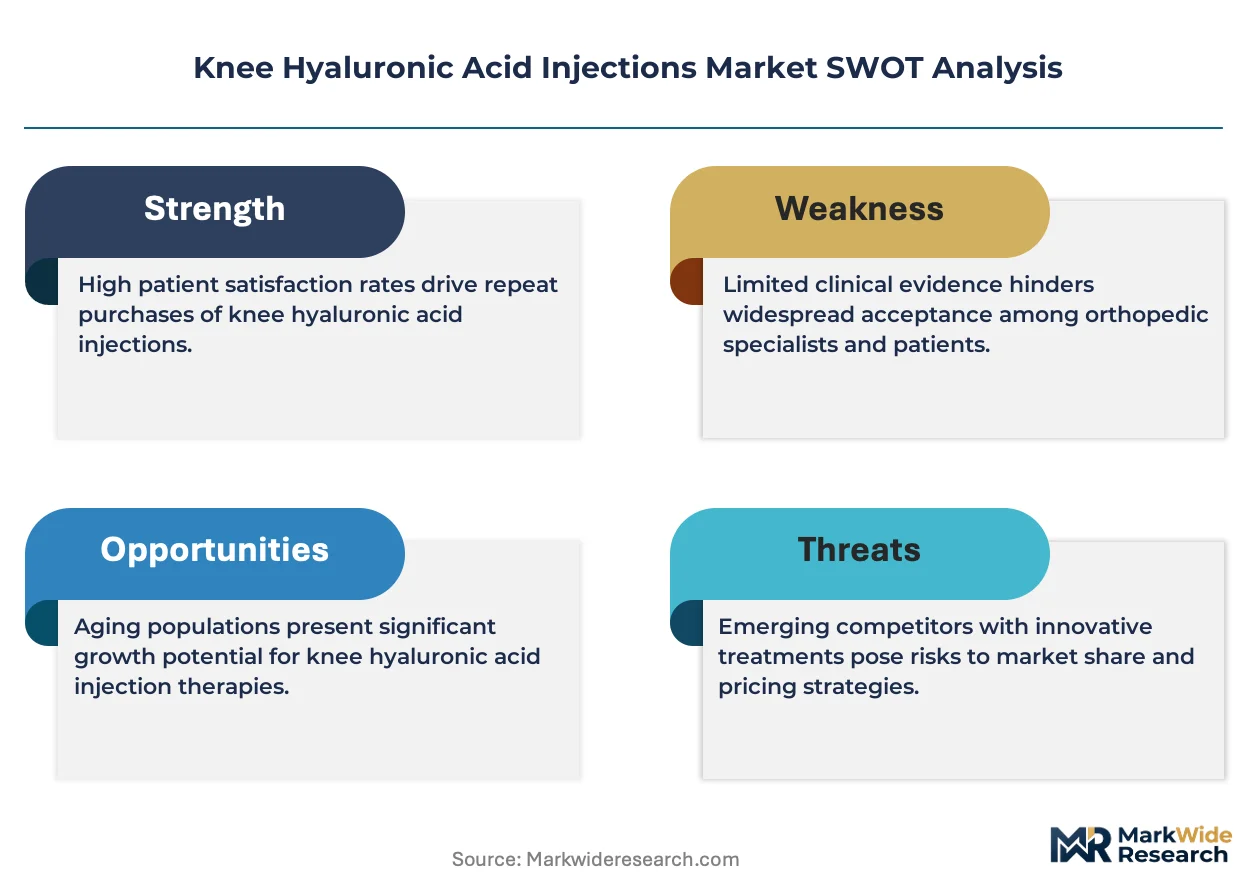
Strategic Opportunities
- German Outpatient Expansion:The country's statutory health insurance system is expanding same-day procedure authorization for intra-articular interventions, opening ambulatory orthopedic networks previously restricted to hospital-based delivery.
- Imaging-Guided Administration:Ultrasound-assisted injection techniques are penetrating sports medicine practices, creating premium service tiers that command differential pricing in private-pay segments.
- IRA Provisions:The US Inflation Reduction Act's Medicare negotiation framework indirectly pressures manufacturers to demonstrate superior cost-effectiveness, favoring combination products with dual mechanism claims.
Industry Challenges
- Biostatistical Talent Scarcity:The specialized expertise required for non-inferiority trial design against corticosteroid benchmarks commands premium compensation, constraining mid-tier manufacturers' clinical development capacity.
- Legacy Sterile Manufacturing Retrofit:Existing fill-finish facilities require substantial capital expenditure to accommodate combination kit configurations, particularly isolator technology for corticosteroid-hyaluronic acid co-packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knee Hyaluronic Acid Injections Market |
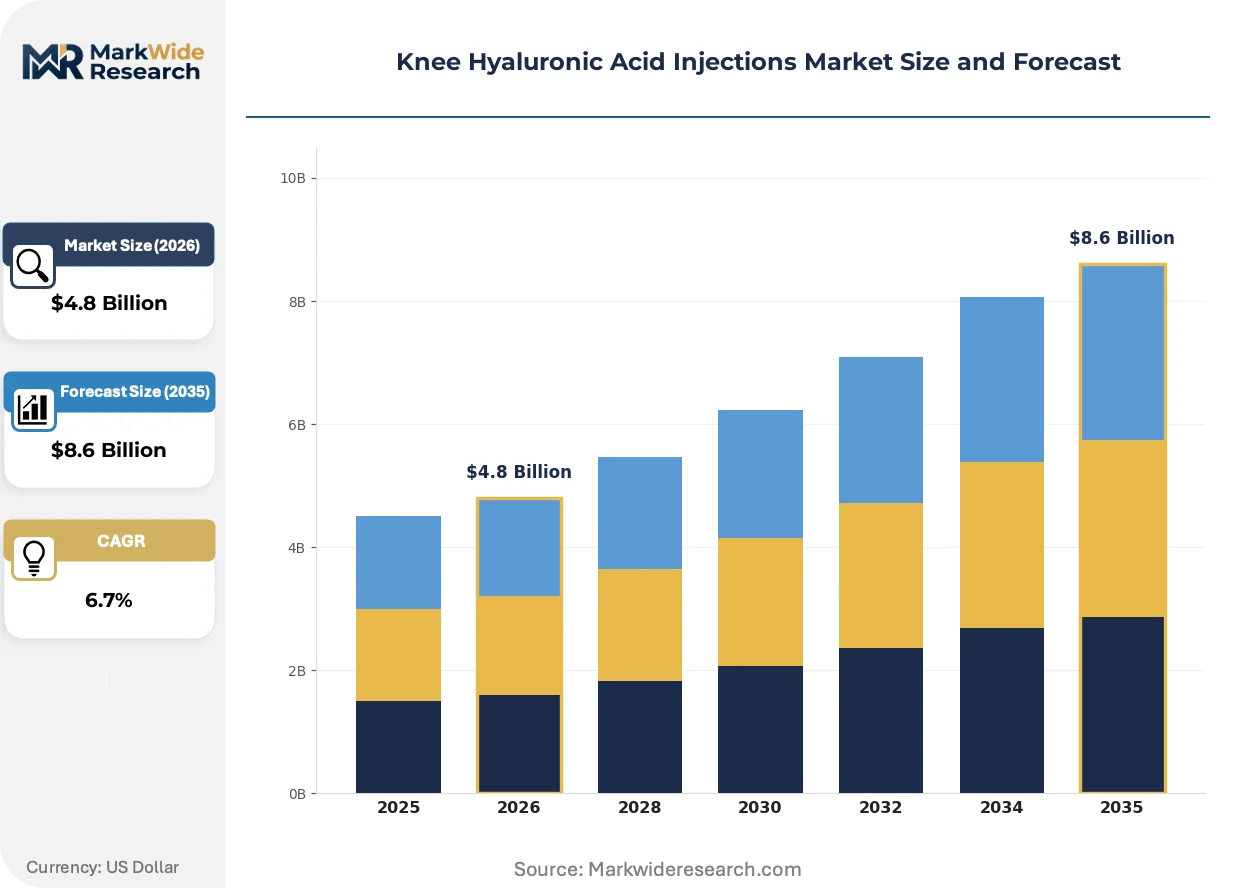
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monotherapy, Combination Therapy, Viscosupplementation, Injectable Application: Osteoarthritis, Pain Management, Joint Lubrication, Rehabilitation End User: Orthopedic Clinics, Physiotherapy Centers, Rehabilitation Facilities, Sports Medicine Delivery Mode: Intra-articular, Subcutaneous, Intravenous, Others |
| Companies Covered | Sanofi S.A., Bioventus LLC, Seikagaku Corporation, Zimmer Biomet, Anika Therapeutics, Inc., Fidia Farmaceutici S.p.A., Ferring B.V., LG Chem, OrthogenRx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knee Hyaluronic Acid Injections Market Strategic Shifts
Product formulation strategies are pivoting toward dual-mechanism platforms as clinicians demand symptomatic relief paired with potential disease-modifying signals, reshaping R&D allocation across the competitive set.
Single-injection cross-linked hyaluronic acid formulations are electrifying the standard-of-care conversation in US orthopedic clinics. Sports medicine physicians in Florida and Arizona markets are accelerating adoption of these extended-duration options. The technology is electrifying volume expectations for 3-injection regimens, compressing revenue-per-patient metrics while expanding total addressable procedure counts.
The European Medicines Agency's MDR transition is forcing systematic clinical evidence regeneration for legacy viscosupplement products. Manufacturers must now submit post-market clinical follow-up data that was previously exempt under the Medical Device Directive framework. German and French notified bodies are processing submissions most aggressively, while Southern European regulators lag in review capacity.
Hospital procurement committees are consolidating vendor relationships around full-line orthopedic biologics suppliers. Independent orthopedic practices in Texas and California are losing direct purchasing autonomy as health system integration accelerates. This concentration is most visible in US metropolitan markets where hospital-employed physician models now dominate knee osteoarthritis case volumes.
Knee Hyaluronic Acid Injections Market Segmentation
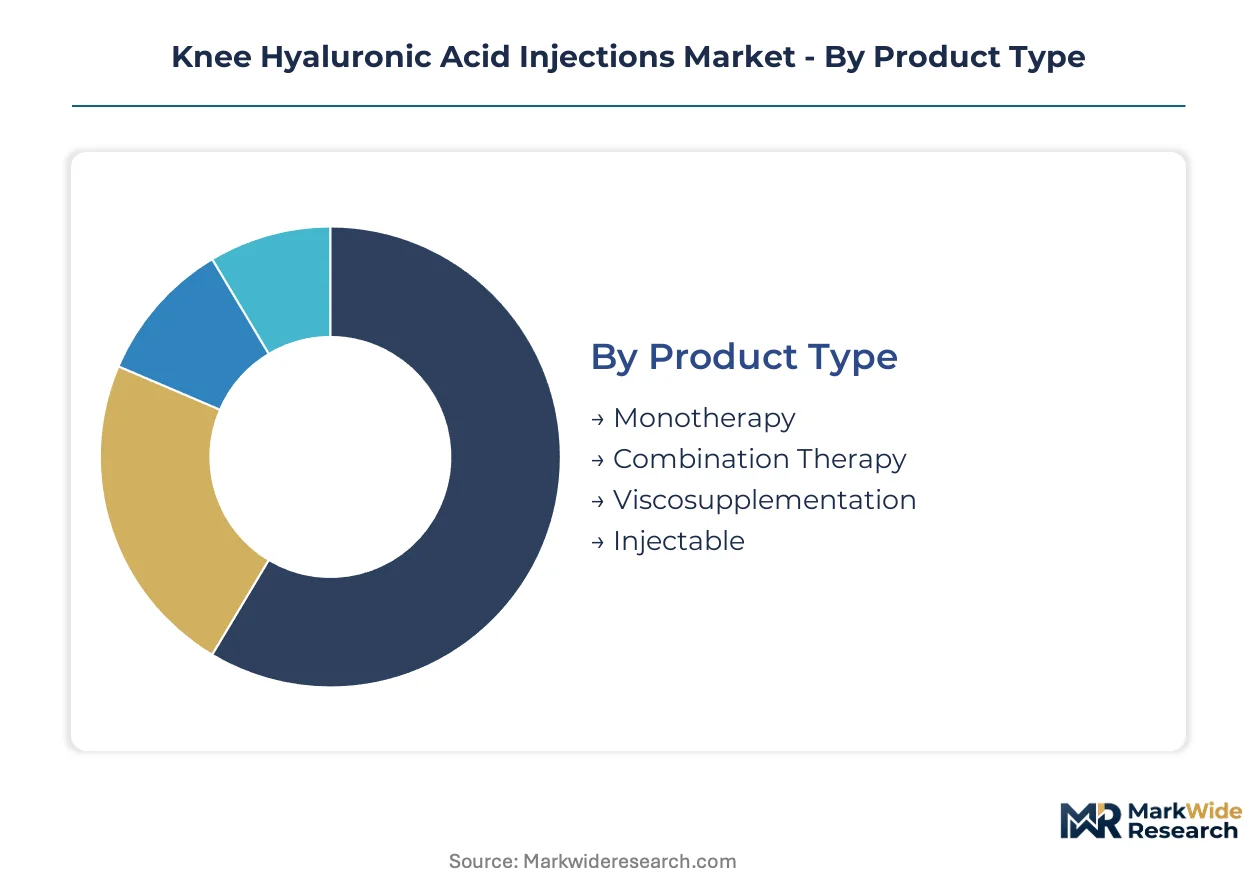
Segmentation in knee hyaluronic acid injections reflects divergent clinical protocols across reimbursement environments and physician specialty training. Product configuration, delivery setting, and administration technique each create distinct margin structures and competitive entry points.
Product Type:
Standardization dominates high-volume viscosupplementation while combination platforms demand customization for dual-mechanism protocols.
- Viscosupplementation:High molecular weight sodium hyaluronate formulations at 10-20 mg/mL concentrations constitute the revenue core. Orthopedic clinics in the United States and Germany generate concentrated demand due to established CPT and EBM reimbursement codes that reward mechanical lubrication protocols.
- Combination Therapy:Co-formulated or co-packaged hyaluronic acid with corticosteroid components enables simultaneous anti-inflammatory and viscoelastic action. Sports medicine practices in Arizona and Florida metropolitan clusters are driving fastest adoption as physicians seek differentiated injection protocols.
- Monotherapy:Single-agent hyaluronic acid without adjunctive pharmaceuticals serves cost-sensitive procurement committees.
- Injectable:General classification covering all parenteral administration formats beyond intra-articular specificity.
Leading the category by volume: Viscosupplementation. Growing fastest: Combination Therapy.
Application:
Clinical endpoints range from symptomatic relief to functional restoration, with reimbursement intensity varying by diagnostic coding specificity.
- Osteoarthritis:Degenerative joint disease management represents the primary commercial indication. Knee osteoarthritis cases in Japan's super-aged population sustain baseline procedural volumes, with Tokyo and Osaka orthopedic networks expanding injection capacity.
- Pain Management:Symptomatic relief protocols target functional improvement metrics. German outpatient clinics leverage expanded same-day procedure authorization under statutory health insurance reforms.
- Joint Lubrication:Mechanical restoration of synovial fluid viscoelasticity.
- Rehabilitation:Post-surgical or post-injury functional recovery support.
Volume concentration: Osteoarthritis. Steepest expansion trajectory: Pain Management.
End User:
Site-of-service economics create tiered pricing power, with hospital-employed models compressing independent practice autonomy.
- Orthopedic Clinics:Specialized musculoskeletal practices command premium positioning through direct physician-patient relationships. Texas and California health system integration is consolidating vendor selection authority away from independent practitioners.
- Sports Medicine:Athletic injury and performance-focused practices adopt imaging-guided techniques. Ultrasound-assisted injection protocols in Florida sports medicine centers command differential private-pay pricing.
- Physiotherapy Centers:Rehabilitation-focused facilities with limited procedural authorization.
- Rehabilitation Facilities:Post-acute care settings emphasizing functional recovery.
Maximum procedure volume: Orthopedic Clinics. Fastest share gain: Sports Medicine.
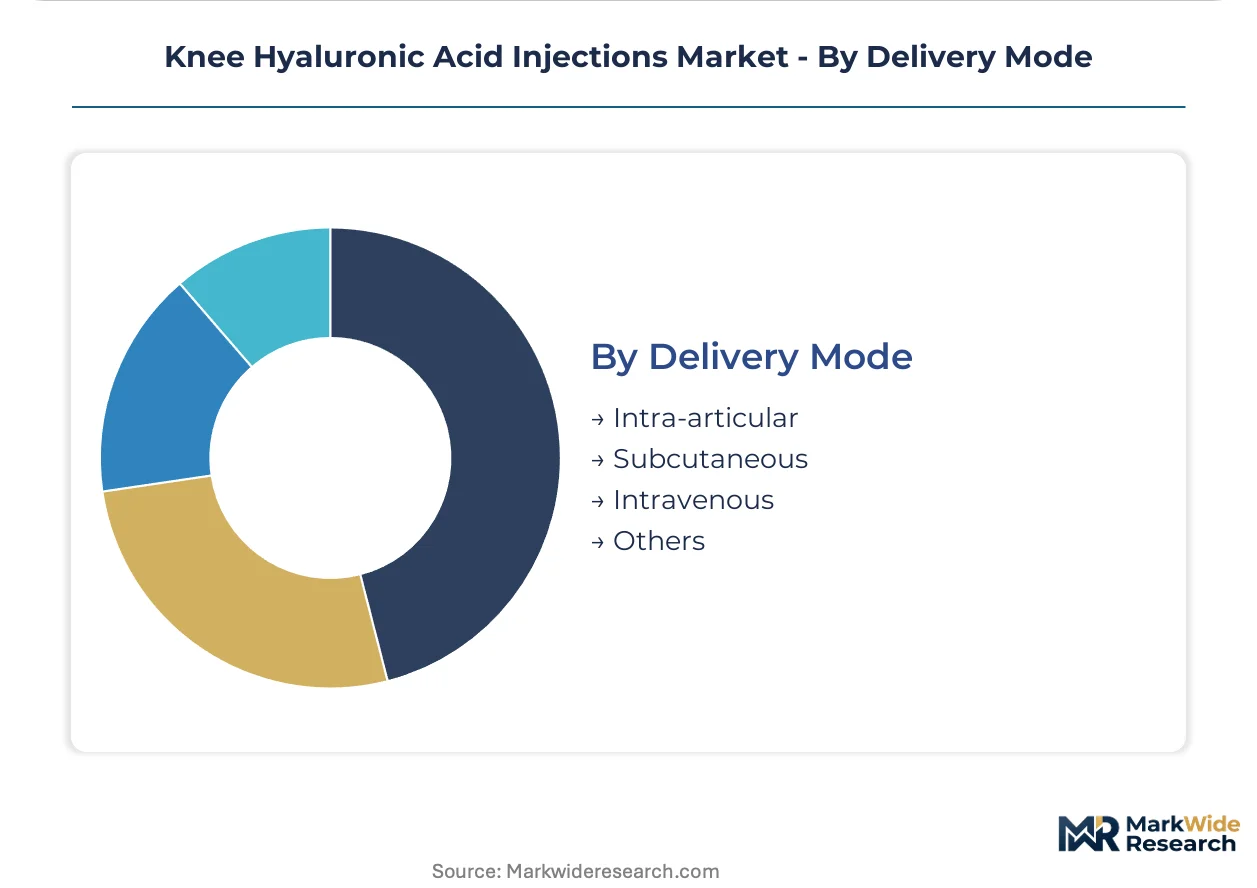
Delivery Mode:
Route of administration determines regulatory pathway complexity and clinical evidence requirements.
- Intra-articular:Direct joint space injection constitutes the structural center of value capture. FDA 510(k) and PMA pathways govern US market entry, with cross-linked chemistry variants facing elevated clinical evidence thresholds.
- Subcutaneous:Alternative route for systemic or localized soft tissue delivery.
- Intravenous:Systemic administration with limited knee-specific application.
- Others:Emerging or investigational delivery modalities.
Revenue dominance: Intra-articular. Regulatory scrutiny intensity: Intra-articular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical device manufacturing zones in Germany's Baden-Württemberg region concentrate European viscosupplement production capacity. Tax incentives for pharmaceutical-grade fermentation facilities in Hyogo Prefecture, Japan, anchor Asian supply chains. Free trade zone status for healthcare imports in Dubai Healthcare City shapes Middle East distribution patterns.
United States
Medicare's evolving reimbursement codes for intra-articular injections drive demand concentration in ambulatory surgical centers. The FDA's 510(k) pathway governs market entry for cross-linked hyaluronic acid formulations. Florida and Arizona metropolitan clusters host expanding sports medicine practices adopting single-injection extended-duration protocols.
Germany
Statutory health insurance expansion of same-day procedure authorization unlocks ambulatory orthopedic networks. The EMA's MDR transition demands enhanced clinical evidence for CE-marked viscosupplements. Munich and Stuttgart medical device clusters concentrate manufacturing infrastructure for fermentation-derived sodium hyaluronate.
Japan
Super-aged demographics sustain procedural volume growth in knee osteoarthritis management. The PMDA maintains distinct pharmacological classification standards shaping local registration strategies. Tokyo and Osaka orthopedic networks are expanding injection capacity to meet baseline demand from the 65-plus population segment.
China
Domestic fermentation capacity for pharmaceutical-grade sodium hyaluronate is scaling in Shandong Province. The NMPA regulates intra-articular biologics under medical device and drug hybrid pathways. Shanghai and Suzhou biotech clusters are attracting joint venture partnerships for localized viscosupplement production.
Knee Hyaluronic Acid Injections Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the knee hyaluronic acid injections landscape. Market structure exhibits moderate consolidation around established fermentation technology holders and surgical device incumbents. Three archetypes dominate: pharmaceutical conglomerates with integrated biologics divisions, orthopedic device specialists extending into biologics adjacencies, and dedicated hyaluronic acid fermentation houses. Competitive moves concentrate on M&A for cross-linked chemistry capabilities and strategic partnerships for combination kit co-development.
Within the pharmaceutical conglomerate tier, Sanofi S.A. exemplifies European manufacturing footprint leverage for supply continuity. Among US-based specialists, Bioventus LLC occupies a position emphasizing direct channel control in ambulatory surgical centers. Japanese fermentation technology is represented by Seikagaku Corporation, which anchors specialized sodium hyaluronate production expertise. These three players collectively illustrate the geographic and technological diversification strategies competing for procurement committee consolidation.
| Leading Market Players |
|---|
| Sanofi S.A. |
| Bioventus LLC |
| Seikagaku Corporation |
| Zimmer Biomet |
| Anika Therapeutics, Inc. |
| Fidia Farmaceutici S.p.A. |
| Ferring B.V. |
| LG Chem |
| OrthogenRx |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade glucose feedstock flows from Shandong Province fermentation facilities through cross-linked chemistry processing in Baden-Württemberg, ultimately stratifying into premium single-injection formulations for US ambulatory surgical centers and standard viscosupplementation kits for German outpatient networks. Input cost volatility at the fermentation stage propagates downstream, compressing margins on economy-tier products while insulated premium tiers maintain pricing power through extended-duration clinical claims.
Pricing Analysis
Margin tightening in economy-tier viscosupplementation reflects reimbursement compression from US Medicare's ongoing CPT code refinements and statutory health insurance cost-containment measures in Germany. Three-tier pricing structure across premium cross-linked single-injection, standard three-injection regimens, and economy non-cross-linked monotherapy segments dominates procurement decisions. Price differentiation hinges on molecular weight certification and FDA 510(k) pathway designation. Sports medicine practices in Florida and Arizona exhibit lowest price sensitivity due to private-pay imaging-guided administration premiums, while hospital-employed orthopedic clinics in Texas face concentrated formulary pressure.
Supply Chain Analysis
Japan's PMDA domestic-content preferences for fermentation-derived sodium hyaluronate are redirecting foreign manufacturers toward Hyogo Prefecture joint venture structures. Supply concentrates in China for pharmaceutical-grade glucose inputs, Germany for precision cross-linking equipment, and Japan for specialized fermentation expertise. Raw material dependencies encompass bacterial culture media, cross-linking agents, and isolator-grade packaging components. Single-source vulnerability in Chinese glucose supply chains exposes manufacturers to export restriction risk. Distribution runs through hospital procurement committees consolidating vendor relationships around full-line orthopedic biologics suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity for pharmaceutical-grade sodium hyaluronate props pricing across all tiers, constraining volume expansion for mid-tier manufacturers lacking captive supply. This bottleneck justifies prioritizing supply security over share capture.
For Market Incumbents: Deploy backward integration into bacterial fermentation capacity to secure glucose supply chain continuity against Chinese export volatility. Incumbents should simultaneously deepen hospital system partnership structures to defend formulary positioning against platelet-rich plasma substitution threats in sports medicine segments. Cross-linked chemistry R&D investment represents the critical lever for maintaining premium tier access. For New Entrants and Emerging Players: Ambulatory orthopedic networks in Germany's same-day procedure expansion zones offer the most penetrable white-space opportunity, given statutory health insurance reimbursement clarity and limited incumbent direct channel control. New entrants should prioritize combination therapy kit development targeting corticosteroid-hyaluronic acid co-formulation demand in Arizona and Florida sports medicine practices. Specialist distributor partnerships with imaging-guided injection training capabilities provide the essential go-to-market angle. For Investors and Strategic Acquirers: FDA's updated guidance on intra-articular biologics elevating clinical evidence requirements is the leading indicator that fermentation technology holders with robust trial infrastructure will command acquisition premiums. Long-term viability centers on combination product platforms with dual-mechanism claims spanning the 5-10 year regulatory consolidation window. Acquisition target archetype: mid-tier manufacturers with CE-marked legacy products facing MDR transition costs but possessing established European distribution. The signal to monitor is German notified body processing speed differentials affecting time-to-revenue for new entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-linked Chemistry Scale-up | Extended residence time formulations align with US value-based care metrics in ambulatory settings. |
| Combination Kit Development | Corticosteroid-hyaluronic acid co-packaging captures fastest-expanding segment in sports medicine. |
| MDR Clinical Evidence Regeneration | Post-market follow-up data submissions secure CE marking continuity under EMA transition timelines. |
| Direct Channel Control | Ambulatory surgical center relationships insulate pricing from hospital procurement committee consolidation. |
| Fermentation Joint Venture | Hyogo Prefecture partnerships satisfy PMDA domestic-content preferences for Japan market access. |
Study Parameters
Multi-period observation of intra-articular injection procedure volumes, reimbursement code utilization patterns, and fermentation capacity utilization anchored the trend analysis, supplemented by interviews with orthopedic clinic administrators, hospital purchasing committee members, sports medicine physicians, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement data, and hospital procurement contract disclosures. Bottom-up procedure volume modeling and top-down market sizing triangulated demand estimates across segmentation dimensions.
Input-output matrices mapped fermentation capacity through cross-linking chemistry variants to end-user price tiers across the analysis window. Segmentation dimensions modeled encompass product type, application indication, end-user site of service, and delivery mode complexity. CAGRs derived from regression analysis against demographic projections and reimbursement policy trajectories. Industry-specific forecast inputs incorporated PMDA registration pathway timelines and US Inflation Reduction Act Medicare negotiation framework impacts.
Several conditions sit outside the modeled scope, including novel orthobiologic regulatory reclassification, autologous blood derivative technology substitution rates, and geopolitical disruption to pharmaceutical-grade glucose trade flows. Forecasts reflect documented assumptions regarding reimbursement stability and clinical evidence generation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Hallux Rigidus Market
Orthopedics
Tendon Repair Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Septic Arthritis Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Europe Bone Metastasis Market
Orthopedics
Rickets Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Osgood-Schlatter Market
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Rotator Cuff Arthropathy Repair Market