
 Europe Orthopedic Braces and Support Market | 2026-2036
Europe Orthopedic Braces and Support Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Orthopedic Braces and Support Market Intelligence
A capital-intensity divergence between automated thermoforming lines and manual cut-and-sew operations is bifurcating competitive economics across the Europe orthopedic braces and support landscape. DJO Global leverages its vertically integrated manufacturing footprint in Germany to sustain margin structures on high-volume knee brace production. medi GmbH & Co. KG anchors premium positioning through specialized medical compression technology that dominates hospital formulary access in Central Europe. Bauerfeind AG differentiates via precision anthropometric fitting systems that control the sports medicine channel across Alpine markets.
Orthopedic braces and support constitute mechanical assistive devices engineered from elastic fabrics, neoprene laminates, thermoplastic shells, or carbon-fiber composites to restrict joint motion, offload structural load, or guide post-injury rehabilitation trajectories. These devices serve commercial purposes ranging from acute trauma immobilization in emergency departments to chronic osteoarthritis management in outpatient physiotherapy settings. Knee braces and ankle supports together occupy the dominant volume position, though back support categories are recording accelerated growth as occupational health programs expand across Northern European manufacturing sectors. Elastic fabric technology leads unit economics due to scalable knitting infrastructure, while composite materials command premium pricing in custom-fabricated post-operative applications where thermoplastic vacuum-forming enables patient-specific geometry.
The EU Medical Device Regulation (MDR) and CE marking framework administered by notified bodies across member states are elevating clinical evidence requirements for reusable brace classifications, directly shaping product development timelines and market access costs. Germany's national reimbursement authority, the G-BA, influences demand patterns through its prosthetics and aids directive that determines which brace categories qualify for statutory health insurance coverage. France's ANSM and the United Kingdom's MHRA maintain parallel vigilance systems for adverse event reporting that manufacturers must navigate for multi-country portfolio registration. Stakeholders must monitor how forthcoming MDR transitional deadline enforcement will reshape the competitive set by filtering out legacy products lacking updated technical documentation.
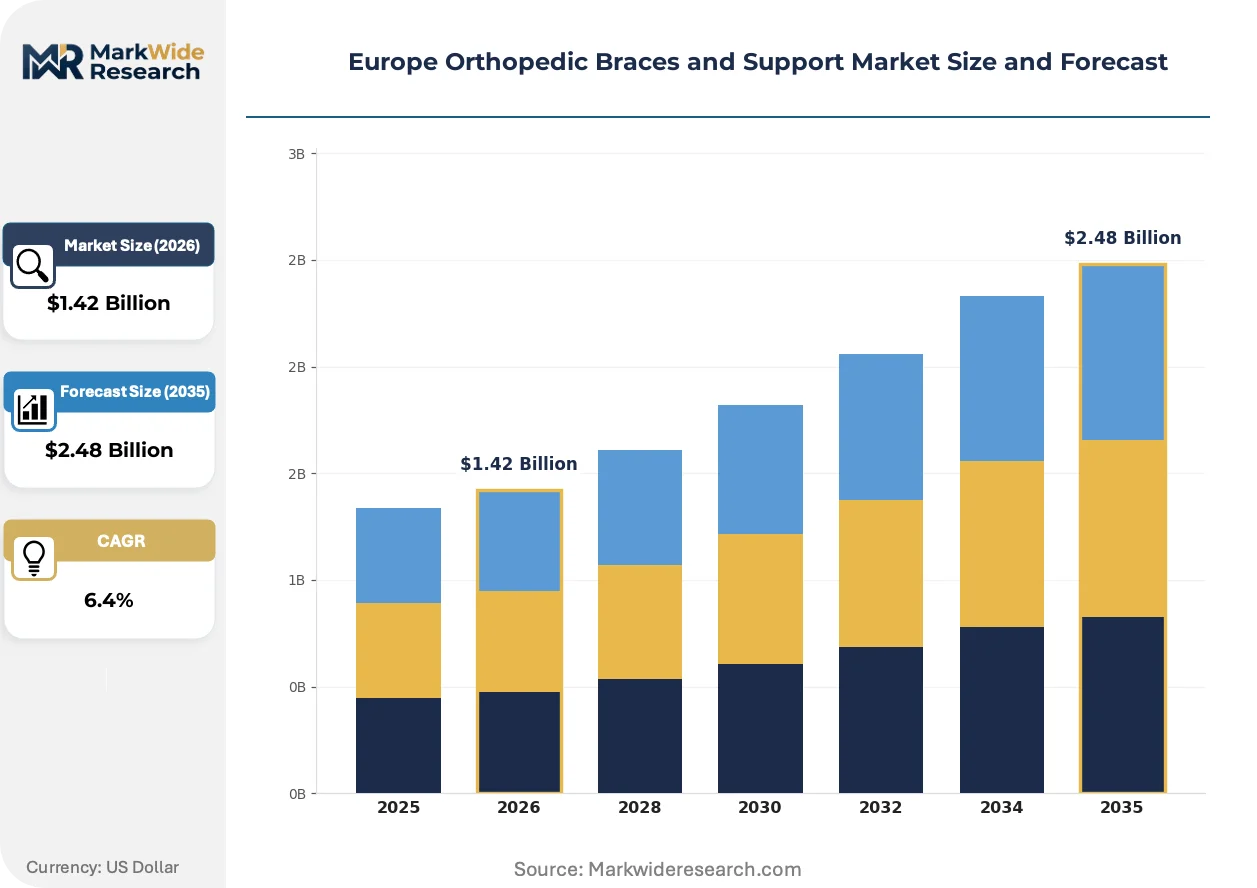
Market Dynamics
EU MDR transitional deadline enforcement is filtering legacy products lacking updated technical documentation, compressing the competitive set while elevating clinical evidence burdens for reusable brace classifications.
Growth Catalysts
- G-BA prosthetics directive expansion:Germany's national reimbursement authority is widening statutory health insurance coverage for post-operative knee and ankle braces, directly lifting hospital procurement volumes.
- Thermoplastic vacuum-forming automation:German manufacturing clusters are deploying precision anthropometric fitting infrastructure that accelerates custom-fabricated brace production cycles.
- Alpine sports medicine infrastructure:Switzerland and Austria are expanding specialized orthopedic rehabilitation centers that anchor premium brace consumption for athletic trauma management.
Market Restraints
- Carbon-fiber composite input volatility:Aerospace and automotive sectors compete for carbon-fiber prepreg supply, squeezing brace manufacturers dependent on lightweight composite shells for premium segments.
- Notified body capacity concentration:CE marking assessments for Class I reusable devices bottleneck at a shrinking pool of EU-accredited conformity assessment bodies, extending time-to-market.
- Elastic fabric substitution pressure:Basic neoprene laminates face displacement from 3D-knitted compression textiles that deliver comparable biomechanical support at lower unit economics.
Strategic Opportunities
- Poland and Czech Republic manufacturing corridors:Central European labor cost differentials and proximity to German distribution networks attract thermoforming line relocation from Western European facilities.
- Occupational back support mandates:Northern European manufacturing sectors in Sweden and Denmark are integrating preventive lumbar braces into workplace health compliance frameworks.
- Digital fitting convergence:Smartphone-based 3D scanning applications are merging with cloud-based prescription platforms to enable remote brace customization without clinical visits.
Industry Challenges
- Biocompatibility testing backlog:Extended skin-sensitization study queues at EU reference laboratories delay MDR technical documentation completion for novel textile formulations.
- Orthopedic technician skill scarcity:Precision thermoforming and CAD-driven brace design require specialized training pipelines that vocational institutions in France and Italy have not scaled to match demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Orthopedic Braces and Support Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee Braces, Ankle Supports, Back Supports, Wrist Braces End User: Hospitals, Clinics, Physiotherapy Centers, Home Care Technology: Elastic Fabric, Neoprene, Thermoplastics, Composite Materials Distribution Channel: Online Retail, Pharmacy Chains, Medical Supply Stores, Direct Sales |
| Companies Covered | DJO Global, medi GmbH & Co. KG, Össur, Breg Inc., DeRoyal Industries, Ottobock, Thuasne, 3M Company, Bauerfeind AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Orthopedic Braces and Support Market Strategic Shifts & Innovations
Material science advances and regulatory digitization are compressing product lifecycles while elevating performance thresholds for mechanical assistive devices across European rehabilitation channels.
Carbon-fiber reinforced thermoplastic composites are displacing traditional aluminum and steel structural elements in custom post-operative knee braces. German university hospitals and Swiss sports medicine clinics are adopting these lightweight alternatives for anterior cruciate ligament reconstruction protocols. The shift is displacing legacy metal-hinged designs from premium reimbursement tiers as patient mobility metrics become central to formulary access decisions.
EU MDR Article 10 technical documentation requirements are mandating clinical evaluation reports for all reusable brace classifications previously exempt under the Medical Devices Directive. Manufacturers must now submit post-market surveillance data and biological safety assessments to notified bodies in Germany, France, and the Netherlands. The regulatory burden falls heaviest on small-to-mid enterprises lacking dedicated regulatory affairs departments, consolidating market share toward vertically integrated producers with captive compliance infrastructure.
Hospital procurement consortia in the United Kingdom and Scandinavia are consolidating brace purchasing through framework agreements that bundle orthopedic supports with physiotherapy service contracts. Independent medical supply distributors are losing shelf space as integrated health systems negotiate direct manufacturer relationships. The concentration is most pronounced in England's NHS Supply Chain and Sweden's regional healthcare procurement bodies, where volume commitments override brand loyalty in supplier selection criteria.
Europe Orthopedic Braces and Support Market Segmentation
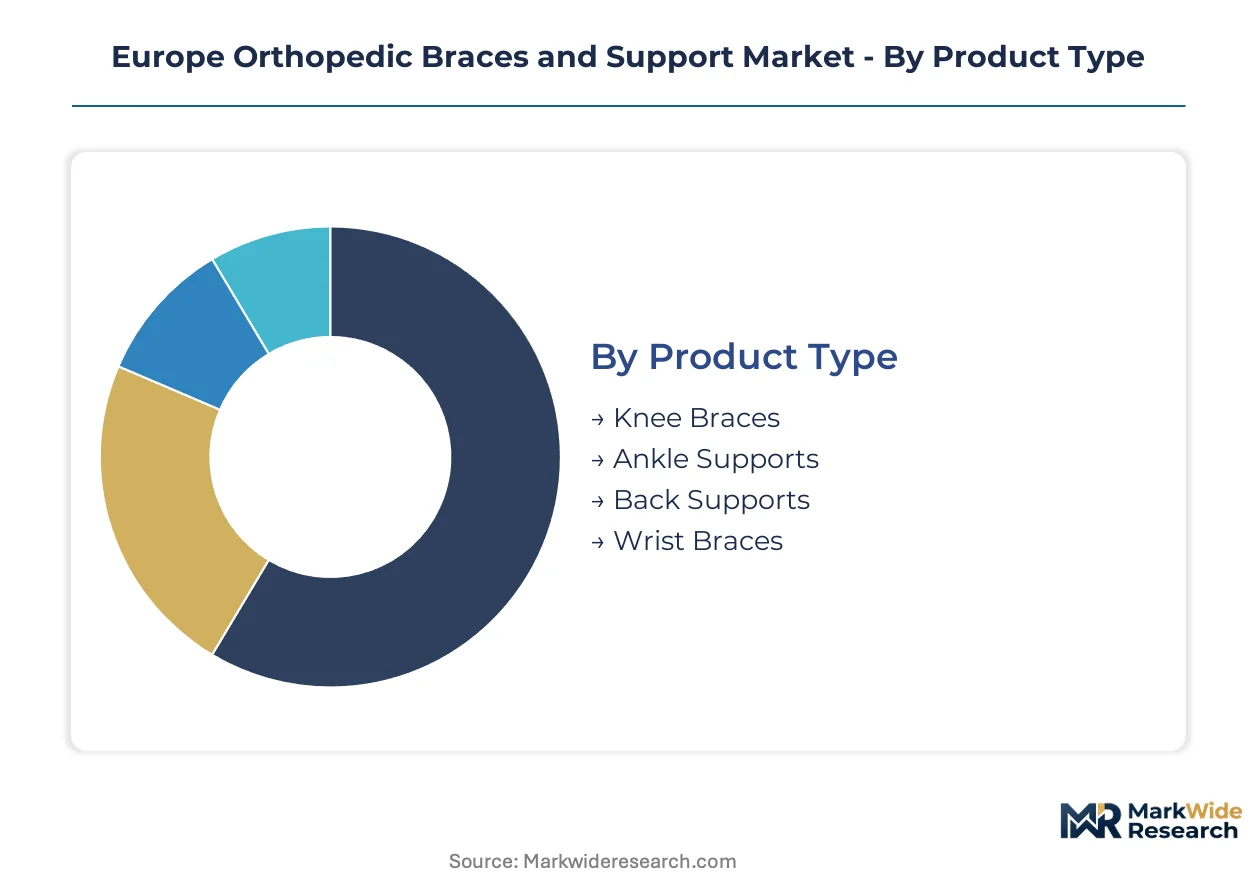
Orthopedic brace manufacturers navigate divergent compliance pathways and reimbursement tiers across product categories. Segmentation clarity determines which technical documentation burdens apply and where margin structures concentrate.
Product Type:
EU MDR classification rules split these categories by risk level and clinical evidence requirements, with Class I reusable devices facing tightened conformity assessments.
- Knee Braces:Hinged and sleeve designs incorporate aluminum stays, carbon-fiber shells, or compression textiles to manage ligament instability and osteoarthritis progression. German university hospitals and Swiss sports medicine clinics are expanding procurement of post-operative hinged variants following anterior cruciate ligament reconstruction protocols.
- Ankle Supports:Lace-up, stirrup, and elastic wrap configurations stabilize inversion-eversion trauma and chronic instability. Alpine rehabilitation centers in Austria and Switzerland anchor premium consumption for athletic trauma management, with thermoplastic stirrup designs displacing neoprene wraps in formulary access decisions.
- Back Supports:Rigid corsets and flexible lumbar belts address occupational strain and post-surgical spinal stabilization. Northern European manufacturing sectors in Sweden and Denmark are integrating preventive variants into workplace health compliance frameworks.
- Wrist Braces:Cock-up splints and compression sleeves immobilize carpal tunnel syndrome and distal radius fractures. Outpatient physiotherapy settings in France and the United Kingdom drive volume for prefabricated elastic designs.
Knee braces handle the majority of throughput; back supports are gaining share fastest as occupational health mandates expand.
End User:
Procurement authority and reimbursement eligibility shift dramatically across these settings, dictating price realization and technical specification requirements.
- Hospitals:Acute care and surgical departments require sterilizable, durable designs with documented biocompatibility for post-operative immobilization. Germany's G-BA prosthetics directive determines which categories qualify for statutory health insurance coverage, directly lifting procurement volumes for qualifying devices.
- Clinics:Orthopedic and sports medicine practices fit custom-fabricated and off-the-shelf braces for trauma and chronic conditions. Precision anthropometric fitting infrastructure in German manufacturing clusters accelerates production cycles for these intermediate care settings.
- Physiotherapy Centers:Rehabilitation-focused practices emphasize progressive mobilization braces and compression textiles. Framework agreements in England's NHS Supply Chain bundle orthopedic supports with service contracts, concentrating purchasing power.
- Home Care:Direct-to-patient channels serve chronic osteoarthritis management and preventive applications. Smartphone-based 3D scanning applications are merging with cloud-based prescription platforms to enable remote customization without clinical visits.
Hospitals command the highest unit values; home care is expanding most quickly as digital fitting convergence reduces clinical dependency.
Technology:
Material selection determines manufacturing capital intensity, regulatory testing burden, and pricing tier placement within reimbursement schedules.
- Elastic Fabric:Knitted nylon-spandex blends deliver compression and mild stabilization through scalable textile infrastructure. These variants lead unit economics due to manufacturing throughput, though they face displacement pressure from 3D-knitted alternatives.
- Neoprene:Laminated rubber-foam composites provide thermal retention and cushioned support for athletic and chronic applications. Basic laminates face substitution from advanced compression textiles delivering comparable biomechanical support at lower unit economics.
- Thermoplastics:Vacuum-formable polyethylene and polypropylene sheets enable patient-specific geometry for post-operative immobilization. German manufacturing clusters deploy precision anthropometric fitting infrastructure that accelerates custom-fabricated production cycles.
- Composite Materials:Carbon-fiber reinforced shells and prepregs deliver strength-to-weight ratios for premium hinged braces. Aerospace and automotive sectors compete for carbon-fiber prepreg supply, squeezing manufacturers dependent on lightweight shells for premium segments.
Elastic fabric handles volume leadership; composite materials command the steepest expansion trajectory as patient mobility metrics become central to formulary access.
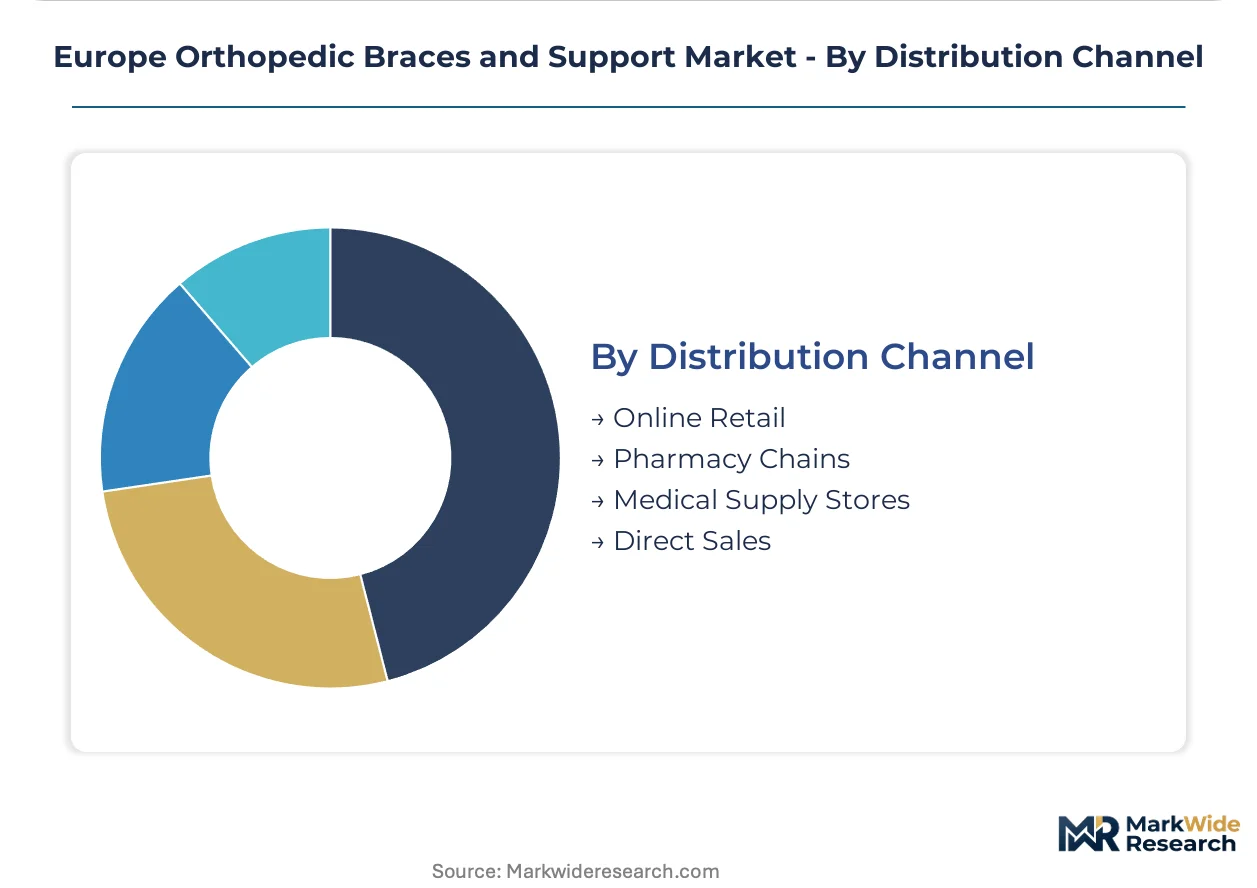
Distribution Channel:
Channel structure is consolidating as hospital procurement consortia and integrated health systems displace independent distributors.
- Online Retail:E-commerce platforms and manufacturer-direct websites serve price-sensitive consumers and repeat purchasers. Digital channels are capturing share fastest where smartphone-based fitting applications reduce sizing uncertainty.
- Pharmacy Chains:National networks in Germany, France, and the United Kingdom stock prefabricated elastic and neoprene supports for acute self-treatment. These channels face margin compression as reimbursement documentation requirements intensify.
- Medical Supply Stores:Independent and chain specialty retailers provide fitting services for custom and semi-custom devices. Independent distributors are losing shelf space as integrated health systems negotiate direct manufacturer relationships.
- Direct Sales:Manufacturer representatives and orthopedic technicians fit custom braces in clinical settings. This channel captures premium pricing where precision anthropometric fitting and G-BA reimbursement eligibility intersect.
Direct sales retains margin leadership; online retail is climbing the fastest as digital fitting convergence expands addressable geography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe runs a modest trade surplus in orthopedic braces, with German and Swiss manufacturing clusters exporting precision-fitted devices to Middle Eastern and Asian markets while importing basic elastic textiles from Southeast Asian suppliers.
Germany
University hospitals in Berlin and Munich are expanding post-surgical brace procurement volumes following anterior cruciate ligament reconstruction protocol standardization. The G-BA prosthetics directive determines statutory health insurance coverage eligibility, directly lifting hospital procurement for qualifying hinged knee devices. Manufacturing clusters in Bavaria and North Rhine-Westphalia deploy automated thermoforming lines that accelerate custom-fabricated production cycles.
France
ANSM vigilance requirements for adverse event reporting shape multi-country portfolio registration strategies for manufacturers serving the French market. The country's occupational health programs in manufacturing sectors around Lyon and Grenoble are integrating preventive lumbar braces into workplace compliance frameworks. Paris-based hospital procurement consortia are consolidating brace purchasing through framework agreements that bundle orthopedic supports with physiotherapy service contracts.
United Kingdom
England's NHS Supply Chain concentration is displacing independent medical supply distributors as integrated health systems negotiate direct manufacturer relationships. The MHRA maintains parallel vigilance systems for adverse event reporting that manufacturers must navigate for market access. London and Manchester orthopedic rehabilitation centers are expanding specialized infrastructure that anchors premium brace consumption for athletic trauma management.
Switzerland
Swissmedic regulatory frameworks exceed baseline EU MDR requirements, creating a premium-tier market access pathway for manufacturers with enhanced clinical documentation. Alpine sports medicine clinics in Zurich and Geneva are adopting carbon-fiber reinforced thermoplastic composites for ligament reconstruction protocols. The country's rehabilitation centers anchor premium consumption patterns that prioritize patient mobility metrics in formulary decisions.
Poland
Central European labor cost differentials and proximity to German distribution networks are attracting thermoforming line relocation from Western European facilities. The country's manufacturing corridors around Warsaw and Kraków are scaling elastic fabric knitting infrastructure to serve EU-wide demand. Polish distributors are capturing share in home care channels where smartphone-based fitting applications reduce clinical dependency.
Europe Orthopedic Braces and Support Market Key Industry Players
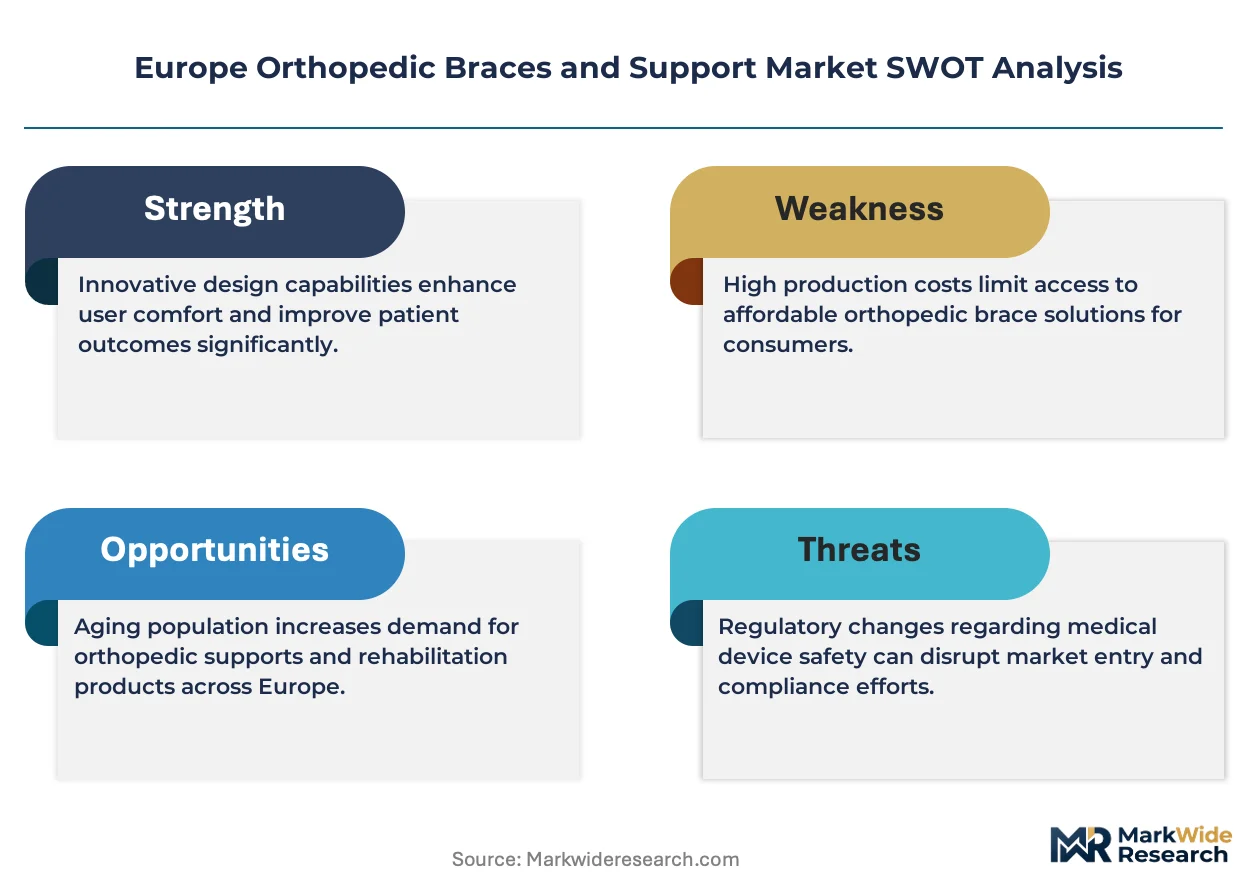
Concentration sits with vertically integrated manufacturers possessing captive regulatory affairs infrastructure and automated production assets. The competitive set compresses as EU MDR transitional deadlines filter legacy products lacking updated technical documentation. Three archetypes dominate: German precision manufacturers with hospital formulary control, Swiss-Alpine sports medicine specialists, and diversified medical technology conglomerates with portfolio breadth. Competitive moves center on manufacturing relocation to Central European cost corridors and digital fitting platform development to reduce clinical visit dependency.
Among Germany-based specialists, DJO Global, medi GmbH & Co. KG, and Bauerfeind AG exemplify distinct positioning vectors. DJO Global represents scale-driven manufacturing with vertically integrated production footprints. medi GmbH & Co. KG occupies a position anchored in specialized medical compression technology. Bauerfeind AG sits within the precision anthropometric fitting tier that controls sports medicine channel access across Alpine markets.
| Leading Market Players |
|---|
| DJO Global |
| medi GmbH & Co. KG |
| Össur |
| Breg Inc. |
| DeRoyal Industries |
| Ottobock |
| Thuasne |
| 3M Company |
| Bauerfeind AG |
| Others |
Cost & Logistics Intelligence
Automated thermoforming line utilization rates above eighty percent in Bavarian manufacturing clusters compress unit costs for custom-fabricated knee braces while elevating price floors for manual cut-and-sew operations. Scale concentration among German producers with captive regulatory affairs infrastructure permits premium pricing on CE-marked post-operative devices, whereas Polish knitting facilities serving basic elastic supports compete on thinner margins.
Pricing Analysis
Hospital procurement consortia anchor pricing stratification across premium, standard, and economy tiers in the Europe orthopedic braces and support landscape. Price differentiation hinges on MDR certification grade and precision anthropometric fitting capability, with carbon-fiber composite variants commanding substantial premiums over neoprene laminates. Pricing pressure stems from framework agreement bundling in England's NHS Supply Chain and Sweden's regional healthcare bodies, which squeezes brand premiums. Home care direct-to-patient channels exhibit highest price sensitivity, while Swiss sports medicine clinics demonstrate lowest sensitivity due to patient mobility metrics driving formulary decisions.
Supply Chain Analysis
Germany and Switzerland anchor precision thermoforming and carbon-fiber composite fabrication for premium hinged braces, while Poland and the Czech Republic scale elastic fabric knitting infrastructure for volume segments. Raw material dependencies center on carbon-fiber prepreg from aerospace suppliers, medical-grade neoprene from petrochemical feedstocks, and biocompatible thermoplastic sheets. Supply chain risk concentrates in single-source carbon-fiber prepreg vulnerability as automotive and aerospace sectors compete for lightweight composite supply. Distribution runs through hospital procurement consortia and direct manufacturer relationships, displacing independent medical supply distributors across Northern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as hospital procurement consortia in Germany, England, and Sweden consolidate brace purchasing through framework agreements that bundle devices with physiotherapy services, fragmenting independent distributor influence.
For Market Incumbents: Compound formulary control through G-BA reimbursement eligibility investments and MDR technical documentation completion ahead of transitional deadlines. Defend margin structures by accelerating thermoforming automation in Polish manufacturing corridors to offset Western European labor costs. Prioritize backward integration into carbon-fiber prepreg supply relationships to mitigate aerospace sector competition for lightweight composite inputs. For New Entrants and Emerging Players: Differentiate on digital fitting convergence by deploying smartphone-based 3D scanning applications that reduce clinical visit dependency for home care channels. Target Poland and Czech Republic manufacturing corridors where labor cost differentials and German distribution proximity enable competitive unit economics. Pursue occupational back support mandates in Swedish and Danish workplace health compliance frameworks as the most penetrable white-space segment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with G-BA statutory health insurance coverage and direct hospital procurement relationships. Long-term viability favors vertically integrated producers with captive regulatory affairs infrastructure and automated thermoforming assets. Monitor EU MDR transitional deadline enforcement as the critical signal for competitive set compression and legacy product filtration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Completion | Filters legacy products lacking clinical evidence for Class I reusable brace classifications. |
| Hospital Procurement Consortium Partnership | Secures volume commitments through England's NHS Supply Chain framework agreements. |
| Thermoforming Line Relocation | Captures Polish labor cost differentials while maintaining German distribution network proximity. |
| Digital Fitting Platform Development | Enables remote brace customization via smartphone-based 3D scanning and cloud prescription. |
| Carbon-Fiber Prepreg Supply Agreement | Insulates premium hinged brace production from aerospace sector demand competition. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU MDR guidance documents, G-BA prosthetics directive rulings, and hospital procurement databases. Primary interviews engaged orthopedic surgeons, hospital purchasing committee members, biomedical engineers specializing in rehabilitation devices, and GPO contracts managers across German, French, and British health systems. Secondary validation drew from notified body conformity assessment records, ANSM vigilance reports, MHRA adverse event databases, and trade flow statistics. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled span product type, end-user setting, material technology, and distribution channel across the projection horizon. Analytical framework derived CAGRs through elasticity analysis of reimbursement expansion, demographic aging trajectories, and sports medicine infrastructure investment. Industry-specific forecast inputs incorporated G-BA coverage eligibility shifts, MDR transitional deadline enforcement patterns, and carbon-fiber composite input cost trajectories.
Forecasts assume regulatory continuity in EU MDR enforcement and G-BA reimbursement frameworks; material policy shifts in notified body capacity or statutory health insurance coverage would require re-modeling. Specific risks include biocompatibility testing backlog delays at EU reference laboratories and orthopedic technician skill scarcity constraining custom-fabricated production scaling. Recalibration cycles align with material shifts in MDR enforcement timing and hospital procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Global Total Knee Replacement Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market