
 Patient Lift Slings Market | 2026-2036
Patient Lift Slings Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Lift Slings Market Outlook
EU MDR is restructuring the cost-of-entry calculus for sling manufacturers serving European healthcare systems, forcing substantial clinical evidence investments for legacy product re-certifications. Arjo leverages its vertically integrated manufacturing footprint across Scandinavia to sustain margin resilience under these compliance burdens. V. Guldmann A/S specializes in ceiling-lift-compatible sling architectures that dominate Northern European hospital retrofit programs. Invacare Corporation anchors North American distribution through durable medical equipment dealer networks, competing on reimbursement navigation rather than product novelty alone.
Patient lift slings are load-bearing textile devices engineered to cradle and transfer mobility-limited individuals between surfaces, typically constructed from polyester, nylon, or mesh fabrics rated for specific weight capacities and incorporating reinforced stitching at stress concentration points. Their primary commercial purpose is eliminating manual lifting injuries among caregivers while preserving patient dignity during transfers in institutional and residential settings. Polyester slings command the largest volume share due to durability and launderability, though mesh slings are capturing faster growth in acute care where infection control protocols demand frequent sterilization cycles. Nursing facilities represent the most concentrated end-user margin pool, as bulk procurement contracts and standardized sling inventories create stickier supplier relationships than fragmented home care purchasing.
FDA 510(k) premarket notification requirements govern sling safety classifications in the United States, while EU MDR and ISO 10535 establish mechanical load testing and biocompatibility benchmarks for European market access. These frameworks collectively elevate R&D fixed costs, advantaging manufacturers with existing regulatory dossiers and clinical trial infrastructure over emerging competitors. Stakeholders must monitor evolving home care reimbursement codes, as shifts toward value-based purchasing for patient handling equipment could redirect volume from institutional buyers toward direct-to-consumer channels with fundamentally different margin and service expectations.
Market Dynamics
EU MDR clinical evidence requirements for legacy sling re-certifications are forcing manufacturers to absorb substantial fixed compliance costs, advantaging incumbents with established regulatory dossiers over emerging competitors seeking European market access.
Growth Catalysts
- Medicare reimbursement codes:US durable medical equipment coverage sustains institutional purchasing volumes for polyester and mesh sling categories across nursing facilities and hospital systems.
- Aging-in-place policy frameworks:Developed healthcare systems in Scandinavia and North America are redirecting long-term care funding toward residential settings, expanding home care provider sling procurement.
- Infection control protocols:Acute care facilities are accelerating sterilization-cycle-compatible mesh sling adoption to satisfy Joint Commission and CDC environmental cleaning standards.
Market Restraints
- Polyester raw material volatility:Petrochemical feedstock price swings compress margin predictability for textile sling manufacturers without backward integration into fiber production.
- EU MDR compliance timeline:Legacy product re-certification deadlines create regulatory friction, forcing clinical trial investments that strain mid-tier manufacturers with limited dossier infrastructure.
- Manual transfer alternatives:Low-acuity care settings in price-sensitive markets retain gait belt and slide sheet protocols, limiting sling penetration in basic mobility assistance segments.
Strategic Opportunities
- US home care channel expansion:Direct-to-consumer and durable medical equipment dealer networks present white space as value-based purchasing redirects volume from institutional buyers.
- Ceiling-lift retrofit programs:Northern European hospital infrastructure upgrades create demand for compatible sling architectures in Denmark, Sweden, and Norway.
- Smart sling sensor integration:Load-monitoring textile electronics are converging with patient lift systems to enable predictive maintenance and usage analytics for facility operators.
Industry Challenges
- Biocompatibility testing capacity:ISO 10535 cytotoxicity and skin sensitization assay bottlenecks extend certification timelines for novel mesh and antimicrobial-coated sling materials.
- Legacy ceiling-lift interoperability:Proprietary hook geometries and sizing standards across installed equipment bases complicate universal sling design and inventory management for multi-site operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Lift Slings Market |
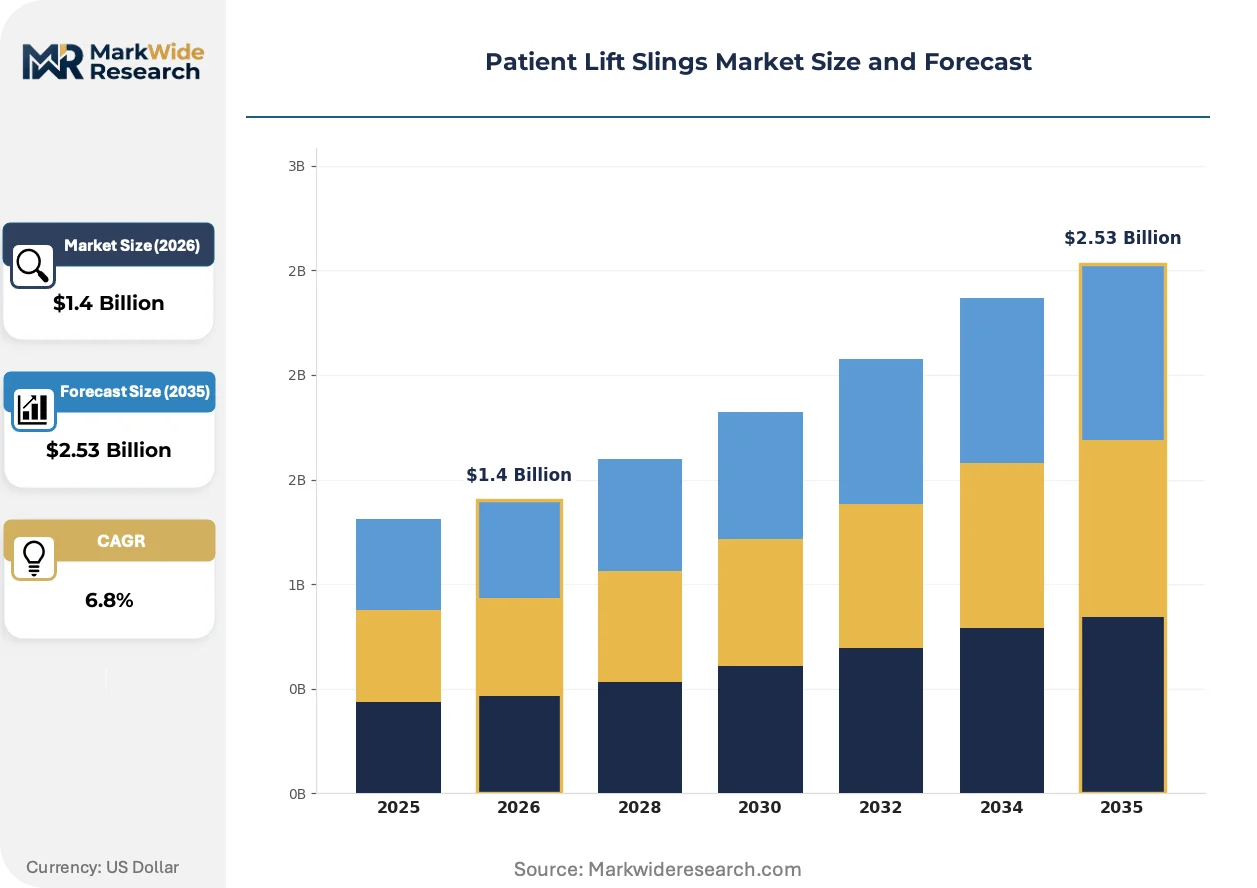
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Slings, Nylon Slings, Cotton Slings, Mesh Slings End User: Hospital, Home Care, Rehabilitation Center, Nursing Facility Design Type: Universal Slings, Transfer Slings, Support Slings, Reclining Slings Weight Capacity: Low Capacity, Medium Capacity, High Capacity, Extra High Capacity |
| Companies Covered | Invacare Corporation, Arjo, Hill-Rom Holdings, Joerns Healthcare, GF Health Products, Drive DeVilbiss Healthcare, V. Guldmann A/S, Medline Industries, Hoyer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Lift Slings Market Strategic Shifts
Textile engineering advances and regulatory digitization are reshaping how sling manufacturers differentiate on safety validation, supply transparency, and patient-specific customization rather than commodity durability alone.
Antimicrobial silver-ion and copper-infused mesh fabrics are converging with standard polyester weaves to reduce nosocomial transmission risk in acute care settings. Hospital infection control committees are mandating these materials for immunocompromised patient transfers. This convergence is compressing the replacement cycle for legacy uncoated slings and elevating supplier qualification requirements.
FDA 510(k) premarket notification pathways are incorporating real-world evidence submissions from post-market surveillance databases, reducing reliance on prospective clinical trials for incremental sling design modifications. This regulatory evolution accelerates iteration cycles for established manufacturers with mature quality management systems. North American suppliers are responding by expanding complaint-handling infrastructure to generate compliant data assets.
Home care agencies are consolidating vendor relationships around full-service patient handling contracts that bundle sling supply with lift maintenance and caregiver training. This purchasing consolidation displaces fragmented spot-buying through durable medical equipment dealers. The shift is most visible in US Medicare Advantage markets where capitated reimbursement rewards equipment standardization across regional networks.
Patient Lift Slings Market Segmentation
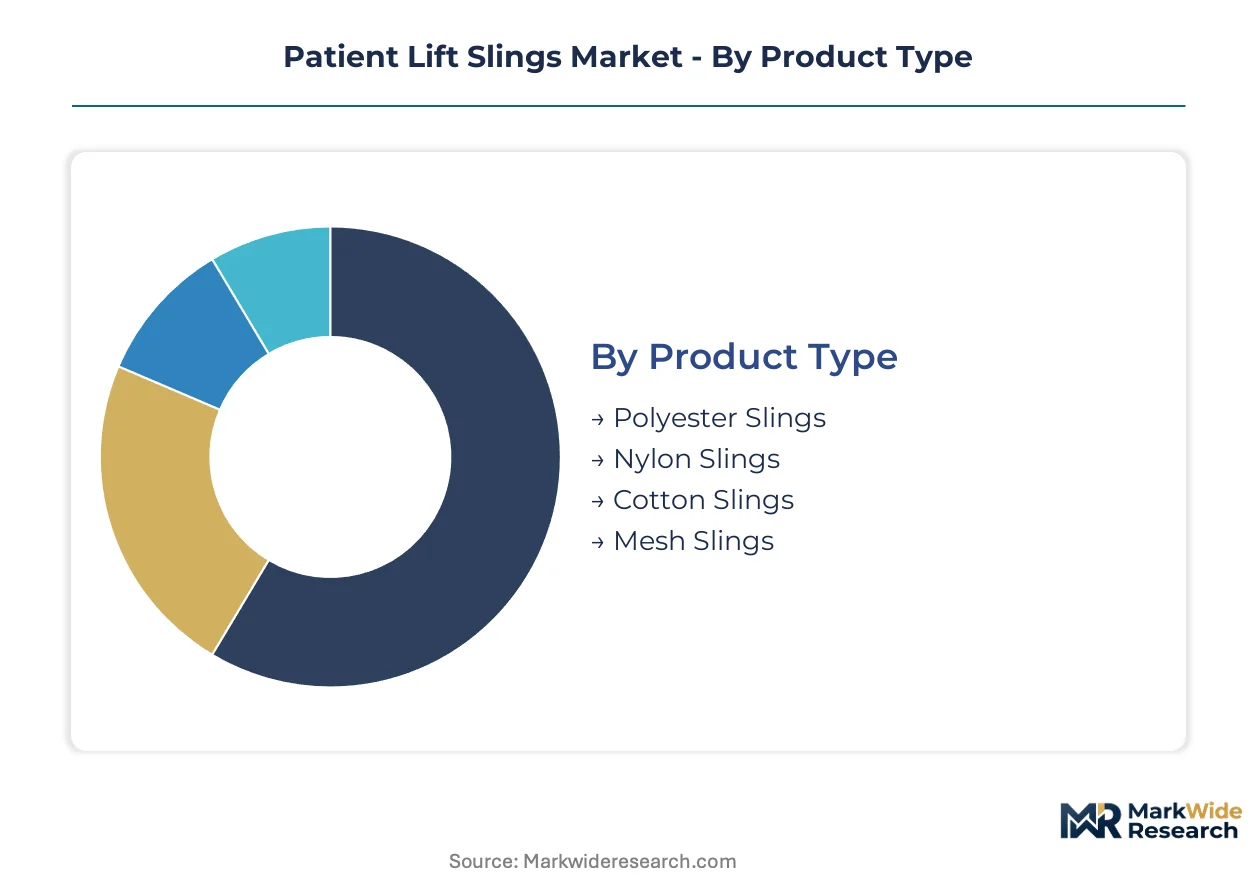
Patient lift sling procurement patterns diverge sharply across material specifications, care settings, and mechanical load requirements. Manufacturers configure product portfolios around these axes to match reimbursement pathways and infection control protocols in target facilities.
Product Type:
Material composition determines laundering protocols, durability cycles, and sterilization compatibility across institutional purchasing categories.
- Polyester Slings:Woven synthetic fabric rated for repeated industrial laundering without tensile degradation. Nursing facilities in the United States concentrate procurement here due to Medicare DME reimbursement durability requirements and bulk contract standardization.
- Mesh Slings:Open-weave textile architecture permitting rapid drying and high-temperature sterilization. Acute care hospitals in Denmark and Sweden are displacing solid-weave alternatives as Joint Commission-aligned infection control protocols mandate shorter sling replacement cycles.
- Nylon Slings:High-strength polymer weave with superior abrasion resistance for bariatric transfer applications. Demand concentrates in specialized obesity care units.
- Cotton Slings:Natural fiber construction for skin-sensitive patients requiring hypoallergenic contact surfaces. Home care providers in Germany favor these for direct-to-consumer channels.
Polyester leads on scale; mesh leads on momentum.
End User:
Facility type shapes volume concentration, pricing tolerance, and service bundling expectations.
- Hospital:Acute care systems with standardized ceiling-lift infrastructure and infection control committees driving antimicrobial mesh specification. Procurement runs through group purchasing organizations with strict biocompatibility documentation requirements.
- Nursing Facility:Long-term care operators with bulk sling inventories and caregiver training programs. These facilities generate the stickiest supplier relationships due to standardized equipment pools and reimbursement-driven cost controls.
- Home Care:Fragmented purchasing through durable medical equipment dealers and direct-to-consumer channels. Aging-in-place policy expansion in Scandinavia and North America is redirecting volume toward residential settings with distinct margin profiles.
- Rehabilitation Center:Short-stay facilities prioritizing rapid patient turnover and versatile sling architectures compatible with multiple lift types.
Nursing facilities anchor procurement volume; home care channels are expanding most quickly.
Design Type:
sling geometry determines compatibility with lift mechanisms and patient positioning requirements.
- Universal Slings:Multi-purpose construction accommodating seated, supine, and standing transfers through adjustable strap configurations. These dominate general ward inventories where sling variety must be minimized.
- Transfer Slings:Minimal-contact design for lateral bed-to-chair movements. Rehabilitation centers specify these for ambulation therapy protocols requiring minimal patient handling time.
- Support Slings:Full-torso cradling architecture for dependent patients with limited trunk control. Bariatric units require reinforced stitching at stress concentration points.
- Reclining Slings:Articulated back support permitting gradual position changes during hoist operation. These align with European hospital retrofit programs for ceiling-lift systems.
Universal slings dominate installed base; reclining variants are gaining share fastest in Northern European retrofit cycles.
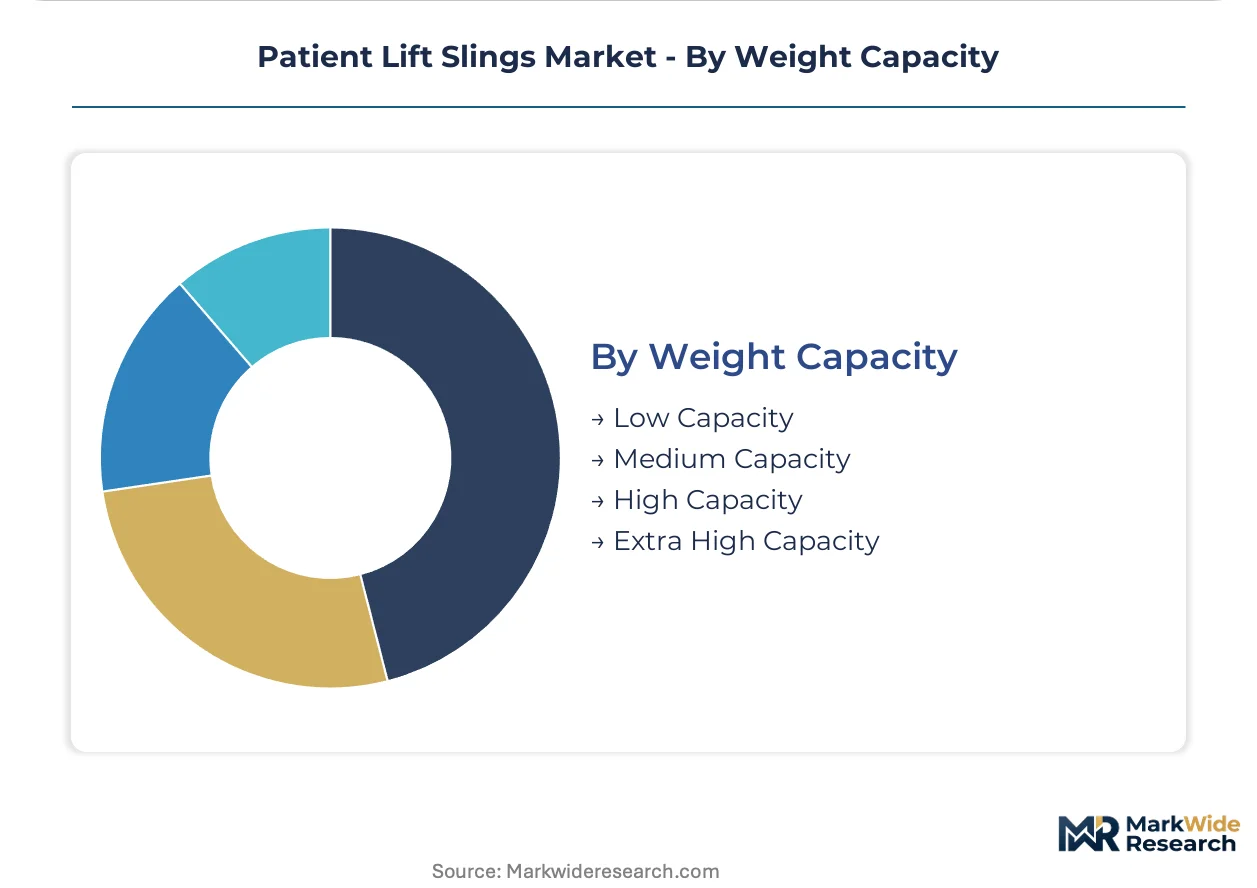
Weight Capacity:
Load rating tiers segment manufacturing complexity, testing protocols, and liability exposure.
- Medium Capacity:Standard-duty construction for patients between typical adult weight thresholds. This tier captures the broadest addressable demand across general care populations.
- High Capacity:Reinforced webbing and extended dimensions for bariatric patients. Acute care facilities in the United States are expanding specification as obesity prevalence drives equipment refresh cycles.
- Low Capacity:Pediatric and small-adult specifications with proportionally scaled hook geometries. Pediatric rehabilitation centers represent concentrated demand.
- Extra High Capacity:Specialized engineering for super-obese patients exceeding standard bariatric thresholds. Manufacturing requires ISO 10535 extended load testing and custom fabrication workflows.
Medium capacity commands volume concentration; high capacity shows the steepest expansion trajectory among institutional buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled nursing workforces in Scandinavia and North America anchor procurement expertise for patient lift sling specification, while acute care clusters in Germany and Japan concentrate ceiling-lift infrastructure investment.
United States
Medicare durable medical equipment reimbursement codes sustain institutional purchasing volumes across nursing facilities and hospital systems. FDA 510(k) premarket notification requirements govern sling safety classifications and elevate compliance costs for new market entrants. The Midwest corridor, particularly Illinois and Ohio, concentrates bulk procurement contracts through group purchasing organizations serving multi-state long-term care operators.
Germany
Home care providers are expanding sling procurement as statutory long-term care insurance redirects funding toward residential settings. BfArM medical device regulations and ISO 10535 compliance frameworks structure market access requirements for textile sling manufacturers. The Rhine-Ruhr metropolitan region anchors distribution networks serving Benelux and Central European acute care systems.
Sweden
Hospital infrastructure retrofit programs are accelerating demand for ceiling-lift-compatible sling architectures in Stockholm and Gothenburg medical centers. EU MDR clinical evidence requirements force substantial fixed compliance investments for legacy product re-certifications. The Medicon Valley cluster spanning Copenhagen-Malmö coordinates Nordic procurement standardization for infection control-compatible mesh sling specifications.
Japan
Super-aging demographics are concentrating demand for home care sling configurations compatible with compact residential lift systems. PMDA and METI medical device regulations establish mechanical load testing and biocompatibility benchmarks for market access. The Kanto region around Tokyo anchors specialized distribution serving geriatric care facilities with high-frequency sling replacement protocols.
Denmark
Public procurement frameworks for municipal home care services are standardizing sling inventories across regional healthcare authorities. Danish Health Authority medical device oversight aligns with EU MDR implementation timelines for legacy product transitions. Aarhus and Odense manufacturing clusters supply Northern European hospital retrofit programs with specialized reclining sling architectures.
Patient Lift Slings Market Competitive Environment
The competitive structure tilts toward vertically integrated European specialists with captive textile production capacity. Incumbents with established regulatory dossiers absorb EU MDR compliance burdens more efficiently than emerging entrants lacking clinical trial infrastructure. Three archetypes dominate: Scandinavian ceiling-lift system integrators, North American durable medical equipment distributors, and diversified hospital bed manufacturers with sling accessories portfolios. Capacity consolidation and strategic partnerships with group purchasing organizations represent the primary competitive vectors.
Among European specialists, Arjo and V. Guldmann A/S exemplify vertically integrated manufacturing archetypes with upstream control over Scandinavian textile production. Invacare Corporation anchors North American distribution positioning through durable medical equipment dealer network relationships. These three entities represent distinct strategic postures: European system integration expertise, North American reimbursement navigation capability, and multi-product hospital equipment bundling respectively.
| Leading Market Players |
|---|
| Invacare Corporation |
| Arjo |
| Hill-Rom Holdings |
| Joerns Healthcare |
| GF Health Products |
| Drive DeVilbiss Healthcare |
| V. Guldmann A/S |
| Medline Industries |
| Hoyer |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FDA 510(k)-cleared institutional slings and unregulated home care alternatives manifests in pricing spreads exceeding three-to-one, with premium tiers commanding bundled service contracts while commodity channels compete on polyester raw material arbitrage from Southeast Asian textile mills.
Pricing Analysis
Bundled service contracts versus unbundled product-only transactions split the market into divergent margin architectures. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10535 certification grade and Medicare DME reimbursement eligibility. Cost compression in the home care channel intensifies because durable medical equipment dealers face reimbursement rate pressure from Medicare Advantage capitation. Nursing facilities show the least price sensitivity due to standardized procurement through group purchasing organizations, while independent home care agencies exhibit acute sensitivity to per-unit sling costs.
Supply Chain Analysis
Freight cost volatility from Southeast Asian polyester fiber suppliers to North American conversion facilities compresses margin predictability for manufacturers lacking captive textile production. Supply concentrates in China, Vietnam, and Bangladesh for woven polyester base fabrics, while Sweden and Denmark host specialized mesh sterilization-compatible finishing. Raw material dependencies span petrochemical feedstocks, industrial sewing thread, and antimicrobial coating chemistries. Single-source vulnerability runs through concentrated polyester fiber suppliers exposed to oil price swings. Distribution runs through group purchasing organizations and durable medical equipment dealer networks serving institutional and residential channels respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Europe run substantially higher than FDA 510(k) pathways in the United States, creating divergent margin structures for manufacturers with regulatory dossier infrastructure in both jurisdictions.
For Market Incumbents: Lock in group purchasing organization contracts through multi-year ceiling-lift service bundling before mid-tier competitors complete EU MDR re-certifications. Threat from emerging mesh sterilization specialists in Denmark demands backward integration into antimicrobial textile finishing. Capacity addition in Vietnam for polyester base fabric production anchors cost position against petrochemical volatility. For New Entrants and Emerging Players: Durable medical equipment dealer networks represent the most penetrable channel for unbundled home care sling sales outside GPO-controlled institutional procurement. White space concentrates in US Medicare Advantage markets where capitated reimbursement rewards equipment standardization. Go-to-market angle: direct-to-consumer cotton sling configurations for skin-sensitive aging-in-place populations in Germany. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR clinical evidence requirements strain mid-tier manufacturers with limited dossier infrastructure. Long-term viability centers on vertically integrated specialists with captive Scandinavian textile production and established FDA 510(k) quality management systems. Acquisition target archetype: ceiling-lift-compatible sling designers with Northern European hospital retrofit relationships. Signal to watch: Medicare reimbursement code shifts toward value-based purchasing for patient handling equipment.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Legacy product re-certification secures continued access to German and Swedish hospital procurement. |
| Ceiling-Lift Retrofit Partnership | Alignment with Stockholm and Copenhagen infrastructure programs captures Northern European specification share. |
| Antimicrobial Mesh Development | Silver-ion coating capabilities satisfy Joint Commission infection control mandates in US acute care. |
| Home Care Channel Expansion | Direct-to-consumer positioning exploits aging-in-place policy funding in Scandinavia and North America. |
| Smart Sling Sensor Integration | Load-monitoring textile electronics enable predictive maintenance contracts with facility operators. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with hospital biomedical engineers, nursing facility procurement directors, durable medical equipment dealer principals, and home care agency operations managers combined with secondary validation against FDA 510(k) filings, CMS Medicare DME reimbursement databases, EU MDR clinical evidence registries, and ISO 10535 testing protocols. Bottom-up facility-level procurement modeling and top-down regional healthcare expenditure triangulation anchored volume estimates.
Segment-weighting approaches distributed total market value across material type, end-user facility, sling design geometry, and weight capacity tier. Projections across the analysis window derived from facility construction pipelines, aging demographic trajectories, and reimbursement policy trajectories. CAGRs were computed from segment-level growth differentials applied to base-year procurement volumes. Industry-specific inputs included hospital infection control committee specification trends and ceiling-lift installation rates in Northern European retrofit programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Medicare reimbursement code revisions, EU MDR enforcement intensity, and petrochemical feedstock price volatility. Forecasts reflect documented assumptions about regulatory timeline adherence and healthcare facility capital expenditure continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Digital Reading Micropipettes Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Sacroiliac Joint Fusion Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Mexican Intraocular Lens Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Self-Injections Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market