
 Global Rheumatoid Arthritis Diagnostic Tests Market | 2026-2036
Global Rheumatoid Arthritis Diagnostic Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rheumatoid Arthritis Diagnostic Tests Market Foresight
Aftermarket service revenue from instrument maintenance and reagent supply contracts is rewriting profitability models for diagnostic manufacturers. Abbott Laboratories leverages its installed base of immunoassay platforms to sustain recurring consumable sales across hospital laboratories. F. Hoffmann-La Roche Ltd. anchors premium positioning through centralized lab automation systems that integrate rheumatoid factor and anti-CCP testing workflows. Thermo Fisher Scientific Inc. competes by extending its research-use-only assay portfolio into clinical validation pipelines.
Rheumatoid arthritis diagnostic tests comprise serological and molecular assays that detect autoantibodies such as rheumatoid factor and anti-cyclic citrullinated peptide in patient serum, typically requiring microplate readers or chemiluminescence analyzers with picogram-level sensitivity to support early intervention decisions. The primary commercial purpose is to differentiate inflammatory arthropathies and stratify patients for disease-modifying therapy selection. Chemiluminescence assays capture the dominant share of routine clinical volume due to throughput advantages, while multiplex assays represent the fastest-expanding category as rheumatologists demand simultaneous quantification of multiple biomarkers from limited sample volumes. Point of care testing remains nascent in rheumatology but attracts development investment aimed at reducing specialist referral delays.
The FDA regulates these devices through premarket notification and laboratory-developed test oversight pathways, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements on class C autoimmune assays. Health Canada's Therapeutic Products Directorate and Japan's PMDA maintain parallel review frameworks that manufacturers must navigate for multi-jurisdiction product registrations. Stakeholders must monitor evolving harmonization efforts between these regimes to anticipate compliance costs and market access timelines.
Market Dynamics
Multiplex serology platforms are compressing diagnostic timelines by enabling simultaneous autoantibody quantification from single serum draws, forcing laboratories to consolidate instrument vendors and renegotiate service contracts around throughput-per-square-meter metrics.
Growth Catalysts
- IVDR Compliance Deadlines:The EU In Vitro Diagnostic Regulation's 2025-2027 staggered enforcement is accelerating laboratory upgrades to certified chemiluminescence systems, pulling forward replacement demand across German and French hospital networks.
- Rheumatology Clinic Consolidation:United States integrated delivery networks are centralizing high-complexity immunology testing into regional reference hubs, concentrating purchasing power and standardizing assay menus.
- Biomarker Panel Expansion:Anti-carbamylated protein antibodies and novel cytokine arrays are entering clinical validation pipelines, extending test menus beyond rheumatoid factor and anti-CCP baselines.
Market Restraints
- Reagent Supply Concentration:Chemiluminescence analyzer consumables depend on three dominant suppliers, creating vulnerability to single-source disruptions for antibodies and detection enzymes.
- Capital Intensity Barriers:Automated immunoassay platforms require $300,000-$800,000 instrument investments, excluding independent rheumatology practices from in-house testing capabilities.
- Reimbursement Compression:United States Medicare's Clinical Laboratory Fee Schedule adjustments are narrowing margins on routine serology panels, pressuring mid-volume laboratories.
Strategic Opportunities
- Point-of-Care Penetration:Fingerstick capillary blood collection devices for rheumatoid factor screening could reduce specialist referral delays in United States rural health clinics and Japanese community hospitals.
- Liquid Biopsy Convergence:Cell-free DNA methylation signatures for inflammatory arthritis stratification are hybridizing with established serology workflows, opening companion diagnostic partnerships with biologic drug developers.
- India's Diagnostic Expansion:The country's PLI scheme for medical device manufacturing is attracting contract manufacturers to produce localized reagent kits for anti-CCP and rheumatoid factor assays.
Industry Challenges
- Cross-Platform Standardization:Harmonization between Abbott, Roche, and Siemens immunoassay platforms remains incomplete, complicating longitudinal patient monitoring across health system transfers.
- Specialized Technologist Shortages:High-complexity immunology laboratories face recruitment gaps for medical laboratory scientists trained in autoantibody interpretation and quality control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rheumatoid Arthritis Diagnostic Tests Market |
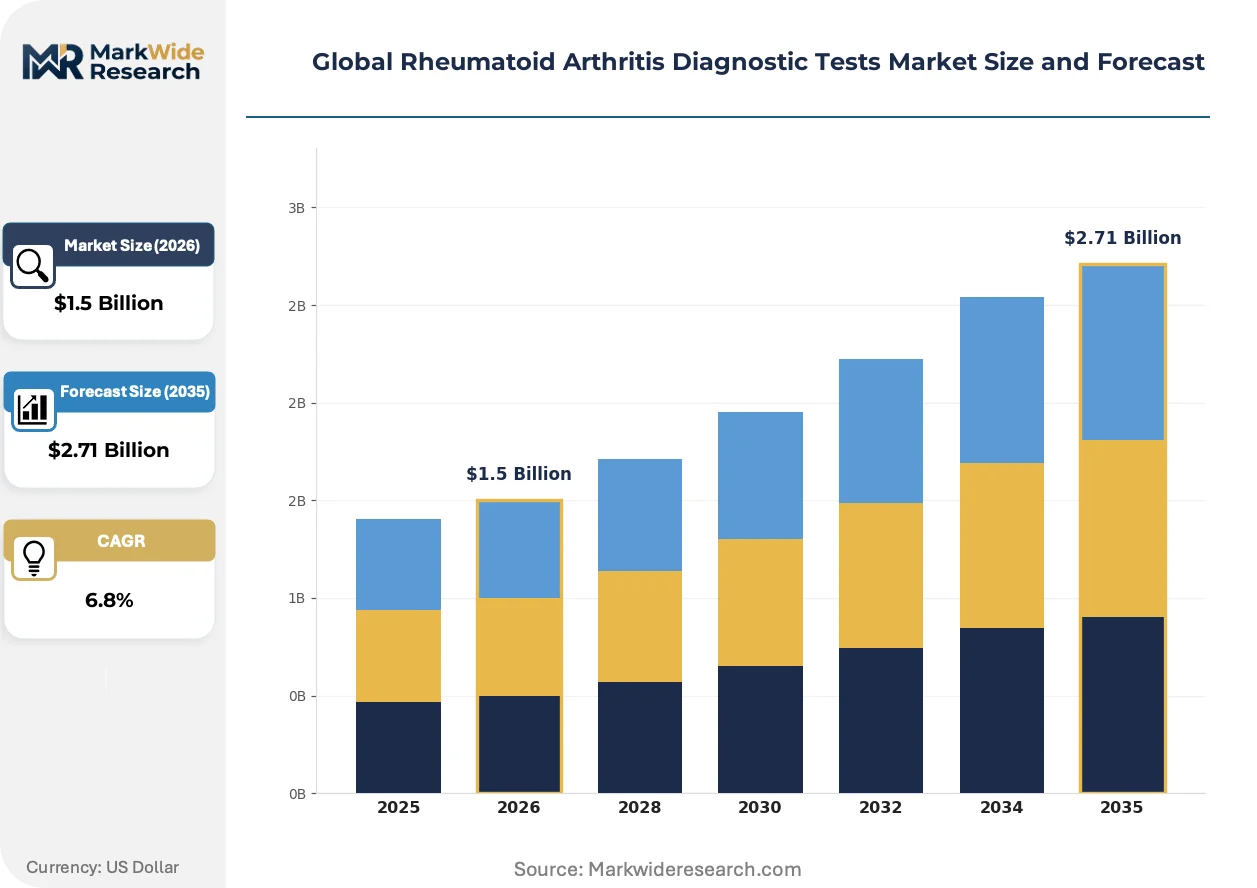
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $2.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme-Linked Immunosorbent Assay, Immunofluorescence Assay, Chemiluminescence Assay, Multiplex Assay, Western Blot Application: Early Diagnosis, Disease Monitoring, Prognostic Assessment, Treatment Response Evaluation End User: Diagnostic Laboratories, Rheumatology Clinics, Research Institutes, Specialized Testing Centers Delivery Mode: Point of Care Testing, Centralized Laboratory Testing, Home Testing Kits, Telehealth Diagnostics |
| Companies Covered | Bio-Rad Laboratories Inc., Exagen Inc., Abbott Laboratories, F. Hoffmann-La Roche Ltd., Augurex Life Sciences Corp., Siemens Healthineers AG, Danaher Corporation, Svar Life Science, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rheumatoid Arthritis Diagnostic Tests Market Shifts & Advancements
Diagnostic manufacturers are repositioning around software-integrated assay ecosystems rather than discrete test sales, embedding artificial intelligence interpretive tools directly into analyzer operating systems to differentiate hardware commoditization.
Multiplex bead-based immunoassays are hybridizing chemiluminescence sensitivity with flow cytometry throughput, enabling rheumatology clinics to profile ten-plus biomarkers from fifty microliters of serum. Large United States academic medical centers are adopting these platforms for research-to-clinic translation, compressing the validation timeline from investigational use to reimbursable testing. The technology is hybridizing previously separate autoimmune and infectious disease testing workflows into unified instrument footprints.
The FDA's evolving laboratory-developed test oversight framework is forcing molecular assay developers to choose between full premarket submission pathways or partnership with certified reference laboratories. This regulatory friction is delaying novel biomarker commercialization timelines by eighteen to thirty-six months for assays targeting early rheumatoid arthritis detection. Smaller diagnostic firms are responding by prioritizing European CE-IVDR certification first, using notified body approvals to support subsequent United States dossier preparation.
Hospital procurement committees are consolidating vendor relationships through enterprise-wide reagent rental agreements that bundle instrument placement, maintenance, and consumable supply into per-test pricing. United States health systems with over five hundred beds are displacing transactional purchasing with multi-year partnerships that lock in volume commitments and service-level agreements. This contractual evolution is most visible in the southeastern United States, where hospital network mergers have concentrated laboratory spending authority into centralized supply chain functions.
Global Rheumatoid Arthritis Diagnostic Tests Market Segmentation
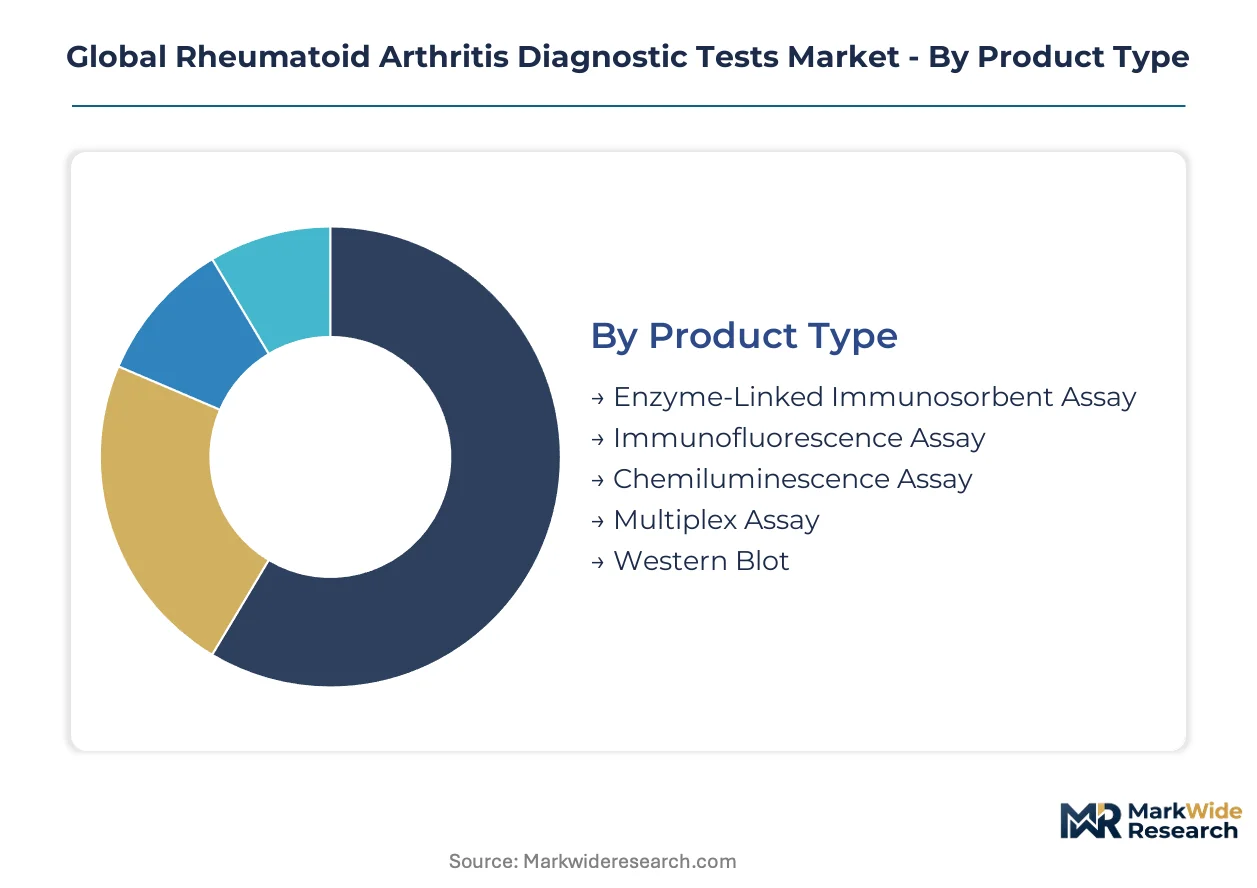
Segmentation in rheumatoid arthritis diagnostics reveals how testing workflows fragment across technology platforms and care settings. Manufacturers calibrate instrument portfolios and reagent pricing to match the service intensity each segment demands.
Product Type:
After-sales service intensity varies sharply across immunoassay platforms, with automated systems demanding multi-year maintenance contracts while manual methods require minimal vendor support.
- Chemiluminescence Assay:Fully automated analyzers detect autoantibodies through light-emitting reactions with picogram-level sensitivity. Demand concentrates in United States urban hospital networks where integrated health systems centralize high-throughput immunology testing and negotiate enterprise reagent rental agreements.
- Multiplex Assay:Bead-based platforms simultaneously quantify ten-plus biomarkers from fifty microliter serum samples. Rheumatology clinics across Germany and Japan are adopting these systems to compress diagnostic timelines and consolidate instrument footprints.
- Enzyme-Linked Immunosorbent Assay:Microplate-based colorimetric detection remains prevalent in resource-limited settings for rheumatoid factor screening.
- Immunofluorescence Assay:Manual microscopy methods persist in smaller diagnostic laboratories with limited capital budgets.
- Western Blot:Confirmatory testing for atypical autoantibody profiles supports research-to-clinic translation at academic medical centers.
Chemiluminescence Assay holds the largest share; momentum sits with Multiplex Assay.
Application:
Clinical utility determines reimbursement coding and influences whether laboratories invest in specialized technologist training for complex interpretation protocols.
- Early Diagnosis:Detection of anti-cyclic citrullinated peptide and rheumatoid factor in pre-symptomatic patients enables disease-modifying therapy initiation. United States rheumatology clinics prioritize this application to reduce joint damage progression and qualify patients for biologic drug coverage.
- Disease Monitoring:Serial autoantibody quantification tracks inflammatory activity and therapeutic efficacy over multi-year treatment courses.
- Prognostic Assessment:Biomarker stratification identifies patients at risk for aggressive erosive disease requiring intensive intervention.
- Treatment Response Evaluation:Post-therapeutic antibody profiling guides switching between conventional and biologic disease-modifying agents.
Early Diagnosis commands premium pricing; Disease Monitoring generates the most recurring test volume.
End User:
Procurement authority concentrates differently across settings, with hospital networks wielding enterprise purchasing power versus independent clinics negotiating transactional reagent supply.
- Diagnostic Laboratories:High-complexity reference hubs process thousands of autoimmune panels daily using automated chemiluminescence platforms. Germany's hospital networks are consolidating testing into regional laboratories to achieve IVDR compliance economies.
- Rheumatology Clinics:Specialist practices demand rapid turnaround for same-day clinical decision-making.
- Research Institutes:Academic centers validate novel biomarkers before clinical translation.
- Specialized Testing Centers:Focused autoimmune facilities serve underserved regions with courier-collected specimens.
Diagnostic Laboratories absorb the majority of instrument placements; Rheumatology Clinics are expanding fastest as point-of-care capabilities mature.
Delivery Mode:
Capital requirements and regulatory pathways diverge substantially between centralized infrastructure and distributed testing models.
- Centralized Laboratory Testing:Hub-and-spoke models aggregate specimens from multiple collection sites into automated high-throughput facilities. Japanese health systems favor this mode to maintain quality control consistency across prefectural networks.
- Point of Care Testing:Fingerstick capillary collection devices aim to reduce specialist referral delays in rural United States clinics.
- Home Testing Kits:Direct-to-consumer serology remains limited by regulatory scrutiny and result interpretation complexity.
- Telehealth Diagnostics:Remote specimen collection with digital result delivery supports post-pandemic care models.
Centralized Laboratory Testing dominates current revenue; Point of Care Testing attracts the steepest development investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for rheumatoid arthritis diagnostic tests varies sharply by healthcare system structure. Germany and Japan exhibit low elasticity due to statutory reimbursement guarantees, while India and Brazil face acute cost constraints that favor manual ELISA methods over automated platforms.
United States
Integrated delivery networks in Texas and Florida are consolidating high-complexity immunology testing into regional reference hubs. The FDA's evolving laboratory-developed test oversight is forcing molecular assay developers toward full premarket submission pathways. Hospital procurement committees in the Southeast negotiate enterprise-wide reagent rental agreements that bundle instrument placement with per-test pricing.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are accelerating laboratory upgrades to meet IVDR 2025-2027 compliance deadlines. The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements on class C autoimmune assays, pulling forward replacement demand for certified chemiluminescence systems. Regional reference laboratories in Munich and Düsseldorf are standardizing multiplex serology menus.
Japan
Prefectural health systems favor centralized laboratory testing to maintain quality control consistency across rheumatology networks. The PMDA maintains parallel review frameworks that manufacturers navigate alongside FDA and EU registrations. Tokyo and Osaka academic medical centers adopt bead-based multiplex platforms for research-to-clinic translation of novel biomarker panels.
India
The PLI scheme for medical device manufacturing is attracting contract manufacturers to produce localized reagent kits for anti-CCP and rheumatoid factor assays. CDSCO regulatory pathways remain less burdensome than FDA premarket notification, enabling faster commercialization of validated assays. Diagnostic expansion concentrates in Maharashtra and Karnataka, where private laboratory chains build regional immunology hubs.
United Kingdom
NHS England's consolidation of specialized testing into designated autoimmune centers is concentrating purchasing authority for high-throughput platforms. The Medicines and Healthcare products Regulatory Agency aligns with EU IVDR standards post-Brexit, maintaining dual compliance burdens for manufacturers. London and Manchester rheumatology clinics demand rapid turnaround times that favor automated chemiluminescence over manual methods.
Global Rheumatoid Arthritis Diagnostic Tests Market Competitive Landscape
Capability concentration sits with specialized autoimmune diagnostics developers; scale advantage sits with diversified life science conglomerates. The market structures around three tiers: multinational platform vendors with installed base leverage, mid-cap specialists with biomarker IP, and emerging point-of-care developers. Strategic moves center on reagent rental agreements that lock in multi-year consumable commitments, and multiplex assay portfolios that consolidate previously separate testing workflows.
Among diversified diagnostics conglomerates, Abbott Laboratories, F. Hoffmann-La Roche Ltd., and Thermo Fisher Scientific Inc. occupy positions defined by instrument platform breadth and recurring revenue from consumable supply contracts. These entities exemplify the scale-driven tier where aftermarket service revenue rewrites profitability models. Mid-cap specialists such as Bio-Rad Laboratories Inc. and Exagen Inc. represent capability-focused archetypes anchored in specific autoimmune biomarker expertise and research-use-only assay development pipelines.
| Leading Market Players |
|---|
| Bio-Rad Laboratories Inc. |
| Exagen Inc. |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Augurex Life Sciences Corp. |
| Siemens Healthineers AG |
| Danaher Corporation |
| Svar Life Science |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
Single-source reagent dependency for chemiluminescence antibodies and detection enzymes compresses both margin structures and procurement flexibility across hospital laboratory networks. This concentration vector forces tiered pricing spreads between premium automated platforms and manual ELISA alternatives while shaping geographic sourcing strategies around IVDR-certified manufacturing sites.
Pricing Analysis
After-sales service contracts and consumable supply agreements generate lifetime value exceeding instrument placement revenue by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels separates enterprise reagent rental bundles from transactional per-test pricing and bare-bones manual assay kits. Cost compression in mid-volume laboratory tiers is intensifying because Medicare Clinical Laboratory Fee Schedule adjustments narrow routine panel margins. Independent rheumatology practices exhibit highest price sensitivity due to capital intensity barriers excluding them from automated platform acquisition.
Supply Chain Analysis
Contract manufacturing for diagnostic reagents concentrates among specialized biotechnology foundries in Germany, Ireland, and Singapore with ISO 13485-certified antibody production capabilities. Supply chains draw from recombinant protein expression systems, magnetic microparticle substrates, and chemiluminescent substrate cocktails as critical inputs. Single-source vulnerability persists for horseradish peroxidase conjugates and proprietary bead chemistries locked to specific analyzer platforms. Distribution runs through regional reference laboratory hubs that aggregate specimens from satellite collection sites into consolidated reagent consumption pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with point-of-care and multiplex assay segments where rheumatology clinic consolidation and biomarker panel expansion create specialized niches underserved by centralized laboratory conglomerates.
For Market Incumbents: Build installed-base moats through enterprise reagent rental agreements that lock hospital networks into multi-year consumable commitments and service-level guarantees. Deepen backward integration into proprietary antibody production to insulate against single-source reagent disruptions. Counter emerging point-of-care developers by accelerating FDA premarket notification pathways for fingerstick-capable platforms before regulatory friction delays competitor commercialization. For New Entrants and Emerging Players: Pursue white-space penetration in United States rural health clinics and Japanese community hospitals where specialist referral delays create demand for rapid rheumatoid factor screening. Target India's diagnostic expansion under PLI scheme incentives for localized anti-CCP reagent manufacturing. Enter through research-use-only assay partnerships with academic medical centers that compress validation timelines toward clinical translation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biomarker IP specialists with multiplex serology platforms and point-of-care development pipelines. Long-term viability centers on companion diagnostic positioning alongside biologic drug developers as liquid biopsy convergence reshapes inflammatory arthritis stratification. Watch FDA laboratory-developed test oversight evolution as inflection signal determining whether molecular assay developers require full premarket submissions or retain reference laboratory partnership pathways.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Prioritization | European notified body approvals accelerate subsequent FDA dossier preparation timelines for novel biomarker assays. |
| Multiplex Assay Portfolio Expansion | Bead-based platforms consolidate previously separate autoimmune and infectious disease testing workflows into unified instrument footprints. |
| Point-of-Care Development Investment | Fingerstick capillary collection devices address specialist referral delays in underserved United States rural and Japanese community settings. |
| Enterprise Reagent Rental Agreements | Per-test pricing bundles lock hospital networks into multi-year volume commitments and aftermarket service revenue streams. |
| Companion Diagnostic Partnership | Cell-free DNA methylation signatures for inflammatory arthritis stratification open biologic drug developer alliances. |
Research Methodology
The analysis maps chemiluminescence assay, multiplex platform, and point-of-care technology sub-sectors, each validated through rheumatology clinic administrators, hospital laboratory directors, diagnostic manufacturer product managers, and GPO contracts specialists. Primary interview insights triangulate against FDA 510(k) filings, EU IVDR notified body approvals, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up instrument placement and reagent consumption estimates reconcile with top-down healthcare expenditure flows across the analysis window.
Forecast assumptions hold IVDR compliance deadlines and Medicare fee schedule trajectories as fixed boundary conditions while varying biomarker panel adoption rates and point-of-care penetration scenarios. Segmentation dimensions span technology platform, application purpose, end-user setting, and delivery mode. CAGRs derive from logistic diffusion curves fitted to historical platform replacement cycles and projected menu expansion timelines. Forecast inputs incorporate rheumatology clinic consolidation rates and health system centralization of high-complexity immunology testing.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, diagnostic capital expenditure cycles, or biologic drug pipeline approvals would shift the trajectory. Quarterly review of FDA laboratory-developed test guidance evolution and IVDR certification completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Breast Cancer Diagnostics Market
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Netherlands in-Vitro Diagnostics Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
Inflammatory Markers Market