
 United States Marine Composites Market | 2026-2036
United States Marine Composites Market Size, Share, and Industry Trends Forecast 2026-2036
United States Marine Composites Market Intelligence
Out-of-autoclave curing and resin infusion molding is tilting production economics toward larger, more complex marine structures without the scale limitations of traditional oven-based fabrication. Owens Corning leverages its glass fiber supply chain dominance to anchor pricing power across recreational boat hull production. Hexcel Corporation specializes in aerospace-grade carbon fiber translation, extending its prepreg expertise into high-performance naval and racing yacht segments. Gurit competes through integrated kit supply and vacuum infusion tooling systems that reduce yard-level labor hours.
Marine composites encompass fiber-reinforced polymer systems engineered with glass, carbon, or aramid reinforcement bound by thermosetting epoxy, vinyl ester, or polyester matrices, typically achieving strength-to-weight ratios exceeding steel by factors of three to five while eliminating corrosion fatigue in saltwater immersion. Their primary purpose is to reduce vessel mass, extend hull life, and enable geometrically complex designs impossible in aluminum or steel. Glass fiber reinforced plastics occupy the volume leadership position across recreational and commercial boat hulls due to cost accessibility and established repair infrastructure. Carbon fiber penetration is accelerating fastest in naval vessels and high-end racing craft where operational efficiency and radar signature reduction justify premium material outlays. Foam core sandwich configurations command concentrated margin pools in superyacht and offshore structure applications where insulation and panel stiffness drive specification.
Coast Guard structural fire protection standards and EPA Clean Air Act marine engine emission regulations jointly elevate composite fire-retardancy and smoke-toxicity requirements, forcing reformulation of resin systems and additive packages. OSHA workplace exposure limits on styrene during open-mold lamination are pushing yards toward closed-mold infusion processes with higher capital barriers. Stakeholders must monitor evolving Department of Defense specifications for next-generation unmanned surface vessels, where payload fraction and signature control will determine composite specification intensity ahead of program commitments.
Market Dynamics
Defense procurement programs are tilting hull and superstructure specifications toward carbon fiber systems, compressing qualification timelines for yard-level suppliers while EPA vessel emission standards simultaneously tighten resin formulation requirements.
Growth Catalysts
- Out-of-autoclave curing:Resin infusion molding eliminates oven scale limitations, enabling larger single-piece hull sections without capital-intensive autoclave infrastructure.
- EPA Clean Air Act marine engine standards:Emission regulations are forcing hull weight reduction to offset engine compliance penalties, accelerating composite substitution for steel.
- Gulf Coast shipbuilding corridor:Concentrated demand from Texas through Florida creates localized supply cluster economies and specialized labor pools.
Market Restraints
- Styrene price volatility:Polyester and vinyl ester resin feedstock costs fluctuate with petrochemical cycles, squeezing open-mold yard margins.
- Carbon fiber supply concentration:Aerospace-grade fiber capacity concentrates among limited producers, creating allocation risk for naval programs.
- OSHA styrene exposure limits:Workplace regulations are forcing capital conversion from open-mold to closed-mold infusion, raising entry barriers for small fabricators.
Strategic Opportunities
- Unmanned surface vessels:Department of Defense next-generation programs prioritize payload fraction and radar signature, creating specification intensity for advanced composites.
- Foam core sandwich configurations:Superyacht and offshore structure applications offer concentrated margin pools where insulation and panel stiffness drive premium specification.
- Closed-mold process conversion:Vacuum infusion tooling systems reduce yard-level labor hours while improving laminate consistency and environmental compliance.
Industry Challenges
- Certified laminator shortage:Skilled technicians capable of naval-grade prepreg layup and infusion execution remain scarce along the Gulf Coast.
- Fire-retardant resin reformulation:Coast Guard structural fire protection standards require additive package redevelopment, extending qualification timelines.
- Legacy repair infrastructure:Established glass fiber repair networks lack carbon fiber damage assessment and restoration capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Marine Composites Market |
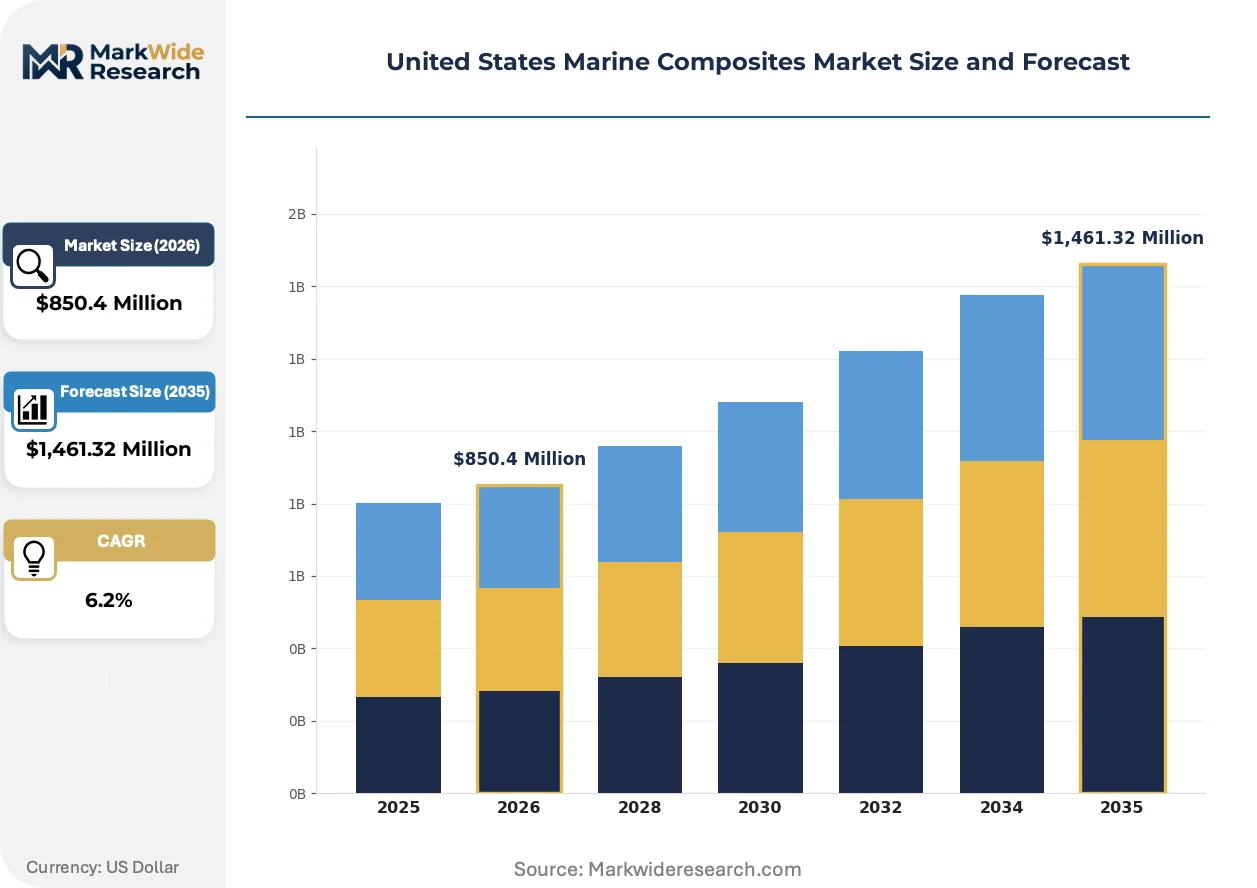
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,461.32 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Plastics, Foam Composites, Hybrid Composites, Thermosetting Composites End User: Commercial Vessels, Recreational Boats, Naval Vessels, Offshore Structures Application: Boat Hulls, Decks, Interiors, Structural Components Material: Glass Fiber, Carbon Fiber, Aramid Fiber, Others |
| Companies Covered | Owens Corning, Hexcel Corporation, DuPont, Toray Industries, Gurit, Cytec Solvay Group, Teijin Limited, Arkema, Huntsman Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Marine Composites Market Strategic Shifts & Innovations
Digital process control and automated fiber placement are compressing production variance while regulatory pressure on vessel emissions is forcing material specification upgrades across hull categories.
Automated fiber placement with in-situ thermoplastic consolidation is digitizing lamination quality documentation and reducing ply misalignment errors in complex hull geometries. Naval shipyards and racing yacht builders are adopting these systems fastest, compressing skilled labor requirements while enabling repeatable precision in radar-signature-critical surfaces.
EPA vessel emission standards and Coast Guard fire safety regulations are jointly elevating smoke-toxicity and flame-spread requirements for resin systems. Hull and superstructure laminates now require intumescent coatings or inherent fire-retardant chemistry, forcing reformulation of established vinyl ester and epoxy platforms and extending material qualification cycles.
Specification-driven procurement is consolidating buyer power among defense prime contractors and superyacht builders, displacing traditional spot-market resin purchasing. Tier-one yards now demand integrated kit supply with certified traceability, compressing margins for undifferentiated commodity fabricators while rewarding suppliers with vacuum infusion tooling and engineering services.
United States Marine Composites Market Segmentation
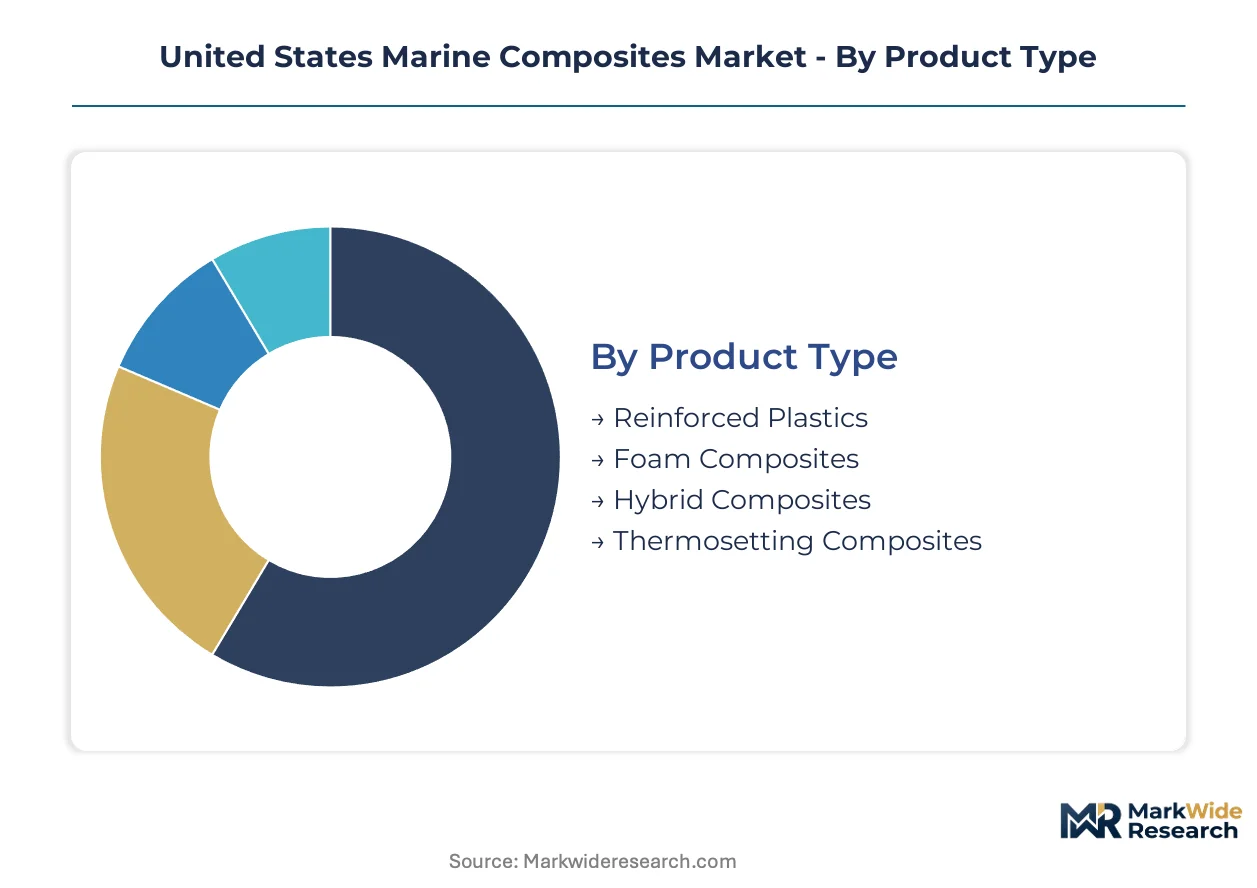
Segmentation in the United States marine composites market reveals how material specifications diverge across defense, commercial, and recreational procurement channels. Each dimension—product chemistry, end-use mission profile, structural application, and fiber reinforcement—carries distinct qualification barriers and aftermarket service requirements that shape supplier economics.
Product Type:
After-sales service intensity varies sharply across product categories, with thermosetting systems demanding periodic requalification of resin batches and hybrid configurations requiring specialized inspection protocols for bond-line integrity.
- Reinforced Plastics:Glass fiber reinforced polymer systems dominate recreational hull production with established repair networks along the Gulf Coast. Demand concentrates in Florida sport fishing boats where blister resistance and gelcoat compatibility drive specification.
- Foam Composites:Sandwich configurations with PVC or SAN cores deliver panel stiffness at reduced mass for superyacht superstructures. Texas and Louisiana offshore fabrication yards specify these for helidecks and accommodation modules where thermal insulation adds value.
- Hybrid Composites:Glass-carbon hybrid laminates balance cost and performance in naval patrol craft. Gulf Coast military shipyards utilize these for mission bay structures requiring damage tolerance.
- Thermosetting Composites:Epoxy and vinyl ester systems cured via vacuum infusion achieve Class-A surface finishes for racing yachts. California and Rhode Island custom builders specify these for America's Cup and grand prix programs.
By volume, reinforced plastics leads. By growth pace, foam composites is ahead.
End User:
Customer procurement sophistication spans from spot-market resin purchasing in recreational boatbuilding to multi-year defense contracts with certified traceability requirements.
- Commercial Vessels:Workboats and ferry operators prioritize life-cycle cost over initial outlay, specifying glass fiber hulls with 25-year fatigue ratings. Gulf Coast operators driving Louisiana offshore supply vessels represent concentrated demand.
- Recreational Boats:Production boatbuilders in Florida and the Great Lakes specify commodity-grade laminates with rapid open-mold throughput. Price sensitivity here compresses margins for undifferentiated fabricators.
- Naval Vessels:Department of Defense programs for unmanned surface vessels and littoral combat ships mandate carbon fiber prepreg with radar signature control. Mississippi and Virginia shipyards anchor this specification tier.
- Offshore Structures:Oil platform modules and wind turbine service vessels require fire-retardant chemistry meeting Coast Guard structural fire protection standards. Texas fabrication yards dominate this specification.
Recreational boats holds volume leadership. Naval vessels claims the steepest expansion trajectory.
Application:
Structural loading conditions and environmental exposure determine fiber architecture and resin selection across marine assemblies.
- Boat Hulls:Primary load-bearing shells require biaxial and quadaxial glass fabrics with vinylester skin coats for osmotic blister prevention. Gulf Coast production lines specialize in 40-60 foot hull molds.
- Decks:Secondary structures utilize lighter laminates with non-skid surfacing integrated during molding. Florida center console and bay boat builders drive specification for integrated hardtops and casting platforms.
- Interiors:Cabin liners and furniture substrates employ lower-modulus laminates with cosmetic gelcoat finishes. California yacht finishers supply this segment with custom fabrication services.
- Structural Components:Bulkheads, stringers, and engine beds demand engineered laminates with calculated fiber orientation for point-load distribution. Naval shipyards in Mississippi specify these with shock-qualified architectures.
Hulls dominate by installed volume. Structural components is climbing the fastest on defense program intensity.
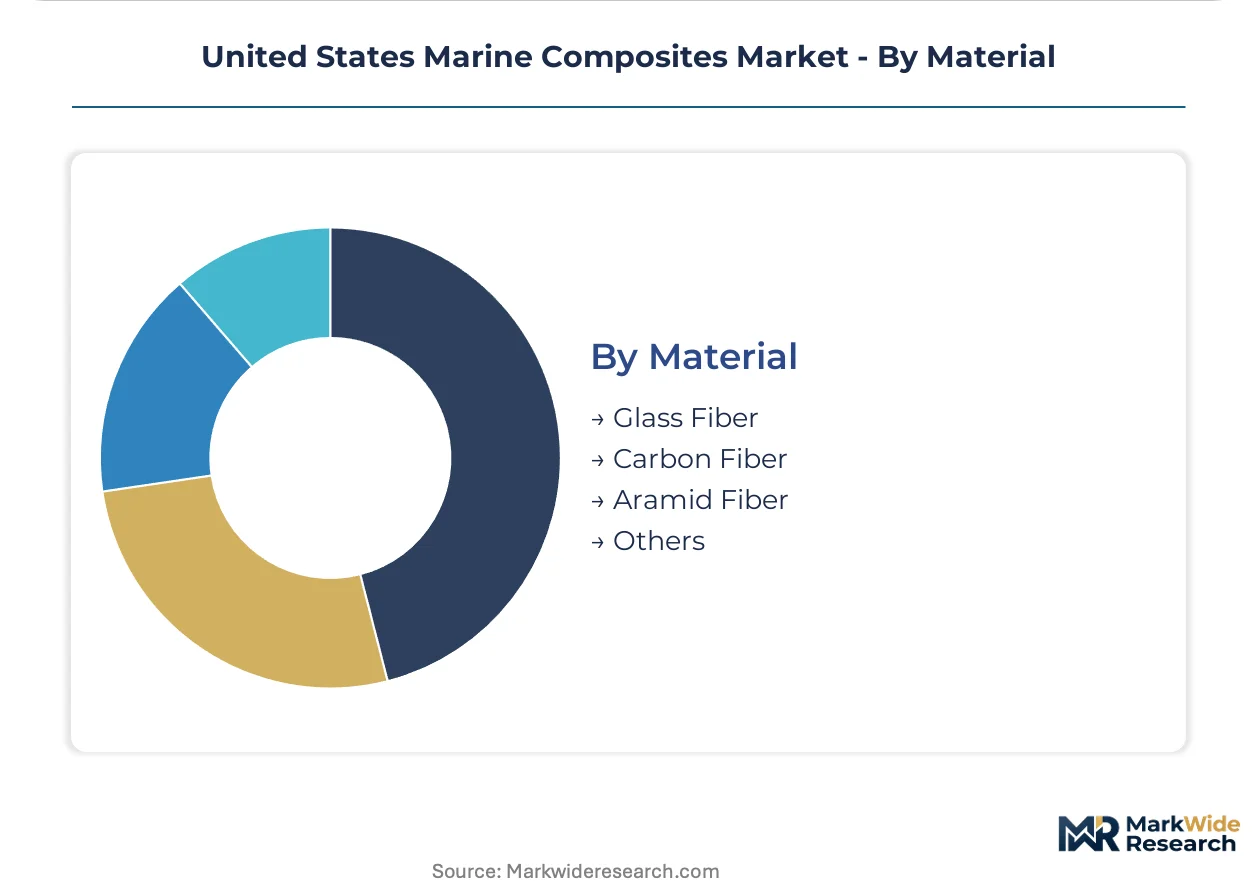
Material:
Fiber selection locks in performance ceiling and dictates downstream repair infrastructure requirements.
- Glass Fiber:E-glass and S-glass rovings supply cost-accessible reinforcement for volume boatbuilding. Owens Corning's Texas manufacturing complex anchors domestic supply security.
- Carbon Fiber:Aerospace-grade PAN-based fibers enable mass reduction and signature control in naval and racing applications. Hexcel Corporation's Salt Lake City facility supplies prepreg to West Coast racing programs.
- Aramid Fiber:Kevlar and Twaron hybrids provide ballistic and impact resistance for military craft. Limited adoption outside patrol boat armor panels constrains segment scale.
- Others:Basalt and natural fiber reinforcements occupy niche sustainability-driven specifications. Experimental adoption in Maine wooden boat restoration circles signals emerging interest.
Glass fiber leads by tonnage consumed. Carbon fiber is gaining share fastest on defense procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast fabricators export hull modules to Caribbean yacht builders and defense contractors along the Atlantic seaboard, creating a north-south trade corridor that concentrates specialized laminator talent from Texas to Virginia.
Southeast (Florida/Georgia)
Florida's recreational boatbuilders drive glass fiber consumption for center console and sport fishing hulls. EPA Clean Air Act marine engine standards push hull weight reduction to offset emission compliance penalties. Miami-Fort Lauderdale yacht finishing clusters specialize in superyacht composite superstructures.
Gulf South (Texas/Louisiana)
Offshore supply vessel operators and oil platform fabricators specify fire-retardant foam core sandwich panels. Coast Guard structural fire protection standards mandate intumescent coatings and smoke-toxicity compliant resin systems. Houston-Galveston shipyards anchor military patrol craft construction for Department of Defense programs.
Mid-Atlantic (Virginia/Mississippi)
Naval shipyards in Pascagoula and Newport News specify carbon fiber prepreg for littoral combat ships and unmanned surface vessels. Department of Defense next-generation programs prioritize radar signature control and payload fraction optimization. Mississippi Gulf Coast military facilities concentrate shock-qualified laminate fabrication.
Pacific Coast (California/Rhode Island)
Custom racing yacht builders specify aerospace-grade thermosetting systems for America's Cup and grand prix programs. OSHA styrene exposure limits accelerate closed-mold vacuum infusion adoption among West Coast custom fabricators. Newport and San Diego marine design studios engineer complex hull geometries for performance sailing craft.
United States Marine Composites Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where raw material suppliers, prepreg converters, and integrated kit providers occupy distinct margin positions. Glass fiber supply concentrates among chemical conglomerates with petrochemical integration, while carbon fiber capacity remains constrained among aerospace-grade producers. Three archetypes dominate: upstream resin and fiber manufacturers, midstream prepreg and core material specialists, and downstream vacuum infusion tooling integrators. Capacity expansion and strategic partnerships represent the primary competitive vectors as yards demand certified traceability and engineering services alongside commodity supply.
Among integrated material suppliers, Owens Corning exemplifies the glass fiber supply chain anchor position, while Hexcel Corporation occupies the aerospace-grade carbon fiber translation tier. Gurit represents the vacuum infusion tooling and kit supply archetype that reduces yard-level labor hours through integrated engineering services.
| Leading Market Players |
|---|
| Owens Corning |
| Hexcel Corporation |
| DuPont |
| Toray Industries |
| Gurit |
| Cytec Solvay Group |
| Teijin Limited |
| Arkema |
| Huntsman Corporation |
| Others |
Cost & Logistics Intelligence
Carbon fiber precursor supply concentrates among Japanese and U.S. aerospace-grade producers, anchoring premium pricing power in naval and racing yacht segments while compressing margins for yards locked into spot-market glass fiber purchasing. This upstream concentration funnels margin pools toward prepreg converters with certified Department of Defense traceability, leaving commodity laminators exposed to styrene cost volatility.
Pricing Analysis
Open-mold glass fiber laminates, vacuum-infused thermosetting systems, and aerospace-grade carbon fiber prepreg occupy distinct pricing tiers separated by certification intensity and performance specifications. Price differentiation rests on Coast Guard fire-safety qualification status and Department of Defense traceability requirements, with naval-grade carbon fiber commanding substantial premiums over recreational boatbuilding commodities. Pricing pressure stems from OSHA styrene exposure regulations forcing capital conversion to closed-mold infusion, raising fixed costs for smaller fabricators. Recreational boatbuilders in Florida exhibit the highest price sensitivity, while Mississippi naval shipyards prioritize payload fraction and signature control over unit cost.
Supply Chain Analysis
ITAR and EAR export controls restrict aerospace-grade carbon fiber flows from U.S. and Japanese facilities to qualified defense contractors, creating allocation bottlenecks for naval programs. Raw material sourcing draws from Texas petrochemical complexes for vinyl ester resins, Japanese precursor facilities for PAN-based carbon fibers, and Owens Corning's Texas glass fiber manufacturing complex. Single-source vulnerability concentrates in aerospace-grade carbon fiber capacity, where qualified alternative suppliers remain limited. Distribution runs through integrated kit providers like Gurit that bundle engineering services with material supply to reduce yard-level labor hours.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering and certification services attach rates are expanding faster than base material supply as yards outsource vacuum infusion tooling design and Coast Guard qualification documentation. This service layer recurs across vessel programs and carries margin structures superior to commodity resin sales.
For Market Incumbents: Build certified laminator training moats through apprenticeship partnerships with Mississippi Gulf Coast community colleges and naval shipyard qualification programs. Consolidate position by acquiring vacuum infusion tooling specialists in Texas and Florida to capture engineering service attach revenue. Carbon fiber allocation risk from defense program expansion threatens undifferentiated glass fiber suppliers lacking prepreg conversion capability. For New Entrants and Emerging Players: Pacific Coast custom racing yacht builders remain underserved by integrated kit suppliers, presenting white-space entry for vacuum infusion tooling providers with aerospace-grade thermosetting expertise. Target closed-mold process conversion demand among California fabricators facing OSHA styrene enforcement acceleration. Lead with engineering services rather than commodity supply to bypass established glass fiber distribution relationships. For Investors and Strategic Acquirers: Capital is best deployed toward prepreg converters with existing Department of Defense qualified supplier status and carbon fiber allocation agreements. Long-term viability hinges on defense unmanned surface vessel program commitments and superyacht foam core sandwich specification intensity. Watch for Coast Guard structural fire protection standard revisions as inflection signals requiring resin system reformulation and requalification investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Hexcel Corporation's Salt Lake City facility secures PAN-based fiber captive supply for naval prepreg programs. |
| Vacuum Infusion Tooling Acquisition | Gurit's integrated kit supply model reduces Gulf Coast yard labor hours while improving laminate consistency. |
| Department of Defense Qualification Investment | Certified traceability requirements compress margins for undifferentiated fabricators lacking military supplier status. |
| Closed-Mold Process Conversion | OSHA styrene exposure limits accelerate capital conversion from open-mold lamination among Florida boatbuilders. |
| Foam Core Sandwich Configuration Expansion | Superyacht and offshore structure applications in Texas deliver concentrated margin pools through insulation value-added specifications. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with shipyard procurement directors, Coast Guard marine safety inspectors, composite engineering leads, and resin formulation chemists; and secondary validation through EPA vessel emission standard filings, Department of Defense program budget documentation, customs trade data for carbon fiber imports, and SEC 10-K disclosures from listed material suppliers. Bottom-up vessel production estimates triangulated against top-down composite consumption metrics derived from fiber manufacturer shipment reports.
Forecast inputs considered defense procurement program timelines, EPA Clean Air Act marine engine standard implementation phases, and Coast Guard structural fire protection rulemaking progress across the projection horizon. Segmentation modeling incorporated fiber reinforcement type, resin chemistry platform, end-use mission profile, and structural application with regional shipbuilding cluster concentration. CAGRs were derived from regression analysis of historical defense budget authority and commercial hull production indices, adjusted for material substitution elasticity between steel and composite specifications.
Practitioners should monitor Department of Defense unmanned surface vessel program commitments and Coast Guard fire-retardant resin qualification timeline extensions for early signals of forecast deviation. Forecasts reflect assumptions regarding continued carbon fiber supply allocation to naval programs and stable petrochemical feedstock costs for vinyl ester production. Material shifts in ITAR-controlled carbon fiber export restrictions or EPA vessel emission standard acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Laminar Composites Market
Composite Materials
Plastic Composites Market
Composite Materials
Epoxy Composite Market
Composite Materials
Marine Composites Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Composite Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Global Geocomposites Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Carbon Fiber Prepreg Market
Composite Materials
Transportation Composites Market