
 Germany Automotive Engine Oils Market | 2026-2036
Germany Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Engine Oils Market Foresight
Aftermarket service revenue is rewriting profit distribution across the Germany Automotive Engine Oils Market. LIQUI MOLY leverages its Stuttgart roots to dominate specialty lubricant channels for German OEM-certified workshops. FUCHS anchors industrial-to-automotive supply continuity through captive blending capacity in Mannheim. ROWE MINERALÖLWERK GMBH differentiates via R&D intensity focused on race-derived formulations for enthusiast segments.
Germany Automotive Engine Oils are lubricating fluids formulated from base oils and additive packages, with viscosity grades such as 5W-30 and 0W-20 engineered to reduce friction, dissipate heat, and prevent wear in internal combustion engines operating under variable thermal loads. Their primary commercial purpose is to protect engine longevity while enabling compliance with tightening emissions and fuel-economy standards. Synthetic oil formulations command expanding share as OEMs mandate lower-viscosity grades for turbocharged direct-injection engines, while conventional oil retains residual volume in older passenger vehicle parc and agricultural equipment applications where drain intervals remain longer and specification tolerance is wider.
KBA vehicle-type approval requirements and EU F-Gas Regulation indirectly shape lubricant formulation paths by pressuring powertrain efficiency gains that depend on lower-viscosity oils. ACEA oil sequences and REACH chemical compliance standards determine which additive chemistries gain market access across German distribution channels. Stakeholders must monitor how Euro 7 emission proposals and carbon-border adjustments reshape base oil sourcing economics and refinery upgrade timelines.
Market Dynamics
Extended oil drain intervals mandated by German OEMs are compressing lubricant volume demand while forcing additive suppliers to reformulate for thermal stability under turbocharged direct-injection stress cycles.
Growth Catalysts
- ACEA C6 oil sequences:The 2021 update mandates lower high-temperature high-shear viscosity for hybrid-compatible formulations, compelling German workshops to upgrade inventory.
- Bavaria manufacturing density:Munich-Stuttgart corridor hosts captive blending capacity serving BMW, Mercedes-Benz, and Porsche assembly plants with just-in-time lubricant logistics.
- EU Green Deal carbon-border adjustments:Base oil imports face embedded-emissions accounting, advantaging Mannheim and Hamburg refineries with renewable hydrogen upgrade projects.
Market Restraints
- Group III base oil import concentration:German blenders rely on Middle Eastern and Asian API Group III supply for synthetic formulations, exposing margins to freight-rate volatility and carbon-border cost pass-through.
- Euro 7 emission proposal uncertainty:Pending particulate limits for gasoline direct-injection engines create formulation freeze risk as OEMs delay lubricant specification finalization.
- Electric vehicle powertrain substitution:Battery-electric drivetrains eliminate crankcase lubrication demand, with German PEV sales penetration reducing addressable engine oil volume in passenger segments.
Strategic Opportunities
- Baden-Württemberg specialty workshop channel:Independent service networks in Stuttgart and Karlsruhe seek differentiated race-derived formulations for enthusiast vehicle parc.
- REACH-compliant bio-based base oils:Rapeseed and sunflower-derived esters gain regulatory preference under EU chemical sustainability scoring for workshop procurement tenders.
- Hybrid thermal management fluids:Plug-in hybrid architectures require dedicated lubricants managing intermittent combustion cycles, opening formulation white space between passenger and industrial specifications.
Industry Challenges
- Additive chemist talent scarcity:German technical universities produce insufficient lubricant formulation specialists relative to REACH compliance and OEM co-development demands.
- KBA type-approval timeline compression:New engine architectures require lubricant certification cycles that outpace traditional 18-month validation windows, forcing parallel testing investments.
- Legacy workshop software integration:Independent garages operate mixed-generation diagnostic platforms that conflict with OEM-specified oil-life monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Engine Oils Market |
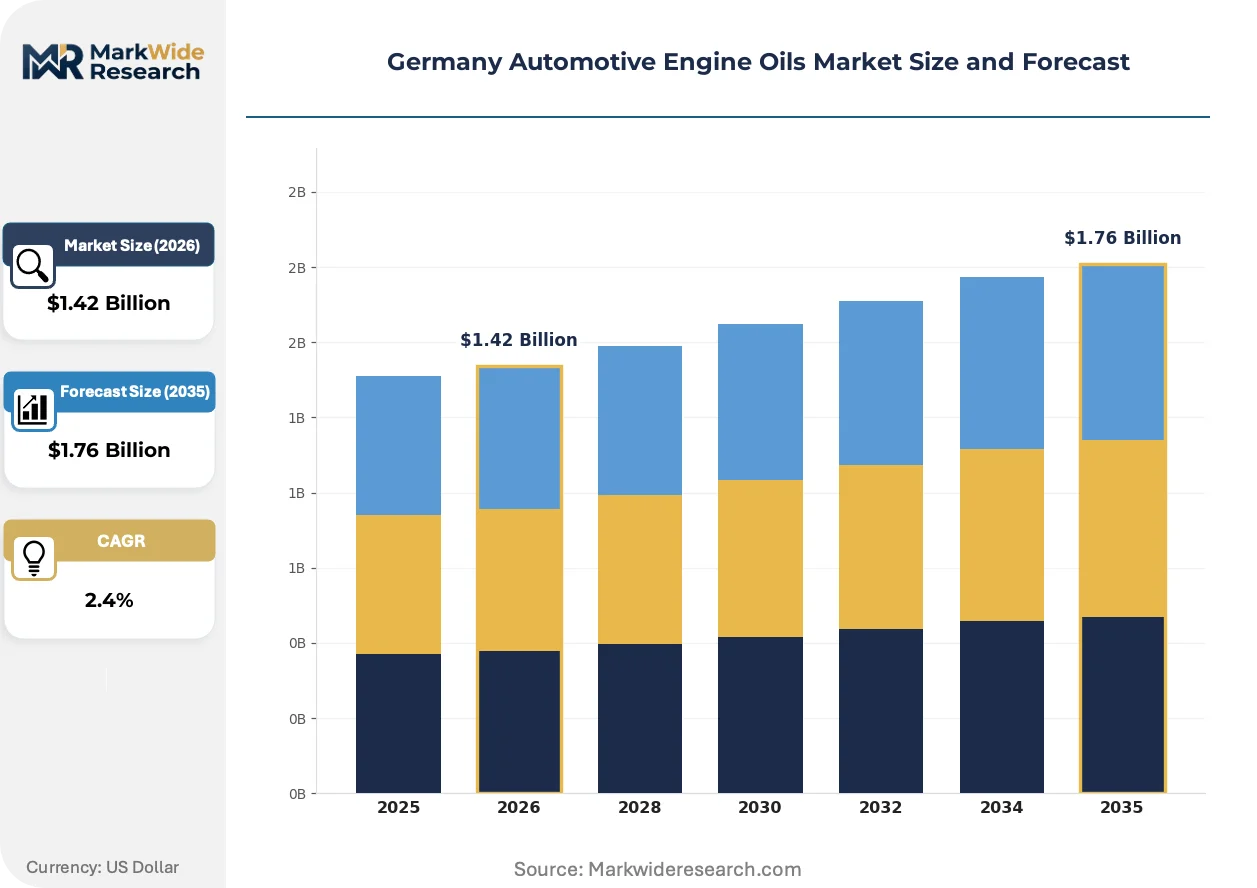
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $1.76 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-Based Oil, High Mileage Oil Viscosity Grade: 5W-30, 10W-40, 0W-20, 15W-40, 20W-50 Application: Passenger Vehicles, Commercial Trucks, Motorcycles, Agricultural Equipment, Construction Machinery End User: OEM Workshops, Independent Garages, Fleet Operators, Aftermarket Retailers, Car Enthusiasts |
| Companies Covered | LIQUI MOLY, CHEVRON CORPORATION, BP PLC (Castrol), ROWE MINERALÖLWERK GMBH, TotalEnergies, ExxonMobil Corporation, Royal Dutch Shell Plc, Motul, FUCHS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Engine Oils Market Shifts & Advancements
Formulation chemistry and distribution logistics are converging to redefine how lubricant value is captured across German automotive service networks.
Lower-viscosity 0W-8 and 0W-12 grades engineered for 48V mild-hybrid systems are collapsing the boundary between passenger car motor oil and industrial hydraulic fluid categories. Mercedes-Benz and Volkswagen powertrain divisions specify these ultra-thin formulations for thermal efficiency gains. The specification compression forces blenders to consolidate R&D programs previously separated by end-use vertical.
REACH Annex XIV authorization requirements for zinc dialkyldithiophosphate anti-wear additives are pressuring German formulators to accelerate sulfur-free alternative validation. ECHA sunset dates for legacy chemistries compress substitution timelines. Mid-tier blending operations lacking captive toxicology testing capacity face outsourcing cost escalation or formulation portfolio reduction.
Workshop procurement consolidation through buying groups in North Rhine-Westphalia and Lower Saxony is compressing distributor margin structures. Independent garage chains negotiate direct supply agreements with Mannheim and Hamburg blenders, bypassing traditional regional distributors. The channel restructuring concentrates volume with multi-site operators while fragmenting single-location service bay sourcing.
Germany Automotive Engine Oils Market Segmentation
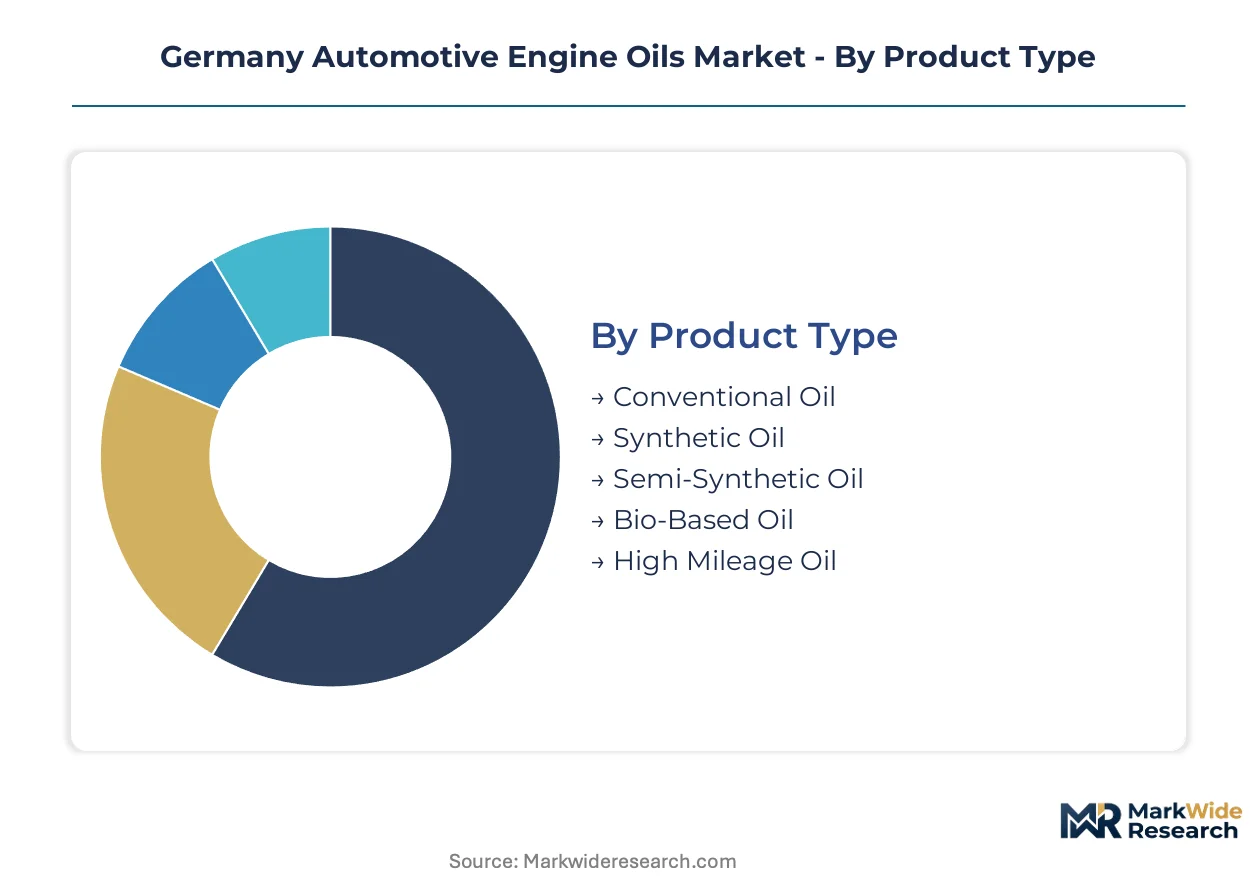
German automotive engine oil segmentation reflects divergent technical requirements across powertrain architectures and service channel economics. Specification fragmentation between OEM-certified workshops and independent garages creates distinct procurement patterns that reshape blender distribution priorities.
Product Type:
Cost tier positioning determines margin structures and R&D allocation across German blending operations.
- Synthetic Oil:Formulated from Group III and Group IV base stocks with precisely engineered additive packages for turbocharged direct-injection engines. Bavarian OEM workshops specify these formulations for BMW and Mercedes-Benz hybrid powertrains facing ACEA C6 thermal stability requirements. REACH-compliant chemistry investments compress mid-tier blender margins.
- Conventional Oil:Mineral-based formulations derived from solvent-refined base stocks with standard additive treat rates for older passenger vehicle parc. Demand concentrates in eastern German states where vehicle age averages higher and drain intervals remain extended. Price-sensitive agricultural equipment operators sustain residual volume despite specification obsolescence.
- Semi-Synthetic Oil:Blended base oil combinations targeting cost-conscious independent garages in North Rhine-Westphalia.
- Bio-Based Oil:Rapeseed and sunflower-derived esters gaining regulatory preference under EU Green Deal procurement scoring.
- High Mileage Oil:Seal conditioner formulations addressing elastomer degradation in vehicles exceeding 150,000 kilometers.
Conventional oil commands the established base. The steepest expansion runs through synthetic formulations.
Viscosity Grade:
Application-specific thermal load profiles drive viscosity selection across German powertrain architectures.
- 5W-30:Mid-range multigrade specification balancing cold-crank protection and high-temperature film strength for mainstream passenger vehicles. Baden-Württemberg independent service networks stock this grade as their default inventory position. ACEA C3 compatibility requirements force additive package upgrades.
- 0W-20:Ultra-low viscosity formulation engineered for 48V mild-hybrid thermal efficiency targets. Mercedes-Benz and Volkswagen powertrain divisions mandate this grade for new gasoline direct-injection architectures. Mannheim blenders face base oil sourcing constraints for consistent low-temperature pumpability.
- 10W-40:Legacy multigrade specification retaining volume in older commercial truck segments.
- 15W-40:Heavy-duty diesel specification for construction machinery operating under sustained load cycles.
- 20W-50:High-viscosity grade for classic vehicle enthusiast segments and air-cooled motorcycle engines.
10W-40 anchors workshop inventory positions. The fastest volume shift moves toward 0W-20 specifications.
Application:
End-use thermal severity and duty cycles determine additive chemistry investment levels.
- Passenger Vehicles:Gasoline and diesel engine lubricants subject to OEM oil-life monitoring systems and extended drain intervals. Stuttgart and Munich corridor workshops specify factory-fill formulations for warranty compliance. Euro 7 emission proposal uncertainty delays specification finalization.
- Commercial Trucks:Heavy-duty diesel engines operating under sustained high-load conditions with extended drain intervals up to 100,000 kilometers. Fleet operators in Hamburg and Frankfurt logistics corridors negotiate direct supply agreements with Mannheim blenders. ACEA E6/E8 specifications mandate soot-handling additive packages.
- Motorcycles:Wet clutch-compatible formulations with JASO MA2 friction certification for Bavarian leisure riding segments.
- Agricultural Equipment:Universal tractor transmission oils serving combined hydraulic and engine lubrication functions.
- Construction Machinery:Off-highway diesel specifications for equipment operating under intermittent load with high particulate exposure.
Commercial trucks concentrate procurement volume. Passenger vehicle specifications are expanding most quickly.
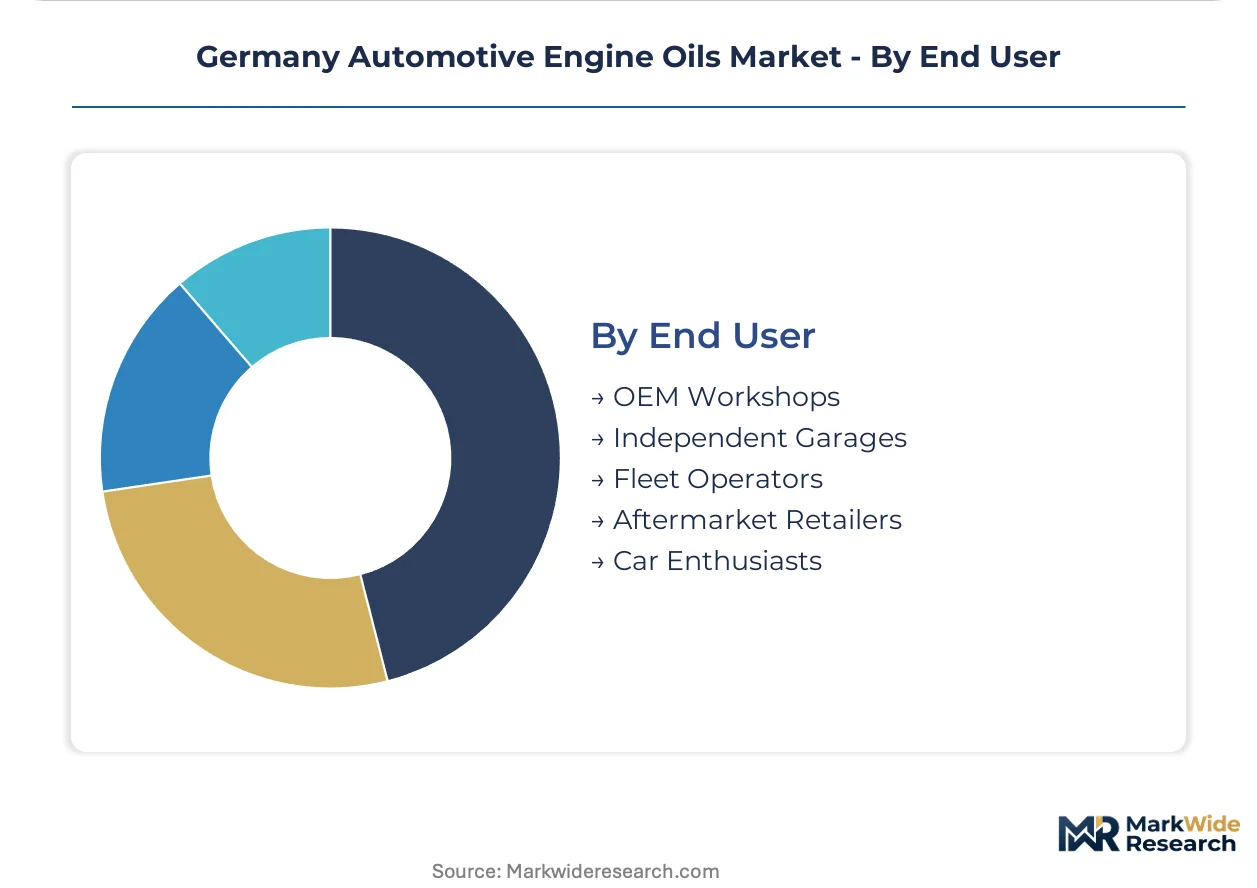
End User:
Customer type determines certification requirements and price negotiation leverage across German distribution channels.
- OEM Workshops:Factory-certified service networks bound by manufacturer-specified lubricant grades and just-in-time inventory systems. BMW, Mercedes-Benz, and Porsche workshop programs require captive blending capacity within 150-kilometer delivery radius. KBA type-approval documentation mandates traceable formulation records.
- Independent Garages:Multi-brand service bays operating mixed-generation diagnostic platforms with fragmented oil-life monitoring integration. Buying groups in North Rhine-Westphalia and Lower Saxony consolidate procurement volume for direct blender negotiations. Price compression forces mid-tier distributor margin erosion.
- Fleet Operators:Commercial vehicle managers with centralized lubricant specification and bulk storage infrastructure.
- Aftermarket Retailers:Do-it-yourself channels serving enthusiast vehicle owners with branded packaged goods.
- Car Enthusiasts:Specialty lubricant buyers seeking race-derived formulations for track-day and classic vehicle applications.
OEM workshops lock in premium pricing. Independent garage consolidation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria and Baden-Württemberg consume engine oils differently from eastern German states, with western manufacturing corridors demanding ACEA C6 synthetic formulations while older vehicle parc in Thuringia and Saxony sustains conventional mineral demand.
Bavaria
BMW and Audi assembly plants in Munich and Ingolstadt drive just-in-time synthetic lubricant logistics. KBA type-approval requirements mandate traceable formulation documentation for factory-fill programs. Munich-Stuttgart corridor blending capacity serves OEM-certified workshops with dedicated distribution networks.
Baden-Württemberg
Mercedes-Benz and Porsche powertrain development centers specify ultra-low viscosity 0W-20 grades for hybrid thermal efficiency. Stuttgart specialty workshops seek race-derived formulations for enthusiast segments. EU Green Deal procurement scoring advantages bio-based esters in regional tender processes.
North Rhine-Westphalia
Independent garage buying groups in Cologne and Düsseldorf consolidate procurement volume for direct blender negotiations. REACH compliance documentation requirements filter distributor participation. Lower Saxony border logistics hubs manage bulk storage for commercial truck fleet operators.
Lower Saxony
Volkswagen Wolfsburg headquarters anchors captive blending relationships for Group-wide specification alignment. Hamburg refinery renewable hydrogen upgrade projects secure regional Group III base oil supply. ACEA E6 heavy-duty diesel specifications dominate commercial vehicle service corridors toward Hanover.
Hesse
Frankfurt logistics concentration supports lubricant distribution to central European export markets. EU F-Gas Regulation compliance pressures thermal management fluid formulation paths. Mannheim blending operations supply Rhine-Main metropolitan aftermarket channels with synthetic passenger vehicle formulations.
Germany Automotive Engine Oils Market Competitive Landscape
Capability concentration sits with specialty German blenders rooted in regional automotive clusters; scale advantage sits with integrated multinational energy majors with captive base oil supply. The market structure divides between OEM-captive formulation specialists and broad-line distributors serving fragmented independent workshops. Two strategic archetypes dominate: Stuttgart-based technical specialists leveraging motorsport heritage for enthusiast channel premium positioning, and Mannheim-anchored industrial conglomerates with backward integration into base oil refining. Competitive moves center on direct procurement consolidation with multi-site garage chains and REACH-compliant additive chemistry substitution timelines.
Among German-anchored specialists, LIQUI MOLY and ROWE MINERALÖLWERK GMBH exemplify the motorsport-heritage archetype with Stuttgart-region technical positioning. FUCHS occupies the industrial-to-automotive continuity tier with Mannheim captive blending infrastructure. These domestic players represent formulation capability concentration against multinational scale advantages held by energy-integrated competitors with global base oil sourcing networks.
| Leading Market Players |
|---|
| LIQUI MOLY |
| CHEVRON CORPORATION |
| BP PLC (Castrol) |
| ROWE MINERALÖLWERK GMBH |
| TotalEnergies |
| ExxonMobil Corporation |
| Royal Dutch Shell Plc |
| Motul |
| FUCHS |
| Others |
Supply & Pricing Matrix
Mannheim-Hamburg rail freight corridors transmit Group III base oil import cost volatility directly into blender margin structures, concentrating pricing power with refineries possessing renewable hydrogen upgrade capacity while fragmenting downstream negotiation leverage across independent garage buying groups.
Pricing Analysis
Long-term offtake contracts between Mannheim blenders and Bavarian OEM workshops lock in synthetic formulation premiums, while spot market exposure dominates conventional oil procurement for eastern German agricultural operators. Price differentiation rests on ACEA certification tier and captive blending proximity to Stuttgart-Munich assembly plants. Cost compression in mid-tier semi-synthetic segments intensifies as North Rhine-Westphalia buying groups consolidate procurement volume. Fleet operators exhibit lowest price sensitivity due to warranty compliance requirements, whereas independent garages face acute margin pressure from diagnostic platform fragmentation.
Supply Chain Analysis
Contract manufacturing concentration sits with FUCHS Mannheim and Hamburg refinery operations holding captive Group III hydrocracking capacity, supplemented by Rotterdam blending facilities serving Rhine-Ruhr distribution nodes. German formulators draw from Middle Eastern and South Korean API Group III supply, with rapeseed ester feedstocks anchoring bio-based formulation lines in Baden-Württemberg. Single-source vulnerability concentrates in zinc dialkyldithiophosphate additive chemistry facing REACH Annex XIV sunset dates. Distribution runs through OEM-certified workshop direct delivery networks and independent garage buying group consolidation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ACEA C6 specification mandates and Euro 7 emission proposal timelines are compressing formulation validation windows, creating a high-growth disruption environment where REACH-compliant chemistry investments separate viable competitors from margin-eroded mid-tier blenders.
For Market Incumbents: Insulate formulation portfolios by accelerating sulfur-free additive validation programs ahead of ECHA sunset dates, while securing captive bio-based ester supply through backward integration into Baden-Württemberg agricultural processing networks. Threat substitution from battery-electric powertrains demands hybrid thermal management fluid R&D expansion.
For New Entrants and Emerging Players: Establish a beachhead in Baden-Württemberg specialty workshop channels for race-derived enthusiast formulations, where technical differentiation commands premium positioning outside OEM-captive supply agreements. The penetrable segment lies in plug-in hybrid dedicated lubricants managing intermittent combustion cycles, with go-to-market execution through Stuttgart-region motorsport heritage branding.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with underutilized Mannheim blending assets and stranded conventional oil capacity facing specification obsolescence. Long-term viability centers on REACH-compliant synthetic formulation capability and OEM co-development relationships. Monitor KBA type-approval timeline compression as inflection signal for parallel testing infrastructure value.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Rapeseed and sunflower ester sourcing secures EU Green Deal procurement scoring advantages. |
| ACEA C6 Certification Investment | Hybrid-compatible formulation approval unlocks BMW and Mercedes-Benz factory-fill programs. |
| Direct Supply Agreement with Garage Buying Groups | North Rhine-Westphalia consolidation channels bypass traditional distributor margin structures. |
| Parallel Testing Infrastructure Expansion | KBA timeline compression demands simultaneous multi-architecture lubricant validation cycles. |
| Hybrid Thermal Management Fluid Development | Plug-in hybrid architectures create formulation white space between passenger and industrial specifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of KBA type-approval databases, ACEA oil sequence documentation, and EU ECHA regulatory filings, combining structured interviews with lubricant formulators, OEM procurement leads, and independent garage operators with trade flow analysis from German customs records and refinery capacity disclosures. Bottom-up volume modeling triangulates against top-down macroeconomic indicators.
Forecast inputs span viscosity grade evolution, powertrain architecture substitution rates, and REACH compliance cost pass-through across the projection horizon. Segmentation dimensions include product type tier, OEM certification status, and regional manufacturing cluster density. CAGRs derive from regression analysis against vehicle parc age distribution and drain interval extension trends, with specific incorporation of Euro 7 proposal uncertainty and carbon-border adjustment implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in German automotive production volumes and Middle Eastern base oil freight rates would shift the trajectory. Forecasts reflect documented assumptions regarding specification adoption curves and regulatory enforcement cadence. Quarterly review of KBA approval timelines and ECHA authorization sunset dates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Textile Machine Lubricants Market
Lubricants
Open Gear Lubricants Market
Lubricants
High Performance Lubricants Market
Lubricants
France Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Graphite Lubricant Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Specialty Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
ASEAN Lubricants Market