
 Laminar Composites Market | 2026-2036
Laminar Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Laminar Composites Market Outlook
Buyer concentration across aerospace OEMs is broadening as tier-one suppliers diversify their laminar composite sourcing beyond traditional single-source contracts. Hexcel Corporation leverages its captive carbon fiber supply chain to sustain pricing leverage on structural prepregs. Toray Advanced Composites anchors its position through deep qualification relationships with commercial aviation programs. Mitsubishi Chemical Group Corporation competes on thermoplastic laminate capacity, positioning its European plants to serve automotive OEMs directly.
Laminar composites are engineered materials built from successive bonded layers of reinforcement and matrix, typically achieving specific strength-to-weight ratios through controlled fiber orientation and resin infusion processes. These structures serve critical load-bearing functions where monolithic materials would fail under multi-axial stress or thermal cycling. Reinforced laminates dominate current volume owing to their established qualification pathways in aerospace structural components, while thermoplastic laminates represent the fastest-expanding category as automotive OEMs pursue recyclable, out-of-autoclave processing. Nano composites command premium positioning in electronics thermal management applications where through-thickness conductivity requirements exceed conventional laminate capabilities.
The FAA's continued airworthiness directives and the EU's REACH substance restrictions jointly shape material selection, testing protocols, and supplier qualification timelines for laminar composite manufacturers. Germany's KBA enforces specific crashworthiness standards that drive carbon fiber laminate specifications in automotive structural components. Stakeholders must monitor evolving recyclability mandates from ECHA and the EU Green Deal, as end-of-life regulations threaten to disqualify thermoset-dominant portfolios unless chemical recycling infrastructure matures.
Market Dynamics
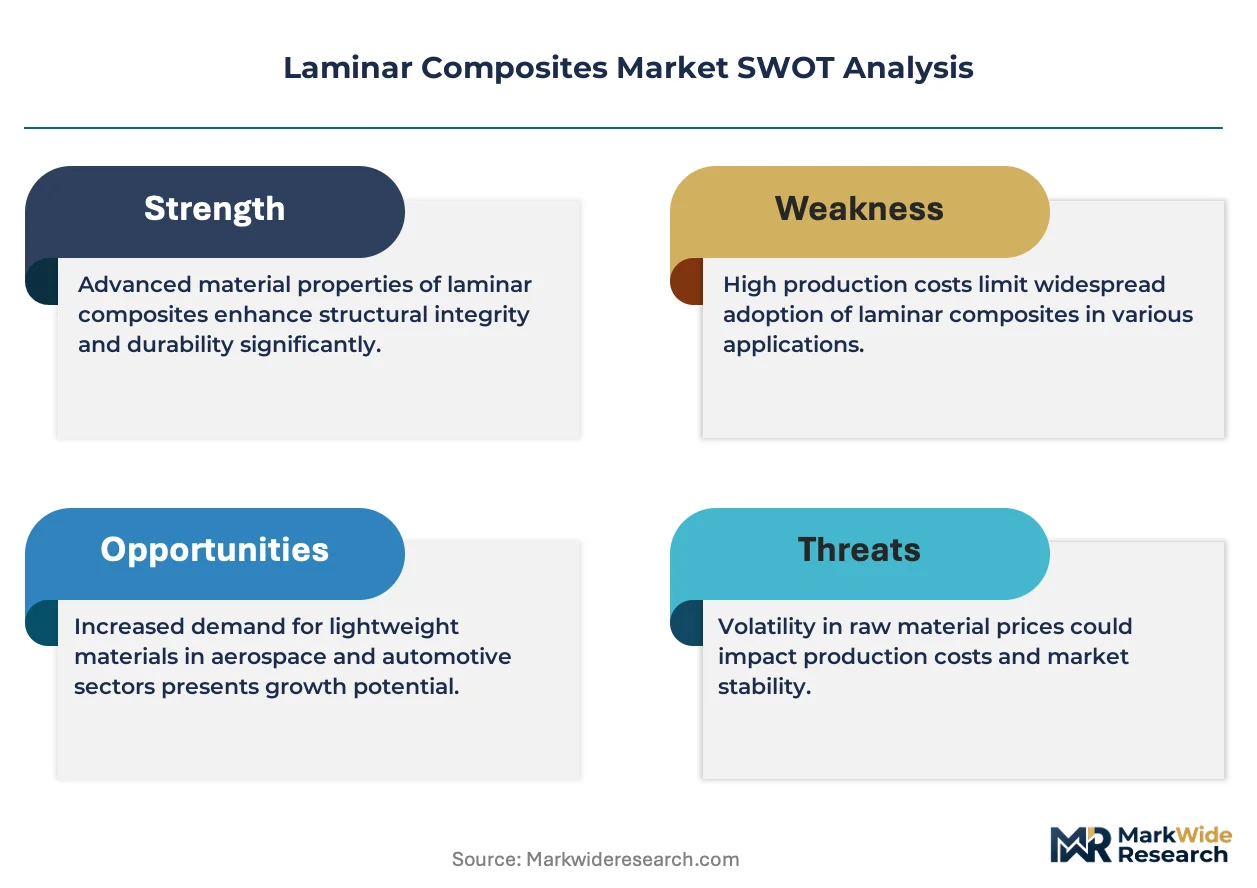
The aerospace procurement pivot toward thermoplastic laminates is restructuring supplier relationships, as airframe OEMs demand out-of-autoclave processing capabilities and chemical recyclability pathways that thermoset portfolios cannot satisfy.
Growth Catalysts
- Thermoplastic laminate qualification:Commercial aviation programs are accelerating thermoplastic adoption for fuselage panels and wing structures, driven by weight reduction targets and reduced cycle times.
- EU Green Deal mandates:REACH compliance deadlines and end-of-life regulations are forcing automotive OEMs toward recyclable composite solutions, directly benefiting thermoplastic laminate demand.
- Stuttgart-Munich corridor concentration:Germany's automotive composites cluster is absorbing expanded thermoplastic capacity as BMW and Porsche integrate carbon fiber structural components into electric vehicle platforms.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with petrochemical feedstock markets, compressing margin stability for prepreg manufacturers.
- Single-source carbon fiber dependency:Aerospace-qualified fiber supply concentrates among three producers, creating qualification bottlenecks for tier-two laminate fabricators.
- Thermoset recycling limitations:Pyrolysis and solvolysis infrastructure remains underdeveloped, threatening thermoset-dominant portfolios with regulatory disqualification under ECHA mandates.
Strategic Opportunities
- India automotive lightweighting:PLI scheme incentives for electric vehicle manufacturing are opening procurement channels for thermoplastic composite structural components.
- Electronics thermal management:Nano-composite laminates with through-thickness conductivity are penetrating semiconductor packaging and 5G base station applications.
- Japan hydrogen storage:METI-funded projects are qualifying carbon fiber laminates for Type IV pressure vessels, creating new demand outside traditional aerospace and automotive verticals.
Industry Challenges
- Automated fiber placement programming:Shortages of technicians capable of operating thermoplastic AFP equipment are constraining capacity expansion at qualified facilities.
- Dual certification timelines:Simultaneous FAA and EASA qualification pathways for new prepreg formulations extend development cycles and freeze R&D capital for years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminar Composites Market |
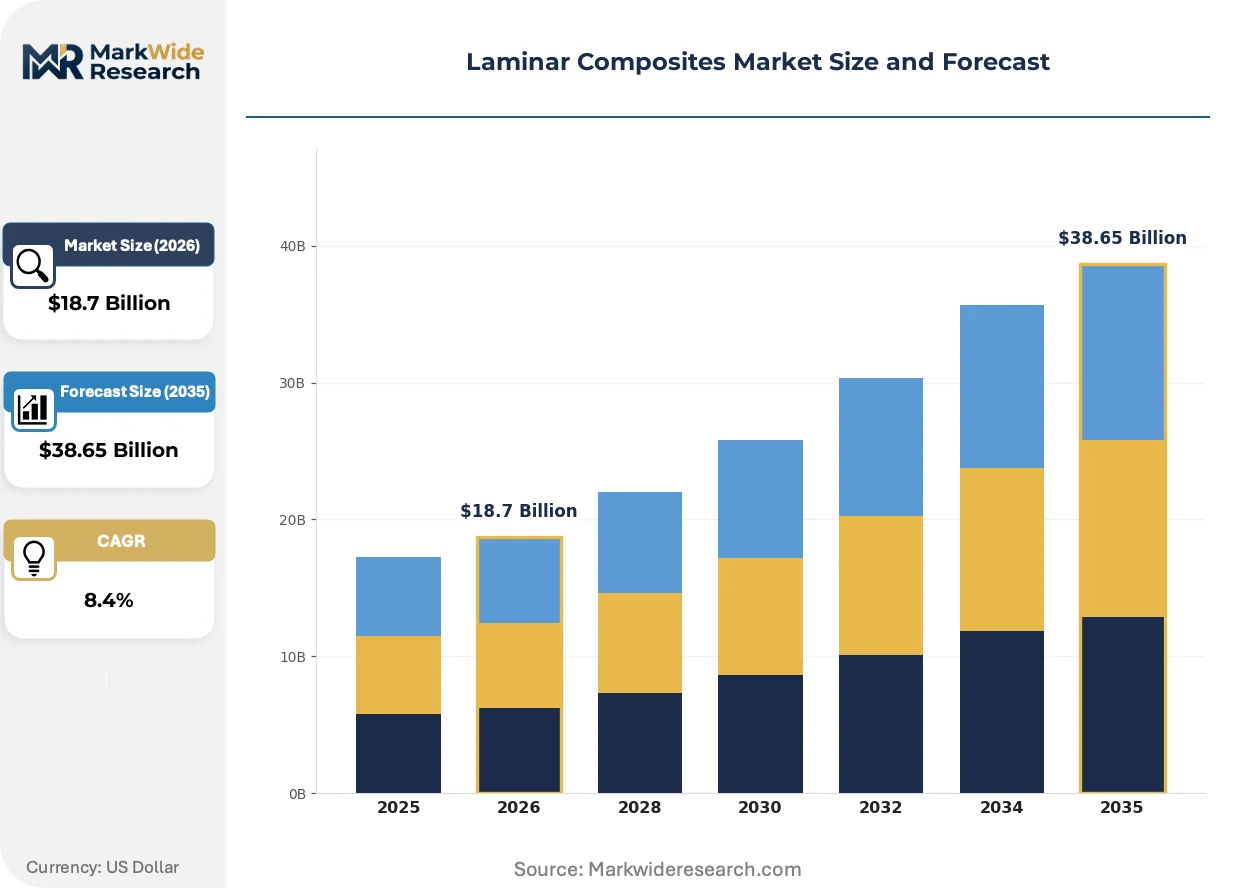
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Laminates, Hybrid Composites, Nano Composites, Thermoplastic Laminates End User: Aerospace, Automotive OEMs, Marine Industry, Electronics Material: Carbon Fiber, Glass Fiber, Polymer Matrix, Ceramic Matrix Application: Structural Components, Thermal Management, Insulation Materials, Surface Protection |
| Companies Covered | Hexcel Corporation, Toray Advanced Composites, Evonik, Honeywell International Inc, 3A Composites, Armacell International S.A., Teijin Limited, Mitsubishi Chemical Group Corporation, JEC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminar Composites Market Strategic Shifts
Processing automation and regulatory disclosure requirements are compressing development cycles while fragmenting the qualified supplier base. Material traceability and in-situ monitoring are becoming competitive differentiators.
Automated fiber placement with in-situ consolidation is automating thermoplastic laminate production for complex aerostructures. Aerospace tier-one suppliers are adopting these systems for wing spars and fuselage frames. The technology is automating layup processes previously requiring manual consolidation, reducing touch labor and defect rates while enabling larger monolithic structures.
REACH substance disclosure expansions are mandating full supply chain chemical transparency for composite formulations imported into EU member states. Manufacturers must now document monomer content, catalyst residues, and additive packages across all tiers. Automotive structural laminate suppliers serving German OEMs face the most aggressive compliance timelines, with material passports required by 2026.
Direct OEM contracting is displacing traditional distributor channels for qualified aerospace prepregs. Tier-one airframe manufacturers are establishing long-term offtake agreements with laminate producers, bypassing regional distributors that previously managed inventory and technical service. This pattern concentrates most visibly in Washington state and Toulouse, where Boeing and Airbus procurement teams are consolidating approved vendor lists.
Laminar Composites Market Segmentation
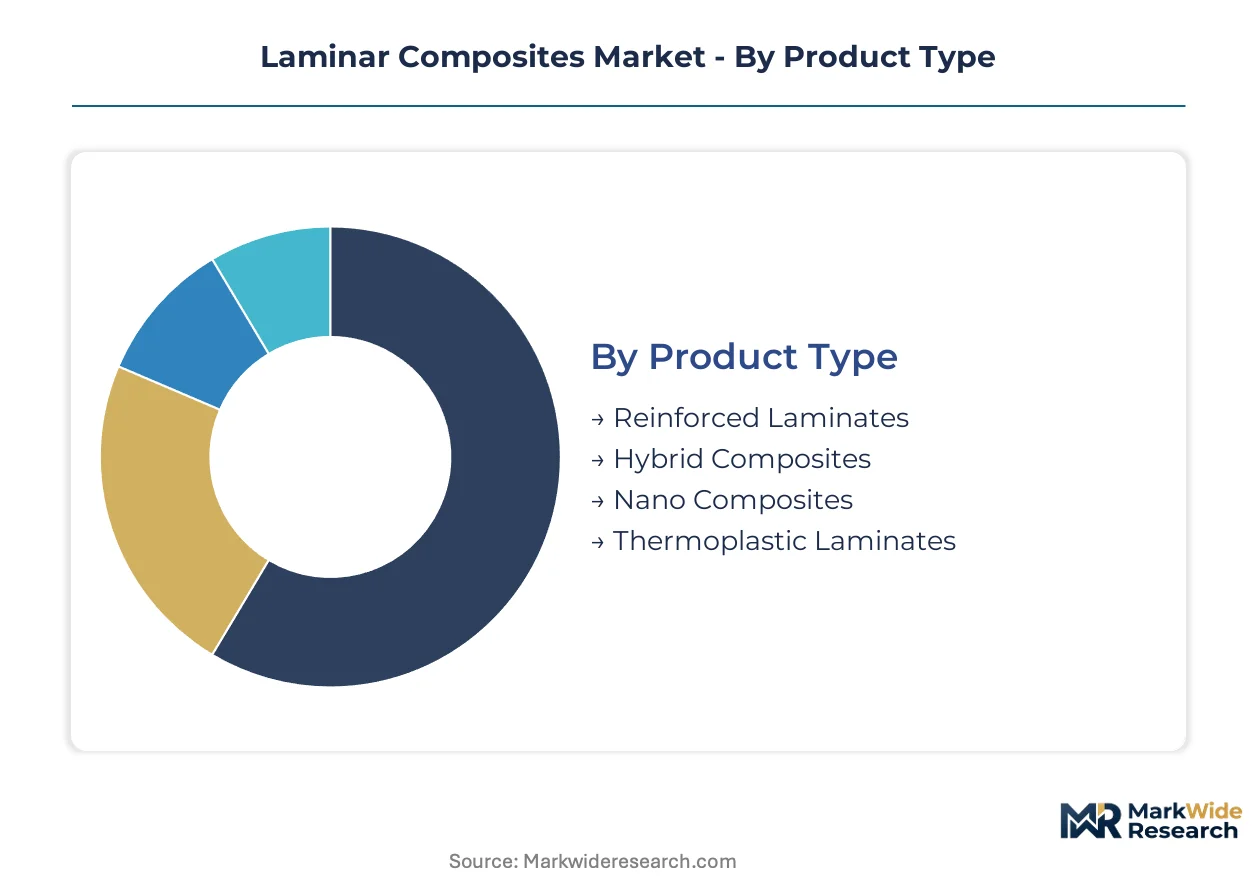
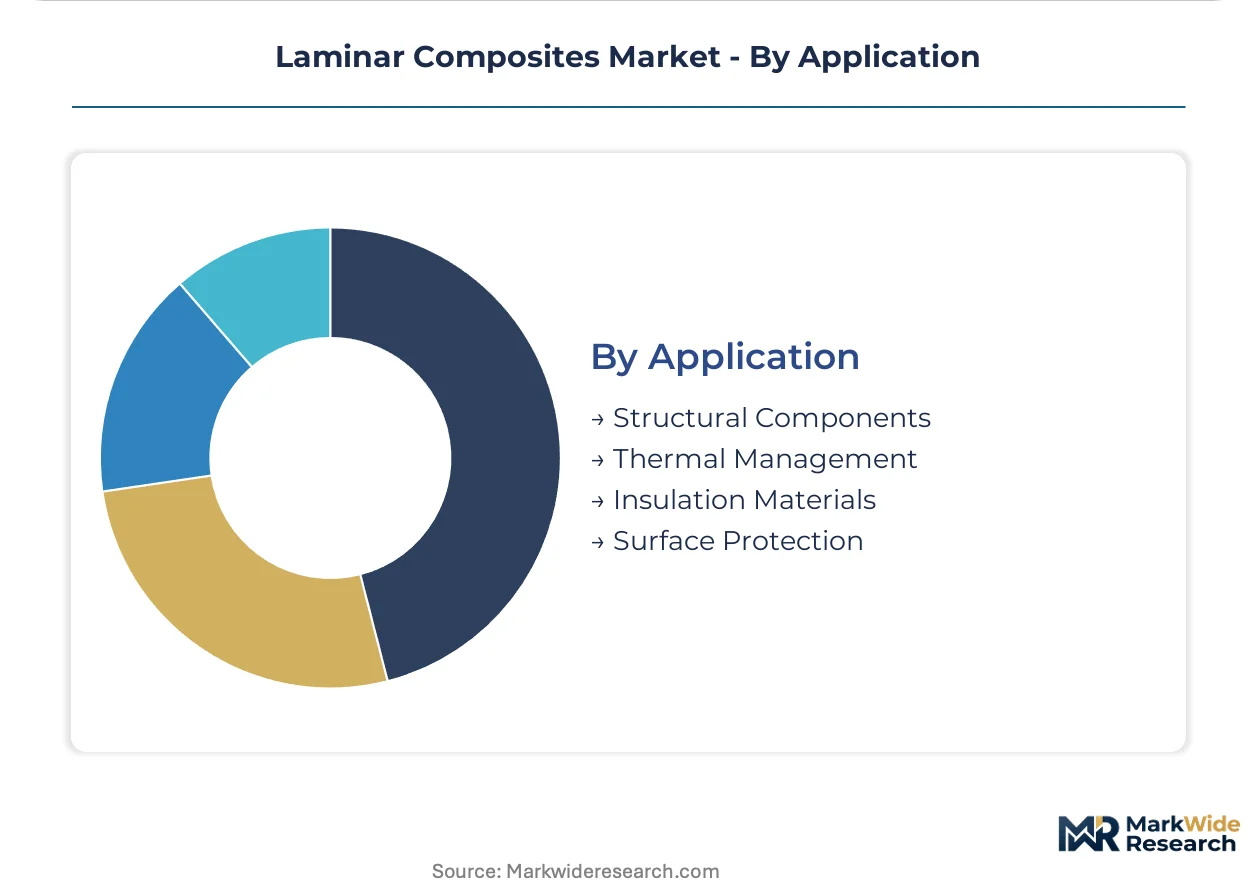
Laminar composite segmentation reveals divergent qualification pathways and margin structures across product architectures. Material selection directly determines processing economics, recyclability compliance, and end-use accessibility for manufacturers competing across aerospace, automotive, and electronics verticals.
Product Type:
Volume concentration sits with established thermoset architectures, while premium positioning and fastest expansion attach to thermoplastic formats qualifying for next-generation airframes.
- Reinforced Laminates:Multi-layer structures combining unidirectional or woven fiber reinforcement with thermoset resin matrices, qualified extensively for primary aerospace structural loads. Demand concentrates in Boeing and Airbus tier-one supply chains where FAA/EASA certification creates decade-long supplier lock-in.
- Thermoplastic Laminates:Fiber-reinforced sheets with PEEK, PPS, or PEI matrices enabling out-of-autoclave processing and chemical recyclability. Stuttgart-Munich automotive OEMs are absorbing expanded capacity for electric vehicle battery enclosures and structural members under EU Green Deal mandates.
- Hybrid Composites:Architectures blending carbon and glass fiber layers or combining thermoset and thermoplastic elements for cost-performance optimization. Marine hull applications in Nordic shipyards drive specification development.
- Nano Composites:Laminates incorporating carbon nanotubes, graphene, or nanoclay additives for through-thickness thermal conductivity. Semiconductor packaging and 5G base station thermal management in Taiwan and South Korea absorb limited but high-margin volumes.
Mature deployment sits with reinforced laminates. Newer deployment is concentrated in thermoplastic laminates.
End User:
Customer concentration splits between qualification-heavy aerospace procurement and volume-scaled automotive programs, with electronics emerging as a conductivity-driven niche.
- Aerospace:Airframe OEMs and tier-one suppliers specifying prepregs for wings, fuselage sections, and empennage structures. Boeing's Washington state operations and Airbus Toulouse facilities anchor global demand through long-term offtake agreements bypassing distributor channels.
- Automotive OEMs:BMW, Porsche, and Mercedes-Benz integrating carbon fiber structural components into electric vehicle platforms for weight reduction and crash performance. Germany's KBA enforces specific laminate specifications for crashworthiness compliance.
- Marine Industry:Yacht builders and commercial vessel manufacturers specifying glass-reinforced laminates for hulls and superstructures. Nordic and Mediterranean shipyards dominate procurement with moderate qualification barriers.
- Electronics:Semiconductor packaging, base station antennas, and consumer device manufacturers requiring thermal management laminates. Taiwan's TSMC supply chain and South Korean memory producers drive nano-composite qualification.
Procurement scale peaks with automotive OEMs. Technical qualification intensity peaks with aerospace.
Material:
Fiber type determines performance tier and precursor cost exposure, while matrix selection governs processing temperature and recyclability pathways.
- Carbon Fiber:PAN-based and pitch-based fibers delivering maximum specific stiffness for primary structural loads. Aerospace-qualified fiber supply concentrates among three producers, creating qualification bottlenecks for tier-two laminate fabricators dependent on acrylonitrile precursor availability.
- Glass Fiber:E-glass and S-glass reinforcements offering cost-effective strength for secondary structures and marine applications. Automotive underbody panels and wind turbine blades absorb volume through established chop and spray processes.
- Polymer Matrix:Epoxy, polyester, and vinyl ester thermosets alongside PEEK, PPS, and PEI thermoplastics binding fiber reinforcement. REACH substance disclosure expansions mandate full chemical transparency for EU-imported formulations.
- Ceramic Matrix:Silicon carbide and alumina matrices enabling ultra-high temperature operation for turbine components and heat shields. Limited volumes serve aerospace propulsion and industrial furnace applications.
Cost-sensitive deployment sits with glass fiber. Performance-critical deployment sits with carbon fiber.
Application:
Functional requirement dictates laminate architecture, with load-bearing applications demanding through-thickness strength and thermal applications prioritizing conductivity.
- Structural Components:Primary and secondary load-bearing elements including wing spars, fuselage frames, automotive crash structures, and marine hulls. Automated fiber placement with in-situ consolidation is automating thermoplastic production for complex aerostructures.
- Thermal Management:Heat spreaders, semiconductor substrates, and battery thermal interface materials requiring through-thickness conductivity. Nano-composite laminates penetrate where conventional laminate capabilities fall short.
- Insulation Materials:Dielectric barriers and thermal insulation for electrical equipment and cryogenic systems. Glass-reinforced laminates dominate with established electrical grade specifications.
- Surface Protection:Erosion shields, corrosion barriers, and cosmetic finish layers. Marine and wind energy applications specify gel-coated surfaces for UV and moisture resistance.
Qualification complexity peaks with structural components. Margin compression risk sits with surface protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for laminar composites clusters in Germany's automotive corridor and the United States aerospace manufacturing belt, with emerging absorption centers forming in Japan and India as hydrogen storage and electric vehicle programs mature.
United States
Boeing's Washington state operations and SpaceX's Texas facilities drive structural prepreg consumption for commercial aviation and space launch systems. FAA airworthiness directives govern material qualification timelines for all airframe applications. The Pacific Northwest manufacturing cluster around Seattle anchors North American aerospace laminate demand through direct OEM contracting.
Germany
BMW, Porsche, and Mercedes-Benz integrate carbon fiber structural components into electric vehicle platforms for weight reduction and crash performance. KBA enforces specific laminate specifications for automotive crashworthiness compliance. The Stuttgart-Munich corridor concentrates expanded thermoplastic capacity serving battery enclosures and structural members under EU Green Deal mandates.
Japan
METI-funded hydrogen storage projects qualify carbon fiber laminates for Type IV pressure vessels outside traditional aerospace applications. JIS standards govern composite material specifications for industrial and transportation uses. The Nagoya aerospace cluster and Tokyo industrial belt absorb specialty laminate volumes for next-generation mobility systems.
China
Commercial Aircraft Corporation of China accelerates domestic composite qualification for C919 and CR929 programs reducing import dependency. MIIT industrial policy directs capacity expansion toward aerospace-grade carbon fiber self-sufficiency. The Yangtze River Delta manufacturing belt concentrates prepreg fabrication serving both aviation and wind energy sectors.
India
PLI scheme incentives for electric vehicle manufacturing open procurement channels for thermoplastic composite structural components. BIS standards development lags behind automotive OEM qualification requirements. The Tamil Nadu and Maharashtra automotive clusters absorb initial volumes as domestic laminate fabrication capacity scales.
Laminar Composites Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue thermoplastic qualification pathways and automated processing capabilities. The supplier base stratifies between aerospace-qualified incumbents with decade-long certification lock-in and automotive-focused challengers scaling out-of-autoclave capacity. Three archetypes dominate: integrated fiber-to-prepreg operators, specialized laminate fabricators, and materials science conglomerates diversifying from chemicals. Competitive moves center on backward integration into carbon fiber precursor supply and strategic partnerships with automated fiber placement equipment vendors.
Among aerospace-anchored suppliers, Hexcel Corporation and Toray Advanced Composites exemplify the qualification-intensive tier where FAA/EASA certification creates structural barriers. Mitsubishi Chemical Group Corporation occupies a position bridging thermoplastic capacity expansion and European automotive direct supply. These three entities represent distinct strategic postures: captive fiber integration, deep program qualification relationships, and regional manufacturing proximity to OEM assembly.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Advanced Composites |
| Evonik |
| Honeywell International Inc |
| 3A Composites |
| Armacell International S.A. |
| Teijin Limited |
| Mitsubishi Chemical Group Corporation |
| JEC Group |
| Others |
Value Chain & Pricing Dynamics
Aerospace tier-one suppliers concentrate procurement leverage through long-term offtake agreements, forcing a contract-based pricing structure that locks in volume commitments against raw material pass-through clauses. This buyer concentration shifts pricing power toward qualified incumbents with FAA/EASA certification lock-in while squeezing tier-two fabricators on margin.
Pricing Analysis
Volume-scale automotive programs run on contract-based long-term offtake pricing with raw material pass-throughs, while aerospace structural prepregs command premium-mid-economy pricing differentiation based on certification grade and qualification depth. Price differentiation stems from FAA/EASA certification tier and captive carbon fiber integration, with Hexcel Corporation sustaining leverage through upstream fiber control. Pricing pressure intensifies in thermoset laminate tiers as ECHA recyclability mandates threaten portfolio viability, while automotive OEMs show highest price sensitivity due to electric vehicle cost targets.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for qualified aerospace prepregs, with Stuttgart-Munich corridor facilities serving BMW and Porsche direct. Supply draws from acrylonitrile precursor markets, PAN-based carbon fiber production, and thermoplastic resin compounding, creating dependency on petrochemical feedstock volatility. Single-source carbon fiber vulnerability concentrates among three qualified producers, generating qualification bottlenecks for tier-two laminate fabricators. Distribution runs through direct OEM contracting channels that displace traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH compliance deadlines and thermoset recycling limitations force weaker players toward exit or acquisition.
For Market Incumbents: Lock in aerospace qualification relationships through accelerated thermoplastic certification investments, securing decade-long program lock-in against emerging entrants. Deepen backward integration into carbon fiber precursor supply to defend margin position against acrylonitrile volatility. Establish captive chemical recycling partnerships to neutralize ECHA disqualification risk on thermoset portfolios. For New Entrants and Emerging Players: Automated fiber placement programming expertise offers a technology-first wedge into aerospace tier-two fabrication, bypassing decade-long FAA qualification barriers. Target India's PLI-subsidized electric vehicle supply chain for thermoplastic structural components, exploiting lagging domestic BIS standards. Pursue direct OEM contracting with Stuttgart-Munich automotive OEMs rather than distributor channels. For Investors and Strategic Acquirers: The window for entry favors mid-cap thermoplastic specialists with out-of-autoclave capacity and European automotive direct supply relationships. Long-term viability centers on recyclability-compliant portfolios as ECHA mandates harden. Watch for FAA thermoplastic qualification announcements as inflection signals for aerospace procurement pivot completion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor | Hexcel Corporation's captive acrylonitrile supply insulates margin against petrochemical volatility. |
| Thermoplastic Qualification Acceleration | Toray Advanced Composites deepens Boeing and Airbus program lock-in through PEEK laminate certification. |
| Direct OEM Contracting Establishment | Mitsubishi Chemical Group Corporation bypasses distributors to serve Stuttgart-Munich automotive OEMs directly. |
| Chemical Recycling Partnership Formation | Thermoset-dominant portfolios secure ECHA compliance pathways against regulatory disqualification risk. |
| Automated Fiber Placement Capacity Expansion | Aerospace tier-one suppliers reduce touch labor and defect rates for complex wing spar production. |
Study Parameters
SEC 10-K filings, ECHA substance registration databases, and FAA airworthiness directive archives formed the secondary backbone, cross-referenced with customs and trade data from Germany's KBA and Japan's METI. Primary interviews with aerospace procurement directors, automotive platform engineers, thermoplastic R&D leads, and composite fabricator plant managers validated demand assumptions across the analysis window. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Historical trendline analysis tracked qualification timeline patterns and raw material cost pass-through mechanisms across the projection horizon. Segmentation modeling incorporated product architecture, end-use vertical, fiber type, and regional regulatory cluster dimensions. CAGRs derived from volume absorption rates in aerospace program ramp-ups and automotive platform launches, with sensitivity testing against acrylonitrile price volatility and REACH compliance deadline shifts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FAA thermoplastic adoption or ECHA recyclability mandate delays. Outputs reflect documented assumptions on qualification timeline compression and chemical recycling infrastructure maturation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Quartz Stone Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Thermoset Composites Market
Composite Materials
FRP Tanks Market
Composite Materials
Medical Composite Material Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Expandable Graphite Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
Isostatic Graphite Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
CFRP Propeller Shaft Market
Composite Materials
Graphite Carbon Raiser Market