
 High Temperature Composite Resin Market | 2026-2036
High Temperature Composite Resin Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Composite Resin Market Analysis
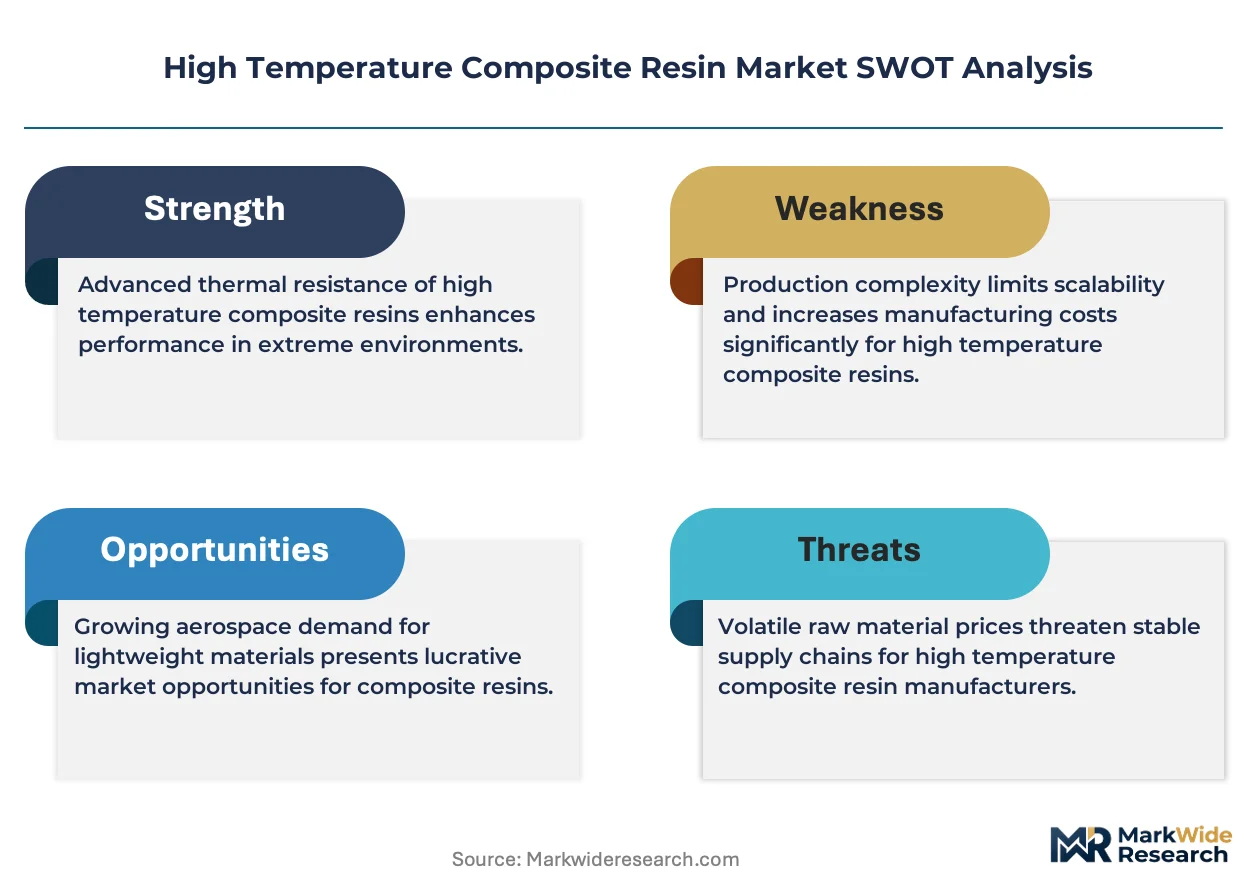
Aerospace procurement is hardening as the dominant demand vector for high temperature composite resins, displacing slower-growing industrial insulation segments. Solvay S.A. leverages its bismaleimide and polyimide chemistry portfolio to anchor European engine supply chains. Huntsman International LLC competes through advanced epoxy formulations optimized for automated fiber placement. Hexcel Corporation specializes in prepreg systems that dominate North American aerostructure tier-one contracts.
High temperature composite resins are thermosetting polymer matrices formulated to retain mechanical integrity above 180 degrees Celsius, typically incorporating aromatic heterocyclic structures or highly crosslinked epoxy backbones for oxidative stability in jet engine environments and exhaust-washed surfaces. Epoxy resins occupy the largest volume position due to processing familiarity and intermediate temperature performance, while bismaleimide captures premium margin pools in hot-zone aerostructures where polyimide processing costs remain prohibitive. Prepreg form factors command structural preference in aerospace for tack and drape control, though liquid resin infusion is penetrating automotive underhood applications where throughput economics favor out-of-autoclave cycles.
FAA airworthiness directives and EASA certification specifications for fire, smoke, and toxicity govern resin selection in commercial aviation interiors and propulsion systems, creating multi-year qualification barriers that freeze incumbent supplier relationships. EPA REACH-equivalent substance restrictions in Europe and emerging MEE environmental compliance protocols in China are forcing reformulation of legacy curing agents and solvent-based processing aids. Stakeholders must monitor how dual carbon regulatory trajectories in major manufacturing jurisdictions reshape feedstock availability and carbon accounting requirements for thermoset supply chains.
Market Dynamics
Aerospace engine qualification cycles are compressing procurement timelines for bismaleimide and polyimide resin systems, forcing suppliers to synchronize formulation development with FAA and EASA certification roadmaps. This structural acceleration is displacing legacy qualification cadences and concentrating contract awards among prepreg-integrated suppliers.
Growth Catalysts
- FAA flame-retardancy mandates:Stricter airworthiness directives for cabin interiors are accelerating resin system replacements. Airlines must comply with revised smoke and toxicity thresholds.
- Turbine blade manufacturing:Hot-section aerostructures demand bismaleimide prepregs capable of sustained operation above 180°C. Engine OEMs are expanding composite content in high-pressure compressors.
- Defense procurement synchronization:United States military aviation rebuild programs are aligning with commercial aerospace recovery. Dual-use resin specifications are streamlining supplier qualification.
Market Restraints
- Aromatic amine feedstock volatility:Curing agent precursors face supply concentration in Chinese and German chemical clusters. Price swings disrupt resin formulation cost models.
- REACH-equivalent substance restrictions:ECHA substance evaluation is forcing reformulation of legacy epoxy hardeners. European formulators face multi-year requalification timelines.
- Polyimide processing cost barriers:High-temperature cure cycles and specialized tooling limit adoption outside premium aerospace segments. Industrial applications remain locked in epoxy and bismaleimide.
Strategic Opportunities
- Automotive underhood thermal management:Electric vehicle battery enclosures and power electronics housings require 150-200°C continuous service. Liquid resin infusion offers throughput advantages over autoclave prepreg.
- China MEE environmental compliance:Dual carbon protocols are creating demand for low-VOC, solvent-free resin systems. Domestic formulators require Western technology transfer partnerships.
- Out-of-autoclave process convergence:Oven-curable bismaleimide formulations are integrating with automated fiber placement. This pairing reduces capital intensity for tier-two aerostructure suppliers.
Industry Challenges
- Multiyear certification timelines:FAA and EASA qualification protocols for new resin systems extend 36-60 months. Incumbent suppliers defend positions through specification lock-in.
- Specialized composite technician scarcity:Prepreg handling, freezer chain management, and cure cycle optimization require skills concentrated in aerospace manufacturing clusters. Workforce gaps constrain capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Composite Resin Market |
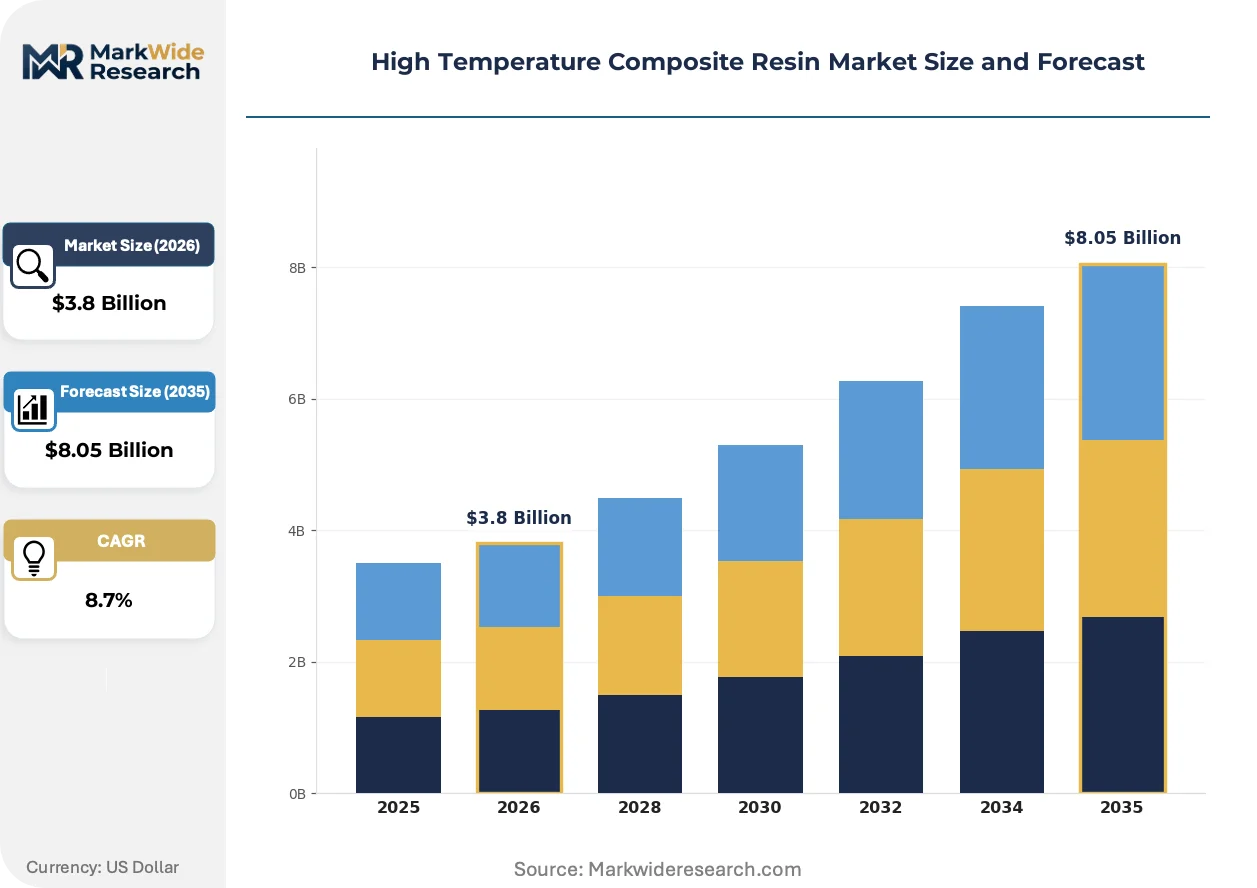
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Polyimide, Bismaleimide End User: Aerospace, Automotive, Electronics, Manufacturing Application: Structural Components, Insulation, Pressure Vessels, Composites Form: Prepreg, Liquid, Film, Powder |
| Companies Covered | Solvay S.A., Huntsman International LLC, Sumitomo Bakelite Co. Ltd., Royal TenCate N.V., Arkema S.A., Hexcel Corporation, Hexion Inc., Lonza AG, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Composite Resin Market Emerging Trajectories
Resin chemistry and processing technology are converging to enable higher-temperature performance at reduced manufacturing cost. Three developments are restructuring competitive positioning across aerospace and adjacent industrial segments.
Automated fiber placement systems are integrating with in-situ consolidation technologies for bismaleimide and thermoplastic composites. Tier-one aerostructure suppliers in the United States and France are deploying these lines for engine nacelle and thrust reverser components. The technology is compressing layup labor content and enabling complex geometries previously requiring hand collation.
REACH substance restrictions in Europe are forcing substitution of methylene dianiline and other legacy aromatic amine curing agents. ECHA authorization requirements are accelerating adoption of anhydride and phenalkamine alternatives in industrial epoxy formulations. German and French resin suppliers are reformulating standard product lines to maintain EU market access.
Long-term supply agreements with fixed-volume, variable-price structures are displacing spot procurement for aerospace-qualified prepreg. Tier-one aerostructure manufacturers in the United States are consolidating supplier panels and demanding inventory liability shifts. This procurement consolidation is visible in multi-year bismaleimide contracts tied to specific engine platform production rates.
High Temperature Composite Resin Market Segmentation
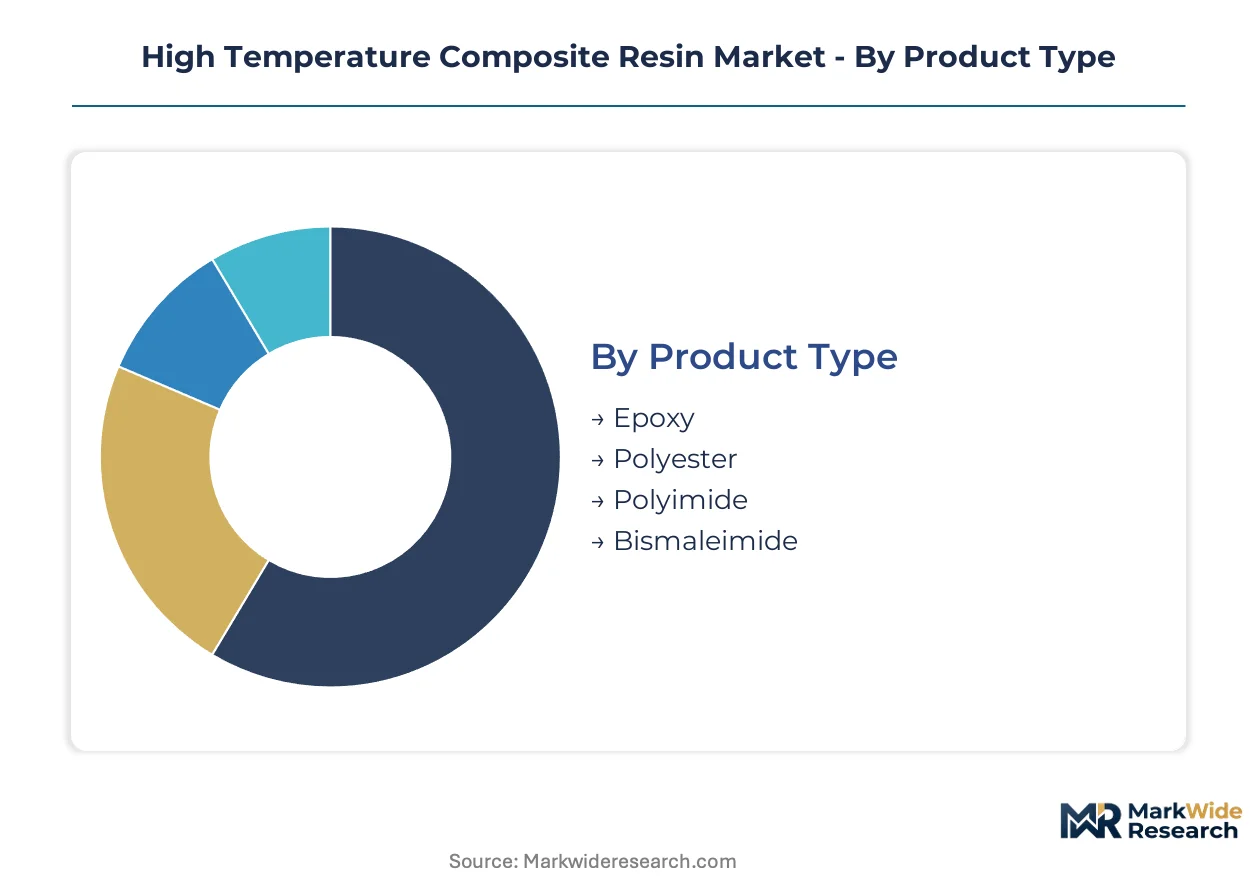
High temperature composite resin procurement varies sharply by thermal requirement, processing method, and qualification burden. Buyers select chemistries and forms based on specific end-use temperature thresholds, autoclave availability, and regulatory certification status.
Product Type:
Material selection hinges on the thermal-mechanical load envelope and acceptable processing cost.
- Epoxy:Crosslinked aromatic backbones deliver 180-200°C service capability with established autoclave processing protocols. Aerospace tier-one suppliers in the United States specify epoxy prepregs for nacelle skins and control surfaces where intermediate thermal performance suffices and qualification databases are mature.
- Bismaleimide:Maleimide-terminated oligomers achieve 230-290°C continuous operation through addition-cure chemistry that eliminates volatile condensation byproducts. Hot-section engine components including high-pressure compressor blades and exhaust fairings drive procurement from GE Aviation and Rolls-Royce supply chains.
- Polyimide:Condensation-cured heterocyclic structures offer 300°C+ capability but require prolonged high-temperature cure cycles and specialized tooling that restricts adoption to military engine programs and spacecraft thermal protection.
- Polyester:Unsaturated thermoset formulations serve industrial insulation and lower-temperature manufacturing fixtures where cost sensitivity outweighs thermal performance requirements.
Volume sits with epoxy; growth tilts toward bismaleimide.
End User:
Customer type determines specification stringency, contract duration, and inventory liability terms.
- Aerospace:FAA and EASA airworthiness directives mandate flame-retardant, low-smoke, low-toxicity formulations for cabin interiors and propulsion systems. Multi-year qualification timelines freeze supplier relationships and concentrate procurement among prepreg-integrated resin manufacturers.
- Automotive:Electric vehicle battery enclosures and power electronics housings require 150-200°C continuous service with throughput economics favoring liquid resin infusion over autoclave processing. OEMs in Germany and China are qualifying out-of-autoclave epoxy systems for underhood thermal management.
- Electronics:Printed circuit board substrates and semiconductor packaging demand thin-film polyimide with controlled coefficient of thermal expansion. Asian electronics manufacturing clusters in Taiwan and South Korea specify solvent-cast films for high-layer-count multilayer boards.
- Manufacturing:Industrial tooling, jigs, and fixtures utilize polyester and lower-grade epoxy systems where thermal cycling is moderate and replacement cycles are shorter.
Contract value concentrates in aerospace; expansion accelerates in automotive electrification.
Application:
Functional role dictates mechanical property requirements and damage tolerance specifications.
- Structural Components:Load-bearing aerostructures including wing skins, spars, and engine cowls require unidirectional or woven prepreg with fiber-dominated stiffness and compression-after-impact performance. Automated fiber placement lines in the United States and France process bismaleimide tape for complex curvature components.
- Composites:General composite fabrication spans non-critical aerostructures, industrial equipment housings, and recreational applications where standard epoxy laminates meet service requirements.
- Insulation:Thermal and electrical barrier applications in industrial equipment and electrical machinery utilize filled polyester and epoxy systems with ceramic additives for enhanced heat resistance.
- Pressure Vessels:Filament-wound tanks for aerospace propulsion and industrial gas storage demand high-strain epoxy and bismaleimide with automated winding compatibility and microcrack resistance under cyclic pressurization.
Structural applications dominate revenue; pressure vessels are climbing the fastest.
Form:
Processing infrastructure availability and part complexity govern form factor selection.
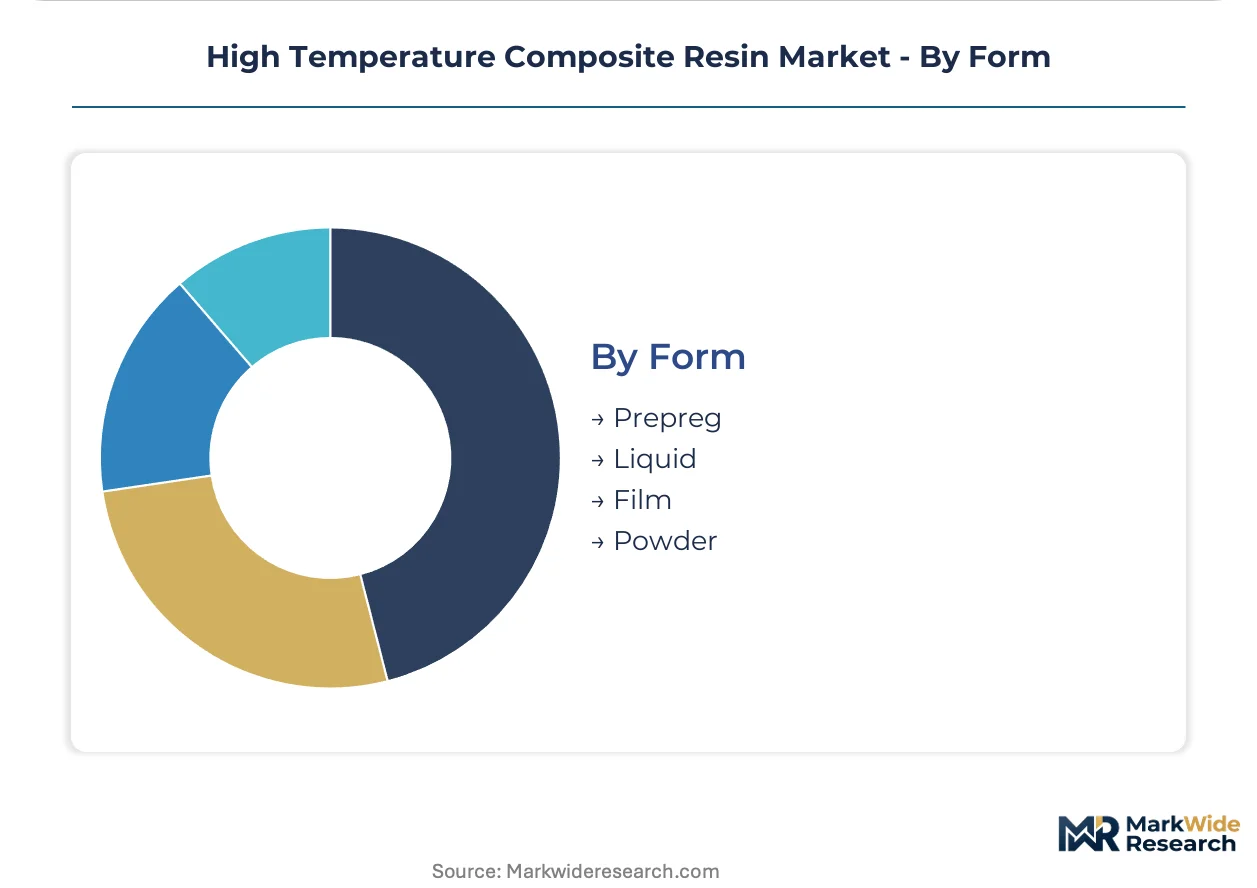
- Prepreg:Fiber-reinforced sheets with controlled resin content and tack properties enable hand layup and automated fiber placement with precise ply orientation. Freezer chain logistics and out-time tracking requirements concentrate supply among specialized manufacturers.
- Liquid:Two-component systems with metered mixing suit resin transfer molding and vacuum-assisted resin transfer molding for automotive and industrial components where autoclave capital is unavailable.
- Film:Unsupported resin films and adhesive layers bond sandwich core structures and integrate into multi-functional laminates for electronics and aerostructures.
- Powder:Solid resin particulates support compression molding and additive manufacturing approaches for complex geometries and localized reinforcement.
Prepreg commands aerospace share; liquid forms are gaining share fastest in automotive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special aerospace economic zones in the United States concentrate bismaleimide prepreg manufacturing near engine OEM final assembly lines. Defense procurement hubs and commercial aviation clusters synchronize resin demand across multiple jurisdictions.
United States
GE Aviation and Pratt & Whitney expand composite content in high-pressure compressor sections. FAA airworthiness directives for flame-retardant cabin materials compress qualification timelines. Cincinnati and Hartford manufacturing corridors anchor bismaleimide prepreg production for next-generation turbine programs.
Germany
Rolls-Royce Deutschland and MTU Aero Engines drive hot-section resin demand for European engine platforms. ECHA REACH substance restrictions force reformulation of aromatic amine curing agents. Munich and Stuttgart industrial clusters host specialized formulators adapting epoxy systems for EU environmental compliance.
China
Domestic engine programs and electric vehicle battery enclosures create dual demand vectors for high-temperature resins. MEE dual carbon protocols mandate low-VOC, solvent-free processing systems. Shanghai and Xi'an aerospace clusters attract Western technology partnerships for bismaleimide qualification.
France
Safran and Airbus consolidate composite aerostructure procurement through long-term prepreg agreements. EASA certification specifications govern resin selection for propulsion and interior applications. Toulouse and Nantes manufacturing basins specialize in automated fiber placement for engine nacelle components.
Japan
Toray Industries and Mitsubishi Heavy Industries integrate carbon fiber and resin capabilities for aerospace tier-one contracts. METI industrial policy supports domestic supply chain security for defense-critical materials. Nagoya and Tokyo industrial corridors concentrate prepreg manufacturing for regional jet and space applications.
High Temperature Composite Resin Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated prepreg suppliers commanding aerospace tier-one relationships while independent formulators serve industrial and automotive niches. The vendor base concentrates among European and North American chemical conglomerates with captive carbon fiber capabilities, creating tiered access to qualification databases. Three archetypes dominate: diversified materials conglomerates with full vertical integration, specialized resin formulators with aerospace certification depth, and Asian fiber-resin integrators leveraging scale economics. Competitive moves center on long-term supply agreements with fixed-volume structures and out-of-autoclave process technology licensing to tier-two suppliers.
Within the diversified conglomerate tier, Solvay S.A. and Huntsman International LLC exemplify European and North American positioning respectively, each anchoring distinct qualification ecosystems. Hexcel Corporation occupies a position among prepreg-integrated specialists with North American aerostructure concentration. These three represent the dominant competitive anchors around which tier-two formulators and regional Asian suppliers coordinate technology access and distribution partnerships.
| Leading Market Players |
|---|
| Solvay S.A. |
| Huntsman International LLC |
| Sumitomo Bakelite Co. Ltd. |
| Royal TenCate N.V. |
| Arkema S.A. |
| Hexcel Corporation |
| Hexion Inc. |
| Lonza AG |
| Toray Industries |
| Others |
Supply Flow & Price Mechanics
Automated fiber placement integration with oven-curable bismaleimide formulations is compressing capital requirements for tier-two aerostructure suppliers while simultaneously redistributing pricing power toward prepreg-integrated resin manufacturers with captive qualification databases. This production-method transition tightens margin capture among specialized formulators and amplifies cost differentials between autoclave-dependent and out-of-autoclave supply tiers.
Pricing Analysis
Short lead-time premiums for aerospace-qualified bismaleimide prepregs command substantial markups over standard-cycle contract pricing, while spot inventory availability in industrial epoxy grades trades at modest discounts. Contract-based long-term offtake structures dominate procurement between tier-one aerostructure manufacturers and resin suppliers, with price differentiation driven by certification tier and volume scale. Cost compression in industrial-grade epoxy segments is intensifying because REACH-equivalent substance restrictions force reformulation investments. Automotive OEMs exhibit the highest price sensitivity due to throughput economics favoring liquid resin infusion, while defense procurement programs demonstrate the lowest sensitivity given multi-year qualification lock-in.
Supply Chain Analysis
Domestic-content mandates in China's aerospace and electric vehicle sectors are reshaping sourcing patterns and compelling Western resin suppliers to establish local formulation partnerships or technology licensing arrangements. Raw material supply concentrates in the United States, Germany, and China, with aromatic amine curing agents and maleimide-terminated oligomers drawing from specialized chemical clusters in each jurisdiction. Feedstock volatility in Chinese and German aromatic amine production creates single-source vulnerability for epoxy hardener precursors. Distribution runs through direct long-term agreements between prepreg-integrated resin manufacturers and tier-one aerostructure OEMs, bypassing traditional chemical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FAA and EASA airworthiness directives erect multi-year qualification barriers that freeze incumbent supplier relationships and deflect unqualified competitors. These regulatory moats reward players with established certification databases and punish entrants lacking capital reserves for extended approval timelines.
For Market Incumbents: Deploy backward integration into aromatic amine curing agent production to insulate margin structures from feedstock volatility in Chinese and German chemical clusters. Anchor capacity expansion in Cincinnati and Hartford manufacturing corridors to synchronize with GE Aviation and Pratt & Whitney turbine program ramps. Consolidate supplier panel positions through inventory liability shifts onto tier-two aerostructure manufacturers seeking qualification access. For New Entrants and Emerging Players: Enter via automotive underhood thermal management segments where liquid resin infusion protocols bypass autoclave capital requirements and EASA certification timelines. Target electric vehicle battery enclosure applications in Germany and China where MEE environmental compliance and REACH-equivalent protocols create demand for low-VOC, solvent-free formulations. Pursue technology transfer partnerships with domestic Chinese formulators seeking Western bismaleimide qualification expertise. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified materials conglomerates seeking aerospace certification depth and prepreg-integrated supply capabilities. Five-to-ten-year viability hinges on positioning within engine OEM supply chains rather than industrial insulation segments. Monitor compression of FAA qualification timelines as the critical inflection signal—acceleration favors incumbents with mature databases, while extension creates entry windows for well-capitalized challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Curing Agent Production | Captive supply of aromatic amine precursors insulates Huntsman and Solvay from ECHA authorization disruptions. |
| Long-term Supply Agreement Restructuring | Fixed-volume, variable-price contracts with tier-one aerostructure OEMs lock in bismaleimide prepreg demand visibility. |
| Out-of-Autoclave Process Licensing | Technology transfer to tier-two suppliers expands addressable market for oven-curable bismaleimide formulations. |
| Joint Venture for China MEE Compliance | Domestic partnerships enable Western resin formulators to meet dual carbon protocols for solvent-free systems. |
| Capacity Expansion in Defense Procurement Corridors | Cincinnati and Hartford manufacturing basins align with synchronized US military and commercial aviation rebuild programs. |
Methodological Framework
SEC 10-K filings, ECHA substance evaluation databases, and FAA airworthiness directive archives formed the secondary backbone, cross-referenced with customs trade data and ACC industry reports. Primary interviews with prepreg manufacturing directors, aerospace procurement leads at tier-one aerostructure suppliers, resin formulation R&D heads, and automated fiber placement system operators validated secondary findings. Bottom-up and top-down triangulation reconciled volume estimates across chemistry types, form factors, and end-use applications.
Bottom-up modeling anchored volume projections across the analysis window, segmented by resin chemistry, processing form, thermal performance tier, and qualification status. Top-down demand validation incorporated engine OEM production rate forecasts and electric vehicle battery enclosure penetration assumptions. CAGRs were derived from slope analysis of year-over-year growth trajectories rather than single-point extrapolation. Industry-specific inputs included bismaleimide adoption curves in high-pressure compressor sections and out-of-autoclave process penetration rates in automotive underhood applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in FAA certification timelines or ECHA substance authorization schedules. Model assumptions reflect documented regulatory trajectories and disclosed OEM platform commitments without speculative scenario weighting. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Ultra-Lightweight Cement Composites Market
Composite Materials
Composite Preforms Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Global Lightweight Construction Material Market
Composite Materials
Core Material for Composites Market
Composite Materials
Global Composite Resin Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
United States Marine Composites Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Metal Matrix Composites (Mmcs) Market