
 China Marine Composites Market | 2026-2036
China Marine Composites Market Size, Share, and Industry Trends Forecast 2026-2036
China Marine Composites Market Intelligence
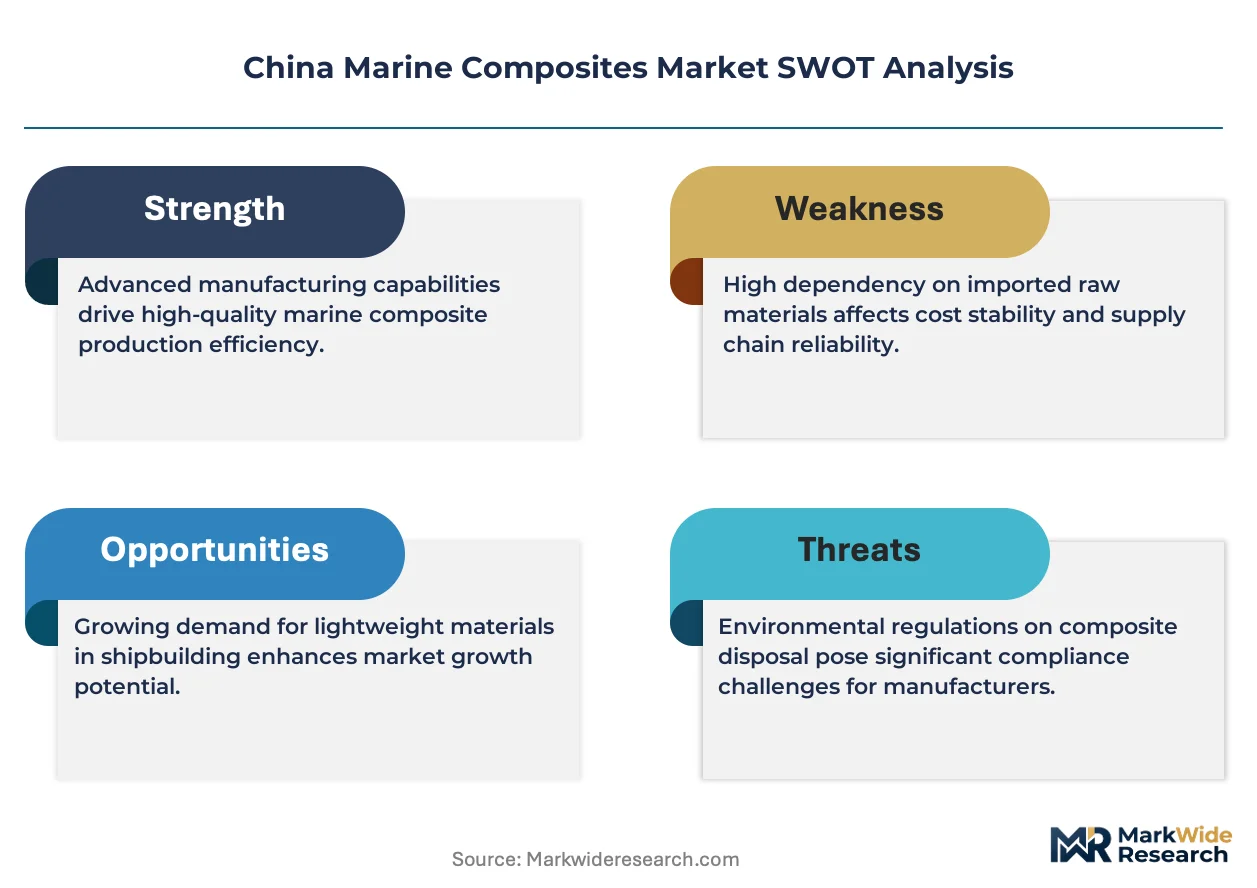
Asset-light leasing arrangements for high-performance prepreg equipment is rewriting capital barriers for mid-tier fabricators entering marine-grade production. China Jushi Co., Ltd. leverages its captive glass fiber supply to dominate domestic reinforcement feedstock. Huayuan Advanced Materials anchors its position through specialized epoxy formulations calibrated for saltwater immersion cycles. Owens Corning competes by extending its technical service footprint directly into Dalian and Zhoushan shipyard zones.
China marine composites encompass fiber-reinforced polymer systems engineered for hydrostatic load-bearing, corrosion resistance, and weight reduction in hull superstructures, typically specified with vinyl ester or epoxy matrices and glass or carbon fiber loadings between 40% and 70% by volume. Vacuum Infusion dominates yacht and patrol craft fabrication for its void-free laminate quality and volatile organic compound containment, while Filament Winding leads submarine pressure hull applications where circumferential strength uniformity is critical. Hand Lay-Up persists in fishing boat retrofit segments where tooling investment minimization outweighs labor intensity penalties.
MIIT's GB standards for vessel structural materials and MEE's shipyard emissions enforcement are tightening permissible styrene emissions during open-mold processes, forcing resin system upgrades toward low-VOC formulations. SAMR's certification protocols for marine construction materials are extending testing requirements for fire-retardant core structures in passenger-carrying vessels. Stakeholders must monitor how China's carbon intensity benchmarks for heavy industry cascade into composite procurement specifications across state-owned shipyard contracts.
Market Dynamics
Naval defense procurement is compressing qualification timelines for carbon fiber hull structures, forcing fabricators to reconfigure production lines around vacuum infusion protocols that satisfy military-grade void tolerance specifications.
Growth Catalysts
- Dual carbon goals under MEE:Shipyard emissions enforcement is accelerating resin system upgrades toward low-VOC formulations, creating pull-through demand for compliant prepreg systems.
- Yangtze River Delta cluster concentration:Jiangsu province's integrated supply chain density reduces logistics friction for hull superstructure fabricators serving state-owned shipyard contracts.
- Carbon fiber pressure hull adoption:Submarine programs are specifying circumferential filament winding for depth-rated structures, displacing conventional steel in deep-dive applications.
Market Restraints
- Epoxy resin price volatility:Feedstock benzene and propylene fluctuations transmit directly to marine-grade formulation costs, compressing margin buffers for mid-tier fabricators.
- Glass fiber supply concentration:Domestic reinforcement feedstock availability clusters around Zhejiang and Jiangsu provinces, creating geographic vulnerability to regional logistics disruptions.
- Fire-retardant core certification delays:SAMR's extended testing protocols for passenger-vessel sandwich structures elongate qualification cycles beyond typical contract award windows.
Strategic Opportunities
- Asset-light equipment leasing:Prepreg system rental models are lowering capital barriers for Yangtze Delta fabricators entering naval-grade production without full ownership burdens.
- Fishing boat retrofit segment:Hand lay-up persistence in coastal vessel refurbishment creates aftermarket service revenue streams for technical service providers.
- MIIT GB standards harmonization:Structural material certification alignment with international classification societies is opening export pathways for qualified Chinese hull fabricators.
Industry Challenges
- Vacuum infusion technician scarcity:Void-free laminate quality demands specialized process control expertise that outpaces vocational training program output in Dalian and Zhoushan shipyard zones.
- Multi-standard compliance complexity:Simultaneous satisfaction of MIIT structural codes, MEE emissions protocols, and military security clearances strains quality management system bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Marine Composites Market |
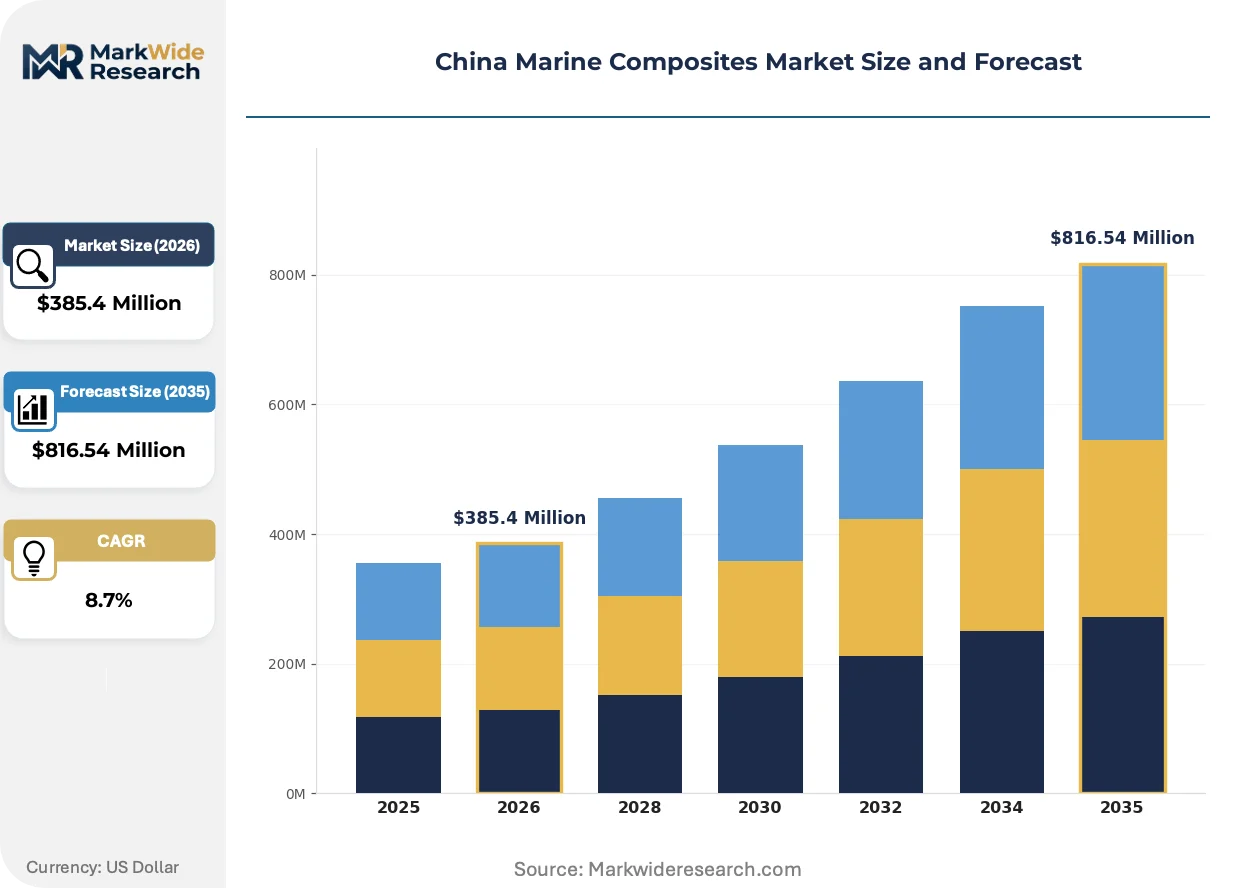
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Plastics, Honeycomb Structures, Laminates, Foam Cores Application: Yachts, Cargo Vessels, Fishing Boats, Submarines End User: Shipbuilders, Government Entities, Commercial Operators, Research Institutions Technology: Vacuum Infusion, Filament Winding, Resin Transfer Molding, Hand Lay-Up |
| Companies Covered | China Jushi Co., Ltd., Huayuan Advanced Materials, Toray Industries, Inc., Owens Corning, Hexcel Corporation, Gurit Holding AG, Mitsubishi Chemical Corporation, Jushi Group Co., Ltd., Xcellent Composites, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Marine Composites Market Strategic Shifts & Innovations
Material qualification protocols and emissions enforcement are converging to reshape process technology selection across Chinese shipyard operations. Fabricators now face simultaneous pressure for structural performance verification and environmental compliance.
Out-of-autoclave prepreg systems are collapsing the capital intensity barrier that previously excluded mid-tier fabricators from aerospace-grade quality tiers. Naval architects at state-owned design institutes are specifying these systems for patrol craft production. The technology is collapsing the historical segmentation between military and commercial hull fabrication capabilities.
MEE's shipyard emissions enforcement is eliminating open-mold styrene processes from newbuild contracts in Jiangsu and Zhejiang provinces. Resin suppliers are accelerating low-VOC vinyl ester formulation deployment to maintain qualified supplier status. Passenger-carrying vessel segments face the steepest compliance cost escalation as core structure fire testing extends under SAMR protocols.
Leasing arrangements for high-performance infusion equipment are displacing outright purchase in Yangtze River Delta fabrication yards. Mid-tier operators now access naval-grade production capability through operational expenditure models rather than capital deployment. Dalian and Zhoushan shipyard zones exhibit the fastest uptake of this procurement pattern as contract volatility discourages fixed asset commitment.
China Marine Composites Market Segmentation
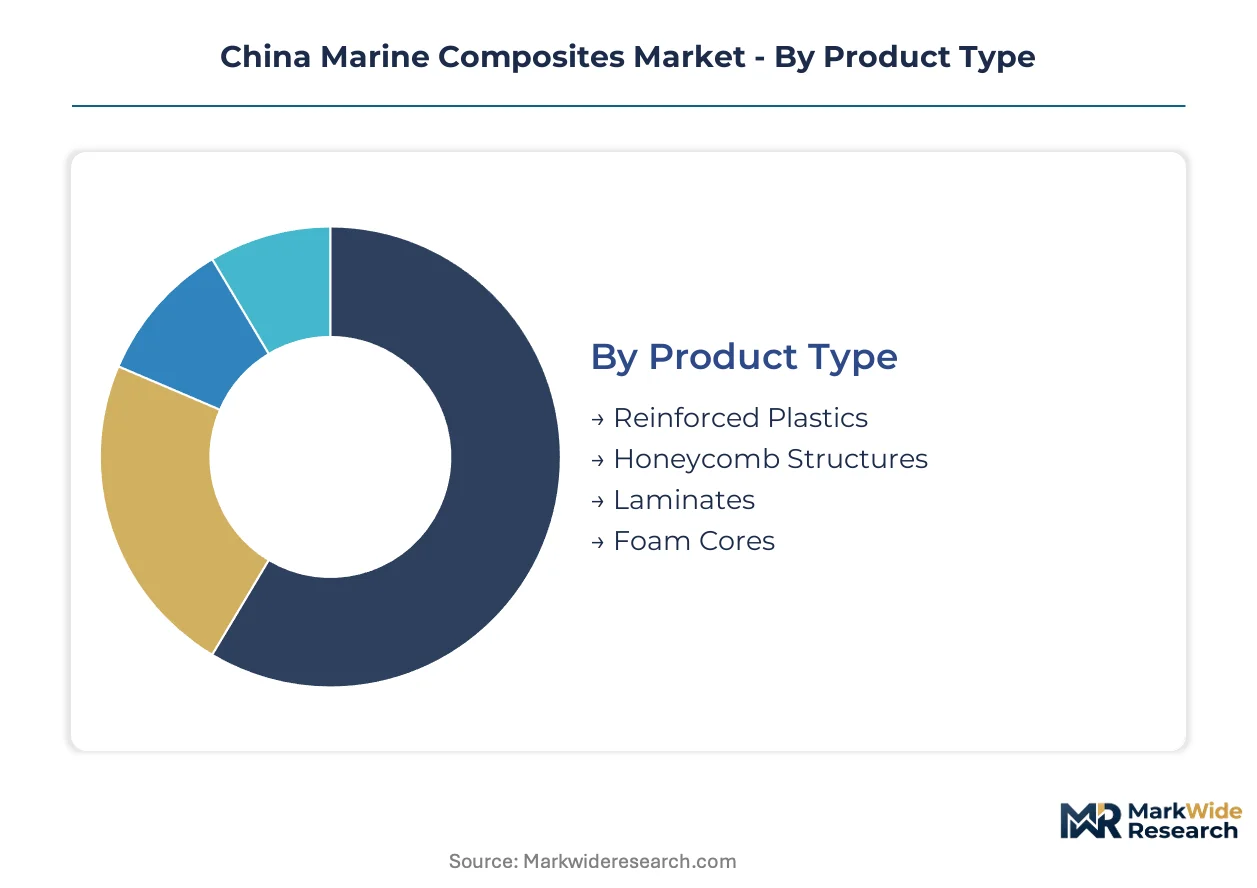
Segmentation in China marine composites reveals divergent procurement cycles across product categories and fabrication technologies. Cycle time variations from naval qualification timelines to fishing boat retrofit turnover create distinct competitive arenas for suppliers and fabricators.
Product Type:
Reinforced plastics turn inventory fastest in coastal retrofit yards, while honeycomb structures face extended certification cycles for passenger vessel applications.
- Reinforced Plastics:Glass or carbon fiber loadings between 40% and 70% by volume in vinyl ester or epoxy matrices dominate hull superstructure fabrication. Jiangsu province's Yangtze River Delta cluster consumes the majority for state-owned shipyard contracts under tightening MEE emissions enforcement.
- Honeycomb Structures:Aramid or aluminum honeycomb cores bonded with structural adhesives provide stiffness-to-weight optimization for deck panels and bulkheads. SAMR's extended fire-retardant testing protocols for passenger-carrying vessels elongate qualification cycles beyond typical contract windows.
- Laminates:Multi-ply fiber-reinforced sheets specified for abrasion-resistant surfaces in high-traffic marine zones.
- Foam Cores:Closed-cell polymer foams for sandwich panel construction in fishing boat refurbishment segments.
Reinforced plastics dominate installed base. Honeycomb structures are where expansion concentrates for next-generation naval hull programs.
Application:
Cost tier separation runs deepest between military submarine specifications and commercial fishing vessel retrofits, with yacht and cargo segments occupying intermediate procurement complexity.
- Yachts:Vacuum infusion fabrication delivers void-free laminate quality for premium hull superstructures. Dalian and Zhoushan shipyard zones specialize in high-performance yacht production with direct technical service support from international resin suppliers.
- Cargo Vessels:Scaled composite adoption focuses on non-structural applications including hatch covers and deck housings to reduce topside weight. MIIT's GB standards for vessel structural materials limit full composite hull deployment in heavy-load configurations.
- Fishing Boats:Hand lay-up persistence in coastal retrofit segments where tooling investment minimization outweighs labor intensity penalties and MEE styrene emissions enforcement is unevenly applied.
- Submarines:Filament-wound carbon fiber pressure hulls specified for deep-dive applications displace conventional steel in circumferential strength-critical zones.
Fishing boats anchor volume throughput. Submarines command the steepest expansion trajectory under naval procurement acceleration.
End User:
Customer type determines specification stringency, with government entities imposing multi-standard compliance that commercial operators rarely face.
- Shipbuilders:State-owned yards in Jiangsu and Zhejiang provinces drive specification-setting for domestic marine composites with integrated supply chain density reducing logistics friction.
- Government Entities:Naval procurement compresses qualification timelines for carbon fiber hull structures and mandates simultaneous satisfaction of MIIT structural codes, MEE emissions protocols, and military security clearances.
- Commercial Operators:Fishing fleet owners and coastal transport companies prioritize capital expenditure minimization in retrofit decisions.
- Research Institutions:State-owned design institutes specify out-of-autoclave prepreg systems for prototype patrol craft production.
Shipbuilders control procurement volume. Government entities are where technology qualification concentrates.
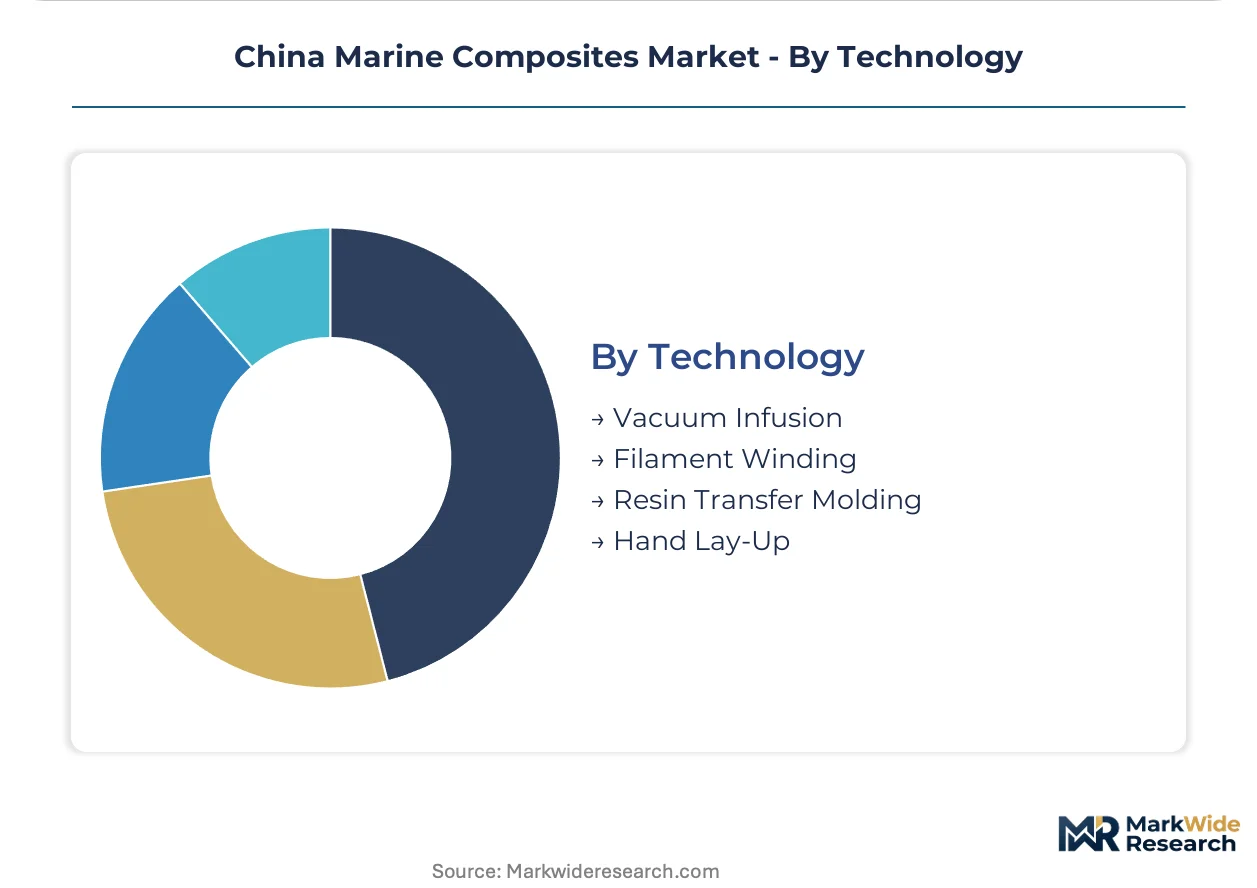
Technology:
Process maturity separates established open-mold methods from emerging closed-mold protocols reshaping competitive capability requirements.
- Vacuum Infusion:Closed-mold resin impregnation under vacuum pressure eliminates voids and contains volatile organic compounds for military-grade laminate quality. Technician scarcity in Dalian and Zhoushan shipyard zones constrains capacity expansion despite equipment leasing availability.
- Filament Winding:Automated fiber placement around rotating mandrels produces circumferential strength uniformity critical for submarine pressure hull applications. Naval programs specify this technology for depth-rated carbon fiber structures.
- Resin Transfer Molding:Closed-cavity injection suited for complex geometry marine components with controlled fiber volume fractions.
- Hand Lay-Up:Open-mold manual lamination persists where MEE emissions enforcement gaps exist and capital constraints dominate procurement decisions.
Hand lay-up retains installed base dominance in coastal retrofit segments. Vacuum infusion is gaining share fastest where emissions enforcement and naval qualification converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's marine composites trade flows reflect deepening import dependence for carbon fiber precursors alongside expanding domestic hull fabrication capacity serving regional export markets.
Yangtze River Delta
Jiangsu province concentrates vacuum infusion capacity for naval and yacht hull production. MEE emissions enforcement is eliminating open-mold styrene processes from Nantong and Taizhou shipyard zones. State-owned yards in Zhoushan anchor carbon fiber procurement for submarine pressure hull programs.
Pearl River Delta
Guangdong province's recreational boat builders drive demand for low-VOC vinyl ester formulations in premium yacht segments. SAMR fire-retardant certification protocols extend qualification timelines for Shenzhen and Zhuhai fabricators serving passenger vessel contracts. The cluster specializes in honeycomb core integration for deck panel systems.
Beijing-Tianjin-Hebei
Research institutions in this corridor specify out-of-autoclave prepreg systems for prototype naval craft. MIIT's GB standards harmonization efforts originate from Beijing-based certification bodies. Tianjin port logistics handle carbon fiber precursor imports for redistribution to eastern fabrication centers.
Shandong Peninsula
Qingdao and Yantai fishing boat retrofit yards sustain hand lay-up process dominance where MEE enforcement gaps persist. Coastal vessel refurbishment generates aftermarket reinforcement demand. The region's glass fiber processing capacity feeds downstream hull fabricators.
Dalian Shipyard Zone
Liaoning province's military-industrial complex compresses qualification timelines for filament-wound submarine structures. Technician scarcity constrains vacuum infusion expansion despite equipment leasing availability. Dalian yards specialize in depth-rated carbon fiber pressure hull fabrication.
China Marine Composites Market Key Industry Players
On the supply side, the industry is bifurcated between state-linked reinforcement producers and international resin specialists competing through technical service proximity. Domestic glass fiber supply concentrates around Zhejiang and Jiangsu provinces, while epoxy formulation expertise clusters with multinational chemical firms. Three archetypes dominate: captive fiber producers with backward integration into raw materials, specialized resin compounders with saltwater-calibrated formulations, and technical service providers embedding directly in shipyard zones. Competitive moves center on equipment leasing models that collapse capital barriers for mid-tier fabricators, and geographic expansion of application engineering teams into Dalian and Zhoushan production zones.
Among domestic reinforcement producers, China Jushi Co., Ltd. and Jushi Group Co., Ltd. exemplify the captive fiber archetype with integrated glass fiber supply chains. Huayuan Advanced Materials occupies a position among specialized resin compounders focused on marine-grade epoxy systems. International players including Owens Corning and Hexcel Corporation represent the technical service-intensive tier, embedding application engineering directly in Yangtze River Delta shipyard clusters to capture naval and yacht specification-setting influence.
| Leading Market Players |
|---|
| China Jushi Co., Ltd. |
| Huayuan Advanced Materials |
| Toray Industries, Inc. |
| Owens Corning |
| Hexcel Corporation |
| Gurit Holding AG |
| Mitsubishi Chemical Corporation |
| Jushi Group Co., Ltd. |
| Xcellent Composites |
| Others |
Cost & Logistics Intelligence
Overcapacity in Zhejiang province's glass fiber processing plants is compressing reinforcement feedstock margins and forcing resin suppliers to absorb benzene-propylene volatility rather than pass through costs to Yangtze Delta hull fabricators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for naval-grade prepreg systems. Three-tier pricing structure across military-certified, commercial marine, and fishing retrofit tiers separates qualified suppliers from commodity resin distributors. Cost compression in commercial marine segments is intensifying because MEE emissions enforcement is eliminating open-mold styrene processes. Fishing fleet operators exhibit highest price sensitivity; state-owned shipyards show lowest sensitivity due to security-cleared supplier mandates.
Supply Chain Analysis
China Jushi and Jushi Group hold captive glass fiber capacity across Zhejiang and Jiangsu provinces. Raw material flows draw from domestic benzene-propylene feedstocks and imported carbon fiber precursors through Tianjin port redistribution. Single-source vulnerability concentrates in carbon fiber precursor dependence on Japanese and South Korean suppliers. Distribution runs through state-owned shipyard procurement offices with direct technical service embedding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as naval procurement acceleration and commercial emissions enforcement create divergent capability requirements that no single supplier archetype can satisfy simultaneously.
For Market Incumbents: Build certification moats around SAMR fire-retardant core testing protocols and MIIT GB structural material approvals. Secure backward integration into low-VOC vinyl ester formulation capacity to defend against resin price volatility. Extend technical service teams into Dalian and Zhoushan zones where vacuum infusion technician scarcity constrains rival expansion. For New Entrants and Emerging Players: Build out equipment-leasing service models targeting mid-tier Yangtze Delta fabricators seeking naval-grade capability without capital deployment. Fishing boat retrofit segments in Shandong Peninsula offer most penetrable entry point where MEE enforcement gaps persist and hand lay-up dominates. Lead with aftermarket technical service rather than resin supply to establish shipyard relationships. For Investors and Strategic Acquirers: Capital is best deployed toward specialized resin compounders with saltwater-calibrated epoxy formulations and existing SAMR certification pathways. Long-term viability favors suppliers positioned at intersection of military security clearance and commercial emissions compliance. Watch for naval procurement timeline compression as inflection signal accelerating qualification-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-VOC Formulation Capacity | Captures margin from benzene-propylene volatility while satisfying MEE emissions protocols. |
| Equipment Leasing Model Expansion | Collapses capital barriers for mid-tier fabricators entering naval-grade vacuum infusion production. |
| SAMR Fire-Retardant Certification Investment | Extends qualification timelines that exclude unqualified rivals from passenger vessel contracts. |
| Technical Service Embedding in Dalian-Zhoushan Zones | Addresses vacuum infusion technician scarcity while capturing specification-setting influence. |
| Carbon Fiber Precursor Supply Agreement | Mitigates single-source vulnerability through diversified import channels via Tianjin logistics. |
Research Approach
Operator-level perspectives from hull fabrication plant managers, state-owned shipyard procurement officers, resin supplier technical directors, and MEE compliance auditors anchored the qualitative base. Primary fieldwork combined with secondary validation from MIIT GB standards documentation, SAMR certification protocols, customs trade data on carbon fiber precursor imports, and SEC filings of multinational chemical firms. Bottom-up hull production estimates triangulated against top-down naval procurement budget allocations.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, fabrication technology, end-user archetype, and regional shipyard cluster. CAGRs derived from production capacity buildout timelines and naval program acceleration curves. Forecast inputs incorporated MEE enforcement phase-in schedules and SAMR testing protocol extensions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-linked reinforcement producers into resin formulation would shift outcomes. Quarterly review of naval procurement timeline compression and carbon fiber precursor import volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Graphite Felt Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Turbine Blade Material Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Expandable Graphite Market
Composite Materials
Composite Rollers Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Global Composite Resin Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Global Sports Composites Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
Phenolic Panel Market