
 Plastic Composites Market | 2026-2036
Plastic Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Composites Market Analytics
Multi-source resin procurement is consolidating across the plastic composites value chain as compounders seek supply security amid petrochemical volatility. Hybron leverages backward integration into polymer compounding to control raw material quality for aerospace grades. Epsilon Composite sustains its position through filament winding specialization for pressure vessel applications. Arris Composites differentiates via automated fiber placement technology that reduces scrap rates in complex geometries.
Plastic composites are engineered materials combining polymer matrices with reinforcing fibers or fillers to achieve specific strength-to-weight ratios, thermal stability, or electrical properties, typically manufactured through injection molding, compression molding, or pultrusion processes. Thermoplastic composites dominate volume consumption due to recyclability advantages and faster cycle times in automotive serial production. The aerospace application segment commands premium pricing through qualification-intensive carbon fiber prepreg systems. Among fabrication methods, pultrusion occupies a mature niche in construction profiles while filament winding captures growth in hydrogen storage tanks.
REACH in Europe governs chemical substance registration and restricts hazardous additives in composite formulations, while the EPA in the United States enforces emissions standards that favor lighter vehicle materials. China's GB standards under SAMR mandate flame retardancy ratings for construction applications, creating compliance barriers for imported compounds. Stakeholders must monitor evolving Extended Producer Responsibility frameworks that will reshape end-of-life economics for thermoset materials.
Market Dynamics
Thermoplastic composite adoption in automotive structural components is compressing cycle times and forcing thermoset suppliers to defend position through aerospace qualification barriers. Material substitution toward bio-based resin systems is accelerating as compounders backward-integrate into polymer production to secure supply.
Growth Catalysts
- REACH chemical safety revisions:The EU's revised framework restricts hazardous additives in composite formulations. Automotive OEMs in Germany are accelerating thermoplastic substitution to maintain market access.
- EV production clustering:Integrated compounding-to-molding facilities in China's eastern manufacturing corridor serve domestic electric vehicle demand. This concentration reduces logistics costs for lightweight battery enclosure components.
- Filament winding specialization:Pressure vessel manufacturers are expanding hydrogen storage tank capacity. The technology enables Type IV composite tanks that meet automotive safety standards.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and epoxy resin prices fluctuate with crude oil markets. Compounders without captive supply face margin compression during spike periods.
- Carbon fiber supply concentration:Precursor production clusters in Japan and the United States create geographic vulnerability. Aerospace qualification requirements lock buyers into single-source arrangements.
- Thermoset recyclability limitations:Cross-linked polymer matrices cannot be remelted for reuse. Extended Producer Responsibility frameworks in Europe will impose end-of-life cost burdens on original manufacturers.
Strategic Opportunities
- Automated fiber placement:Robotics integration with thermoplastic tape laying reduces scrap in complex geometries. Aerospace tier suppliers are retrofitting facilities to capture this efficiency gain.
- Construction pultrusion expansion:Infrastructure rehabilitation programs in Germany and Japan specify fiberglass-reinforced profiles. Window and door frame applications offer volume scale absent aerospace qualification delays.
- Bio-based resin formulation:Epoxy alternatives derived from lignin or plant oils address Scope 3 emissions reporting. Consumer electronics brands are specifying these materials for enclosure components.
Industry Challenges
- Composite technician scarcity:Filament winding and automated fiber placement require specialized programming skills. Vocational pipelines in Germany and Japan cannot match facility expansion rates.
- Qualification timeline compression:Aerospace OEMs demand faster material certification for new programs. Testing protocols for carbon fiber prepreg systems extend 18-24 months despite program pressure.
- Multi-material joining complexity:Dissimilar coefficient of thermal expansion between composites and metals creates assembly stress. Automotive engineers struggle with adhesive selection for hybrid body-in-white structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Composites Market |
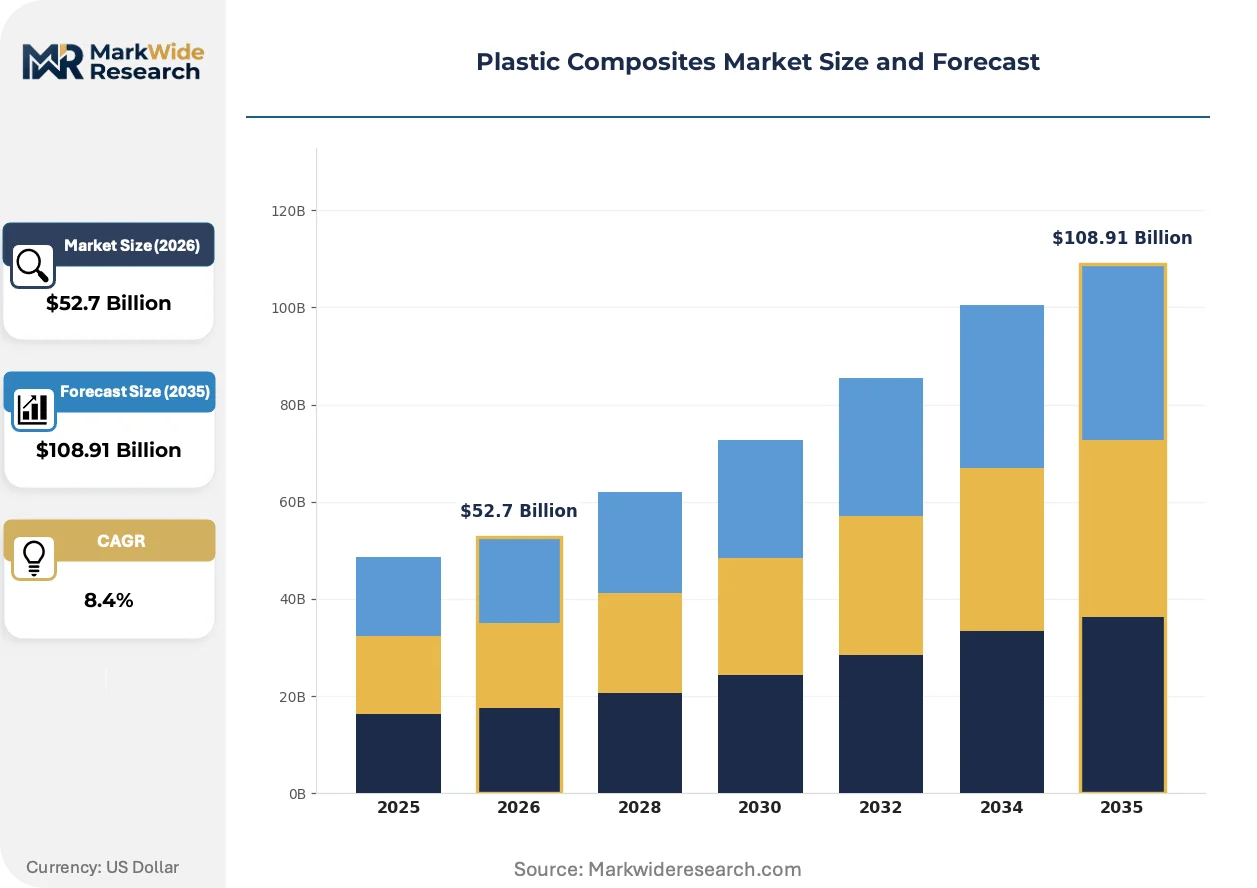
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Composites, Thermosetting Composites, Filled Composites, Hybrid Composites Application: Aerospace, Automotive, Construction, Consumer Goods End User: OEMs, Tier-1 Suppliers, Manufacturers, Assemblers Fabrication Method: Injection Molding, Compression Molding, Filament Winding, Pultrusion |
| Companies Covered | Hybron, Epsilon Composite, Arris Composites, Magnum Venus Products, Continental Corp. USA, Soarce, Inc., KraussMaffei, CompoTech, Raven Space Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Composites Market Evolving Landscape
Continuous fiber-reinforced thermoplastic tapes are displacing short-fiber compounds in load-bearing automotive applications. Manufacturing technology convergence is collapsing the traditional separation between compounding and final forming operations.
Recyclable thermoplastic composites are rewriting material specification protocols in serial automotive production. BMW and Mercedes-Benz structural engineers are specifying unidirectional tape layups for battery tray assemblies. The shift is compressing supplier qualification cycles from aerospace timelines toward automotive speed.
REACH authorization requirements for SVHC substances are forcing reformulation of flame-retardant epoxy systems. Compounders serving construction applications must eliminate halogenated additives to maintain EU market access. German window profile manufacturers are accelerating bio-based intumescent coating development.
Specification authority is migrating from tier suppliers to OEM material engineering teams. Direct procurement of pre-impregnated tapes bypasses traditional distributor channels. This disintermediation is most advanced in Germany, where Volkswagen and BMW operate captive composite research centers.
Plastic Composites Market Segmentation
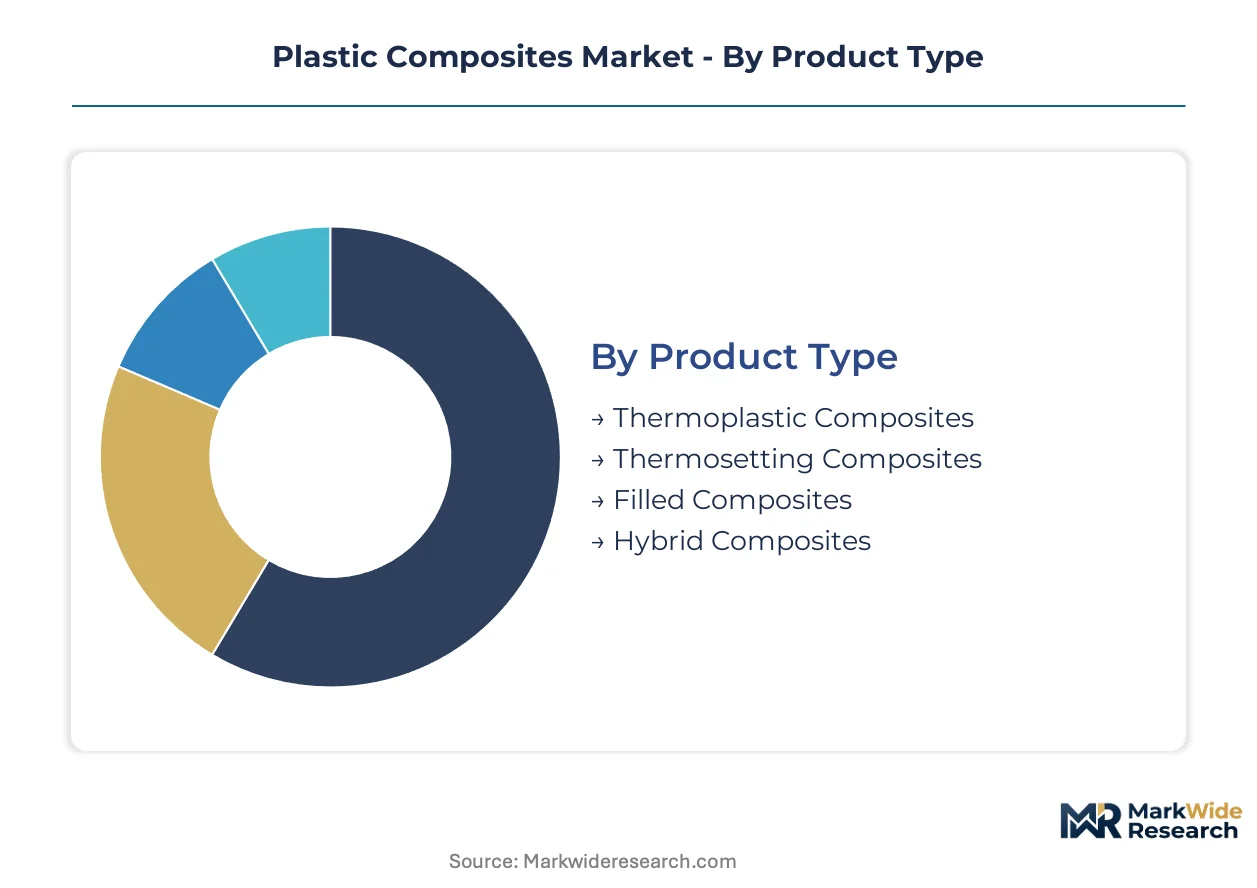
Segmentation in plastic composites reveals how supply chain configuration and fabrication economics shape competitive positioning across material classes and end-use verticals. Understanding these divisions exposes where margin pools concentrate and where substitution threats emerge.
Product Type:
Supply concentration in polymer compounding clusters favors integrated producers who control resin formulation and fiber impregnation within single facilities.
- Thermoplastic Composites:Polymer matrices such as polypropylene or PEEK reinforced with continuous glass or carbon fibers enable rapid cycle times and post-consumer recyclability. Automotive OEMs in Germany specify these for battery enclosures and structural seat pans to meet EU end-of-life directives.
- Thermosetting Composites:Cross-linked epoxy or polyester systems deliver dimensional stability under sustained thermal load. Aerospace qualification protocols for carbon fiber prepreg systems lock buyers into single-source arrangements with Japanese and US precursor suppliers, creating geographic vulnerability.
- Filled Composites:Short-fiber or mineral-filled compounds serve cost-sensitive applications where modulus requirements are moderate.
- Hybrid Composites:Multi-material systems combining thermoplastic and thermoset layers optimize performance-to-cost ratios in select construction profiles.
Today's leader: Thermoplastic Composites. Tomorrow's challenger: Thermosetting Composites.
Application:
Cost tier differentiation separates qualification-intensive aerospace programs from high-volume automotive serial production.
- Automotive:Structural components including battery trays, bumper beams, and seat structures leverage continuous fiber-reinforced tapes for weight reduction. China's eastern manufacturing corridor concentrates demand where integrated compounding-to-molding clusters serve domestic EV production.
- Aerospace:Primary and secondary structures require carbon fiber prepreg systems meeting FAA and EASA certification standards. Boeing and Airbus material specifications drive multi-year qualification timelines that protect incumbent suppliers.
- Construction:Pultruded fiberglass profiles gain specification in infrastructure rehabilitation programs across Germany and Japan.
- Consumer Goods:Electronics enclosures and sporting equipment utilize short-fiber compounds where surface finish and cost dominate selection criteria.
Automotive applications are climbing the fastest as EV platform architectures multiply material insertion points.
End User:
Customer type determines procurement sophistication and specification authority within the value chain.
- OEMs:Original equipment manufacturers in automotive and aerospace increasingly direct-source pre-impregnated tapes and molding compounds, bypassing traditional distributor channels. Volkswagen and BMW operate captive composite research centers in Germany.
- Tier-1 Suppliers:System integrators manage sub-assembly fabrication and multi-material joining operations for hybrid body-in-white structures.
- Manufacturers:Compounders and converters operate compounding lines and molding presses under contract or toll arrangements.
- Assemblers:Final assembly operations focus on adhesive bonding and mechanical fastening of composite components into finished products.
Specification authority migrates upward: OEMs tighten grip on material selection. Tier-1 Suppliers defend position through assembly integration.
Fabrication Method:
Volume scale and geometric complexity dictate process selection across the maturity spectrum.
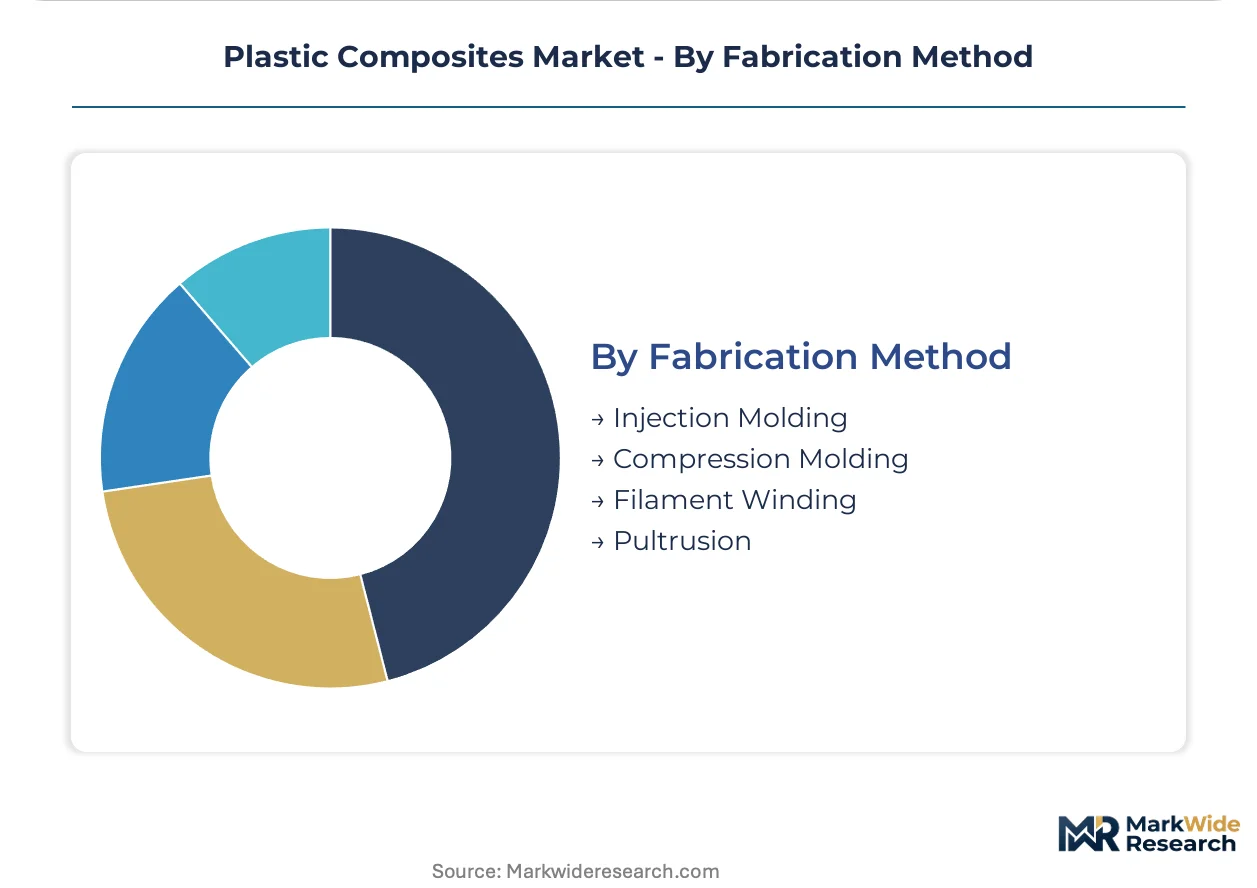
- Injection Molding:High-pressure processing of short-fiber compounds enables complex geometries with cycle times measured in seconds. Mass production of consumer electronics housings and automotive interior components concentrates in Chinese molding clusters.
- Filament Winding:Automated fiber placement around mandrels produces pressure vessels and cylindrical structures. Hydrogen storage tank manufacturers in Germany and Japan expand Type IV composite capacity to meet automotive safety standards.
- Compression Molding:Matched-die forming of sheet molding compound serves medium-volume automotive panels and construction elements.
- Pultrusion:Continuous pulling of resin-impregnated fiber through heated dies yields standardized profiles for window frames and structural sections.
Mature incumbent: Injection Molding. Steepest expansion trajectory: Filament Winding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor anchors plastic composites demand through integrated compounding-to-molding clusters serving domestic EV production. Automotive OEMs in Germany and Japan drive thermoplastic adoption for lightweight structural components. Regulatory pressure from the EU's revised REACH framework accelerates material substitution toward bio-based resin systems across manufacturing hubs.
China
Battery enclosure demand from NIO, BYD, and Tesla Shanghai operations consumes continuous fiber-reinforced thermoplastic tapes. GB standards under SAMR mandate flame retardancy ratings for construction applications, creating compliance barriers for imported compounds. The Yangtze River Delta concentrates integrated facilities where Sinopec and private compounders co-locate compounding lines with automotive molding presses.
Germany
Volkswagen and BMW structural engineers specify unidirectional tape layups for battery tray assemblies to meet EU end-of-life directives. The KBA enforces vehicle safety standards that favor lightweight materials in crash-critical applications. Bavaria hosts captive composite research centers where OEM material engineering teams direct-source pre-impregnated tapes, bypassing traditional distributor channels.
United States
Boeing and Lockheed Martin qualification protocols for carbon fiber prepreg systems protect incumbent aerospace suppliers through 18-24 month certification timelines. The EPA enforces emissions standards that favor lighter vehicle materials in commercial transportation. The Pacific Northwest clusters precursor production and aerospace tier suppliers near Boeing's Everett and Renton manufacturing sites.
Japan
Toray and Teijin precursor production concentrates in Chubu and Kansai regions, creating geographic vulnerability for global carbon fiber supply. METI promotes hydrogen infrastructure deployment that expands Type IV composite tank demand from automotive OEMs. Nagoya-area filament winding specialists serve Toyota and Honda pressure vessel programs under tight qualification arrangements.
South Korea
Hyundai and Kia EV platform architectures multiply material insertion points for structural composites in battery enclosures and body panels. The MFDS maintains medical device standards that influence biocompatible composite formulations for healthcare applications. The Seoul Capital Area concentrates molding operations for consumer electronics housings serving Samsung and LG supply chains.
Plastic Composites Market Competitive Landscape
Global majors compete with regional champions across qualification-intensive aerospace segments and high-volume automotive supply chains. The vendor base stratifies between integrated polymer compounders controlling resin formulation and specialized fabricators focused on single-process excellence. Three archetypes dominate: backward-integrated resin producers, filament winding specialists, and automated fiber placement technology providers. Competitive moves center on captive supply arrangements and robotics integration for scrap reduction.
Among aerospace-tier suppliers, Hybron exemplifies backward integration into polymer compounding for quality control. Epsilon Composite occupies a specialist position in filament winding for pressure vessel applications. Arris Composites represents the automated manufacturing tier with fiber placement technology reducing geometric complexity scrap. These three anchors illustrate how capability concentration shapes competitive positioning without vertical integration mandates.
| Leading Market Players |
|---|
| Hybron |
| Epsilon Composite |
| Arris Composites |
| Magnum Venus Products |
| Continental Corp. USA |
| Soarce, Inc. |
| KraussMaffei |
| CompoTech |
| Raven Space Systems |
| Others |
Value Network & Pricing Analysis
Backward integration into polymer compounding anchors both supply security and pricing power for aerospace-grade producers, as captive resin formulation insulates margin structures from petrochemical volatility while locking in qualification-dependent buyers under long-term offtake arrangements.
Pricing Analysis
Input-cost pass-through from polypropylene and epoxy resin markets governs contract negotiations, with compounders indexing quarterly adjustments to crude oil benchmarks. Pricing stratifies across aerospace qualification tiers, automotive volume scales, and construction commodity grades. Cost compression in standard thermoplastic compounds is intensifying because Chinese integrated producers are expanding compounding-to-molding capacity. Automotive OEMs exhibit highest price sensitivity, while aerospace buyers accept premiums for carbon fiber prepreg systems with locked-in precursor supply.
Supply Chain Analysis
China's GB standards under SAMR and local-content preferences in EV procurement are reshaping sourcing patterns toward domestic compounders. Raw material flows draw from Japanese and US carbon fiber precursor production, German polymer compounding clusters, and Chinese integrated molding facilities. Single-source vulnerability concentrates in aerospace-qualified carbon fiber supply. Distribution runs through direct OEM procurement channels that bypass traditional distributor networks, particularly in Germany where Volkswagen and BMW operate captive sourcing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical safety revisions in Europe and GB construction standards in China create a geographic-arbitrage opportunity, as compounders with dual-qualified production lines can capture margin premiums from buyers facing asymmetric compliance burdens.
For Market Incumbents: Hedge against bio-based resin substitution by securing lignin-derived epoxy supply partnerships before agricultural processors lock in offtake. Deepen captive precursor arrangements with Toray or Teijin to defend aerospace qualification barriers against emerging filament winding specialists.
For New Entrants and Emerging Players: Capture construction pultrusion demand in Germany and Japan where infrastructure rehabilitation programs specify fiberglass-reinforced profiles absent aerospace certification delays. Lead with automated fiber placement technology to reduce scrap rates and win tier supplier retrofit contracts.
For Investors and Strategic Acquirers: Roll-up economics work for regional filament winding specialists because hydrogen storage tank demand is fragmenting across automotive OEM programs without scale concentration. Watch for Type IV tank qualification approvals as the inflection signal for capacity valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Hybron controls resin quality for aerospace grades, reducing qualification risk. |
| Filament Winding Capacity Expansion | Epsilon Composite captures hydrogen tank demand from Toyota and Honda programs. |
| Automated Fiber Placement Technology | Arris Composites reduces geometric scrap in complex automotive battery enclosures. |
| Bio-Based Resin Formulation | Lignin-derived epoxies address EU Scope 3 reporting for construction profiles. |
| Direct OEM Procurement Channels | Bavarian research centers bypass distributors, compressing supplier margins. |
Research Methodology
Coverage spans China, Germany, Japan, and the United States, with primary inputs from each market combining interviews with polymer compounding plant managers, automotive OEM procurement leads, aerospace tier supplier technical directors, and construction profile distributors. Secondary validation draws from SAMR GB standards filings, REACH authorization databases, ECHA SVHC substance lists, and customs trade data for carbon fiber precursor flows. Bottom-up facility capacity assessments triangulate against top-down end-use consumption models.
Rate-of-change decomposition separates volume drivers from price mix effects across the projection horizon. Segmentation dimensions include product type, application vertical, fabrication method, and regional production hub clustering. CAGRs derive from fitted growth curves applied to qualified demand segments, with hydrogen storage tank capacity buildouts and EV battery enclosure specifications as industry-specific forecast inputs.
Petrochemical feedstock volatility, REACH substance authorization delays, and carbon fiber precursor supply disruptions are the dominant revision risks to modeled outputs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Preforms Market
Composite Materials
Case Material Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Global Composite Resin Market
Composite Materials
Pultrusion Market
Composite Materials
Composite Rollers Market
Composite Materials
FRP Grating Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
CFRTP Market
Composite Materials
Composite Process Material Kits Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
GCC Decorative Laminates Market