
 Global Carbon Fiber Resin Market | 2026-2036
Global Carbon Fiber Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Fiber Resin Market Foresight
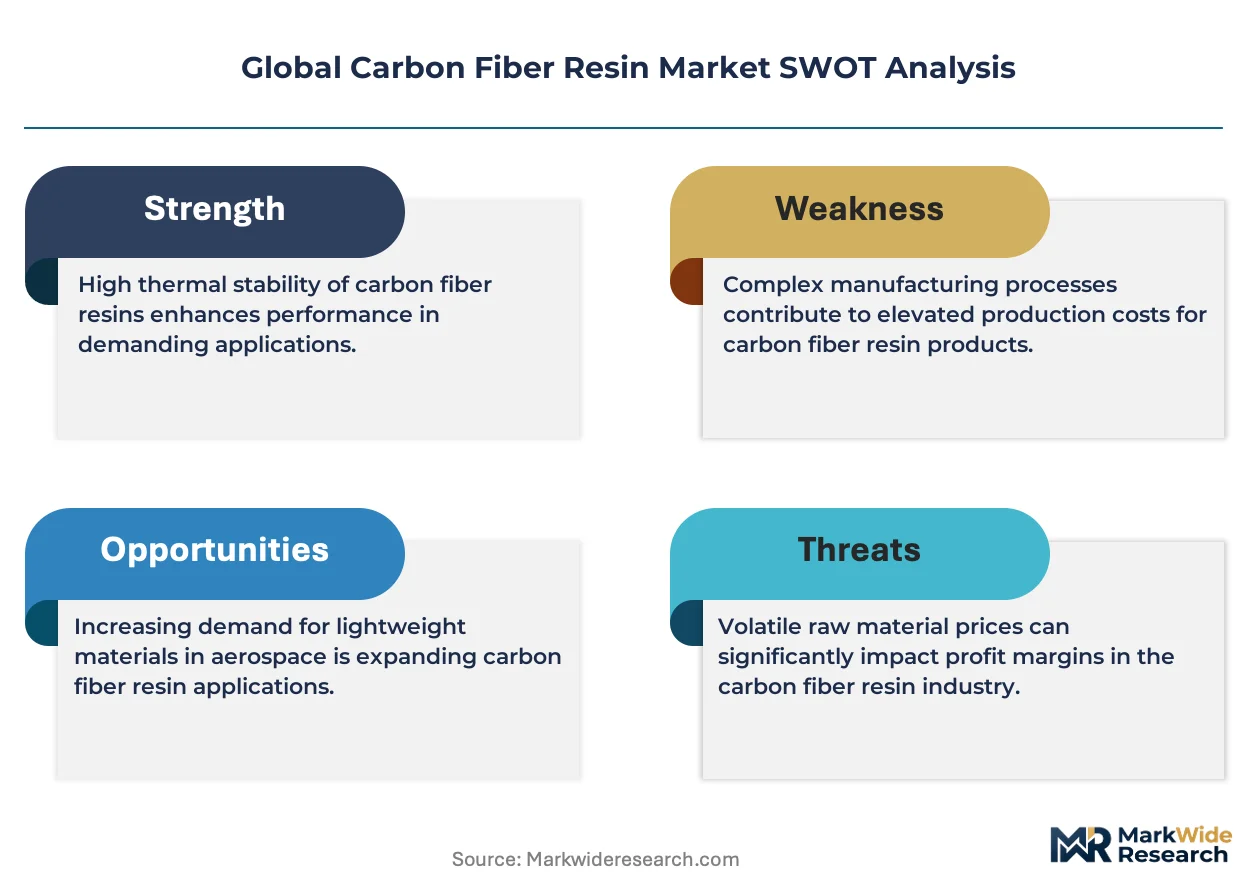
High-modulus epoxy specification tiers is rotating toward dominance as aerospace and wind OEMs reject lower-grade formulations for primary structural loads. Huntsman Corporation leverages captive amine hardener supply to lock in margin at the resin-to-curing-agent interface. Hexion Inc. anchors North American wind blade contracts through bisphenol-A-free epoxy platforms. Westlake Epoxy Inc. competes on phenolic resin thermal stability for brake friction and high-temperature industrial applications.
Carbon fiber resin denotes thermoset and thermoplastic polymer matrices formulated to impregnate, bind, and transfer load between carbon fiber filaments in composite laminates, with glass transition temperatures typically exceeding 120°C for structural grades and cure cycles tuned to prepreg out-time or resin transfer molding viscosity windows. The material enables stiffness-to-weight ratios unobtainable in metals for primary structures. Epoxy resin commands the largest volume share across aerospace and wind energy applications where fatigue resistance and fiber adhesion outweigh cost premiums. Prepreg manufacturing process retains margin concentration due to refrigerated supply chain requirements and qualified material lock-ins with Boeing and Airbus tier networks. Vinyl ester growth in marine and corrosion-resistant construction reflects open-mold process compatibility and styrene emission regulatory thresholds.
EMA MDR biocompatibility standards and FAA airworthiness certification paths constrain formulation changes for medical and aerospace resins, locking incumbent suppliers into multi-year qualification cycles. EPA TSCA Section 5 premanufacture notices and REACH SVHC candidate list screenings now govern bisphenol-A alternatives and novel curing agents entering commercial supply. China MIIT dual carbon goals and GB standards for composite recycling are reshaping resin chemistry roadmaps in Asian supply bases. Stakeholders must monitor qualification timeline compression versus regulatory lag as next-generation thermoplastic resins challenge epoxy incumbency in automotive structural programs.
Market Dynamics
High-modulus epoxy specification tiers are rotating toward dominance as aerospace and wind OEMs reject lower-grade formulations for primary structural loads, compressing margins for commodity resin suppliers while locking qualified suppliers into multi-year airframe contracts.
Growth Catalysts
- REACH SVHC candidate list expansion:EU Green Deal carbon-intensity rules are tightening material specifications for aerospace and automotive laminates, forcing reformulation toward low-VOC curing systems.
- Wind blade OEM procurement:Bisphenol-A-free epoxy platforms are securing North American contracts as blade manufacturers qualify alternative hardener systems for 80+ meter rotor structures.
- Japan METI composite roadmaps:Thermoplastic resin development targets automotive structural programs, with PEEK and PPS matrices gaining traction in electric vehicle battery enclosures.
Market Restraints
- Amine hardener supply concentration:Captive backward integration by dominant resin producers locks independent compounders out of margin-critical curing agent supply chains.
- FAA airworthiness certification timelines:EMA MDR biocompatibility standards and FAA qualification paths constrain formulation changes, locking incumbent suppliers into multi-year validation cycles.
- Recyclability technical limitations:Thermoset epoxy matrices resist end-of-life recovery, with pyrolysis and solvolysis methods failing to recover fiber mechanical properties at commercial scale.
Strategic Opportunities
- China MIIT dual carbon goals:GB standards for composite recycling are reshaping resin chemistry roadmaps, creating entry points for bio-based epoxy and recyclable thermoplastic platforms.
- Automotive structural thermoplastics:PEEK-PAEK hybrid matrices enable out-of-autoclave processing and weldability, targeting crash-critical EV chassis components.
- Digital twin qualification:Virtual resin flow simulation and cure kinetics modeling compress Boeing and Airbus tier network material lock-in timelines by 30-40%.
Industry Challenges
- Prepreg refrigerated supply chain complexity:Qualified material out-time windows demand continuous cold-chain integrity, with temperature excursions voiding $50,000+ laminate batches.
- Resin transfer molding viscosity control:Automotive programs demand 30-second injection cycles incompatible with traditional epoxy pot life, requiring novel fast-cure catalyst systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Fiber Resin Market |
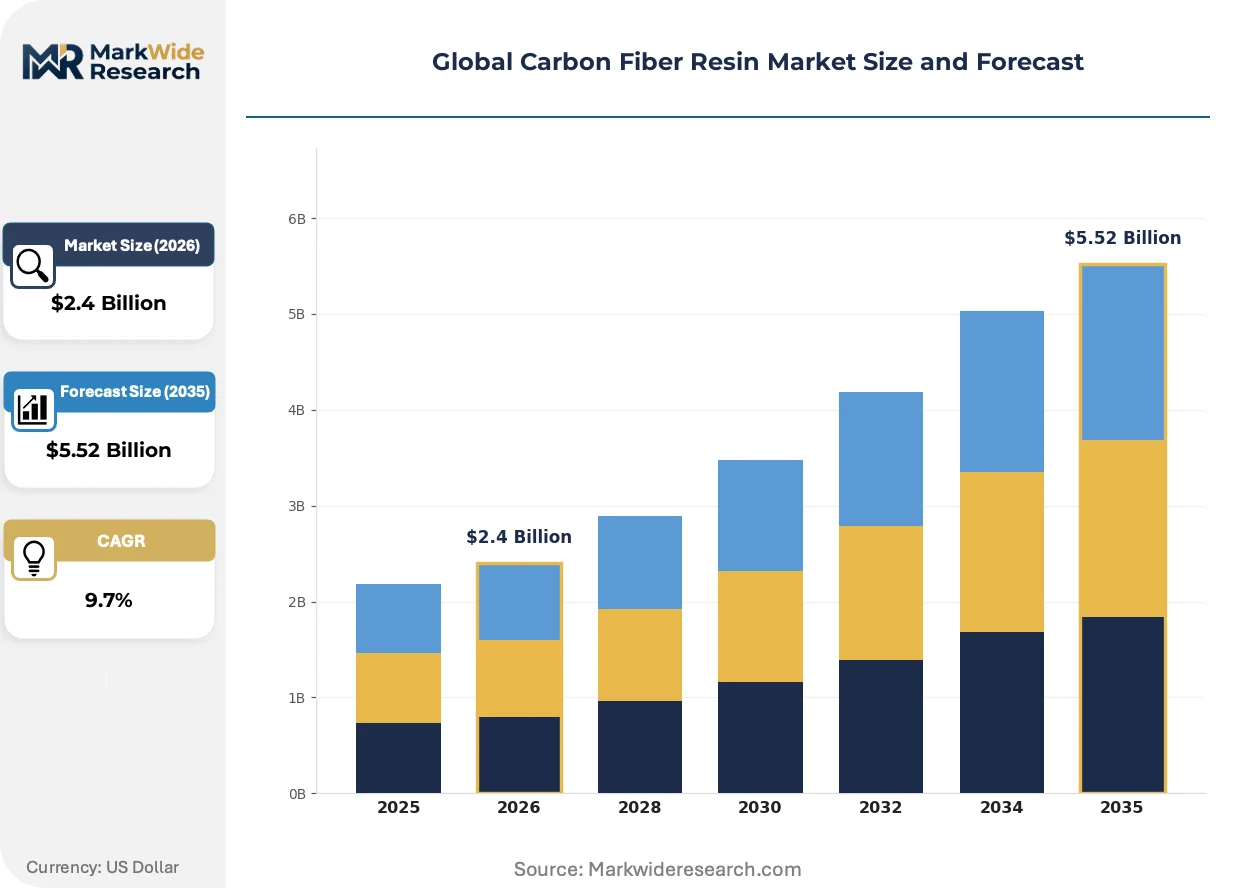
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Vinyl Ester, Phenolic, Polyimide Application: Aerospace, Wind Energy, Marine, Sports Equipment, Construction End User Industry: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Defense Contractors Manufacturing Process: Prepreg, RTM, Pultrusion, Filament Winding, Compression Molding |
| Companies Covered | Huntsman Corporation, Hexion Inc., Westlake Epoxy Inc., Kumho P&B Chemicals Inc., Swancor Holding Co. Ltd., Reichhold LLC, Scott Bader Company Ltd., Atul Ltd., Aditya Birla Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Fiber Resin Market Shifts & Advancements
Resin chemistry roadmaps are diverging sharply between aerospace-qualified thermosets and automotive-scalable thermoplastics, with qualification protocols and processing windows becoming the decisive competitive moats rather than base polymer cost.
Thermoplastic resin development is bifurcating the structural composites landscape. PEEK and PPS matrices enable welding and thermoforming for automotive crash structures, while epoxy retains lock-in for aerospace primary loads. BMW and Porsche tier suppliers are qualifying PEEK-PAEK hybrids for battery enclosures at 10x production rates versus prepreg autoclave cycles. The technology is bifurcating supplier bases into aerospace-qualified thermoset incumbents and automotive-focused thermoplastic entrants.
EPA TSCA Section 5 premanufacture notices now govern bisphenol-A alternatives and novel curing agents entering commercial supply. Industrial consequence includes 18-24 month notification delays for bio-based epichlorohydrin feedstocks and amine hardener substitutions. Marine and corrosion-resistant construction segments in the United States are accelerating vinyl ester adoption to preempt styrene emission thresholds.
Buyer concentration among Boeing and Airbus tier networks is compressing supplier switching cycles. Tier-1 laminators now demand resin suppliers co-locate technical service engineers at final assembly lines, replacing distributor-mediated procurement. Germany and Japan advanced composites clusters exhibit the tightest supplier-airframer integration, with Huntsman and Hexion maintaining resident formulation chemists at Hamburg and Nagoya facilities.
Global Carbon Fiber Resin Market Segmentation
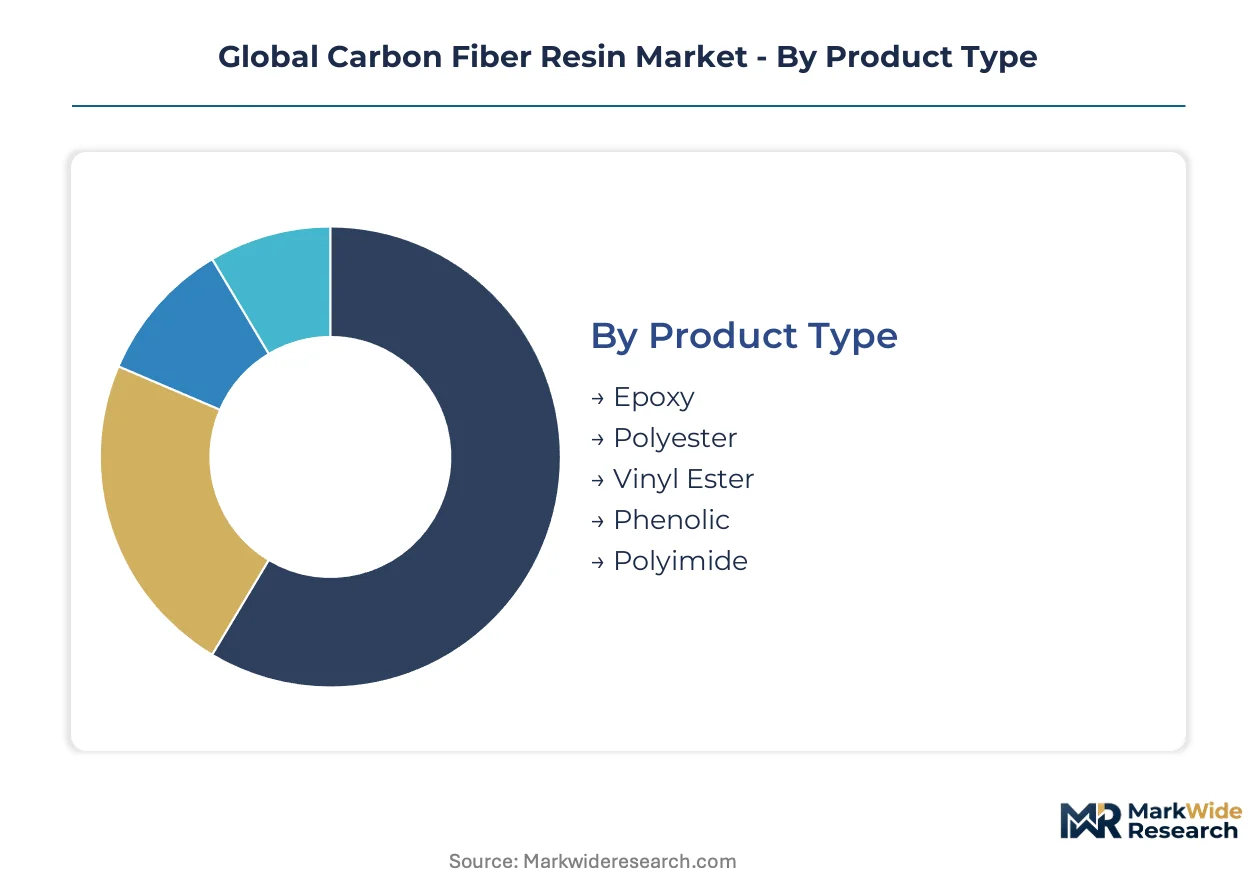
Carbon fiber resin segmentation reveals how formulation chemistry, process requirements, and end-use certification tiers fragment margin capture across the value chain. Each dimension carries distinct qualification barriers and procurement patterns that reshape supplier positioning.
Product Type:
Margin concentration pools in aerospace-qualified thermosets where certification lock-ins protect pricing power, while automotive and industrial grades compete on throughput and reformulation speed.
- Epoxy:Dominates aerospace primary structures and wind blade spar caps through superior fiber adhesion and fatigue resistance. Demand concentrates in Hamburg and Nagoya aerospace clusters where Boeing and Airbus tier networks enforce qualified material lock-ins. REACH SVHC screening and EU Green Deal carbon-intensity rules are forcing low-VOC curing system migrations.
- Vinyl Ester:Marine hulls and corrosion-resistant tanks favor this chemistry for open-mold process compatibility and moisture resistance. Procurement is accelerating in United States coastal manufacturing bases as EPA TSCA Section 5 delays on styrene alternatives compress formulation timelines.
- Polyester:Cost-sensitive construction and industrial applications utilize orthophthalic and isophthalic grades for hand lay-up and spray-up methods.
- Phenolic:Brake friction linings and high-temperature industrial components exploit its thermal stability and low smoke emission characteristics.
- Polyimide:Extreme-service aerospace and defense applications require its glass transition temperatures exceeding 300°C for engine nacelles and thermal protection systems.
The dominant share belongs to Epoxy, while Vinyl Ester is closing the gap fastest.
Application:
Application segmentation tracks how load-bearing requirements and regulatory exposure split the market between certified primary structures and commoditized secondary components.
- Aerospace:Fuselage skins, wing boxes, and empennage structures demand high-modulus epoxy prepregs with FAA airworthiness certification. Germany and Japan clusters exhibit tightest supplier-airframer integration with resident formulation chemists at final assembly lines.
- Wind Energy:80+ meter rotor blades require bisphenol-A-free epoxy platforms qualified for lightning strike protection and fatigue cycling. North American OEM procurement is securing alternative hardener systems as blade manufacturers reject lower-grade formulations.
- Marine:Yacht hulls and naval vessels balance weight reduction against osmotic blistering resistance in saltwater immersion.
- Sports Equipment:Bicycle frames, hockey sticks, and golf shafts prioritize cosmetic surface finish and impact toughness over structural certification.
- Construction:Bridge decks and seismic retrofit strips utilize carbon fiber reinforced polymer laminates for corrosion-free reinforcement.
Aerospace commands the premium tier by certification barrier, though Wind Energy is expanding most quickly through blade scaling.
End User Industry:
Customer-type segmentation exposes how procurement concentration and technical service demands stratify supplier relationships.
- OEMs:Boeing, Airbus, and Vestas direct procurement locks suppliers into multi-year contracts with co-located engineering support. Tier-1 laminators now demand resident technical service engineers replacing distributor mediation.
- Tier-1 Manufacturers:Spirit AeroSystems and TPI Composites intermediate between resin suppliers and final assembly, capturing formulation tailoring value.
- Defense Contractors:Lockheed Martin and Northrop Grumman programs impose ITAR compliance and secure facility requirements on resin supply chains.
- Aftermarket Suppliers:Repair stations and MRO facilities purchase qualified materials in smaller lots with compressed lead times.
OEMs retain the dominant procurement position, while Tier-1 Manufacturers are gaining share fastest through outsourcing consolidation.
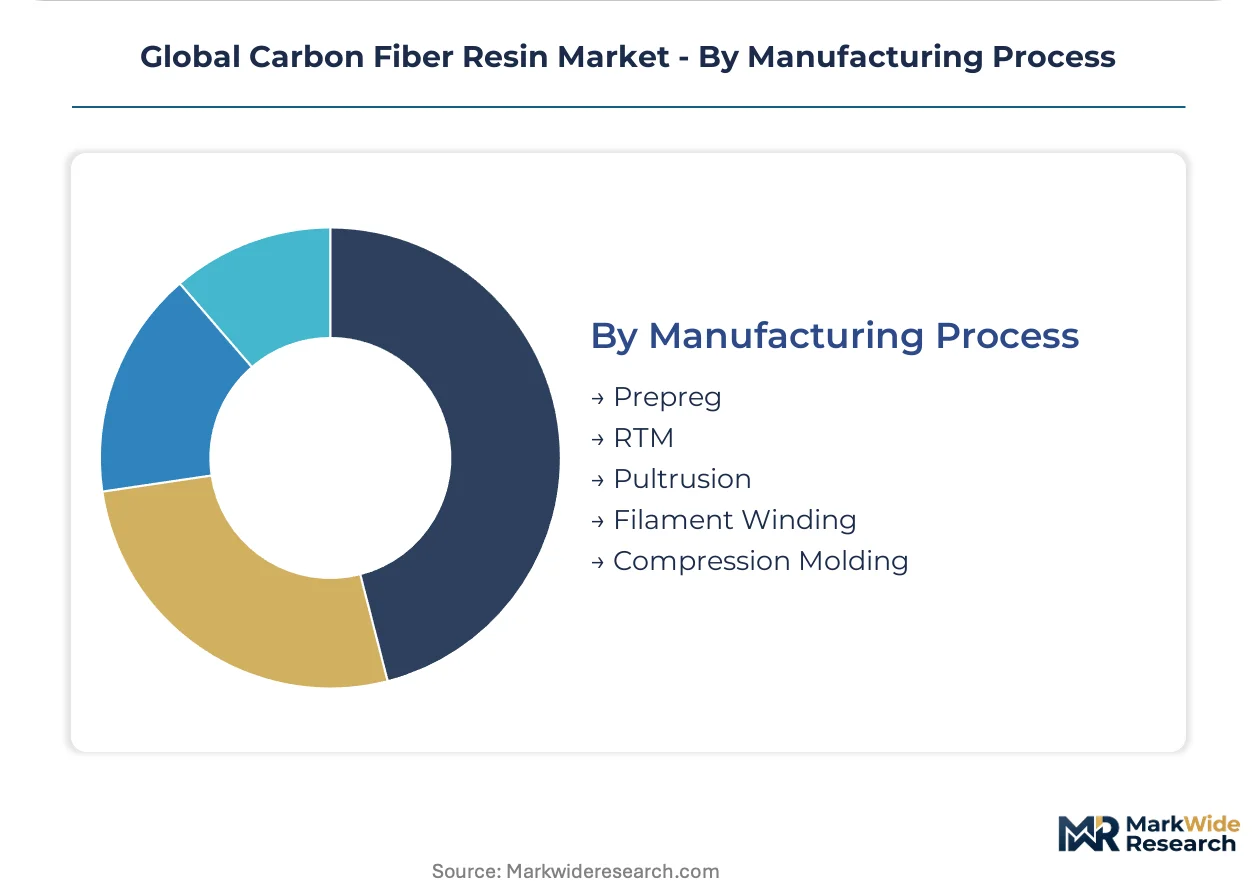
Manufacturing Process:
Process segmentation determines resin viscosity windows, cure kinetics, and supply chain infrastructure requirements.
- Prepreg:Refrigerated supply chains with qualified material out-time windows demand continuous cold-chain integrity. Temperature excursions void $50,000+ laminate batches, concentrating margin with integrators controlling logistics.
- RTM:Resin transfer molding for automotive structural programs demands 30-second injection cycles incompatible with traditional epoxy pot life, requiring novel fast-cure catalyst systems.
- Pultrusion:Continuous profiles for construction and electrical applications favor vinyl ester and polyester for rapid line speeds.
- Filament Winding:Pressure vessels and pipe structures exploit automated fiber placement with controlled resin impregnation.
- Compression Molding:Thermoplastic PEEK and PPS matrices enable out-of-autoclave processing for automotive crash-critical EV chassis components at 10x production rates.
Prepreg holds the dominant share through aerospace lock-in, though Compression Molding is climbing the fastest on thermoplastic automotive adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German resin exports supply Airbus Hamburg and Toulouse assembly lines, while Japanese producers feed Boeing Nagoya and Kawasaki Heavy Industries networks across the Pacific Rim.
United States
Wind blade OEMs in Iowa and Texas are qualifying bisphenol-A-free epoxy platforms for 80+ meter rotor structures. EPA TSCA Section 5 premanufacture notices now govern novel curing agents entering commercial supply, creating 18-24 month notification delays. Huntsman Corporation maintains resident formulation chemists at Boeing final assembly lines in Washington State.
Germany
Airbus Hamburg and Premium Aerotec drive high-modulus epoxy procurement for A350 fuselage skins and wing boxes. REACH SVHC candidate list expansion and EU Green Deal carbon-intensity rules are tightening material specifications for aerospace laminates. Hexion Inc. anchors technical service operations at Hamburg facilities with qualified material lock-ins.
Japan
Toray and Teijin carbon fiber producers in Nagoya and Oita prefectures pull specialized resin formulations for automotive structural programs. METI composite roadmaps target thermoplastic resin development, with PEEK and PPS matrices gaining traction in electric vehicle battery enclosures. Supplier-airframer integration concentrates in the Chubu industrial corridor.
China
COMAC C919 production ramp in Shanghai is driving qualified thermoset procurement for domestic airframe programs. MIIT dual carbon goals and GB standards for composite recycling are reshaping resin chemistry roadmaps in Asian supply bases. Sichuan-Chongqing and Yangtze River Delta clusters host emerging prepreg manufacturing capacity.
Global Carbon Fiber Resin Market Competitive Landscape
Listed leaders compete with private specialists across qualification timelines and curing agent supply chains. The vendor base separates into aerospace-qualified incumbents with multi-year Boeing and Airbus tier network lock-ins, automotive-focused thermoplastic entrants targeting PEEK-PAEK hybrid platforms, and regional compounders serving marine and industrial open-mold segments. Three archetypes dominate: captive backward integrators controlling amine hardener supply, bisphenol-A-free epoxy specialists securing wind blade contracts, and phenolic resin producers competing on thermal stability. Dominant competitive moves include co-location of technical service engineers at final assembly lines and qualification timeline compression through digital twin resin flow simulation.
Among North American-listed suppliers, Huntsman Corporation and Hexion Inc. occupy positions within the aerospace-qualified thermoset tier, with the former representing captive backward integration into amine hardener supply and the latter exemplifying bisphenol-A-free epoxy platform specialization. Westlake Epoxy Inc. anchors the phenolic resin thermal stability vector for high-temperature industrial applications. These three structures illustrate how qualification protocols and processing windows have become decisive competitive moats rather than base polymer cost.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Hexion Inc. |
| Westlake Epoxy Inc. |
| Kumho P&B Chemicals Inc. |
| Swancor Holding Co. Ltd. |
| Reichhold LLC |
| Scott Bader Company Ltd. |
| Atul Ltd. |
| Aditya Birla Chemicals |
| Others |
Supply & Pricing Matrix
Long-term qualified material contracts lock aerospace resin suppliers into multi-year Boeing and Airbus tier network commitments that guarantee supply access while capping price volatility through volume-based indexing against amine hardener feedstock baskets.
Pricing Analysis
Current-generation high-modulus epoxy prepregs command substantial premiums over prior-generation standard-modulus formulations, while next-generation thermoplastic PEEK-PAEK hybrids are resetting price benchmarks through out-of-autoclave processing economics. Three-tier pricing structure across aerospace-qualified, wind-certified, and industrial-grade resin tiers separates formulation complexity from certification investment recovery. Pricing pressure stems from automotive OEMs demanding 30-second RTM cycle compatibility that compresses catalyst margins. Wind blade manufacturers exhibit highest price sensitivity as bisphenol-A-free platform migration forces hardener system substitution costs downstream.
Supply Chain Analysis
Germany and Japan anchor high-modulus epoxy production for Airbus Hamburg and Boeing Nagoya assembly lines, while the United States concentrates wind blade resin compounding in Iowa and Texas manufacturing corridors. Epichlorohydrin feedstocks and aromatic amine hardeners draw from petrochemical complexes along the US Gulf Coast and Rotterdam-Antwerp hub. Single-source vulnerability concentrates in Huntsman Corporation's captive amine hardener supply chain. Distribution runs through qualified material distributors with refrigerated logistics networks serving Boeing and Airbus tier-1 laminators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic resin substitution threatens epoxy incumbency in automotive structural programs, forcing qualification timeline compression as the primary defense mechanism against PEEK-PAEK hybrid platform displacement.
For Market Incumbents: Consolidate backward integration into amine hardener supply to protect margin at the resin-to-curing-agent interface, while accelerating digital twin qualification investments that compress Boeing and Airbus material lock-in timelines by 30-40 percent against thermoplastic challengers. For New Entrants and Emerging Players: Differentiate on bisphenol-A-free epoxy platforms for North American wind blade OEMs qualifying alternative hardener systems for 80-plus meter rotor structures, targeting the procurement gap between established aerospace suppliers and commodity industrial compounders. For Investors and Strategic Acquirers: The market sits at a substitution-threat phase that favors automotive-focused thermoplastic entrants with PEEK-PAEK hybrid platforms over aerospace-qualified thermoset incumbents locked in slow-turn qualification cycles. Long-term viability centers on resin chemistry roadmaps aligned with China MIIT dual carbon goals and EU Green Deal carbon-intensity rules. Watch COMAC C919 production ramp rates as inflection indicator for qualified thermoset demand in Asian supply bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Hardener Supply | Captive curing agent production locks margin at the formulation interface against independent compounders. |
| Digital Twin Qualification Investment | Virtual resin flow simulation compresses Boeing and Airbus tier network material lock-in timelines substantially. |
| Bisphenol-A-Free Epoxy Platform Development | REACH SVHC screening and EPA TSCA Section 5 delays create first-mover advantage in wind blade procurement. |
| Co-Location of Technical Service Engineers | Resident formulation chemists at Hamburg and Nagoya facilities replace distributor-mediated procurement relationships. |
| Thermoplastic PEEK-PAEK Hybrid Scale-Up | Out-of-autoclave processing enables 10x production rates for automotive EV battery enclosure contracts. |
Research Methodology
Desk research of customs and trade flow databases, SEC 10-K filings, and ECHA REACH SVHC candidate list screenings preceded structured interviews with resin formulation chemists, wind blade procurement managers, aerospace tier-1 laminator technical directors, and automotive OEM composite engineers. Primary fieldwork combined with secondary validation against Japan METI composite roadmaps, China MIIT dual carbon policy documents, and FAA airworthiness certification databases. Bottom-up segment sizing triangulated against top-down market aggregation.
Variance decomposition across product type, application, manufacturing process, and regional production hub dimensions drove forecast construction across the analysis window. Aerospace-qualified thermoset, wind-certified epoxy, and automotive thermoplastic segments were modeled separately with CAGRs derived from qualification timeline compression rates and OEM procurement cycle visibility. Epoxy resin volume splits were cross-referenced against carbon fiber filament consumption patterns and prepreg manufacturing capacity announcements.
The analysis sits within stated boundaries; outcomes outside continued Boeing and Airbus production rate stability, REACH SVHC candidate list expansion trajectory, or China MIIT dual carbon policy enforcement would require recalibration. Forecasts reflect assumptions regarding thermoplastic resin substitution velocity and pyrolysis recycling technology commercialization timelines. Recalibration cycles align with material shifts in FAA airworthiness certification path updates and EU Green Deal carbon-intensity rule implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global FRP Sheets and Panels Market
Composite Materials
Fiber-Reinforced Plastic (FRP) Grating Market
Composite Materials
Marine Composites Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Green Composites Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
FRP Grating Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Laminar Composites Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Composite Drums Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Global Coupling Agents Market
Composite Materials
Wood Plastic Composite (WPC) Market
Composite Materials
Global Geocomposites Market