
 Carbon Fiber Composites Market | 2026-2036
Carbon Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber Composites Market Intelligence
AS9100D certification is rotating as the primary gatekeeper for aerospace-grade carbon fiber composite suppliers, forcing Tier-2 material providers to complete multi-year qualification cycles before OEM adoption. Toray Industries leverages its PAN precursor verticality to sustain qualification pipelines across Boeing and Airbus supply chains. Hexcel Corporation anchors North American defense and space programs through long-term sole-source agreements on IM7 intermediate modulus fiber. SGL Carbon specializes in automotive thermoplastic composites, competing for electric vehicle platform contracts with press-formable organosheet solutions.
Carbon fiber composites are fiber-reinforced polymer matrices combining carbon filaments with thermoset or thermoplastic resins, typically achieving tensile strengths exceeding 1,500 MPa with densities below 1.6 g/cm³, manufactured through prepreg layup, resin transfer molding, or automated fiber placement for structural load-bearing applications. Prepreg dominates aerospace value capture due to controlled resin content and out-time management, while wind energy towpreg consumption is expanding fastest as blade lengths surpass 100 meters and dry fiber infusion faces scalability limits. Woven fabric maintains mature positioning in marine and industrial tooling where drapeability and multi-axial strength justify manual processing costs.
FAA airworthiness directives and EASA CS-25 certification protocols govern structural composite approval timelines, extending development cycles but creating defensible moats for qualified suppliers. EPA hazardous air pollutant standards under NESHAP Subpart WWWW regulate styrene emissions from open mold operations, pressuring coastal U.S. fabricators toward closed-mold infusion or out-of-state relocation. Stakeholders must monitor evolving EU Green Deal embodied carbon accounting rules, as proposed CBAM extensions to composite-intensive sectors could reconfigure sourcing economics between Asian precursor producers and European finished goods manufacturers.
Market Dynamics
Thermoset prepreg qualification pipelines for narrowbody aerospace programs are compressing supplier margins while locking in multi-year procurement commitments. The EU F-Gas Regulation and REACH compliance are tightening material qualification requirements for European suppliers, forcing upstream precursor investments.
Growth Catalysts
- Wind blade scaling:Turbine manufacturers in China are consuming towpreg for blades exceeding 100 meters, displacing dry fiber infusion at the 100-meter threshold.
- AS9100D certification:Aerospace OEMs require this quality standard for structural composite suppliers, creating qualified supplier moats in commercial aviation.
- Press-formable organosheets:Automotive platforms are adopting thermoplastic composites for electric vehicle battery enclosures and body-in-white structures.
Market Restraints
- PAN precursor concentration:Acrylic fiber supply for carbon fiber production concentrates among Japanese and Chinese petrochemical complexes, exposing buyers to acrylonitrile price volatility.
- Multi-year qualification cycles:FAA airworthiness directives and EASA CS-25 protocols extend development timelines for new composite formulations, delaying revenue recognition.
- Recycled glass fiber competition:Lower-cost fiber-reinforced polymers challenge carbon fiber in non-structural automotive and construction applications.
Strategic Opportunities
- India civil aviation localization:Domestic MRO facilities and tier-1 suppliers are qualifying carbon fiber repairs and component manufacturing under DGFT import substitution frameworks.
- EU Green Deal embodied carbon accounting:Proposed CBAM extensions to composite-intensive sectors favor European finished goods manufacturers with verified low-carbon precursor sourcing.
- Automated fiber placement convergence:Robotics integration with in-situ thermoplastic consolidation is enabling out-of-autoclave production for defense and space structures.
Industry Challenges
- Composite repair technician scarcity:FAA-certified NDT inspectors and bonded repair specialists face supply shortages as fleet composite content rises.
- Capex intensity for AFP/ATL:Automated fiber placement and automated tape laying equipment require capital commitments exceeding 15 million USD per production cell.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber Composites Market |
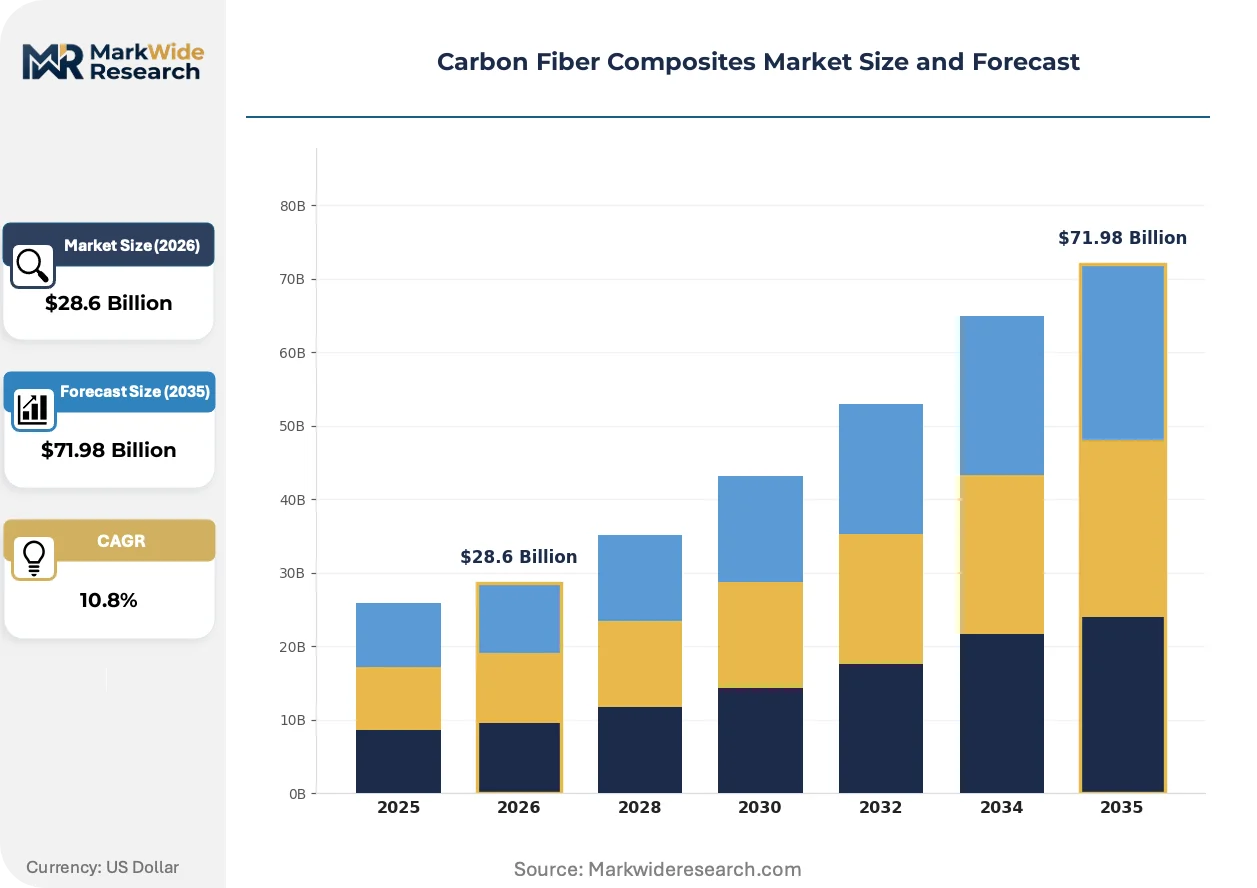
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $71.98 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepreg, Chopped Fiber, Woven Fabric, Towpreg Technology: Polyacrylonitrile (PAN), Rayon, Pitch, Carbon Nanotube Reinforced Application: Aerospace, Sporting Goods, Wind Energy, Marine End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Research Institutions |
| Companies Covered | Toray Industries, Hexcel Corporation, Mitsubishi Chemical Group, Teijin Limited, SGL Carbon, Solvay, Hyosung Advanced Materials, DowAksa, Formosa Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber Composites Market Strategic Shifts & Innovations
Process automation and regulatory carbon accounting are restructuring how carbon fiber composites move from precursor to finished structural component. The competitive edge is shifting toward qualification speed and embodied carbon verification.
Thermoplastic unidirectional tapes with in-situ consolidation capability are supplanting autoclave-cured thermoset prepregs in defense and urban air mobility airframes. Northrop Grumman and Joby Aviation are qualifying these materials for primary structure, compressing cure cycles from hours to minutes and enabling high-rate production.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents used in core materials, forcing sandwich panel suppliers to qualify CO2-blown or bio-based alternatives. Wind blade manufacturers in Germany and Denmark are reformulating PET and PVC cores to maintain structural performance under tightened environmental standards.
Consolidated buying by Chinese wind OEMs is compressing supplier margins while demanding localized precursor production. Goldwind and Envision are requiring domestic carbon fiber content for blade supply contracts, rotating procurement toward Sinopec and Zhongfu Shenying facilities and away from established Japanese suppliers.
Carbon Fiber Composites Market Segmentation
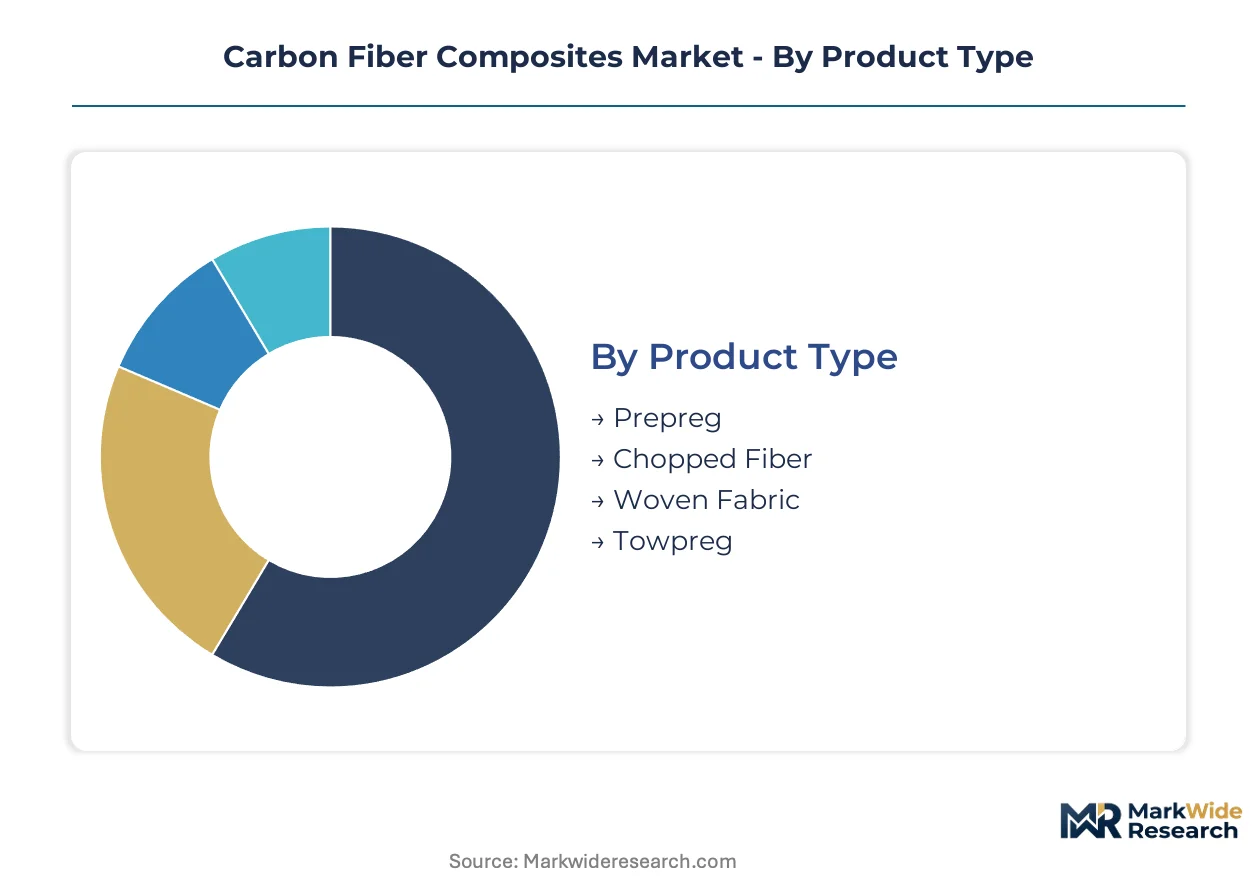
Carbon fiber composites fragment across product forms, precursor technologies, and end-use applications with sharply divergent qualification requirements and margin profiles. Understanding these divides reveals where capital concentrates and where new entrants face structural barriers.
Product Type:
Prepreg dominates export-oriented aerospace supply chains, while woven fabric and chopped fiber serve more localized industrial and construction markets.
- Prepreg:Pre-impregnated fiber sheets with precisely controlled resin content enable autoclave-cured aerospace structures meeting AS9100D standards. Boeing and Airbus narrowbody programs source this format almost exclusively from Toray, Hexcel, and Solvay facilities in Japan, the United States, and France.
- Towpreg:Impregnated fiber tows for automated fiber placement are displacing dry fiber in Chinese wind blade manufacturing as Goldwind and Envision scale beyond 100-meter blade lengths. Domestic Sinopec and Zhongfu Shenying supply chains are capturing procurement previously directed toward Japanese imports.
- Woven Fabric:Multi-axial textiles serve marine and industrial tooling applications where manual layup and drapeability justify processing costs.
- Chopped Fiber:Short-fiber reinforcements compound with thermoplastics for automotive and consumer electronics housings.
Prepreg holds the largest share; momentum sits with towpreg.
Technology:
Precursor chemistry determines fiber modulus, thermal stability, and the capital intensity of production assets.
- Polyacrylonitrile (PAN):Acrylic-based precursors yield 90% of commercial carbon fiber, with tensile strengths exceeding 5,000 MPa in aerospace grades. Toray, Mitsubishi Chemical, and Sinopec control global PAN supply from petrochemical complexes in Japan, the United States, and China.
- Pitch:Mesophase pitch precursors from petroleum or coal tar produce ultra-high modulus fiber for satellite structures and precision instruments. Demand concentrates in Japanese and U.S. defense programs with stringent thermal expansion requirements.
- Rayon:Cellulose-based precursors serve niche ablative applications in rocket nozzles and re-entry vehicles.
- Carbon Nanotube Reinforced:Hybrid matrices incorporating CNTs for enhanced electrical conductivity and interlaminar fracture toughness remain in qualification for next-generation urban air mobility airframes.
PAN dominates volume; pitch commands premium positioning in modulus-critical applications.
Application:
End-use markets separate into long-cycle aerospace qualification pipelines and rapidly scaling renewable energy procurement.
- Aerospace:Primary and secondary structural applications under FAA airworthiness directives and EASA CS-25 protocols consume intermediate modulus fiber in fuselage sections, wing boxes, and empennage assemblies.
- Wind Energy:Blade spar caps and shear webs drive towpreg consumption as turbine scaling exceeds dry fiber infusion limits. Chinese OEM procurement is rotating toward domestic supply chains under import substitution frameworks.
- Sporting Goods:Bicycles, golf clubs, and hockey sticks utilize standard modulus prepreg with shorter qualification cycles and higher volume throughput.
- Marine:Racing yachts and commercial vessels employ woven fabric and prepreg for hull and deck structures, with demand clustering in Italian, New Zealand, and U.S. shipyards.
Aerospace captures value; wind energy is climbing the fastest.
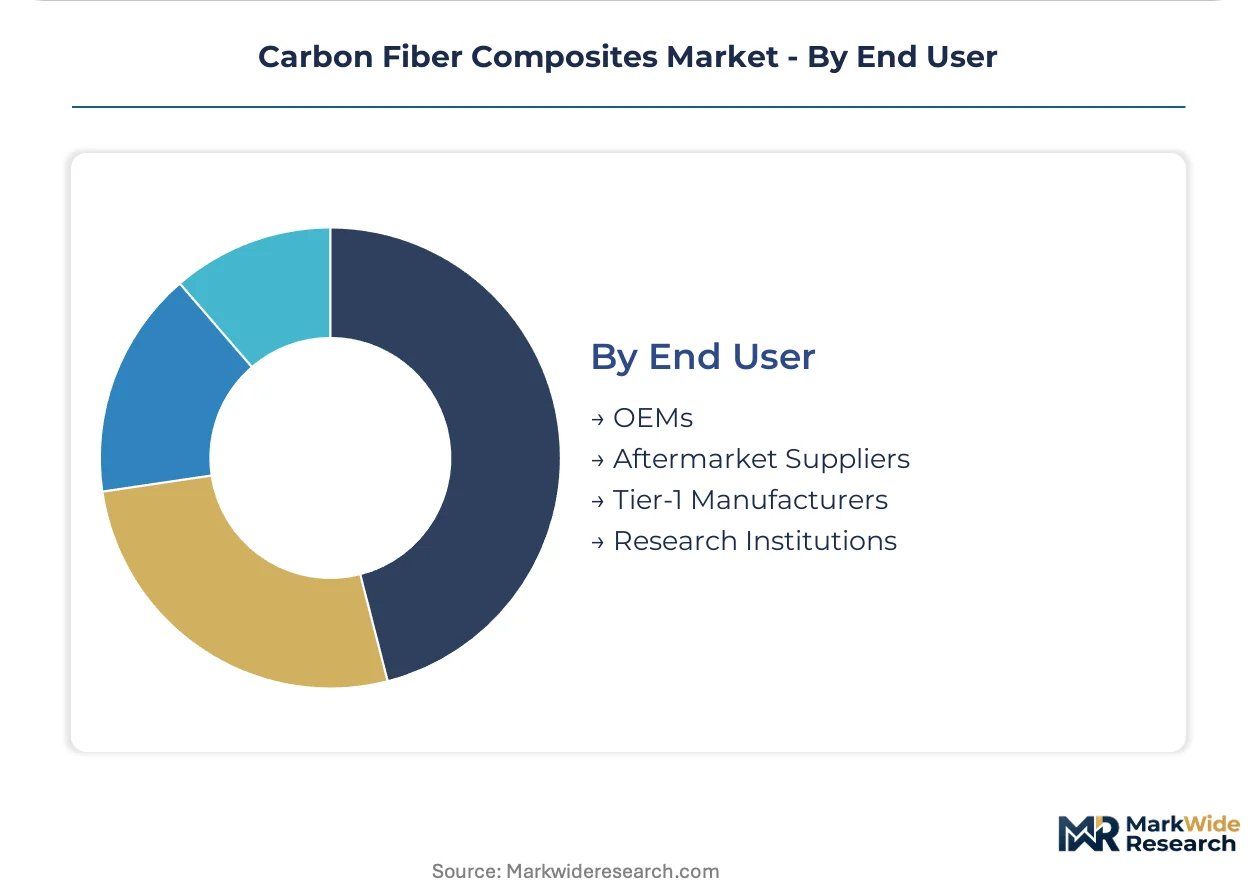
End User:
Customer type determines contract structure, from sole-source aerospace agreements to fragmented industrial distribution.
- OEMs:Boeing, Airbus, and Northrop Grumman negotiate multi-year prepreg supply agreements with qualified tier-1 material providers, locking in volume commitments through narrowbody program ramps.
- Tier-1 Manufacturers:Spirit AeroSystems, GKN Aerospace, and FACC convert prepregs into finished components, managing AS9100D certification and automated fiber placement capital deployment.
- Aftermarket Suppliers:MRO facilities and repair stations source prepreg for bonded repairs and replacement parts, with FAA-certified technician scarcity constraining capacity expansion.
- Research Institutions:National laboratories and university composites centers qualify novel thermoplastic matrices and out-of-autoclave processes for future platform adoption.
OEMs anchor procurement volume; tier-1 manufacturers face the steepest capital intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and India's PLI scheme for advanced materials are redirecting procurement toward domestic supply chains, while EU F-Gas Regulation compliance costs reshape European competitive positioning.
United States
Defense programs and commercial aviation sustain demand for intermediate modulus fiber. FAA airworthiness directives govern structural composite approval timelines for Boeing narrowbody programs. Automated fiber placement clusters concentrate around Seattle-Tacoma and Charleston aerospace corridors.
Germany
Wind blade manufacturers and automotive OEMs drive thermoplastic composite consumption. ECHA REACH compliance tightens material qualification requirements for precursor imports. Industrial fabricators cluster in Bavaria and North Rhine-Westphalia near automotive assembly plants.
China
Goldwind and Envision are scaling towpreg consumption for blades exceeding 100 meters under import substitution frameworks. MIIT domestic content requirements rotate procurement toward Sinopec and Zhongfu Shenying facilities. Manufacturing concentrates in Jiangsu and Shandong wind blade clusters.
Japan
PAN precursor verticality sustains qualification pipelines across international aerospace supply chains. METI industrial policy supports high-modulus fiber development for satellite structures. Production assets concentrate in Ehime and Hiroshima prefectures.
India
Domestic MRO facilities and tier-1 suppliers are qualifying carbon fiber repairs under DGFT import substitution frameworks. BIS standards alignment with AS9100D creates pathway for aerospace-grade supplier certification. Activity clusters around Bengaluru and Hyderabad aviation hubs.
Carbon Fiber Composites Market Key Industry Players
Player mix skews toward vertically integrated petrochemical conglomerates with captive precursor supply. Three archetypes dominate: PAN precursor producers with aerospace qualification pipelines, thermoplastic composite specialists targeting automotive platforms, and regional wind energy suppliers with localized towpreg capacity. Competitive moves center on backward integration into acrylonitrile supply and strategic partnerships for automated fiber placement equipment access.
Within the precursor-integrated tier, Toray Industries and Mitsubishi Chemical Group exemplify archetypes combining petrochemical feedstock control with multi-year aerospace qualification cycles. Hexcel Corporation occupies a position representing North American defense and space program anchoring through sole-source agreements. These three demonstrate how geographic concentration of acrylonitrile production shapes competitive boundaries.
| Leading Market Players |
|---|
| Toray Industries |
| Hexcel Corporation |
| Mitsubishi Chemical Group |
| Teijin Limited |
| SGL Carbon |
| Solvay |
| Hyosung Advanced Materials |
| DowAksa |
| Formosa Plastics |
| Others |
Cost & Logistics Intelligence
Towpreg displacement of dry fiber infusion in Chinese wind blade manufacturing simultaneously rotates procurement geography toward domestic Sinopec and Zhongfu Shenying facilities and compresses pricing power previously held by Japanese precursor exporters. This substitution dynamic reconfigures margin capture across the value chain as blade lengths exceed 100 meters and localized supply chains displace import-dependent procurement.
Pricing Analysis
AS9100D certification level creates the primary spread between aerospace-grade prepreg and industrial commodity grades, with qualification-locked suppliers commanding sustained premiums against price-pressured wind energy towpreg. Three-tier pricing structure separates qualified aerospace prepregs from standard industrial formats from economy-grade chopped fiber compounds. Cost compression in Chinese wind energy procurement is intensifying because Goldwind and Envision mandate domestic content thresholds. Tier-1 aerospace OEMs exhibit lowest price sensitivity due to sole-source dependency, while construction and marine fabricators face acute margin pressure from recycled glass fiber substitutes.
Supply Chain Analysis
Japan and China anchor PAN precursor production, with petrochemical complexes in Ehime, Hiroshima, and Jiangsu provinces feeding carbonization lines for intermediate and high-modulus fiber output. Acrylonitrile feedstock, oxidation ovens, and surface treatment chemistries constitute critical input dependencies. Single-source vulnerability concentrates in aerospace-qualified precursor supply, where Toray and Mitsubishi Chemical qualification pipelines lock out rapid supplier switching. Distribution runs through tier-1 converter networks for aerospace and direct OEM procurement for Chinese wind energy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story. Multi-year FAA and EASA qualification cycles create switching costs that defend incumbent positioning against faster-moving substitute technologies.
For Market Incumbents: Shield aerospace qualification pipelines through accelerated AS9100D certification investments at tier-2 supplier partners facing compressed margins from Chinese wind energy procurement. Deepen captive acrylonitrile supply through backward integration into petrochemical feedstock or long-term offtake agreements with Sinopec and Mitsubishi Chemical complexes. Defend against thermoplastic composite substitution in defense applications by qualifying in-situ consolidation processes with Northrop Grumman and Joby Aviation. For New Entrants and Emerging Players: Differentiate on embodied carbon verification for EU Green Deal compliance, targeting European finished goods manufacturers facing CBAM extension exposure. Penetrate the Indian civil aviation aftermarket through DGFT import substitution frameworks and BIS standards alignment with AS9100D. Pursue automotive thermoplastic organosheet contracts with press-formable solutions for electric vehicle battery enclosures as the most penetrable segment outside entrenched aerospace supply chains. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive thermoplastic specialists lacking precursor verticality and facing margin compression from Chinese wind energy procurement rotation. Long-term viability rests on qualification moat durability and regional supply chain localization trends. Watch for EU F-Gas Regulation enforcement actions against core material suppliers as an inflection indicator for sandwich panel reformulation demand and qualified alternative qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile | Toray's petrochemical feedstock control defends margin capture against Chinese precursor expansion. |
| AS9100D Certification Acceleration | Compressed qualification cycles for tier-2 suppliers lock in Boeing and Airbus narrowbody program sourcing. |
| Thermoplastic Tape Qualification | In-situ consolidation with Northrop Grumman enables out-of-autoclave defense production at reduced cycle times. |
| EU Green Deal Carbon Verification | Verified low-carbon precursor sourcing positions European manufacturers favorably under proposed CBAM extensions. |
| Automated Fiber Placement Deployment | Robotics integration with AFP equipment access determines tier-1 converter competitive positioning in defense programs. |
Research Approach
Operator-level perspectives from aerospace procurement directors, wind blade manufacturing engineers, carbon fiber plant managers, and automotive platform material specialists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FAA airworthiness directives, EASA CS-25 certification protocols, MIIT domestic content requirements, and SEC 10-K filings from precursor-integrated conglomerates. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verified demand estimates across product forms and end-use applications.
Sensitivity analysis tested forecast robustness across acrylonitrile price volatility scenarios, qualification timeline compression assumptions, and Chinese import substitution acceleration pathways. The analytical framework modeled volume and value outputs across the projection horizon by product type, precursor technology, application sector, and regional production hub. CAGRs derived from segment-level demand build-ups incorporating blade length scaling curves, narrowbody program ramp schedules, and electric vehicle platform composite content trajectories.
Material uncertainties — abrupt EU F-Gas Regulation enforcement, Chinese dual carbon goal acceleration, or aerospace program deferrals — sit outside the modeled envelope. Forecasts reflect documented assumptions about qualification pipeline durations and precursor capacity expansion timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Structural Composites Market
Composite Materials
Global Thermoplastic Composites Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Tow Prepreg Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Medical Composite Material Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Lightweight Materials Market
Composite Materials
Global FRP Sheets and Panels Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Global FRP Vessels Market
Composite Materials
Composite Drums Market
Composite Materials
Global Composite Resin Market