
 Carbon Fiber Prepreg Market | 2026-2036
Carbon Fiber Prepreg Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber Prepreg Market Intelligence
Multi-source resin procurement is pivoting toward captive epoxy formulation among large prepreg manufacturers. Hexcel Corporation leverages in-house resin synthesis to secure supply continuity for aerospace-qualified prepregs. Toray Industries anchors its competitive position through backward integration into PAN-based carbon fiber production. SGL Carbon specializes in thermoplastic prepreg systems for automotive structural applications, differentiating its portfolio from conventional thermoset offerings.
Carbon fiber prepreg consists of unidirectional or woven carbon fiber reinforcements pre-impregnated with a partially cured resin matrix, typically formulated to fiber areal weights between 150 and 300 grams per square meter and resin contents of 33-42% by weight. The material serves as a mold-ready feedstock for autoclave, out-of-autoclave, and press-molding processes in weight-critical structural applications. Intermediate modulus fiber grades dominate current aerospace procurement volumes due to their balanced stiffness-to-cost performance in primary aircraft structures. Wind energy blade applications represent the fastest-expanding demand channel, with epoxy-based prepreg systems displacing glass fiber in longer, more efficient turbine designs. Standard modulus segments retain cost advantages in industrial and sporting goods markets where ultimate performance thresholds remain lower.
FAA airworthiness directives and EASA CS-25 certification standards mandate flame-smoke-toxicity performance and damage tolerance for composite primary structures, directly shaping resin system selection and qualification timelines. REACH chemical registration requirements in Europe constrain certain amine hardener chemistries, pushing formulators toward alternative curing agents with improved environmental profiles. Stakeholders must monitor evolving OEM qualification protocols and regional chemical regulations to align R&D investments with certifiable material pathways.
Market Dynamics
Aerospace OEM qualification protocols for thermoplastic prepreg systems are compressing supplier development cycles while forcing parallel investments in out-of-autoclave curing infrastructure.
Growth Catalysts
- FAA and EASA airworthiness mandates:Certification requirements for damage-tolerant composite primary structures accelerate material substitution from aluminum in next-generation airframes.
- Wind blade manufacturers:Epoxy-based prepreg systems displace glass fiber in longer turbine designs as rotor diameters exceed 150 meters.
- Bavarian aerospace cluster:Tier-1 suppliers in southern Germany integrate autoclave-capable prepreg into wing and fuselage assemblies at scale.
Market Restraints
- Acrylonitrile price volatility:PAN precursor costs fluctuate with oil and natural gas feedstock markets, squeezing carbon fiber producer margins.
- Toray-Hexcel-SGL supply triad:Three manufacturers control over 60% of aerospace-qualified prepreg capacity, creating concentration risk.
- REACH amine hardener restrictions:ECHA registration constraints eliminate certain curing chemistries from European formulation portfolios.
Strategic Opportunities
- India defense aerospace:Indigenization mandates under the country's offset procurement rules create localized prepreg qualification pathways.
- Thermoplastic-thermoset hybrid systems:Automated fiber placement of PEEK-toughened epoxy enables weldable, recyclable airframe joints.
- Direct-to-fabricator digital platforms:Specialty distributors bypass traditional master distributor tiers to serve mid-volume industrial buyers.
Industry Challenges
- Autoclave operator certification:Aerospace laminators face 18-24 month training pipelines for pressure-vessel technicians qualified to NADCAP standards.
- OEM material qualification timelines:Boeing and Airbus specification lock-ins require 3-5 year validation cycles before volume procurement authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber Prepreg Market |
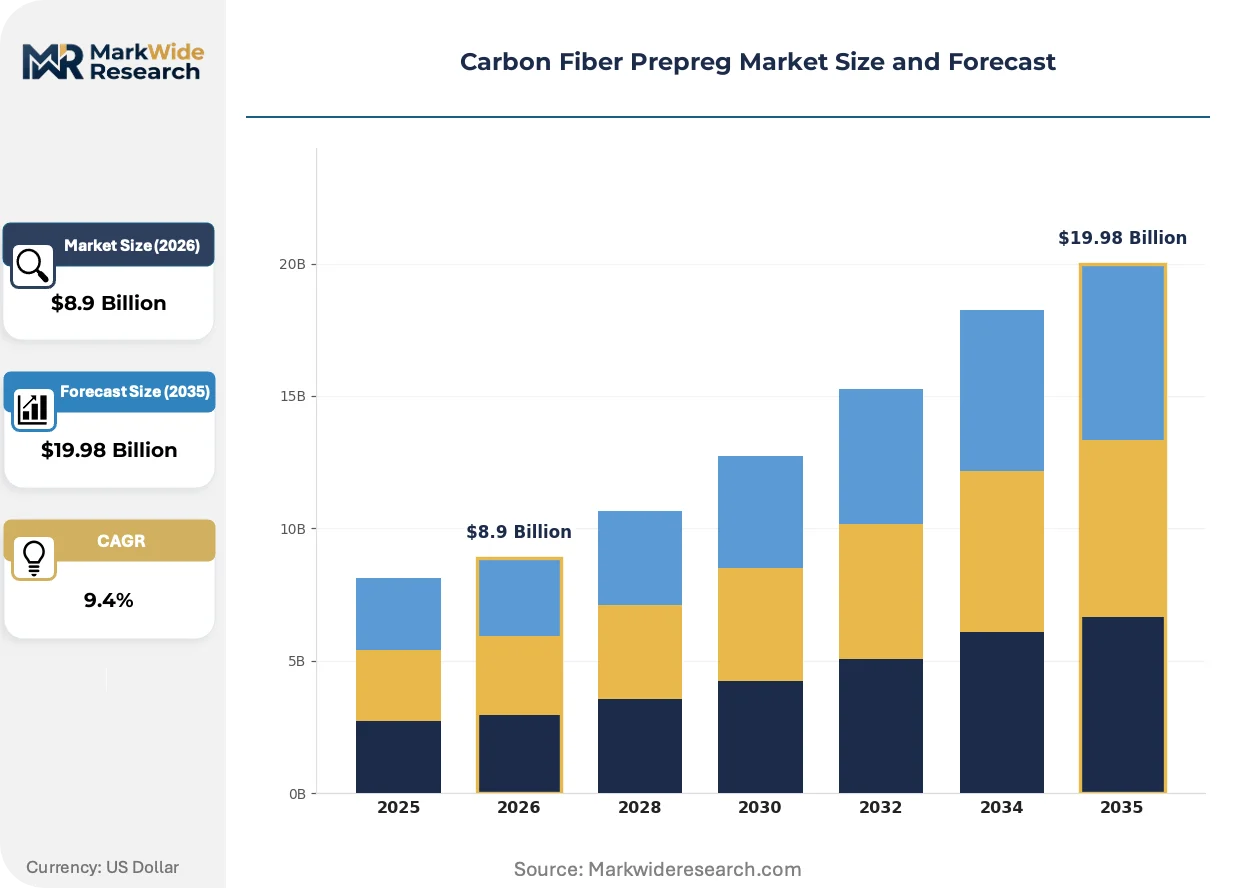
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $19.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Modulus, Ultra High Modulus, Intermediate Modulus, Standard Modulus Application: Aerospace & Defense, Sports Equipment, Marine Structures, Wind Energy Blades, Consumer Electronics End User Industry: Aircraft Manufacturers, Sports Goods Makers, Shipbuilding Firms, Renewable Energy Companies, Electronics OEMs Resin System: Epoxy, BMI, Vinyl Ester, Cyanate Ester, Polyester |
| Companies Covered | Hexcel Corporation, Toray Industries, Teijin Limited, Solvay, Mitsubishi Chemical Carbon Fiber and Composites, SGL Carbon, Gurit Holding AG, Royal TenCate, Axiom Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber Prepreg Market Strategic Shifts & Innovations
Automated fiber placement and in-situ consolidation are collapsing the boundary between raw material supply and finished component fabrication across aerospace and wind energy verticals.
Automated tape laying with laser-assisted fiber placement is automating the transition from hand lay-up to fully programmed deposition for complex aerostructures. Tier-1 aerostructure suppliers in Germany and Japan deploy these systems for wing skin and spar production. The technology is automating workforce reduction in traditionally labor-intensive composite fabrication cells.
REACH chemical registration deadlines in Europe constrain amine hardener formulations, pushing resin suppliers toward anhydride and phenolic curing systems. Formulators must resubmit environmental safety dossiers for alternative chemistries. Wind blade manufacturers face the steepest adaptation costs as epoxy systems dominate their current supply base.
Consolidated procurement by Boeing, Airbus, and Vestas concentrates volume purchasing power among fewer buyers with stricter technical service requirements. Smaller prepreg distributors lose direct OEM access and retreat to industrial and sporting goods segments. The compression is most visible in North American supply chains where distributor count has halved since 2019.
Carbon Fiber Prepreg Market Segmentation
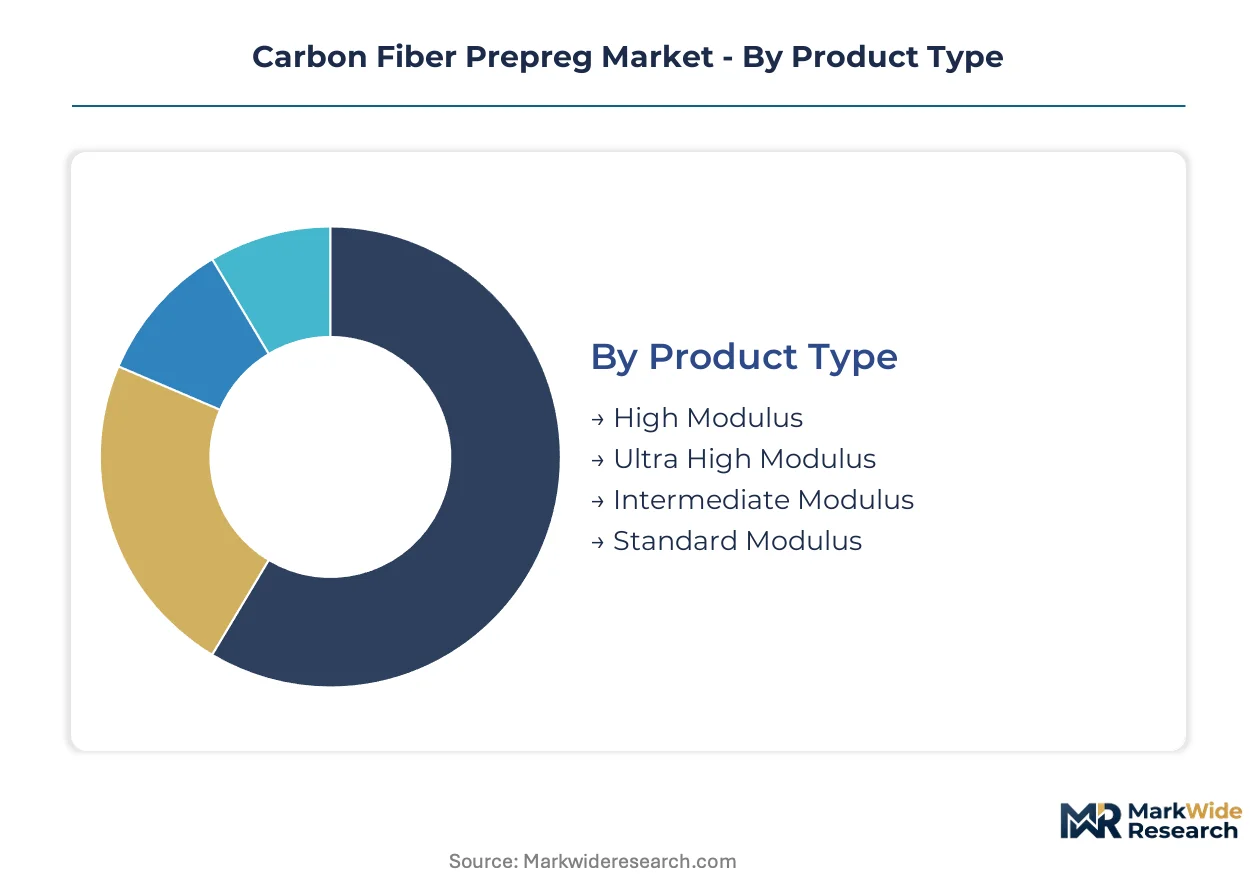
Carbon fiber prepreg segmentation reflects divergent performance requirements across load-bearing applications. Buyers prioritize modulus-to-cost ratios in primary structures versus processing speed in industrial components. Each segmentation dimension carries distinct qualification barriers and supply chain configurations.
Product Type:
Modulus selection directly determines fiber grade procurement budgets and autoclave cycle parameters for laminators.
- Intermediate Modulus:Fiber grades between 276-350 GPa stiffness balance structural performance against qualification cost. Boeing and Airbus specify these grades for wing skins and fuselage barrels. Bavarian Tier-1 suppliers consume the largest procurement volumes for narrow-body programs.
- Standard Modulus:Lower-cost grades at 230 GPa stiffness serve industrial tooling and sporting goods where ultimate performance thresholds remain modest. Japanese manufacturers dominate capacity for these grades, feeding automated tape laying systems in wind blade fabrication.
- High Modulus:350-450 GPa stiffness grades command premium positioning for satellite structures and high-performance racing components.
- Ultra High Modulus:Grades exceeding 450 GPa stiffness serve specialized defense and space applications with limited volume throughput.
Intermediate modulus leads on scale; wind energy applications are expanding most quickly for standard modulus grades.
Application:
End-use certification requirements create tiered entry barriers that stratify supplier portfolios.
- Aerospace & Defense:FAA and EASA damage-tolerance mandates govern material qualification for primary structures. NADCAP-accredited laminators in Germany, Japan, and the United States maintain dedicated autoclave cells for airframe prepreg consumption. Specification lock-ins with Boeing and Airbus compress supplier margins while securing volume commitments.
- Wind Energy Blades:Rotor diameters exceeding 150 meters drive epoxy prepreg substitution for glass fiber in spar caps and shear webs. Vestas and Siemens Gamesa procurement concentrates in Denmark and Spain, with Chinese blade manufacturers scaling domestic prepreg qualification.
- Sports Equipment:Bicycle frames and hockey sticks demand rapid-cure out-of-autoclave systems for batch production economics.
- Marine Structures:Yacht hulls and racing craft utilize intermediate modulus systems with vinyl ester compatibility for moisture resistance.
- Consumer Electronics:Laptop chassis and wearable housings require ultra-thin prepreg formats with cosmetic surface quality.
Aerospace and defense commands premium positioning; wind energy blades are gaining share fastest.
End User Industry:
Customer scale and technical service requirements fragment procurement patterns across verticals.
- Aircraft Manufacturers:Boeing and Airbus consolidate material specifications through qualified supplier lists, forcing 3-5 year validation cycles. Direct procurement bypasses distributor tiers for master roll supply.
- Renewable Energy Companies:Vestas, Siemens Gamesa, and Goldwind negotiate frame agreements for blade prepreg with technical field support requirements.
- Sports Goods Makers:Mid-volume buyers rely on specialty distributors for slit-width customization and rapid lead times.
- Shipbuilding Firms:Yacht builders in Italy and the Netherlands source marine-qualified systems with fire-retardant resin formulations.
- Electronics OEMs:Apple and Samsung suppliers demand ultra-thin unidirectional tapes with automated handling compatibility.
Aircraft manufacturers concentrate purchasing power; renewable energy companies are scaling procurement fastest.
Resin System:
Cure chemistry determines processing temperature, environmental compliance, and recycling pathways.
- Epoxy:Dominant thermoset matrix for aerospace and wind applications with 120-180°C cure windows. REACH amine hardener restrictions in Europe push formulators toward anhydride alternatives.
- BMI:Bismaleimide systems serve high-temperature engine nacelles and military airframes with service temperatures exceeding 230°C.
- Cyanate Ester:Low dielectric loss properties qualify these systems for satellite antenna structures and radomes.
- Vinyl Ester:Marine and corrosion-resistant industrial applications favor these styrene-containing formulations.
- Polyester:Cost-driven industrial tooling and temporary structures utilize these rapid-cure systems with limited durability requirements.
Epoxy leads on scale; BMI formulations are climbing the fastest in defense procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's aerospace cluster anchors prepreg consumption for commercial aviation programs, while wind energy expansion in northern Europe and Asia drives broader geographic diversification of demand centers.
United States
Boeing's 737 MAX and 787 programs sustain aerospace-qualified prepreg volumes in Washington and South Carolina manufacturing centers. FAA damage-tolerance mandates for composite primary structures enforce rigorous material qualification protocols. Wichita's aerostructure supplier base integrates intermediate modulus prepregs into wing assemblies for narrow-body platforms.
Germany
Airbus A320 and A350 fuselage production in Hamburg and wing manufacturing in Bremen concentrate European prepreg procurement. EASA CS-25 certification standards align with FAA requirements for flame-smoke-toxicity performance in cabin structures. Bavaria's Tier-1 supplier network around Munich operates dedicated autoclave cells for aerospace laminate fabrication.
China
Comac C919 certification progress and wind turbine blade scaling propel domestic prepreg qualification efforts. MIIT industrial policy supports carbon fiber self-sufficiency through state-backed capacity expansion in Jiangsu and Shandong provinces. Yangtze River Delta blade manufacturers trial epoxy prepreg systems for 16MW offshore turbine platforms.
Japan
Toray's PAN-based carbon fiber production in Ehime Prefecture supplies aerospace and industrial prepreg feedstock globally. METI strategic material initiatives prioritize advanced composite retention amid export control tightening. Nagoya's aerospace manufacturing corridor consumes intermediate modulus grades for regional jet and space launcher structures.
India
Defense offset procurement rules under the Ministry of Defence mandate localized prepreg sourcing for fighter and transport programs. BIS certification requirements for aerospace materials create qualification pathways for domestic laminators. Bengaluru's aerospace cluster attracts Tier-1 suppliers establishing autoclave capability for indigenous platform integration.
Carbon Fiber Prepreg Market Key Industry Players
Global majors compete with regional champions across qualification-intensive aerospace supply chains, creating a tiered structure where specification lock-ins compress margins at the top while specialty niches retain pricing power. Three manufacturers control dominant share of aerospace-qualified capacity, generating concentration risk for OEM procurement teams. Strategic archetypes separate resin-integrated formulators from carbon fiber producers and independent prepreg converters. Competitive moves center on backward integration into precursor supply and thermoplastic system development for next-generation airframes.
Within the integrated materials tier, Hexcel Corporation exemplifies captive resin synthesis strategies, while Toray Industries anchors positioning through PAN-based carbon fiber production. SGL Carbon occupies a specialist position in thermoplastic prepreg systems. These three represent distinct archetypes: aerospace-qualified formulator, upstream fiber producer, and automotive-focused thermoplastic developer.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Industries |
| Teijin Limited |
| Solvay |
| Mitsubishi Chemical Carbon Fiber and Composites |
| SGL Carbon |
| Gurit Holding AG |
| Royal TenCate |
| Axiom Materials |
| Others |
Cost & Logistics Intelligence
Backward integration into PAN-based carbon fiber production anchors supply security and pricing power for aerospace-qualified prepreg manufacturers. Hexcel Corporation's captive epoxy synthesis and Toray Industries' fiber-to-prepreg control insulate margins from acrylonitrile feedstock volatility while locking in qualification-dependent buyer relationships.
Pricing Analysis
Acrylonitrile cost pass-through from oil and natural gas markets squeezes carbon fiber producer margins and propagates into prepreg pricing tiers. Aerospace-qualified systems command premium positioning against industrial grades through FAA and EASA certification investments, while wind blade manufacturers exhibit highest price sensitivity as they scale epoxy prepreg substitution for glass fiber. Cost compression in standard modulus segments intensifies as Chinese capacity expansion feeds automated tape laying systems for turbine fabrication.
Supply Chain Analysis
Carbon fiber supply rests on Japanese and American PAN precursor producers, with Toray's Ehime Prefecture operations and Hexcel's Utah facilities feeding global prepreg conversion. Epoxy resin formulations draw from German and Chinese specialty chemical suppliers, while amine hardener availability faces ECHA registration constraints. Single-source vulnerability concentrates in aerospace-qualified fiber grades where three manufacturers control dominant capacity. Distribution runs through master distributors serving industrial segments and direct OEM supply for aircraft manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon fiber prepreg market compounds steadily as airframe material substitution from aluminum locks in multi-decade procurement cycles for qualified suppliers.
For Market Incumbents: Cement specification lock-ins with Boeing and Airbus through accelerated NADCAP accreditation investments in Bavarian and Japanese laminator networks. Expand captive resin synthesis capacity to offset REACH amine hardener restrictions threatening European formulation portfolios. Prioritize thermoplastic prepreg R&D to capture next-generation out-of-autoclave airframe programs before qualification windows close. For New Entrants and Emerging Players: Mid-volume industrial buyers seeking slit-width customization and rapid lead times present accessible entry points outside consolidated aerospace procurement channels. Target wind energy blade manufacturers in China's Yangtze River Delta scaling domestic prepreg qualification for 16MW offshore platforms. Establish direct-to-fabricator digital platforms bypassing traditional master distributor tiers to serve specialty sporting goods and marine fabricators. For Investors and Strategic Acquirers: Consolidation pressure builds where qualification-intensive aerospace supply chains concentrate procurement power among fewer buyers with stricter technical service requirements. The 5-10 year viability window favors targets with established FAA and EASA certification pathways and backward integration into PAN precursor or captive resin supply. Watch for Indian defense offset procurement milestones as inflection indicators for localized prepreg demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Toray Industries secures fiber feedstock continuity for aerospace-qualified prepreg volumes. |
| Thermoplastic Prepreg Development | SGL Carbon differentiates from thermoset competitors for automotive structural weldability requirements. |
| NADCAP Accreditation Expansion | Bavarian Tier-1 suppliers lock in Boeing and Airbus laminate fabrication contracts. |
| Direct-to-Fabricator Digital Platform | Specialty distributors bypass master tiers to serve mid-volume wind blade manufacturers. |
| REACH-Compliant Resin Reformulation | Hexcel Corporation pivots toward anhydride curing systems as ECHA restricts amine hardeners. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with aerospace procurement directors, wind blade manufacturing engineers, prepreg technical sales managers, and NADCAP-accredited laminator operations heads with secondary validation from FAA airworthiness directives, EASA CS-25 certification standards, customs trade data, and SEC filings from listed carbon fiber producers. Bottom-up fiber grade consumption estimates and top-down aerospace program build rate projections were triangulated against intermediate modulus and standard modulus segment outputs.
Historical reference periods spanning pre-pandemic baseline through current qualification cycle completions anchored the projection horizon. Segmentation modeling incorporated modulus grade, cure chemistry, end-use application, and regional manufacturing hub dimensions. CAGRs were derived from fitted trend analysis against named OEM program ramp schedules and wind turbine blade length expansion trajectories, with epoxy resin pricing and acrylonitrile feedstock cost curves as primary forecast inputs.
Underlying measurement precision varies by segment; aerospace and defense qualification volumes carry tighter precision than emerging industrial applications. Forecasts reflect documented assumptions on Boeing and Airbus delivery schedules, Vestas and Siemens Gamesa blade procurement patterns, and Chinese domestic capacity expansion timelines. Regulatory shifts in REACH chemical registration, FAA damage-tolerance mandates, and Indian defense offset rules warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Wind Turbine Composites Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
FRP Reactor Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Structural Core Materials Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Composites Distributor Market
Composite Materials
Global Lightweight Construction Material Market
Composite Materials
Global Geocomposites Market
Composite Materials
Composite Coatings Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Pcb Laminate Materials Market