
 Global Geocomposites Market | 2026-2036
Global Geocomposites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Geocomposites Market Foresight
The geocomposites supply base is rebalancing between engineered multilayer systems and basic separation fabrics. TenCate Geosynthetics leverages its vertical manufacturing chain to dominate high-specification drainage composites for landfill containment. HUESKER Synthetic GmbH anchors the European railway subgrade segment through specialized reinforcement geogrids. SKAPS Industries competes aggressively in the North American erosion control market with cost-optimized needlepunched offerings.
Geocomposites are manufactured geosynthetic structures combining two or more distinct materials—typically geotextiles bonded to geonets, geogrids, or geomembranes via thermal or mechanical processes—to perform integrated drainage, filtration, reinforcement, or separation functions in civil and environmental engineering. Needlepunching and thermal bonding represent the dominant fabrication technologies, with extrusion lamination gaining share for high-flow drainage applications where hydraulic conductivity exceeds 1×10⁻³ m/s. Drainage composites command the largest product segment due to persistent demand from landfill liner systems and tunnel waterproofing, while reinforcement composites represent the fastest-expanding category as railway operators specify polymer-geogrid solutions for ballast stabilization. Filtration composites remain a mature margin pool concentrated in coastal and riverine erosion control projects.
EPA landfill liner regulations in the United States, REACH chemical compliance frameworks in Europe, and GB standards administered by SAMR in China collectively shape product certification requirements and cross-border market access for geocomposite manufacturers. The EU Green Deal infrastructure provisions and F-Gas Regulation indirectly stimulate demand through accelerated tunnel and rail investment programs. Stakeholders must monitor evolving polymer feedstock cost volatility and the pace of bio-based geotextile commercialization to calibrate capacity and R&D commitments.
Market Dynamics
Railway subgrade modernization programs across Germany, France, and Japan are concentrating polymer-geogrid demand specifications, forcing manufacturers to reconfigure production lines toward high-tensile reinforcement composites and away from basic drainage products.
Growth Catalysts
- EU Green Deal infrastructure mandates:The EU Green Deal's resilience provisions accelerate material upgrades in tunnel waterproofing and landfill containment across member states.
- Railway ballast stabilization:Federal transport investment programs in Germany specify polymer-geogrid solutions for subgrade reinforcement, pulling volume from conventional aggregate methods.
- Polypropylene feedstock availability:Captive resin supply from integrated petrochemical complexes in the US Gulf Coast stabilizes input costs for drainage composite manufacturers.
Market Restraints
- Polymer price volatility:Crude oil-linked polypropylene and polyethylene resin costs swing quarterly, compressing margins on fixed-price civil infrastructure contracts.
- REACH chemical compliance:ECHA's substance authorization requirements add 18-24 month certification timelines for new geotextile chemistries entering European markets.
- Natural aggregate substitution:Crushed stone and sand remain cost-competitive for separation and filtration functions in budget-constrained developing markets.
Strategic Opportunities
- Bio-based geotextile commercialization:Polylactic acid and hemp-fiber reinforcement composites unlock premium positioning in EU public procurement with sustainability scoring.
- India coastal protection:Unpenetrated demand for erosion control composites exists along Gujarat and Tamil Nadu shorelines as cyclone resilience spending accelerates.
- Extrusion lamination technology:Bonding geonets to geomembranes via continuous extrusion enables high-flow drainage products exceeding 1×10⁻³ m/s hydraulic conductivity for tunnel applications.
Industry Challenges
- Geotechnical engineer shortage:Specialized design expertise for multilayer composite systems remains scarce in Southeast Asian and African markets, slowing specification adoption.
- ISO 10318 certification timelines:Third-party testing for geosynthetic identification and classification extends product launch cycles by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Geocomposites Market |
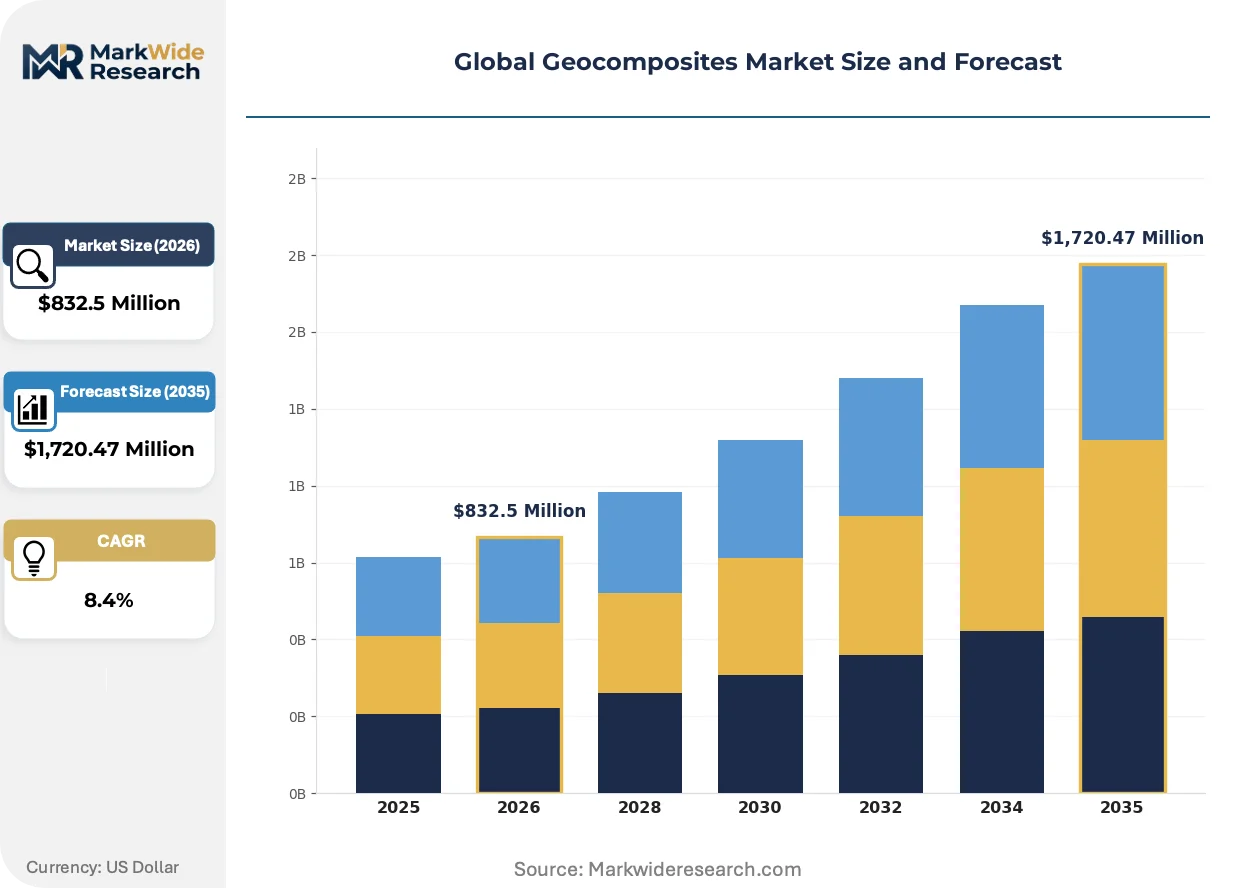
| Market Size in 2026 | $832.5 Million |
| Market Size in 2035 | $1,720.47 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drainage Composites, Reinforcement Composites, Separation Composites, Filtration Composites Technology: Needlepunching, Stitching, Thermal Bonding, Stitchbonding, Extrusion Lamination Application: Road Construction, Erosion Control, Railway Subgrade, Landfill Liners, Retaining Structures End User Industry: Civil Infrastructure, Mining, Water Management, Environmental Engineering, Oilfield Services |
| Companies Covered | TenCate Geosynthetics, GSE Environmental, HUESKER Synthetic GmbH, Officine Maccaferri Spa, Thrace Group, SKAPS Industries, ABG Ltd, Leggett & Platt, NAUE GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Geocomposites Market Shifts & Advancements
Manufacturing automation and regulatory chemistry restrictions are compressing product development cycles while elevating performance thresholds for civil infrastructure specifications.
Automated needlepunching lines with real-time basis-weight control are automating quality consistency in drainage composite production. German and Japanese tunnel contractors now specify machine-verified geotextile-geonet laminates for waterproofing systems. This automation is compressing defect rates and enabling just-in-time delivery for large-scale rail projects.
The EU F-Gas Regulation's phase-down of fluorinated greenhouse gases indirectly stimulates geocomposite demand through accelerated tunnel and rail investment programs requiring alternative waterproofing solutions. Manufacturers reformulate geomembrane adhesives to eliminate perfluorinated compounds ahead of 2030 bans. Railway operators in France and Italy specify compliant drainage composites for new high-speed corridors.
Asset owners in Germany and Japan now bundle 20-year performance warranties with geocomposite procurement, displacing transactional material purchasing. Engineering firms absorb installation risk and guarantee subgrade settlement rates. This contractual unbundling concentrates buyer power among tier-one contractors with balance-sheet capacity to underwrite long-term obligations.
Global Geocomposites Market Segmentation
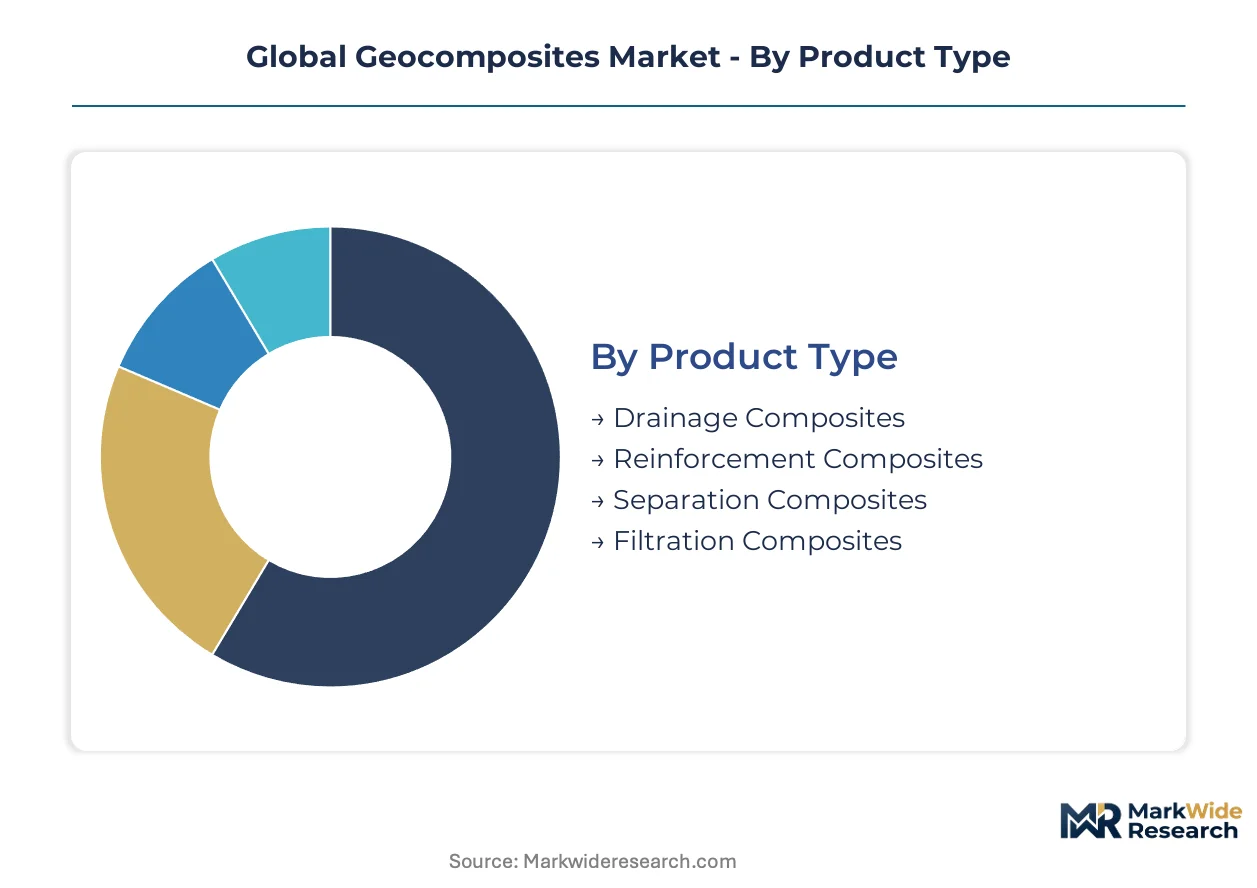
Geocomposite specifications diverge sharply across civil infrastructure end-uses, with polymer selection and bonding technology directly determining performance in high-load railway subgrades versus static landfill containment. Procurement patterns in this market cluster around hydraulic conductivity requirements for drainage functions and tensile modulus thresholds for reinforcement applications, creating distinct supplier qualification tiers.
Product Type:
Cost sensitivity separates landfill operators seeking standardized drainage laminates from railway authorities demanding certified reinforcement systems with 20-year performance warranties.
- Drainage Composites:Geotextile-geonet laminates engineered for transmissivity exceeding 1×10⁻³ m/s dominate landfill leachate collection and tunnel waterproofing specifications. German tunnel contractors now mandate machine-verified basis weights for these products under federal transport investment programs, compressing defect rates and enabling just-in-time delivery for rail corridors.
- Reinforcement Composites:High-tensile polymer geogrids bonded to nonwoven substrates deliver ballast stabilization for railway subgrade modernization across Germany, France, and Japan. Federal specifications in Germany are pulling volume from conventional aggregate methods, forcing manufacturers to reconfigure production lines toward these high-specification products.
- Separation Composites:Basic geotextile layers prevent intermixing of subgrade soils and aggregate in road construction applications.
- Filtration Composites:Coastal erosion control projects in Gujarat and Tamil Nadu drive specification of these mature-margin products for cyclone resilience infrastructure.
Drainage composites lead volumes today; reinforcement composites are gaining share fastest.
Technology:
Application performance requirements dictate bonding method selection, with hydraulic conductivity targets favoring continuous extrusion and structural load specifications demanding mechanical interlock durability.
- Needlepunching:Barbed needle mechanical entanglement of staple fibers creates robust geotextile substrates for drainage composite manufacturing. Automated lines with real-time basis-weight control now dominate production for landfill containment specifications in the United States.
- Thermal Bonding:Calendered heat fusion of polymer fibers delivers dimensional stability for reinforcement geogrids in railway subgrade applications. Japanese rail operators specify thermally bonded composites for high-speed corridor ballast stabilization under JIS standards.
- Extrusion Lamination:Continuous polymer extrusion bonding of geonets to geomembranes enables high-flow drainage products for tunnel waterproofing.
- Stitching:Mechanical yarn interlock provides flexible bonding for erosion control composites in coastal protection.
- Stitchbonding:Warp-knitted fiber fixation creates structured geotextiles for separation functions in road construction.
Needlepunching commands installed capacity; extrusion lamination is climbing the fastest as tunnel specifications tighten.
Application:
Project scale and regulatory oversight intensity create divergent procurement patterns, with federal transport programs concentrating demand in railway applications and EPA mandates standardizing landfill liner specifications.
- Railway Subgrade:Polymer-geogrid reinforcement systems stabilize ballast layers against cyclic loading and settlement in high-speed rail corridors. Germany's federal transport investment programs specify these solutions for subgrade modernization, displacing conventional aggregate methods across European rail networks.
- Landfill Liners:Multilayer drainage composites with geomembrane protection layers form leachate collection systems under EPA Subtitle D regulations. United States waste management operators specify certified products with documented hydraulic transmissivity for containment cell construction.
- Road Construction:Separation and reinforcement composites reduce aggregate thickness in highway subbase applications.
- Erosion Control:Biodegradable and synthetic filtration composites stabilize slopes and shorelines against hydraulic scour.
- Retaining Structures:Geogrid-soil reinforcement systems provide facing support for mechanically stabilized earth walls.
Railway subgrade is expanding most quickly; road construction retains the largest installed base.
End User Industry:
Contractor capability and project financing structures segment buyers, with tier-one civil infrastructure firms absorbing long-term performance risk and mining operators prioritizing upfront material cost minimization.
- Civil Infrastructure:Federal and state transport agencies specify geocomposites for road, rail, and tunnel projects with 20-year design lives. German engineering firms now bundle performance warranties with material procurement, concentrating buyer power among balance-sheet-capable contractors.
- Environmental Engineering:Landfill containment and remediation specialists source drainage composites under EPA and EU regulatory frameworks. REACH chemical compliance requirements from ECHA add 18-24 month certification timelines for new geotextile chemistries entering European markets.
- Water Management:Coastal protection and flood control authorities deploy erosion control composites for shoreline stabilization.
- Mining:Heap leach pad and tailings dam operators utilize chemical-resistant geomembrane composites.
- Oilfield Services:Secondary containment and pad construction applications drive specification of reinforced geomembrane systems.
Civil infrastructure leads procurement volumes; environmental engineering shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent clusters around Stuttgart and Munich anchor European geocomposite specification development. Japanese polymer scientists in Nagoya and Osaka drive high-tensile reinforcement innovation. Indian coastal engineers in Gujarat and Tamil Nadu are accelerating erosion control adoption.
United States
EPA Subtitle D landfill liner mandates concentrate drainage composite demand in Texas and California waste management corridors. The EPA enforces documented hydraulic transmissivity certification for containment cell construction. Houston-based engineering firms bundle 20-year performance warranties with material procurement for Gulf Coast petrochemical containment projects.
Germany
Federal transport investment programs specify polymer-geogrid solutions for railway subgrade modernization across the Rhine-Ruhr corridor. The EU Green Deal infrastructure resilience provisions accelerate material upgrades in tunnel waterproofing specifications. Stuttgart engineering clusters dominate high-tensile reinforcement composite design for Deutsche Bahn high-speed corridors.
China
SAMR-administered GB standards shape product certification for railway and landfill applications across the Yangtze River Delta. Dual carbon goals stimulate tunnel waterproofing investment requiring alternative geomembrane solutions. Shanghai manufacturing bases supply drainage composites for coastal flood control infrastructure along the Jiangsu shoreline.
Japan
METI rail infrastructure programs specify thermally bonded reinforcement composites for Shinkansen ballast stabilization. JIS standards govern geosynthetic identification and classification testing protocols. Nagoya polymer research institutes develop high-modulus geogrids for cyclic loading resistance in the Tokaido corridor.
India
Cyclone resilience spending accelerates erosion control composite deployment along Gujarat and Tamil Nadu shorelines. BIS certification requirements standardize geotextile performance parameters for coastal protection tenders. Surat engineering contractors source needlepunched filtration composites for Narmada riverbank stabilization projects.
Global Geocomposites Market Competitive Landscape
Top-tier vendors anchor specification-driven premium tiers, while mid-scale fabricators compete on cost-optimized volume. The vendor base stratifies across integrated polymer producers, specialized geosynthetic converters, and regional installation contractors. Three archetypes dominate: backward-integrated resin suppliers with captive feedstock, technology licensors with proprietary bonding patents, and project-integrated engineering firms absorbing installation risk. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Among European-based specialists, HUESKER Synthetic GmbH and NAUE GmbH & Co. KG exemplify the premium-tier reinforcement archetype with German engineering lineage. TenCate Geosynthetics represents the vertically integrated multinational structure. SKAPS Industries anchors the North American cost-optimized segment. These three names illustrate how competitive positioning fragments across geographic specialization and integration depth rather than product overlap.
| Leading Market Players |
|---|
| TenCate Geosynthetics |
| GSE Environmental |
| HUESKER Synthetic GmbH |
| Officine Maccaferri Spa |
| Thrace Group |
| SKAPS Industries |
| ABG Ltd |
| Leggett & Platt |
| NAUE GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Polypropylene resin indices on the US Gulf Coast cascade through three distinct pricing tiers, with captive petrochemical supply anchoring premium drainage composite margins while spot-market exposure compresses economy-grade geotextile profitability in Asian export hubs.
Pricing Analysis
Bundled 20-year performance warranties now command 15-25% premiums over transactional material procurement in German railway contracts, while unbundled component sales dominate landfill liner specifications in the United States. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10318-certified reinforcement systems from basic needlepunched separation fabrics. Pricing pressure stems from crude oil-linked polypropylene volatility, with quarterly resin swings eroding fixed-price civil infrastructure margins. Mining operators in developing markets exhibit highest price sensitivity, while Deutsche Bahn and JR East absorb premium positioning for guaranteed settlement-rate performance.
Supply Chain Analysis
ISO 10318 and REACH certification timelines gate European market access, stretching supplier qualification to 18-24 months and concentrating procurement among balance-sheet-capable tier-one contractors. Manufacturing gravity centers on Germany, the United States, and China, with Stuttgart engineering clusters and Houston petrochemical corridors anchoring high-specification output. Polypropylene pellet supply draws from integrated US Gulf Coast complexes, polyester staple fiber feeds from Chinese petrochemical bases, and high-tenacity polyester yarn sources from Japanese polymer institutes. Single-source vulnerability concentrates in specialized geogrid extrusion equipment from German machinery builders. Distribution runs through project-integrated engineering firms absorbing installation risk alongside material procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with German and Japanese railway operators consolidating procurement around 20-year performance warranties that displace transactional purchasing and concentrate margin with specification-capable incumbents.
For Market Incumbents: Lock in specification control by acquiring captive polypropylene resin supply or securing long-term offtake from US Gulf Coast crackers, insulating margins from quarterly volatility that erodes fixed-price civil infrastructure contracts. Deepen certification moats through accelerated ISO 10318 testing investment, compressing product launch cycles below the 8-12 month industry standard and starving mid-tier competitors of specification access. Threat vector: bio-based geotextile entrants capturing EU public procurement sustainability scoring. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian coastal protection tenders opens white-space positioning for cost-optimized needlepunched filtration composites against European import pricing. Target Gujarat and Tamil Nadu cyclone resilience programs with localized stitching and stitchbonding capacity, leveraging BIS certification as entry gating rather than full ISO compliance. Go-to-market angle: Surat-based engineering contractor partnerships bundling installation expertise with material supply. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale German geosynthetic converters possessing REACH-authorized chemistries and Deutsche Bahn qualification history, positioned for consolidation by resin-integrated multinationals seeking European railway specification access. Five-to-ten year viability hinges on polymer-geogrid share capture in high-speed rail corridors versus aggregate substitution resilience. Signal to watch: Indian government PLI scheme extensions for domestic geotextile manufacturing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Feedstock | Captive resin supply from US Gulf Coast crackers stabilizes input costs against quarterly volatility. |
| REACH Certification Fast-Track Investment | ECHA authorization timelines compress from 24 months to 12 months, accelerating European market entry. |
| Indian Coastal Manufacturing Footprint | Gujarat production bases capture cyclone resilience tenders under BIS localization requirements. |
| Extrusion Lamination Technology Licensing | German machinery partnerships enable high-flow drainage products exceeding tunnel waterproofing specifications. |
| 20-Year Performance Warranty Bundling | Deutsche Bahn and JR East contracts absorb installation risk and guarantee subgrade settlement rates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with geosynthetic plant managers, civil infrastructure procurement leads at Deutsche Bahn and JR East, EPA compliance officers, and Indian coastal engineering contractors with secondary validation. Trade data from USITC and Eurostat, SEC filings from resin-integrated multinationals, ECHA substance authorization databases, and BIS certification registries anchored volume estimation. Bottom-up project pipeline analysis across German railway subgrade programs and Indian coastal protection tenders triangulated against top-down polymer feedstock consumption models.
Segment-weighting applied product type, bonding technology, and application dimensions across the analysis window, with drainage composites, reinforcement composites, and filtration composites each carrying distinct growth trajectories. CAGRs derived from elasticity modeling against railway capital expenditure cycles and landfill containment cell construction permits. Industry-specific forecast inputs included Deutsche Bahn federal transport investment program allocations and EPA Subtitle D enforcement intensity trends.
Caveats apply where polymer price volatility, REACH authorization delays, or bio-based geotextile commercialization pace could materially shift the outlook. Forecasts reflect assumptions about crude oil linkage persistence and railway operator warranty adoption thresholds. A model refresh is warranted upon material change in German federal transport budget allocations or Indian PLI scheme geotextile manufacturing incentives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
China Marine Composites Market
Composite Materials
Global Composites Cylinder Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Turbine Blade Material Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Pcb Laminate Materials Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Copper Clad Laminates Market