
 Polycarbonate Composites Market | 2026-2036
Polycarbonate Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Polycarbonate Composites Market Analysis
Market Dynamics
The capital-intensity divergence between integrated resin producers and downstream compounders is reorganizing competitive tiers in polycarbonate composites. Covestro leverages its backward integration into bisphenol A and phosgene chemistry to sustain margin capture across aerospace-grade sheets. SABIC Innovative Plastics anchors its position through geographic dominance in the Middle East feedstock corridor, while LG Chem differentiates via specialty optical grades for electronics.
Product Landscape
Polycarbonate composites are engineering thermoplastics formed by alloying polycarbonate resin with glass fibers, mineral fillers, or elastomeric modifiers to achieve specific stiffness, impact resistance, and thermal dimensional stability targets. These materials serve critical functions where transparent or semi-transparent structural performance replaces glass, metal, or lesser thermoplastics in weight-sensitive assemblies. Impact-Resistant Sheets occupy the largest volume position across automotive glazing and safety equipment, while Glass-Like Sheets command premium positioning in medical equipment and high-end lighting fixtures where optical clarity meets sterilization tolerance. Reinforced forms capture expanding share in under-hood automotive applications as OEMs pursue metal replacement at elevated continuous-use temperatures.
Regulatory Environment
The EPA oversees volatile organic compound emissions from sheet extrusion operations, while REACH restricts certain halogenated flame retardants in European electronics applications; both frameworks elevate formulation costs for non-compliant suppliers. China's MEE enforces increasingly stringent wastewater standards around bisphenol A production, tightening feedstock availability for domestic compounders. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where certification burdens will shift sourcing patterns.
Market Dynamics
Automotive lightweighting mandates in Germany and Japan are compressing substitution cycles for glass and metal components, forcing compounders to certify flame-retardant grades under divergent EPA and REACH frameworks simultaneously.
Growth Catalysts
- EV battery enclosure demand:China's eastern manufacturing corridor clusters appliance and EV supply chains, concentrating procurement for thermally stable polycarbonate grades. Local compounders scale capacity to serve CATL and BYD tier-one suppliers.
- REACH flame-retardant reformulation:European electronics OEMs face mandatory halogen-free transitions by 2026, pulling non-brominated additive packages into medical equipment and high-end lighting fixtures.
- Optical grade specialization:Korean display panel manufacturers specify low-birefringence polycarbonate for AR/VR lens substrates, creating premium pricing tiers distinct from commodity sheet extrusion.
Market Restraints
- Bisphenol A feedstock volatility:China's MEE wastewater enforcement tightens domestic phenol-acetone availability, elevating working capital requirements for non-integrated compounders in Shandong and Jiangsu provinces.
- Acrylic substitution in glazing:Eastman and Mitsubishi Chemical advance weatherable acrylic systems for automotive side windows, threatening polycarbonate's optical clarity positioning in exterior applications.
- Sheet extrusion energy intensity:German automotive suppliers face ETS carbon cost passthroughs exceeding €80 per tonne, compressing margins on thick-gauge safety glazing production.
Strategic Opportunities
- Underpenetrated Indian appliance sector:BIS certification timelines for refrigerator inner liners lag Chinese standards by 18-24 months, opening first-mover positioning for flame-retardant sheet producers before domestic capacity scales.
- Recycled content mandates:The EU Green Deal's 25% post-consumer recycled plastic targets for electronics housings by 2025 create formulation partnerships between resin producers and mechanical recyclers.
- 5G small cell infrastructure:NMPA radio frequency transparency standards in China specify low-dielectric polycarbonate for antenna radomes, displacing traditional thermoset composites in base station deployments.
Industry Challenges
- Multi-jurisdiction certification backlog:Compounders serving automotive OEMs face 14-18 month validation cycles for simultaneous UL 94 V-0, FMVSS 302, and ECE R43 compliance, freezing formulation lock dates ahead of model-year launches.
- Specialized extrusion technician scarcity:Germany's KBA-documented skills gap in thick-gauge optical sheet production limits expansion of medical-grade capacity despite demand pull from sterilizable device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycarbonate Composites Market |
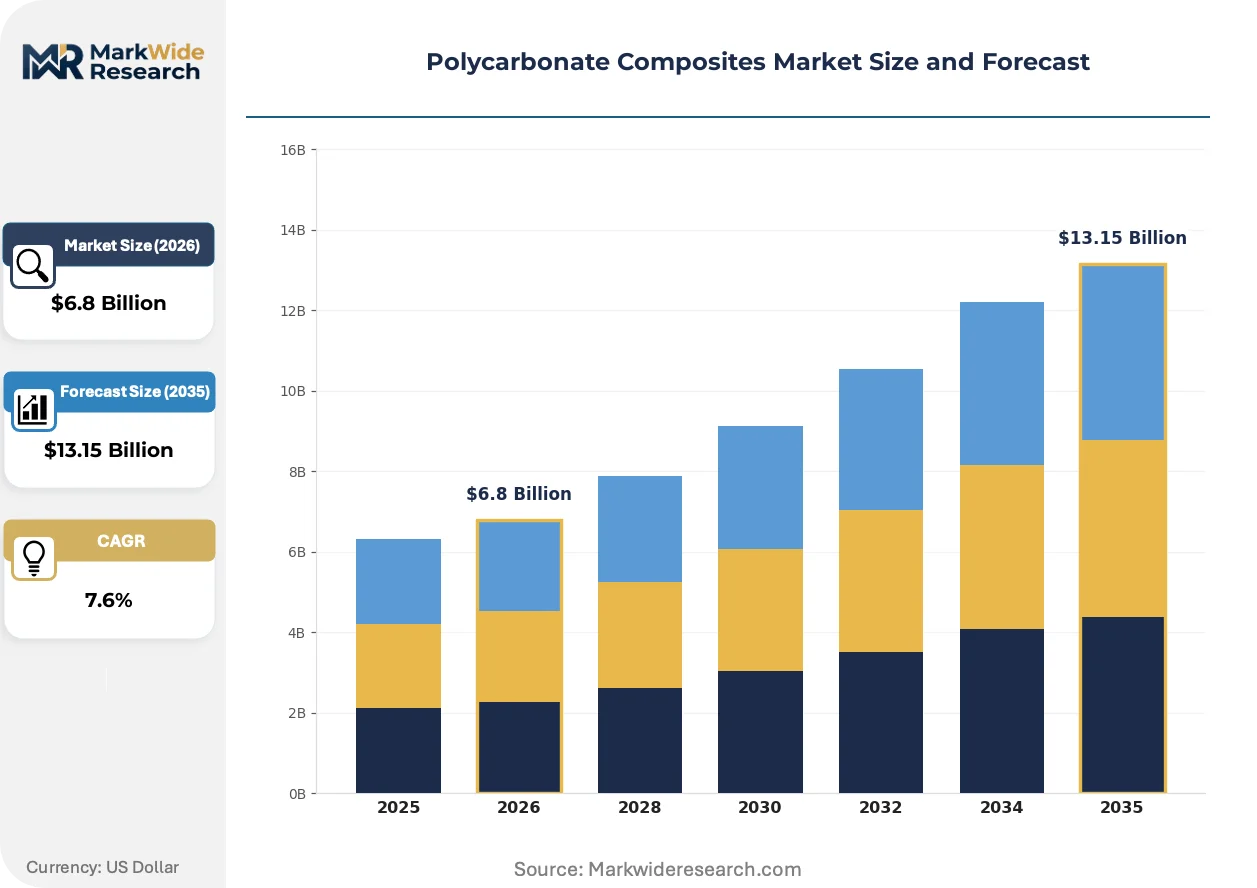
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact-Resistant Sheets, Glass-Like Sheets, Lexan Films, Hollow Sheets End User: Aerospace, Construction, Automotive, Electronics Application: Window Glazing, Lighting Fixtures, Signage, Medical Equipment Form: Solid, Foam, Coated, Reinforced |
| Companies Covered | Covestro, SABIC Innovative Plastics, Asahi Kasei Advance Corporation, Chi Mei Corporation, Formosa Chemicals & Fibre Corporation, LG Chem, Mitsubishi Chemical Corporation, Samyang Corporation, Sumika Polycarbonate Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycarbonate Composites Market Emerging Trajectories
Formulation science and processing control are diverging along performance-specialized versus cost-optimized trajectories, splitting the competitive landscape into distinct capability tiers.
Co-extruded multi-layer polycarbonate sheet is bifurcating the automotive glazing market. Tier-one suppliers in Stuttgart and Nagoya specify hard-coated UV-blocking surfaces for panoramic roof modules, while Chinese EV startups procure uncoated base grades for interior trim. This technology compression is collapsing single-layer commodity pricing while expanding premium coating service margins.
REACH Annex XIV authorization requirements for short-chain chlorinated paraffins are forcing reformulation of legacy flame-retardant packages. German electrical enclosure manufacturers now specify phosphorus-nitrogen synergist systems, passing €200-400 per tonne additive costs to industrial automation OEMs. Medical device producers in Ireland accelerate halogen-free qualification to preempt supply disruption.
Direct-to-OEM procurement platforms are disintermediating regional distributors for standardized sheet grades. Automotive interior suppliers in Shanghai and Detroit now contract resin producers through integrated vendor-managed inventory systems, compressing spot-market volumes. This channel consolidation concentrates pricing power with compounders holding AS9100 aerospace and IATF 16949 automotive certifications.
Polycarbonate Composites Market Segmentation
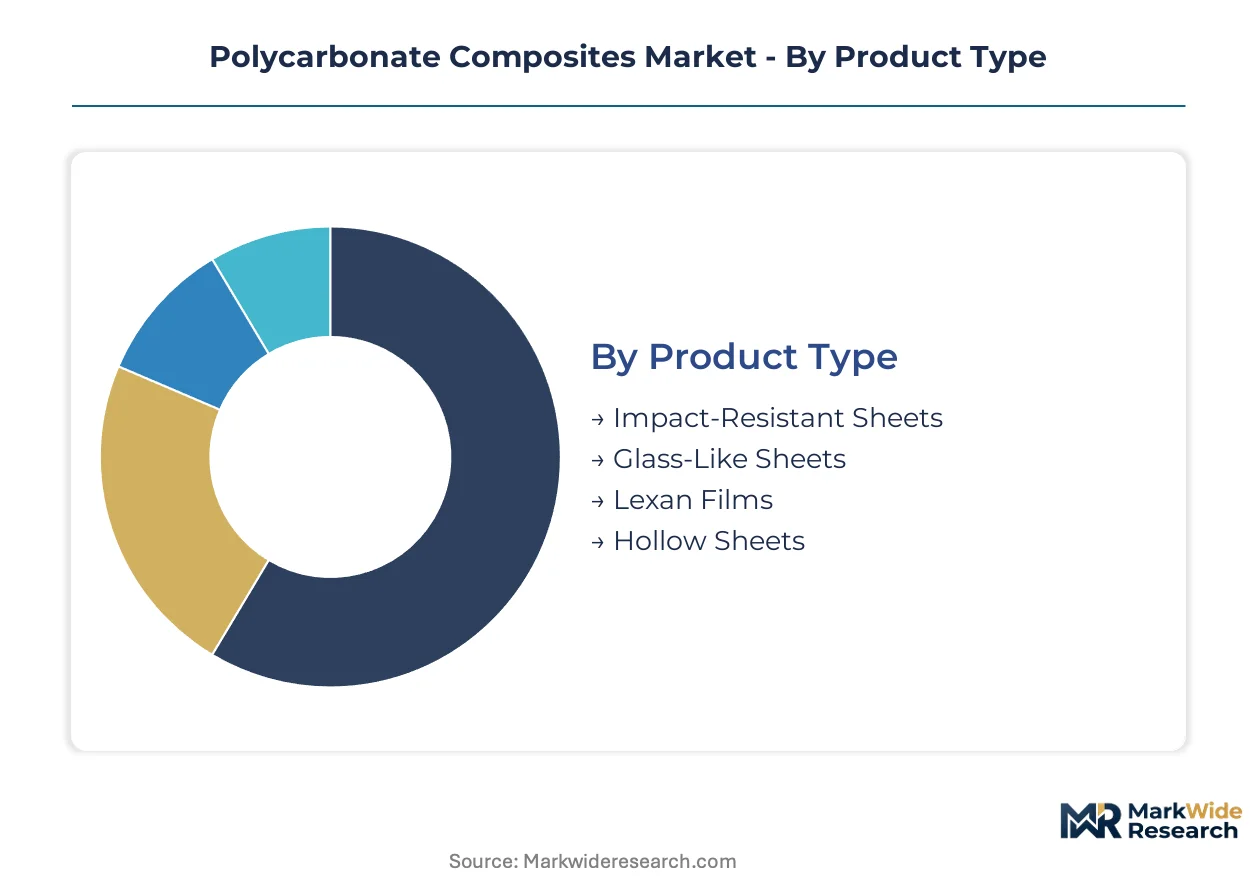
Segmentation in polycarbonate composites reveals how formulation specialization separates domestic appliance supply from export-driven automotive and electronics certification chains. Understanding these splits exposes where margin capture concentrates versus where volume commoditization pressures compound.
Product Type:
Domestic markets in China and India absorb commodity sheet grades, while export-led demand for optical and aerospace-certified products flows through German and Japanese compounders.
- Impact-Resistant Sheets:These grades alloy polycarbonate resin with elastomeric modifiers to achieve ductile failure modes under dynamic loading. German automotive suppliers specify these for panoramic roof modules facing ECE R43 certification, though acrylic substitution in side windows threatens exterior positioning. Impact-Resistant Sheets hold the largest share; momentum sits with Glass-Like Sheets.
- Glass-Like Sheets:Optical-grade polycarbonate achieves light transmission above 90% with minimal birefringence through controlled molecular orientation. Korean display panel manufacturers drive demand for AR/VR lens substrates, creating premium tiers distinct from commodity extrusion. REACH flame-retardant reformulation is pulling halogen-free grades into Irish medical device production.
- Lexan Films:Thin-gauge calendered products serve membrane switch overlays and instrument cluster faces in Detroit automotive supply chains.
- Hollow Sheets:Multi-wall extruded profiles deliver thermal insulation for Chinese agricultural greenhouse construction and European industrial roofing.
Impact-Resistant Sheets anchor volume; Glass-Like Sheets command pricing power through optical certification.
End User:
Cost-tier segmentation separates specification-heavy aerospace and automotive from price-sensitive construction procurement.
- Aerospace:AS9100-certified sheet producers supply cockpit transparencies and cabin interior components where flame-smoke-toxicity standards exceed automotive benchmarks. Boeing and Airbus tier-one suppliers in Wichita and Toulouse consolidate procurement with compounders holding captive resin supply.
- Construction:Unfilled sheet grades dominate skylight and cladding applications where UV weatherability determines replacement cycles. Chinese distributors stock standard widths for provincial infrastructure projects, compressing margins on non-differentiated extrusion.
- Automotive:OEM lightweighting programs in Stuttgart and Nagoya specify hard-coated grades for fixed glazing, while interior trim accepts uncoated base material.
- Electronics:EU Green Deal recycled content mandates are reshaping enclosure formulation partnerships between resin producers and mechanical recyclers.
Construction captures volume throughput; aerospace retains margin concentration.
Application:
Application splits track how sterilization tolerance and optical precision create specification moats versus commoditized signage demand.
- Window Glazing:Automotive panoramic roofs and architectural facades specify UV-blocking co-extruded surfaces. German ETS carbon costs exceeding €80 per tonne compress thick-gauge safety glazing margins.
- Lighting Fixtures:High-end LED housings in medical and commercial settings demand Glass-Like Sheet clarity with thermal dimensional stability. BIS certification lags in India open first-mover positioning before domestic capacity scales.
- Signage:UV-printable sheet grades serve retail and transit advertising with minimal performance differentiation.
- Medical Equipment:Sterilizable device housings and surgical lighting lenses require gamma-radiation-stable formulations.
Window Glazing leads volume; Medical Equipment climbs fastest on sterilization qualification requirements.
Form:
Form differentiation separates reinforced and coated value-added grades from commodity solid sheet.
- Solid:Standard extruded sheet serves general-purpose glazing and thermoformed components where optical perfection is secondary.
- Foam:Microcellular structures reduce weight for interior automotive panels and transport packaging applications.
- Coated:Hard-coated UV-resistant surfaces command premium positioning in automotive exterior glazing. Stuttgart suppliers specify these for scratch resistance and weatherability validation.
- Reinforced:Glass fiber or mineral-filled compounds achieve metal replacement stiffness in under-hood automotive and 5G antenna radome applications. NMPA radio frequency transparency standards in China specify low-dielectric grades for base station deployments.
Solid form dominates tonnage; Reinforced grades gain share on metal substitution programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese automotive supply chains, while Chinese compounders compete on volume throughput. This asymmetry shapes where margin capture accumulates versus where capacity expansion concentrates.
United States
EPA standards for volatile organic compound emissions from sheet extrusion operations elevate formulation costs for domestic compounders. The agency oversees compliance timelines that freeze formulation lock dates ahead of automotive model-year launches. Detroit automotive supply chains cluster procurement for membrane switch overlays and instrument cluster faces through integrated vendor-managed inventory systems.
Germany
KBA-documented skills gaps in thick-gauge optical sheet production limit medical-grade capacity expansion despite sterilizable device manufacturer demand. ETS carbon cost passthroughs exceeding €80 per tonne compress margins on safety glazing production. Stuttgart tier-one suppliers specify hard-coated UV-blocking surfaces for panoramic roof modules, consolidating procurement with AS9100-certified compounders.
China
MEE wastewater enforcement around bisphenol A production tightens feedstock availability for Shandong and Jiangsu compounders. NMPA radio frequency transparency standards specify low-dielectric polycarbonate for 5G antenna radomes in base station deployments. The eastern manufacturing corridor clusters appliance and EV supply chains, concentrating procurement for thermally stable grades serving CATL and BYD tier-one suppliers.
Japan
METI lightweighting mandates compress substitution cycles for glass and metal components in automotive glazing applications. JIS standards govern optical-grade specifications for display panel manufacturers. Nagoya-based tier-one suppliers specify hard-coated grades for fixed glazing while accepting uncoated base material for interior trim applications.
India
BIS certification timelines for refrigerator inner liners lag Chinese standards by 18-24 months, opening first-mover positioning for flame-retardant sheet producers. The central bank's working capital requirements elevate financing costs for non-integrated compounders. Domestic appliance manufacturers in Maharashtra and Gujarat scale procurement before local capacity reaches export-grade certification thresholds.
Polycarbonate Composites Market Vendor Landscape
Concentration sits with integrated resin producers controlling captive bisphenol A and phosgene chemistry. Three archetypes define competitive positioning: backward-integrated petrochemical conglomerates, specialty optical-grade compounders, and regional sheet extrusion specialists. Dominant moves include AS9100 aerospace and IATF 16949 automotive certification acquisition and co-extruded multi-layer technology deployment for automotive glazing differentiation.
Within the integrated-resin tier, Covestro leverages upstream control over feedstock chemistry to sustain margin capture across aerospace-grade sheet production. SABIC Innovative Plastics anchors its position through geographic dominance in Middle East feedstock corridors. LG Chem exemplifies the specialty-grade archetype, differentiating via low-birefringence optical formulations for electronics applications. These three represent distinct capability vectors: feedstock integration, geographic feedstock access, and formulation specialization.
| Leading Market Players |
|---|
| Covestro |
| SABIC Innovative Plastics |
| Asahi Kasei Advance Corporation |
| Chi Mei Corporation |
| Formosa Chemicals & Fibre Corporation |
| LG Chem |
| Mitsubishi Chemical Corporation |
| Samyang Corporation |
| Sumika Polycarbonate Limited |
| Others |
Supply Flow & Price Mechanics
Acrylic substitution in automotive side glazing simultaneously redraws supply geography toward Eastman and Mitsubishi Chemical production nodes and compresses pricing power for commodity polycarbonate sheet grades. This substitution dynamic forces polycarbonate compounders to retreat into certified optical and medical grades where specification moats defend margins.
Pricing Analysis
The customization-premium spread between configured-to-order aerospace-grade sheet and standard commodity extrusion runs three-to-one across German supply chains. Contract-based long-term offtake dominates automotive procurement, with price differentiation driven by AS9100 certification tier and volume scale commitments. Pricing pressure stems from ETS carbon cost passthroughs exceeding €80 per tonne, squeezing thick-gauge safety glazing margins. Construction distributors exhibit highest price sensitivity, while medical device OEMs absorb premium additive costs for halogen-free qualification.
Supply Chain Analysis
Just-in-time inventory strategies dominate Stuttgart and Nagoya automotive supply chains, while Chinese compounders maintain strategic stockpiles of bisphenol A feedstock against MEE enforcement volatility. Geographic supply concentration centers on Germany, China, and Japan, with raw material dependencies on phenol-acetone chemistry, phosgene derivatives, and phosphorus-nitrogen flame retardants. Single-source vulnerability sits with Middle East feedstock corridors controlled by SABIC. Distribution runs through integrated vendor-managed inventory systems for automotive OEMs, bypassing regional distributors for standardized grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XIV authorization deadlines for short-chain chlorinated paraffins constitute a regulatory inflection compressing formulation timelines and rewarding pre-qualified halogen-free suppliers. This disruption accelerates consolidation around compounders with captive resin supply and certification depth.
For Market Incumbents: Compound defensive positioning through backward integration into bisphenol A chemistry and accelerated AS9100/IATF 16949 certification acquisition. Acrylic substitution in exterior glazing and ETS carbon cost passthroughs threaten commodity sheet margins; vertical integration into feedstock production and co-extruded multi-layer technology deployment represent priority levers for margin defense. For New Entrants and Emerging Players: Differentiate on specialty optical grades for Korean AR/VR lens substrates and Indian appliance sector flame-retardant sheet supply ahead of domestic capacity scaling. The underpenetrated Indian BIS certification lag offers 18-24 month white-space opportunity; direct-to-OEM procurement platform partnerships provide viable go-to-market angle against established distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated compounders with certification moats and captive feedstock supply. Long-term viability over the next decade hinges on EU Green Deal recycled content mandate compliance and 5G infrastructure material qualification. The signal to watch is NMPA low-dielectric specification adoption velocity for antenna radome displacement of thermoset composites.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol A Chemistry | Covestro's upstream control sustains margin capture across aerospace-grade sheet production. |
| Co-extruded Multi-layer Technology Deployment | Stuttgart suppliers specify hard-coated UV-blocking surfaces for panoramic roof differentiation. |
| Halogen-free Flame Retardant Reformulation | REACH Annex XIV compliance pulls phosphorus-nitrogen systems into Irish medical device production. |
| AS9100 Aerospace Certification Acquisition | Boeing and Airbus tier-one suppliers consolidate procurement with certified compounders. |
| Direct-to-OEM Procurement Platform Launch | Shanghai and Detroit automotive suppliers bypass distributors through integrated inventory systems. |
Methodological Framework
The analysis maps impact-resistant sheet, glass-like sheet, and reinforced compound sub-sectors, each validated through primary interviews with plant managers at integrated resin producers, procurement leads at automotive Tier 1 suppliers, and technical R&D directors at specialty compounders. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH regulatory filings. Bottom-up segment sizing and top-down macroeconomic triangulation ensure consistency across volume and value outputs.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework models grade tier, end-use industry, and regional production hub segmentation dimensions. CAGRs derive from historical trajectory analysis adjusted for substitution elasticity and regulatory compliance cost passthroughs. Forecast inputs include EV battery enclosure content per vehicle trends and 5G infrastructure deployment pipelines.
Forecasts assume regulatory continuity in REACH, EPA, and MEE enforcement regimes; material policy shifts would require re-modeling around flame-retardant authorization timelines or carbon pricing trajectories. Revision becomes warranted when acrylic substitution rates in automotive glazing or NMPA low-dielectric specification adoption cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Thermoset Composites Market
Composite Materials
CFRTP Market
Composite Materials
Isostatic Graphite Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Global Sports Composites Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Pultrusion Market
Composite Materials
Global Geocomposites Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Phenolic Panel Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Pcb Laminate Materials Market
Composite Materials
Synthetic Rope Market
Composite Materials
Case Material Market
Composite Materials
Copper Clad Laminates Market