
 Global Cosmetic Dyes Market | 2026-2036
Global Cosmetic Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Dyes Market Foresight
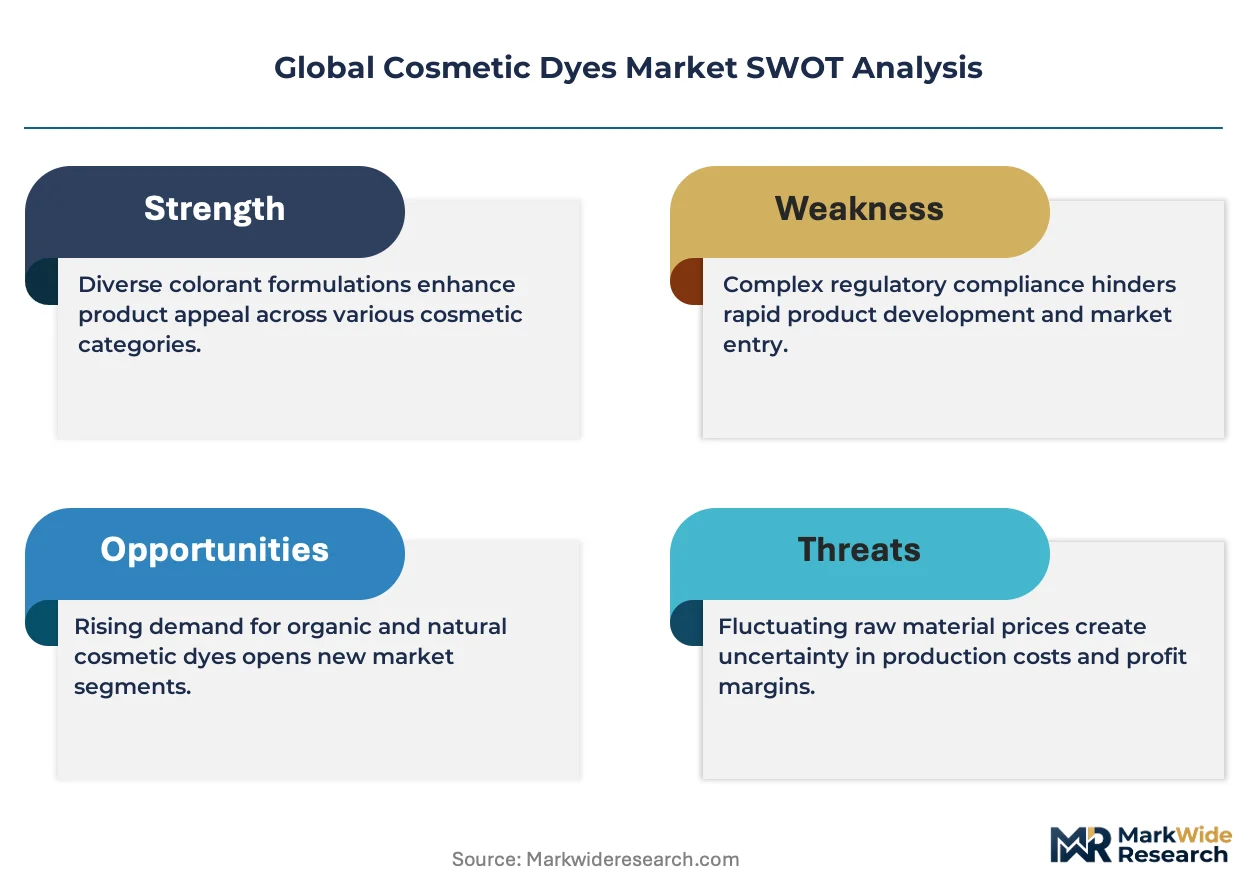
The capital-intensity divergence between integrated pigment manufacturers and specialty dye blenders is unwinding competitive stability in cosmetic colorants. BASF SE leverages its petrochemical backbone to sustain captive intermediate supply for azo and lake pigments. Sensient Cosmetic Technologies anchors premium natural colorant development through botanical extraction capabilities. Clariant competes by dominating halogen-free dye certifications for European personal care brands.
Cosmetic dyes encompass organic molecules, inorganic metal oxides, and lake complexes that impart color to skin, hair, and nail formulations through selective light absorption or particulate dispersion, typically requiring heavy metal limits below 20 ppm and batch-to-batch Delta E consistency of 1.0 or less. Organic dyes command the widest formulation flexibility in lipsticks and hair colorants where solubility-driven shade precision matters. Natural colorants represent the fastest-expanding product type as clean-label mandates from cosmetics manufacturers reshape procurement specifications. Inorganic pigments retain margin density in eye shadows and foundations where opacity and photostability resist substitution.
REACH registration requirements under ECHA govern synthetic dye imports into Europe, while FDA 21 CFR 73 and 74 listings determine permissible color additives for US cosmetics manufacturers. The EU F-Gas Regulation and evolving MEE discharge standards in China additionally constrain solvent-based dye processing. Stakeholders must monitor regulatory divergence between permissible synthetic dye lists in North America and Europe when configuring regional formulation portfolios.
Market Dynamics
Clean-label procurement mandates from personal care conglomerates are compressing synthetic dye volumes while forcing capital reallocation toward botanical extraction infrastructure and lake pigment certification pipelines.
Growth Catalysts
- FDA 21 CFR 74 expansion:New listings for iron oxide complexes in lip and eye applications opened formulation latitude for mineral pigment suppliers serving US cosmetics manufacturers.
- Halal certification penetration:Malaysia and Indonesia now require alcohol-free extraction solvents for colorants, pulling investment into supercritical CO2 processing equipment across Southeast Asian supply bases.
- Biotechnology fermentation:Microbial-derived carotenoids and anthocyanins achieved commercial scale, offering batch consistency that agricultural extraction cannot match for premium skincare lines.
Market Restraints
- Petrochemical intermediate volatility:Crude-derived naphthalene and aniline feedstock costs swing 15-40% quarterly, eroding margin predictability for azo dye manufacturers without captive aromatics supply.
- European import concentration:60% of certified lake pigments for EU cosmetics originate from three German chemical parks, creating single-point vulnerability during ECHA compliance audits.
- Natural colorant stability ceiling:Anthocyanin pH sensitivity and curcumin photodegradation limit shelf life to 8-12 months, blocking adoption in mass-market retail distribution cycles.
Strategic Opportunities
- Brazil ANVISA fast-track pathway:Simplified colorant additive approvals for botanical extracts create first-mover advantage for suppliers establishing local analytical laboratories.
- India PLI scheme for specialty chemicals:Production-linked incentives cover 30% of capital expenditure for fermentation-based natural dye facilities serving domestic and export markets.
- Direct-to-brand digital platforms:Specialty dye blenders bypass traditional distributor markups by offering cloud-based shade matching and batch tracking to mid-size cosmetics formulators.
Industry Challenges
- Cross-functional formulation chemists:Shortage of specialists who bridge colorimetry, regulatory toxicology, and scale-up engineering delays product development cycles by 4-6 months.
- Dual certification timelines:Simultaneous REACH dossier preparation and FDA color batch certification requires 18-24 month lead times that misalign with seasonal cosmetics launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Dyes Market |
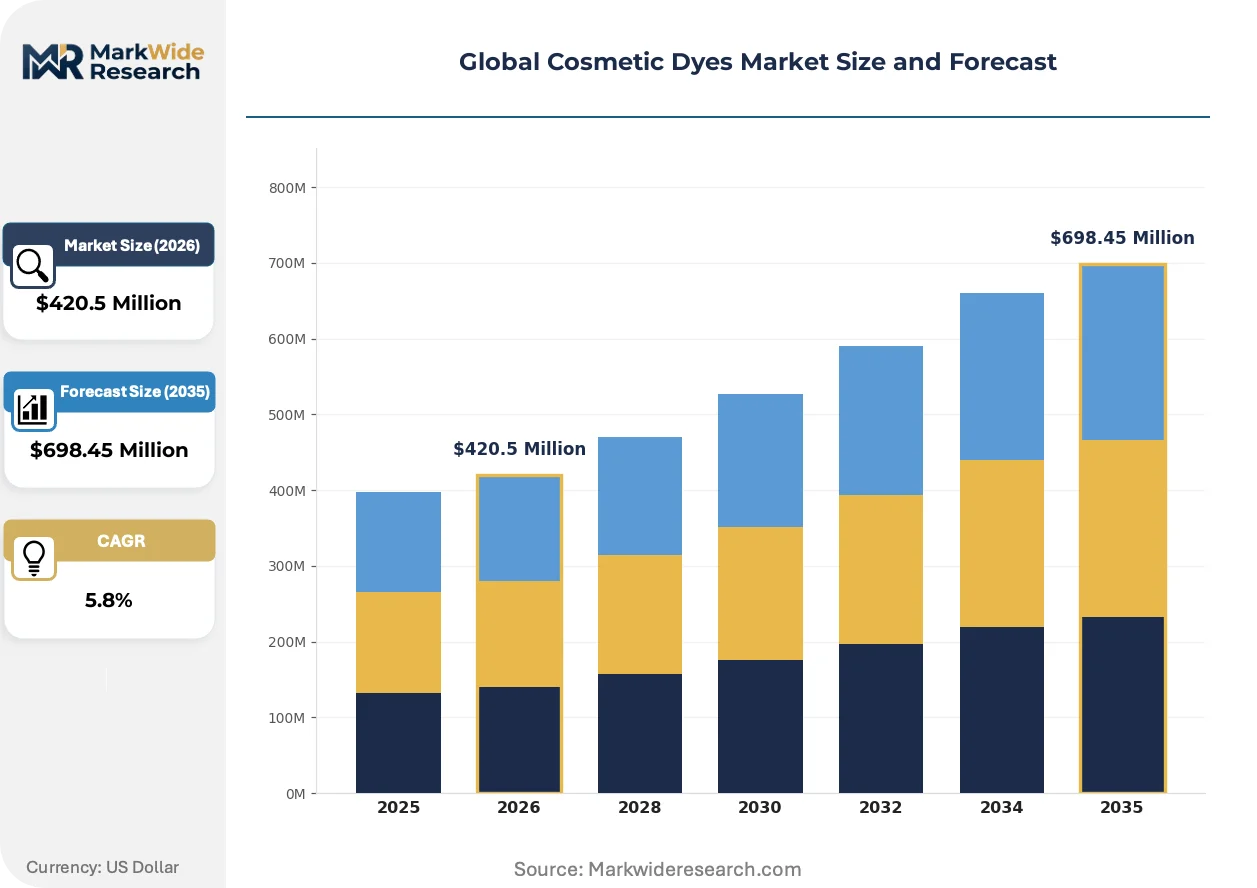
| Market Size in 2026 | $420.5 Million |
| Market Size in 2035 | $698.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Dyes, Inorganic Pigments, Synthetic Dyes, Natural Colorants, Lakes Application: Lipsticks, Foundations, Eye Shadows, Nail Polishes, Hair Colorants End User: Beauty Salons, Cosmetics Manufacturers, Personal Care Brands, Professional Makeup Artists, Dermatology Clinics Distribution Channel: Specialty Stores, E-Commerce Platforms, Pharmacies, Supermarkets, Direct Sales |
| Companies Covered | Sensient Cosmetic Technologies, Clariant, DyStar, BASF SE, DIC Corporation, Neelikon Food Dyes and Chemicals Limited, Sun Chemical Corporation, Koel Colours Private Limited, Chromatech Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Dyes Market Shifts & Advancements
Biotechnology-derived colorants and precision fermentation platforms are collapsing the traditional agricultural supply chain for natural dyes, while regulatory divergence between major markets forces parallel certification investments.
Encapsulation technologies using lipid and polysaccharide matrices are fragmenting the natural colorant market by solving stability and release-control problems that previously restricted botanical dyes to premium positioning. Liposome-encapsulated chlorophyll and curcumin now survive pasteurization and UV exposure, enabling adoption by mass-market sun care and foundation manufacturers. The technology is fragmenting competitive advantage away from raw agricultural sourcing toward formulation science capabilities.
REACH authorization requirements under ECHA for certain azo dyes are tightening substance volume thresholds and demanding enhanced toxicity data packages from importers. German and French cosmetics manufacturers now exclude non-authorized synthetic dyes from new product development pipelines entirely. The policy shift is compressing demand for legacy azo chemistries while redirecting procurement budgets toward pre-registered lake pigment and mineral oxide alternatives.
Clean-label transparency requirements are altering buying patterns as cosmetics brands demand full supply chain disclosure from dye suppliers through raw material origin. Third-party blockchain verification platforms are displacing traditional certificate-of-analysis documentation for natural colorant batches. This behavioral shift is most visible in German and US premium skincare markets where ingredient storytelling drives consumer price tolerance.
Global Cosmetic Dyes Market Segmentation
Cosmetic dye procurement splits across four dimensions that determine formulation economics and regulatory exposure. Product chemistry dictates heavy metal compliance burden. Application type governs photostability requirements. End-user concentration shapes batch size and certification depth. Channel selection determines margin capture versus technical service intensity.
Product Type:
Natural colorants face the steepest substitution pressure from biotechnology-derived alternatives, while synthetic azo chemistries confront REACH authorization phase-outs.
- Organic Dyes:Soluble azo and anthraquinone molecules deliver precise shade matching in lipsticks and hair colorants through selective light absorption. Demand concentrates in German and US cosmetics manufacturers seeking batch-to-batch Delta E consistency below 1.0 for premium positioning.
- Natural Colorants:Botanical extracts and fermentation-derived carotenoids serve clean-label mandates from personal care brands. Anthocyanin pH sensitivity and curcumin photodegradation limit shelf life to 8-12 months, constraining mass-market adoption despite biotechnology advances in microbial production.
- Inorganic Pigments:Iron oxides, titanium dioxides, and ultramarines provide opacity and photostability in foundations and eye shadows.
- Synthetic Dyes:Petrochemical-derived colorants face ECHA authorization tightening and FDA 21 CFR 74 listing constraints.
- Lakes:Insoluble dye-precipitate complexes on alumina substrates offer regulatory-compliant alternatives for lip and eye applications.
Inorganic pigments retain volume leadership; natural colorants hold the steepest expansion curve.
Application:
Cost tier differentiation separates premium professional lines from mass-market retail formulations across facial and nail categories.
- Foundations:Mineral oxide blends dominate for opacity and UV stability, with titanium dioxide and iron oxide complexes commanding premium positioning in photoprotective formulations. Indian and US manufacturers drive specification tightening for non-nano particle disclosure.
- Hair Colorants:Oxidative dye precursors and direct dyes require REACH-compliant aromatic amine profiles. German and French salons demand ammonia-free alternatives, shifting procurement toward ME+ (2-methoxy-methyl-p-phenylenediamine) and plant-derived developers.
- Lipsticks:Lake pigments and organic dyes balance migration resistance with regulatory compliance for incidental ingestion exposure.
- Eye Shadows:Inorganic pigments and approved synthetic dyes must meet FDA 21 CFR 73 and 74 listings for periorbital safety.
- Nail Polishes:Film-forming dyes and pigments face volatile solvent regulation under EU F-Gas and MEE discharge standards in China.
Hair colorants anchor procurement volume; foundation actives gain share fastest.
End User:
Customer type stratifies between formulation-scale buyers requiring full certification packages and artisan-scale users prioritizing shade diversity over compliance depth.
- Cosmetics Manufacturers:Integrated personal care conglomerates and contract manufacturers demand REACH dossiers, FDA color batch certifications, and blockchain-verified supply chain documentation. German and US premium skincare brands drive third-party verification platform adoption.
- Beauty Salons:Professional hair color services in Malaysia and Indonesia require halal-certified, alcohol-free extraction solvents, pulling supercritical CO2 processing investment into Southeast Asian supply bases.
- Personal Care Brands:Clean-label mandates compress synthetic dye volumes while expanding botanical extraction infrastructure procurement.
- Professional Makeup Artists:Kit-assemblers prioritize shade range breadth and portability over batch consistency certification.
- Dermatology Clinics:Medical-aesthetic channels demand hypoallergenic certification and heavy metal testing below 20 ppm limits.
Cosmetics manufacturers concentrate procurement spend; beauty salons expand specification influence fastest.
Distribution Channel:
Channel concentration reflects technical service requirements versus transaction efficiency trade-offs across geographic markets.
- E-Commerce Platforms:Direct-to-brand digital interfaces enable cloud-based shade matching and batch tracking for mid-size formulators, bypassing traditional distributor markups. Indian PLI scheme beneficiaries leverage online channels to reach export markets.
- Specialty Stores:Technical service-intensive pigment and dye suppliers maintain physical presence in German chemical parks and US cosmetics clusters for just-in-time formulation support.
- Direct Sales:Integrated manufacturers like BASF SE and Clariant deploy technical representatives for large-account colorimetry and regulatory consulting.
- Pharmacies:OTC cosmetic channels in Brazil and Europe require ANVISA or EMA-aligned documentation for dermocosmetic positioning.
- Supermarkets:Mass-market retail distribution demands 24-month shelf life stability that natural colorants struggle to meet without encapsulation technology.
E-commerce platforms capture volume leadership; specialty stores defend margin position through technical service intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb premium pricing for certified lake pigments and natural colorants with minimal volume elasticity, while Indian and Brazilian formulators remain acutely sensitive to feedstock cost swings in petrochemical-derived azo dyes.
United States
Personal care brands in New York and Los Angeles drive clean-label procurement for botanical colorants with blockchain-verified supply chains. FDA 21 CFR 74 expansion for iron oxide complexes in lip and eye applications opened formulation latitude for mineral pigment suppliers. Cincinnati and Chicago host concentrated contract manufacturing clusters where mid-size formulators access cloud-based shade matching platforms.
Germany
REACH authorization tightening under ECHA compresses demand for legacy azo chemistries while redirecting budgets toward pre-registered lake pigment alternatives. Three chemical parks in Ludwigshafen, Leverkusen, and Frankfurt supply 60% of certified lake pigments for EU cosmetics, creating single-point vulnerability during compliance audits. Premium skincare brands in Hamburg and Munich demand full supply chain disclosure through third-party verification platforms.
India
Production-linked incentives under the PLI scheme cover 30% of capital expenditure for fermentation-based natural dye facilities serving domestic and export markets. Maharashtra and Gujarat host expanding botanical extraction infrastructure as formulators prioritize clean-label positioning for European and North American export contracts. Mumbai-based suppliers leverage e-commerce platforms to bypass traditional distributor markups in mid-size cosmetics segments.
China
MEE discharge standards constrain solvent-based dye processing while dual carbon goals accelerate investment in supercritical CO2 extraction equipment. Shanghai and Guangzhou cosmetics manufacturers face margin pressure from quarterly naphthalene and aniline feedstock cost swings of 15-40%. Yangtze River Delta chemical parks dominate lake pigment production for domestic personal care brands.
Brazil
ANVISA fast-track pathways for botanical colorant additives create first-mover advantage for suppliers establishing local analytical laboratories. São Paulo and Rio de Janeiro beauty salons expand specification influence through halal-certified professional hair color services. Mass-market retail distribution in Southeast Brazil demands 24-month shelf life stability that drives encapsulation technology adoption for natural colorants.
Global Cosmetic Dyes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in cosmetic dyes. BASF SE leverages captive petrochemical supply for azo and lake pigment intermediates, while Sensient Cosmetic Technologies anchors premium natural colorant development through botanical extraction capabilities. Strategic moves concentrate on fermentation platform licensing and halogen-free dye certification pipelines for European compliance.
Within the integrated chemical conglomerate tier, BASF SE and Clariant exemplify divergent positioning: BASF SE represents backward integration into petrochemical feedstocks, while Clariant occupies a position centered on regulatory certification depth for European personal care brands. Sensient Cosmetic Technologies sits within the specialty natural colorant segment, anchoring biotechnology-derived alternatives to agricultural extraction. These three entities collectively illustrate how capital intensity and regulatory proximity determine competitive stability in cosmetic colorant supply.
| Leading Market Players |
|---|
| Sensient Cosmetic Technologies |
| Clariant |
| DyStar |
| BASF SE |
| DIC Corporation |
| Neelikon Food Dyes and Chemicals Limited |
| Sun Chemical Corporation |
| Koel Colours Private Limited |
| Chromatech Incorporated |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German lake pigment manufacturers and premium cosmetics brands lock in both feedstock access and price visibility across volatile petrochemical cycles. These arrangements insulate BASF SE and Clariant from quarterly naphthalene and aniline cost swings while forcing smaller azo dye blenders into spot market exposure.
Pricing Analysis
After-sales certification services and regulatory consulting packages drive lifetime value for specialty dye suppliers serving multinational cosmetics manufacturers. Three-tier pricing structure across premium certified, standard compliant, and economy unverified tiers separates REACH-authorized lake pigments from legacy azo chemistries. Cost compression in synthetic dye segments is intensifying because Indian and Brazilian formulators absorb crude-derived intermediate volatility directly. Contract manufacturers in Mumbai and São Paulo exhibit acute price sensitivity, whereas Hamburg and Los Angeles premium skincare brands tolerate premium positioning for blockchain-verified natural colorants.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg chemical terminals elevates inbound logistics costs for alumina substrate and botanical raw materials entering German lake pigment facilities. Supply concentrates in Germany, India, and China, with Ludwigshafen and Leverkusen chemical parks feeding 60 percent of EU-certified lake pigments. The chain draws from naphthalene, aniline, and alumina hydrate inputs. Single-source vulnerability during ECHA compliance audits threatens European cosmetics manufacturers. Distribution runs through direct technical sales for large accounts and e-commerce platforms for mid-size formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense as biotechnology-derived carotenoids and anthocyanins from microbial fermentation displace agricultural extraction for premium skincare lines.
For Market Incumbents: Compound captive petrochemical supply positions with fermentation platform licensing to neutralize Sensient Cosmetic Technologies' biotechnology threat. Secure backward integration into supercritical CO2 extraction equipment for Southeast Asian halal certification compliance. Capacity addition in Maharashtra under India's PLI scheme defends margin position against Chinese feedstock volatility. For New Entrants and Emerging Players: Differentiate on blockchain-verified supply chain transparency for German and US premium skincare brands demanding ingredient storytelling. Target Brazil's ANVISA fast-track pathway for botanical colorant additives before incumbents establish local analytical laboratories. Cloud-based shade matching platforms offer a direct go-to-market angle to bypass distributor markups in mid-size cosmetics segments. For Investors and Strategic Acquirers: Fermentation-based natural dye specialists with commercial-scale microbial carotenoid production represent the priority acquisition archetype. Long-term viability hinges on biotechnology platforms achieving batch consistency that agricultural extraction cannot match. Watch for ECHA authorization tightening on legacy azo dyes as the inflection signal compressing synthetic dye valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | BASF SE's captive naphthalene and aniline supply insulates azo pigment margins from crude volatility. |
| Fermentation Platform Licensing | Microbial-derived carotenoids collapse agricultural supply chain dependency for premium natural colorants. |
| Supercritical CO2 Processing Investment | Malaysia and Indonesia halal mandates pull alcohol-free extraction capacity into Southeast Asia. |
| Blockchain Supply Chain Verification | Third-party platforms displace certificate-of-analysis documentation for German clean-label procurement. |
| Direct-to-Brand Digital Platform Launch | Cloud-based shade matching bypasses distributor markups for mid-size Indian and US formulators. |
Research Methodology
Initial hypotheses were tested against primary input from cosmetic formulation chemists, regulatory affairs directors at personal care conglomerates, botanical extraction facility managers, and specialty dye procurement leads at contract manufacturers, then refined through secondary validation against FDA 21 CFR filings, ECHA REACH dossiers, Indian customs trade data, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up demand modeling across product chemistry tiers triangulated with top-down market sizing from petrochemical feedstock consumption patterns.
Variance decomposition across natural colorants, synthetic dyes, inorganic pigments, and lake complexes isolates growth contribution by chemistry type over the projection horizon. Segmentation dimensions modeled include product chemistry, application category, end-user scale, and distribution channel structure. CAGRs were derived from elasticity-adjusted volume projections. Forecast inputs incorporated ECHA authorization timelines and FDA color batch certification lead times specific to cosmetic dye regulatory pathways.
Decision-makers should treat outputs as directional under assumptions of stable REACH and FDA regulatory frameworks; material divergence in authorization thresholds or listing expansions would warrant model refresh. Practitioners should keep alternative scenarios live as biotechnology fermentation scale-up rates and European import concentration risks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Inorganic Pigments Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Azo Pigments Market
Dyes and Pigments
Basic Violet 10 Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Asia-Pacific Feed Pigments Market
Dyes and Pigments
Laser Sensitive Pigments Market
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Cadmium Pigments Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market