
 Composite Market | 2026-2036
Composite Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Market Intelligence
Aerospace-grade prepreg specification is unwinding the market's reliance on lower-performance wet layup materials. This shift favors suppliers with deep qualification and process control expertise. Hexcel Corporation leverages its long-standing relationships with airframers to supply advanced carbon fiber prepregs. Toray Industries sustains its market position through large-scale production of high-tensile strength carbon fiber, while Solvay differentiates through its portfolio of high-performance thermoplastic composites.
A composite is a material engineered from a matrix, like a polymer resin, and a reinforcement, such as carbon or glass fibers. Its primary purpose is to create components with a high strength-to-weight ratio for demanding industrial uses. Fiber Reinforced Polymers represent the largest product category by volume. While the aerospace end-user segment generates significant value, automotive OEMs are driving growth through the adoption of composites for vehicle lightweighting.
Material selection in aerospace is governed by stringent certification processes from bodies like the FAA in the United States and EASA in Europe. Concurrently, chemical regulations including the EU's REACH framework influence the formulation of resins and additives. Stakeholders must now prioritize the development of scalable and cost-effective end-of-life recycling solutions for composite structures to address sustainability concerns.
Market Dynamics
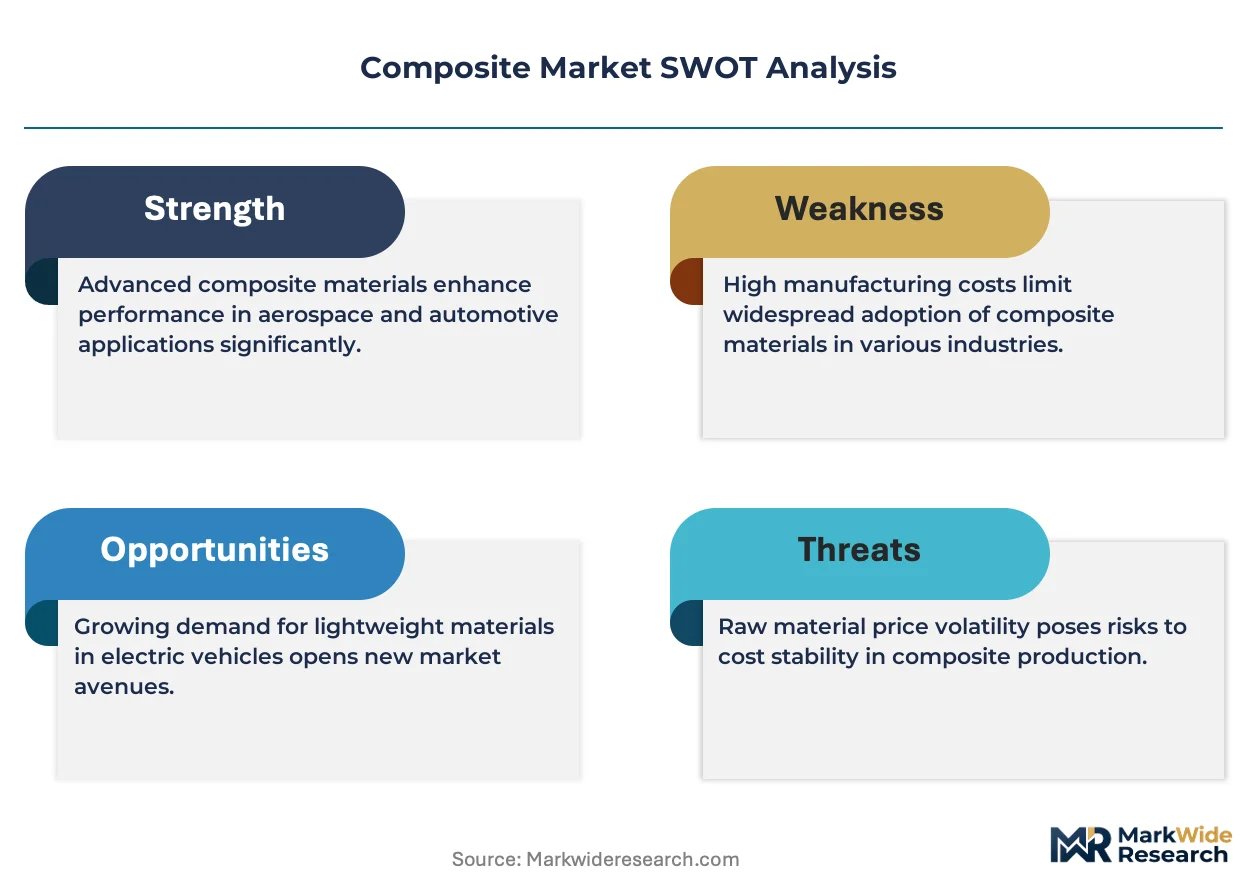
The composite market's evolution is defined by the dual pressures of performance-driven aerospace qualification and cost-driven automotive industrialization. This creates a bifurcation where high-margin, long-cycle prepregs for aviation coexist with emerging high-volume, rapid-cycle thermoplastic technologies for mass-market vehicles.
Growth Catalysts
- Automated Manufacturing:Innovations in automated fiber placement (AFP) and tape laying (ATL) reduce labor costs and improve part consistency, making composites more viable for series production in aerospace and industrial applications.
- Renewable Energy Mandates:Government targets for wind energy capacity in countries like Germany and China directly stimulate demand for high-performance glass and carbon fiber composites for manufacturing longer, more efficient turbine blades.
- Vehicle Lightweighting Regulations:Fuel economy and emissions standards, such as the US CAFE standards and EU CO2 emission targets, compel automotive OEMs to adopt lightweight composite materials to reduce overall vehicle mass.
Market Restraints
- High Input Costs:The price of precursor materials, particularly aerospace-grade carbon fiber, remains a significant barrier to wider adoption in cost-sensitive industries compared to traditional metals like aluminum and steel.
- Recycling Complexity:A lack of scalable, cost-effective recycling infrastructure for end-of-life thermoset composites creates sustainability challenges and potential long-term liability, hindering circular economy goals.
- Stringent Certification Cycles:The extensive and costly qualification processes mandated by bodies like the FAA in the US and EASA in Europe for new aerospace materials and components slow the pace of innovation adoption.
Strategic Opportunities
- Hydrogen Economy Infrastructure:The build-out of hydrogen fuel systems creates an opportunity for carbon fiber composites in Type IV and Type V high-pressure storage tanks for fuel cell electric vehicles (FCEVs) and ground storage.
- Thermoplastic Composites:The development of recyclable thermoplastic composites and associated automated processing techniques like overmolding offers a path to penetrate high-volume automotive applications with fast cycle times.
- Industrial Modernization in India:India's focus on domestic manufacturing through initiatives like the PLI scheme presents an opportunity for composites in defense, rail, and corrosion-resistant industrial equipment.
Industry Challenges
- Specialized Skills Gap:A shortage of technicians and engineers proficient in composite design, finite element analysis (FEA), and the operation of automated manufacturing systems constrains production scaling.
- Capital-Intensive Automation:The significant upfront investment required for automated production equipment, such as large-scale AFP machines or high-pressure RTM presses, poses a barrier for smaller manufacturers.
- Material Standardization Gaps:A lack of universally accepted standards for composite material data and testing protocols complicates supply chain interoperability and part qualification across different industrial sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Market |
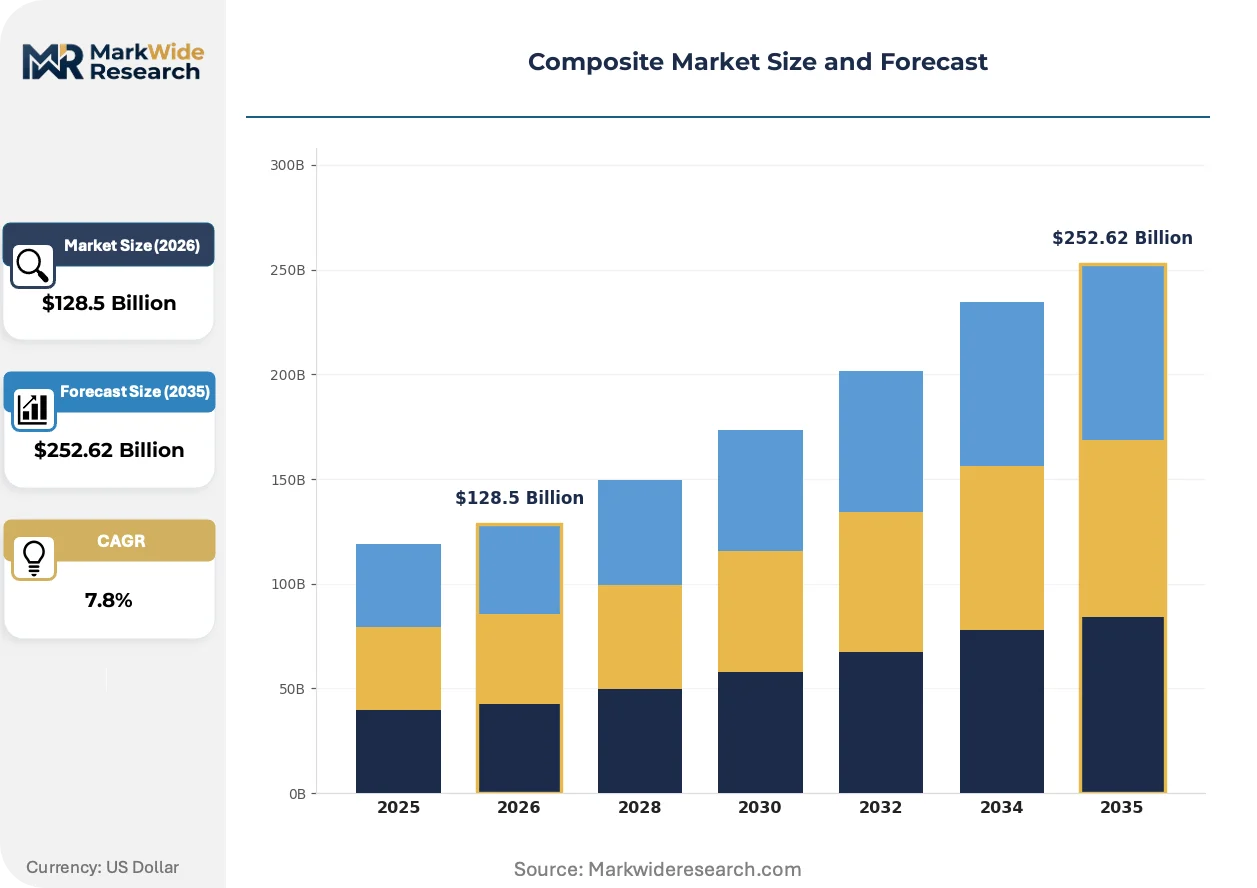
| Market Size in 2026 | $128.5 Billion |
| Market Size in 2035 | $252.62 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Reinforced Polymer, Wood Plastic Composite, Ceramic Matrix Composite, Metal Matrix Composite End User: Aerospace, Automotive OEMs, Construction, Marine Technology: Hand Layup, Pultrusion, Filament Winding, Injection Molding Application: Wind Energy, Sporting Goods, Consumer Electronics, Medical Devices |
| Companies Covered | Toray Industries, Hexcel Corporation, Solvay, SGL Carbon, Mitsubishi Chemical Group, Teijin Limited, Owens Corning, Gurit Holding, Koninklijke Ten Cate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Market Strategic Shifts & Innovations
A fundamental shift toward industrialization is underway, prioritizing process control, material qualification, and automation over traditional hands-on fabrication methods. This evolution favors suppliers who can deliver validated material systems and integrated manufacturing solutions, moving the basis of competition from raw material supply to certified component delivery.
Continuous fiber 3D printing enables the fabrication of complex composite parts with optimized fiber paths without the need for expensive molds. Aerospace and medical device firms are adopting the technology for rapid prototyping, custom tooling, and production of non-structural components. This additive approach is fragmenting the conventional tooling supply chain by allowing for decentralized, on-demand manufacturing of highly customized parts.
European Union chemical regulations, particularly REACH, are forcing a reformulation of composite resin systems. The framework's scrutiny of substances like certain epoxy hardeners, catalysts, and styrene in polyester resins compels chemical suppliers to invest in developing and qualifying safer alternatives. The marine and construction sectors are most impacted, accelerating a transition toward low-VOC and styrene-free resin formulations.
Buyer specifications are becoming increasingly sophisticated, especially in the aerospace and automotive sectors. OEMs are moving away from purchasing individual fibers and resins, instead demanding pre-qualified, fully characterized material systems from a single source to simplify their own certification and quality control processes. This preference is most pronounced in North America and Europe, where airframers and premium automakers seek to de-risk their supply chains.
Composite Market Segmentation
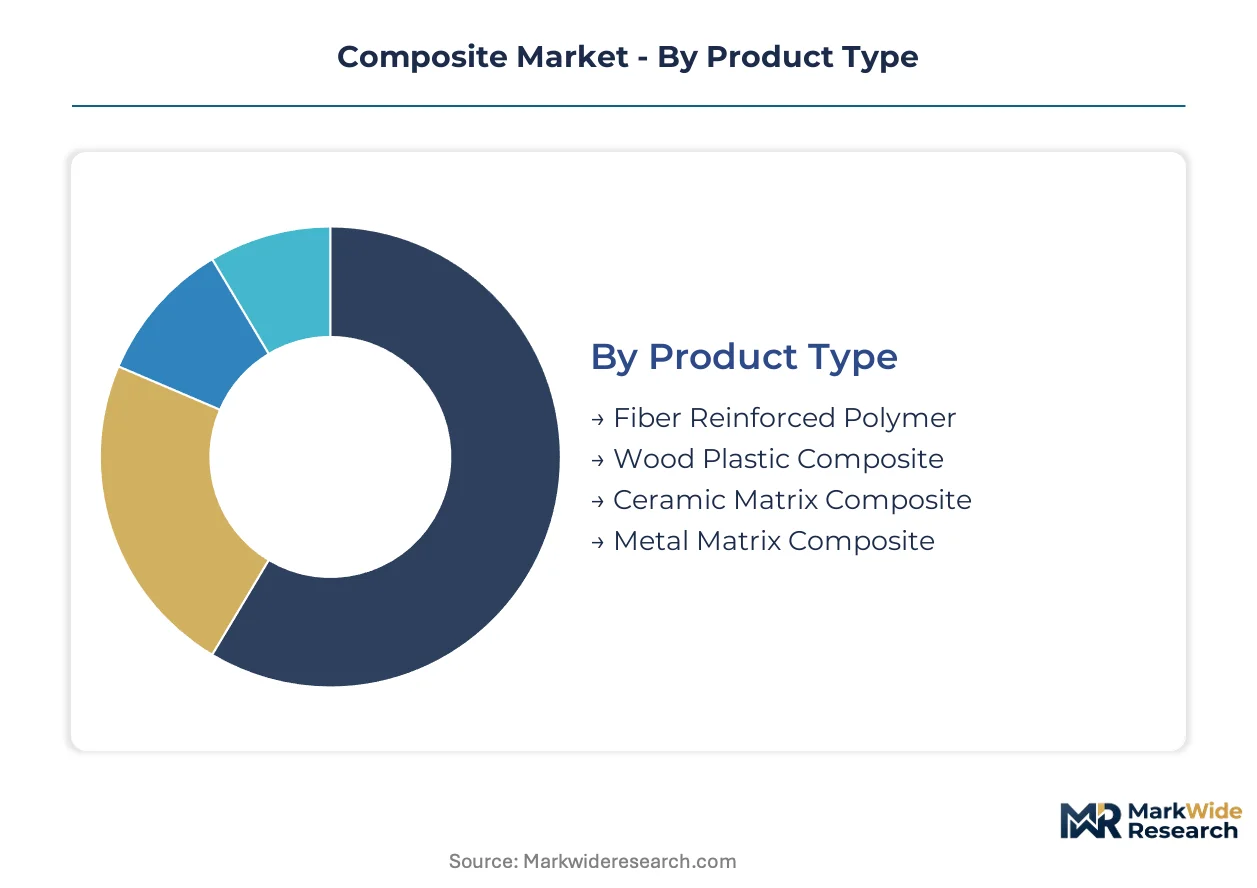
The Composite Market's segmentation reflects the diverse material science and engineering requirements across its applications. Understanding these distinct categories provides clarity on the varying performance demands, processing complexities, and regulatory compliance impacting different composite product types and end-user industries.
Product Type:
The regulatory landscape profoundly influences material selection within the composite product types, particularly concerning performance standards and chemical compliance.
- Fiber Reinforced Polymer:These composites combine a polymer matrix, such as epoxy or polyester resin, with high-strength fibers like carbon or glass, offering exceptional strength-to-weight ratios. Demand concentrates in aerospace for structural components and in renewable energy for large wind turbine blades, driven by stringent performance specifications from bodies like the FAA.
- Wood Plastic Composite:Blending wood fibers or flour with thermoplastics, these materials provide enhanced durability and moisture resistance compared to traditional wood. Automotive OEMs use them for interior panels and trim, seeking cost-effective lightweighting solutions that meet specific flammability standards.
- Ceramic Matrix Composite:Engineered from ceramic fibers embedded in a ceramic matrix, these materials withstand extreme temperatures and harsh chemical environments, making them ideal for high-performance applications. Aerospace and defense sectors drive demand for jet engine components and missile nose cones, where thermal stability is paramount.
- Metal Matrix Composite:These materials integrate high-strength fibers or particles into a metallic matrix, delivering superior stiffness and wear resistance. Automotive and industrial machinery applications utilize them for brake components and engine parts, demanding high thermal conductivity and strength.
Established volume favors Fiber Reinforced Polymer; emerging adoption favors Ceramic Matrix Composite.
End User:
Market demand dictates the scale and specification requirements across various end-user segments.
- Aerospace:This sector requires composites with unparalleled strength, stiffness, and fatigue resistance for aircraft structures, wings, and fuselage components, crucial for fuel efficiency. Airframers like Airbus and Boeing drive demand for advanced carbon fiber prepregs, with materials undergoing rigorous certification processes by EASA and the FAA.
- Automotive OEMs:Original Equipment Manufacturers integrate composites into vehicle bodies, chassis, and interior components to reduce overall weight, directly impacting fuel economy and emissions. Regulations like the US CAFE standards compel automakers to adopt lightweight materials for mass production, favoring rapid-cycle thermoplastic composites.
- Construction:Composites offer lightweight, corrosion-resistant, and high-strength solutions for infrastructure projects, including bridge decks, rebar, and architectural panels. Durability and long-term performance are key drivers in this segment.
- Marine:The marine industry utilizes composites for boat hulls, decks, and superstructures due to their corrosion resistance, design flexibility, and reduced weight. Performance in saltwater environments is a critical selection criterion.
Aerospace sets the performance benchmark, while Automotive OEMs are driving significant volume expansion.
Technology:
Manufacturing efficiency and part complexity drive the selection of composite processing technologies.
- Hand Layup:This traditional, labor-intensive method involves manually applying resin to fiber layers in a mold, suitable for low-volume production and complex geometries. Small-scale marine craft and custom prototypes frequently utilize hand layup due to its low tooling costs.
- Pultrusion:A continuous process where fibers are pulled through a resin bath and then a heated die to create constant cross-section profiles, ideal for high-volume structural elements. Construction and industrial applications demand pultruded profiles for their consistent properties and cost-effectiveness.
- Filament Winding:Fibers impregnated with resin are wound onto a rotating mandrel, creating hollow, high-strength structures like pipes and pressure vessels. The hydrogen economy's demand for Type IV and Type V storage tanks for FCEVs relies heavily on filament winding technology.
- Injection Molding:This high-volume, rapid-cycle process involves injecting molten thermoplastic composite into a mold cavity, suitable for complex, intricate parts. Automotive interior components and consumer electronics frequently employ injection molding for efficiency and design freedom.
Traditional Hand Layup offers versatility, but automated Injection Molding and Pultrusion are gaining share fastest for series production.
Application:
Specific functional requirements and structural demands define composite material utility across diverse applications.
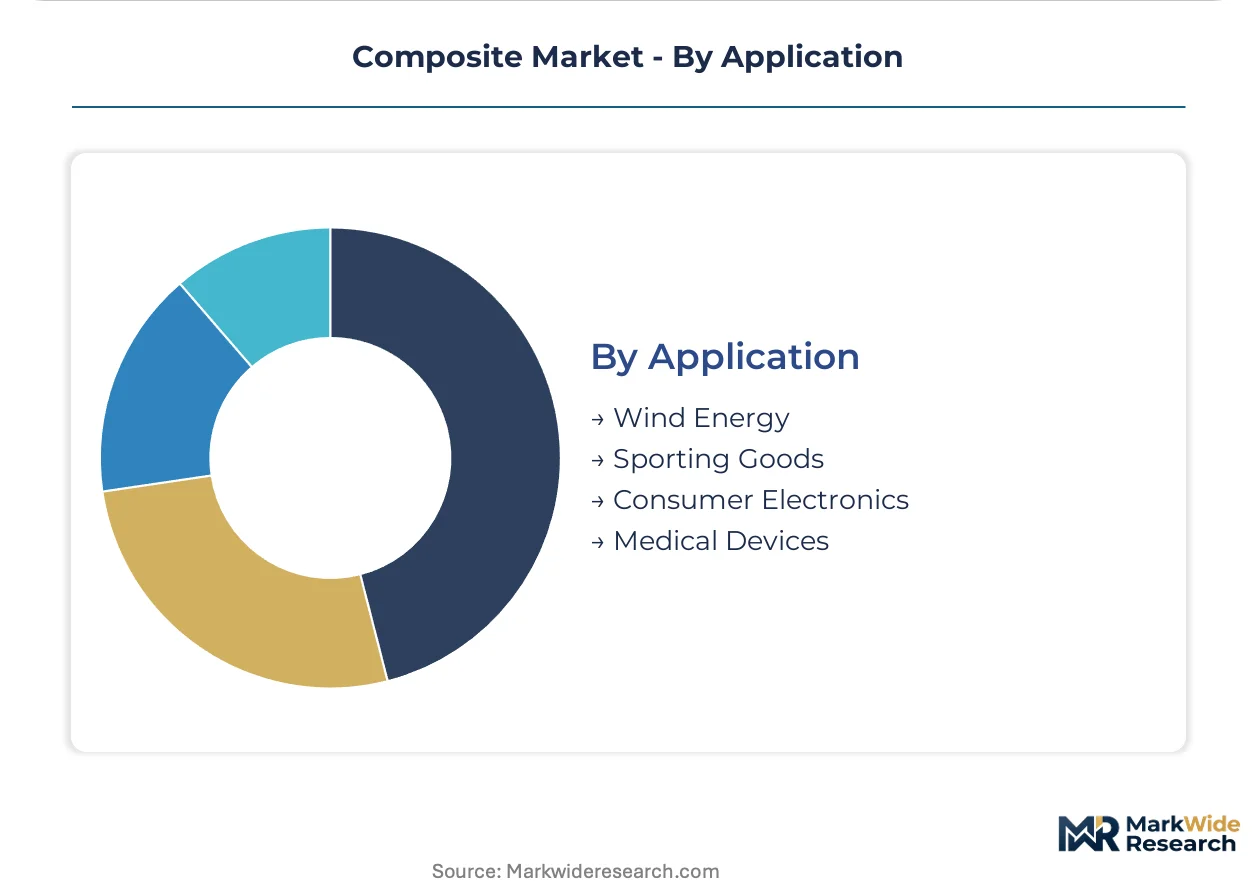
- Wind Energy:Composites are essential for manufacturing long, aerodynamic wind turbine blades, which require high stiffness, fatigue resistance, and lightweight properties for optimal energy capture. Government renewable energy mandates in Germany and China directly stimulate demand for glass and carbon fiber composites.
- Sporting Goods:High-performance composites enhance athletic equipment like tennis rackets, golf clubs, and bicycles, providing lightweight strength and improved performance characteristics. Consumer demand for competitive advantage drives material innovation in this segment.
- Consumer Electronics:Composites offer lightweight, durable enclosures for devices like laptops, smartphones, and drones, enabling thinner designs and improved impact resistance. The need for robust yet aesthetically pleasing materials influences selection.
- Medical Devices:Biocompatible and radiolucent composites are used in prosthetics, surgical instruments, and imaging equipment, offering strength and transparency to X-rays. Precision and material inertness are crucial for patient safety and diagnostic accuracy.
Wind Energy applications command large-scale material volumes, while Medical Devices emphasize precision and biocompatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across composite market applications, with aerospace buyers exhibiting lower price sensitivity for mission-critical components, while automotive OEMs prioritize cost-effectiveness for mass production. This bifurcation shapes regional investment patterns and material development priorities across key geographies. Each region demonstrates distinct drivers and regulatory influences on composite material adoption.
United States
Aerospace and defense sectors drive substantial demand for advanced composites in the United States, particularly for new aircraft programs and military applications. The FAA's stringent certification processes for airworthiness ensure high-performance material specifications. Major aerospace clusters in Seattle, Wichita, and Southern California concentrate composite manufacturing and research activities.
Germany
Germany's renewable energy mandates and automotive industry demand high-performance composites. Government targets for wind energy capacity directly stimulate demand for advanced glass and carbon fiber composites for turbine blades. The EU's REACH framework influences resin formulations, while automotive hubs like Stuttgart and Munich adopt composites for vehicle lightweighting.
China
China's rapid industrialization and ambitious renewable energy goals create immense demand for composites in wind energy and infrastructure projects. The country's dual carbon goals accelerate the adoption of lightweight materials across various sectors. Manufacturing centers in Jiangsu and Guangdong provinces are expanding their capabilities in composite production and application.
India
India's focus on domestic manufacturing through initiatives like the PLI scheme presents significant opportunities for composites in defense, rail, and industrial equipment. Infrastructure development projects drive demand for corrosion-resistant and high-strength composite solutions. Industrial clusters around Bengaluru and Pune are emerging as centers for composite fabrication and engineering.
France
France maintains a strong position in the aerospace industry, driving consistent demand for high-performance prepregs and structural composites. EASA regulations govern material qualification for airframe components and engine parts manufactured in the country. Toulouse, a major aerospace hub, anchors significant composite research and development activities.
Composite Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the composite market, creating a tiered competitive structure. This market features both highly specialized material developers and large-scale commodity producers. Strategic partnerships and targeted M&A activities are common competitive moves, alongside continuous investment in process automation.
On the advanced materials vector, Toray Industries and Hexcel Corporation exemplify firms with deep expertise in high-performance carbon fiber and aerospace-grade prepregs. Solvay occupies a position among innovators in high-performance thermoplastic composites, aligning with emerging automotive requirements. These companies anchor the market's premium segment by focusing on material qualification and process control.
| Leading Market Players |
|---|
| Toray Industries |
| Hexcel Corporation |
| Solvay |
| SGL Carbon |
| Mitsubishi Chemical Group |
| Teijin Limited |
| Owens Corning |
| Gurit Holding |
| Koninklijke Ten Cate |
| Others |
Cost & Logistics Intelligence
Large-scale production capacity for precursor materials like carbon fiber dictates supply concentration and influences price floors for composite raw materials. This scale-driven dynamic affects pricing across the value chain, from material suppliers to component manufacturers.
Pricing Analysis
FAA certification dictates the pricing tier structure for aerospace-grade prepregs, driving a contract-based long-term offtake model. Price differentiation stems from the stringent certification level required by bodies like EASA and the high customization level for specific airframe programs. Cost compression in high-volume automotive composites is intensifying due to competition from traditional metals. Automotive OEMs are most price-sensitive, while aerospace buyers exhibit lower price sensitivity for mission-critical components.
Supply Chain Analysis
The limited global supply of aerospace-grade carbon fiber precursor underwrites the high cost structure of advanced composites. Geographic supply concentration primarily rests in Japan, the USA, and Germany for high-performance fibers. The market draws from critical raw materials such as polyacrylonitrile (PAN) precursor and specialized epoxy resins. Single-source vulnerability for high-performance fibers presents a structural supply chain risk. Downstream distribution sources from direct sales and long-term contracts between material suppliers and Tier 1 component manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Composite Market presents a significant service-attach opportunity, with advanced engineering and simulation services expanding faster than core material sales. This layer offers recurring revenue streams for specialized suppliers.
For Market Incumbents: Shield existing market share by investing in next-generation automated manufacturing capabilities like AFP and ATL. This mitigates the threat from lower-cost material alternatives and emerging high-volume processing techniques in automotive. Deepen vertical integration into pre-qualified material systems to control quality and supply for aerospace clients.
For New Entrants and Emerging Players: Specialized design and simulation services for complex composite structures represent a service-layer gap where incumbents under-serve. New entrants can target the industrial modernization segment in India with cost-effective, localized composite solutions. A compelling go-to-market angle involves offering integrated material and processing packages for niche applications.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists in recyclable thermoplastic composites and advanced automation solution providers. Long-term viability rests on addressing end-of-life recycling challenges and achieving cost parity with traditional materials in high-volume applications. The signal to watch is the accelerated adoption of thermoplastic composites in mainstream automotive platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Thermoplastics | Supports high-volume automotive demand and reduces reliance on traditional thermosets. |
| R&D in Recycling Technologies | Addresses sustainability concerns and unlocks circular economy opportunities for composites. |
| Automated Fiber Placement Integration | Improves manufacturing efficiency and consistency for aerospace and industrial components. |
| Strategic Partnerships with OEMs | Secures long-term supply contracts and co-develops application-specific material systems. |
| Geographic Expansion in India | Capitalizes on industrial modernization and infrastructure development initiatives. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, procurement managers, material scientists, and aerospace engineers, and refined through iterative analysis. This involved combining in-depth interviews with validation from secondary sources like company annual reports, government publications (e.g., FAA, EASA, REACH documents), and industry association reports. A bottom-up approach to market sizing was triangulated with top-down validation.
Variance decomposition isolated the impact of key drivers, including aerospace build rates, renewable energy mandates, and vehicle lightweighting regulations, on composite demand across the analysis window. The analytical framework modeled market evolution by product type, end-user, technology, application, and regional regulatory frameworks. CAGRs were derived from historical trends and projected future growth vectors, incorporating inputs like new aircraft program schedules and automotive production forecasts.
Underlying assumptions cover material cost stability and regulatory continuity, with deviation risk concentrated in geopolitical shifts affecting supply chains or unforeseen technological breakthroughs. Forecasts reflect these assumptions, acknowledging potential impacts from raw material price volatility or stricter environmental mandates. Practitioners should keep alternative scenarios live as global economic conditions and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
PCR Laminates Market
Composite Materials
Composite Adhesives Market
Composite Materials
Structural Core Materials Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Carbon Composites Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Case Material Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
United States Marine Composites Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Global Wind Turbine Composites Material Market