
 United States Copper Pipes and Tubes Market | 2026-2036
United States Copper Pipes and Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
United States Copper Pipes and Tubes Market Intelligence
Wholesale distribution is fragmenting across the United States copper pipes and tubes market as regional buying cooperatives gain share from legacy two-step distributors. Mueller Industries leverages captive brass and copper alloy production to sustain margin control through upstream integration. Wieland Group anchors its North American position through continuous casting technology leadership and mill-direct relationships with mechanical contractors. Cerro Flow Products competes on geographic proximity, operating redraw facilities in the Southwest to reduce freight exposure for construction customers.
Copper pipes and tubes are seamless or welded hollow cylindrical products manufactured from UNS C12200 or C12000 alloy, typically ranging from 1/4 inch to 1 inch nominal diameter, designed to convey fluids, gases, or electrical current across pressurized and non-pressurized systems. Plumbing applications dominate volume demand yet face structural pressure from PEX substitution in residential rough-in, while HVAC specification of copper refrigerant lines holds firmer due to thermal conductivity requirements and EPA Section 608 leak-rate standards. Industrial manufacturing end users concentrate margin pools through long-term alloy contracts and just-in-time delivery terms that favor domestic melt-and-cast producers with integrated logistics.
EPA Lead and Copper Rule revisions and NSF/ANSI 61 drinking water system component standards shape product chemistry and certification requirements for manufacturers serving potable water segments. OSHA workplace exposure limits for copper dust and fume govern foundry and fabrication facility operations, particularly in redraw and annealing processes. NIBCO and Cambridge-Lee Industries navigate this regulatory matrix through in-house metallurgical testing and third-party laboratory partnerships. Stakeholders must monitor alloy surcharge volatility and state-level plumbing code amendments that could accelerate or retard copper's competitive position against cross-linked polyethylene alternatives.
Market Dynamics
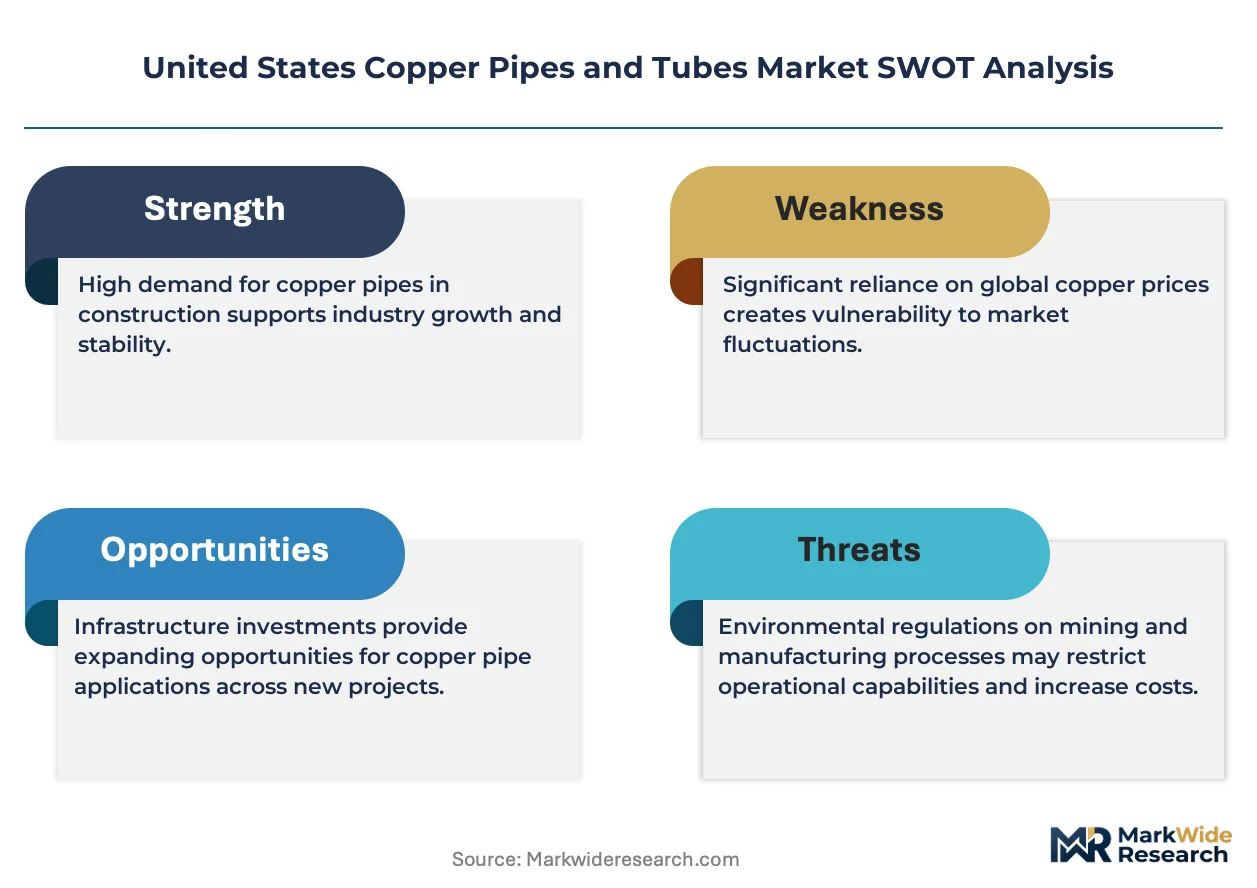
EPA Lead and Copper Rule revisions are compressing specification timelines for potable water infrastructure while Sun Belt housing starts accelerate contractor demand for compliant copper alternatives to polymer piping systems.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Tightening compliance requirements for potable water infrastructure are mandating material upgrades that favor copper's established NSF/ANSI 61 certification profile over uncertified polymer alternatives in municipal retrofit programs.
- Sun Belt housing construction:Residential plumbing contractors across Florida, Texas, and Arizona are expanding copper specification for new rough-in work as building codes in these states maintain stricter fire-resistance standards than national baselines.
- HVAC refrigerant line demand:Thermal conductivity requirements and EPA Section 608 leak-rate standards are preserving copper specification for commercial and residential air-conditioning installations despite PEX encroachment elsewhere.
Market Restraints
- Copper price volatility:London Metal Exchange copper pricing swings directly compress fabricator margins and destabilize long-term contract negotiations with mechanical contractors.
- PEX substitution in residential plumbing:Cross-linked polyethylene systems are capturing share in single-family rough-in applications due to lower material cost and faster installation labor requirements.
- Domestic melt capacity concentration:Limited number of integrated copper alloy producers with captive casting operations creates supply bottleneck risk during demand spikes in construction seasonality.
Strategic Opportunities
- Commercial HVAC retrofit wave:Aging R-22 system replacements across the Southeast and Southwest are generating demand for copper refrigerant line sets that meet updated efficiency standards.
- Regional buying cooperative expansion:Independent plumbing wholesalers are consolidating procurement through member-owned cooperatives, creating direct mill-access channels that bypass legacy two-step distribution markups.
- NSF/ANSI 61 certification premium:Third-party drinking water component validation is enabling price differentiation for compliant copper tube manufacturers serving municipal and healthcare specification segments.
Industry Challenges
- Skilled installer shortage:Aging plumber workforce and declining apprenticeship enrollment are extending project timelines and raising labor cost premiums for copper soldering work relative to push-fit polymer systems.
- Alloy chemistry compliance:NSF/ANSI 61 lead-content thresholds require continuous metallurgical testing and third-party laboratory partnerships that add fixed cost burden for redraw and fabrication facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Copper Pipes and Tubes Market |
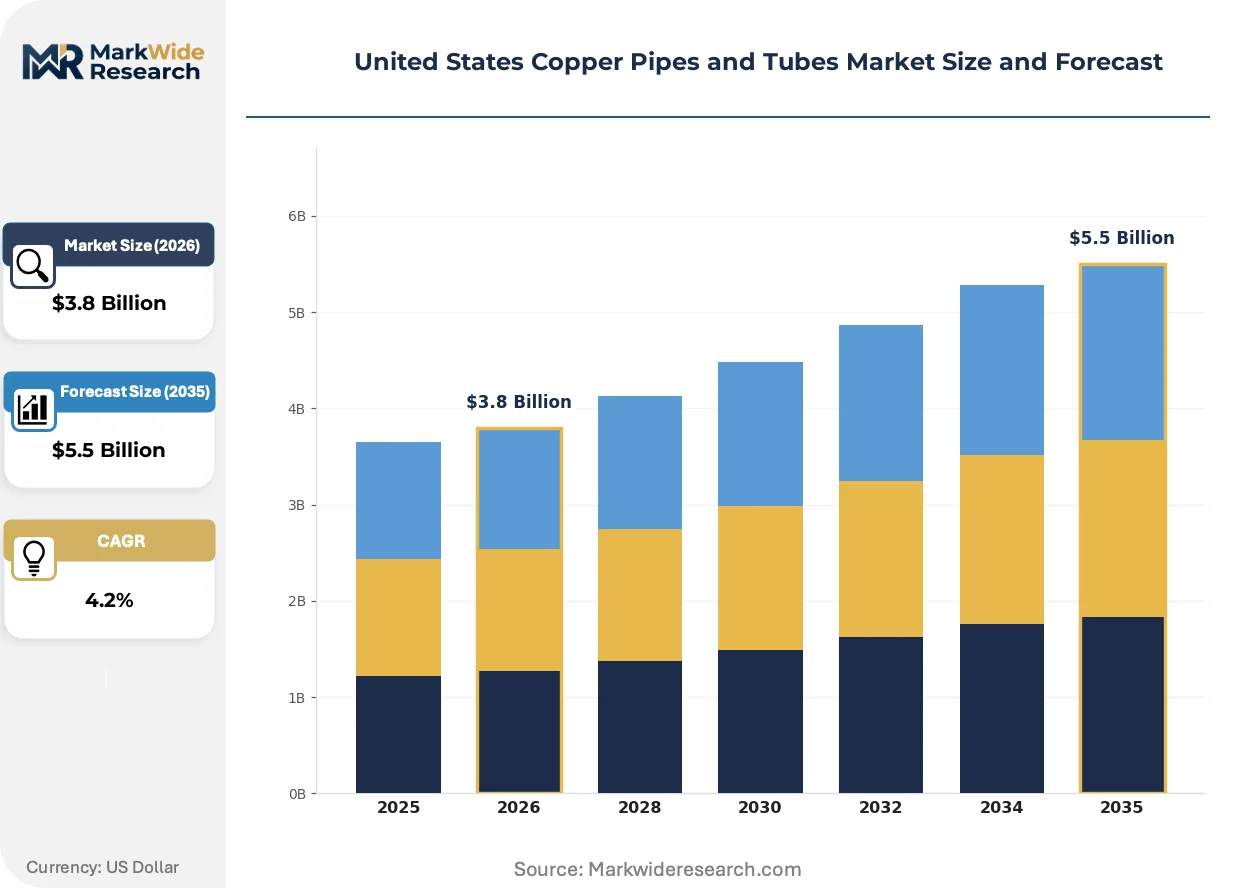
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Pipes, Square Tubes, Rectangular Tubes, Specialty Shapes Application: Plumbing, HVAC, Electrical, Industrial Manufacturing End User: Construction, Automotive, Aerospace, Electronics Size: 1/4 inch, 1/2 inch, 3/4 inch, 1 inch |
| Companies Covered | Cambridge-Lee Industries, Golden Dragon Precise Copper Tube Group, Mueller Industries, Luvata, Kobe Steel, Wieland Group, NIBCO, Lawton Tubes, Cerro Flow Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Copper Pipes and Tubes Market Strategic Shifts & Innovations
Continuous casting technology and automated redraw processes are compressing production economics while regulatory chemistry standards and distribution channel restructuring reshape competitive positioning across the value chain.
Continuous casting technology is migrating from specialty alloy production into standard plumbing tube manufacturing. Wieland Group and integrated domestic producers are deploying this process to reduce solidification defects and improve dimensional consistency. Mechanical contractors in high-volume Sun Belt markets are specifying continuous-cast product for large-scale multifamily projects where lot uniformity reduces field fitting waste.
EPA Lead and Copper Rule revisions are mandating lower lead-content thresholds in potable water system components. Manufacturers serving municipal and residential plumbing segments must maintain third-party NSF/ANSI 61 certification and in-house metallurgical testing protocols. NIBCO and redraw specialists with established laboratory partnerships are capturing specification share in healthcare and educational construction verticals where compliance documentation is mandatory.
Buying cooperatives are consolidating procurement for independent plumbing wholesalers across the Southwest and Southeast. These member-owned entities negotiate direct mill contracts that compress delivered cost versus legacy two-step distribution through national distributors. The cooperative model is most visible in Texas and Arizona markets where contractor density supports volume aggregation and regional freight optimization.
United States Copper Pipes and Tubes Market Segmentation
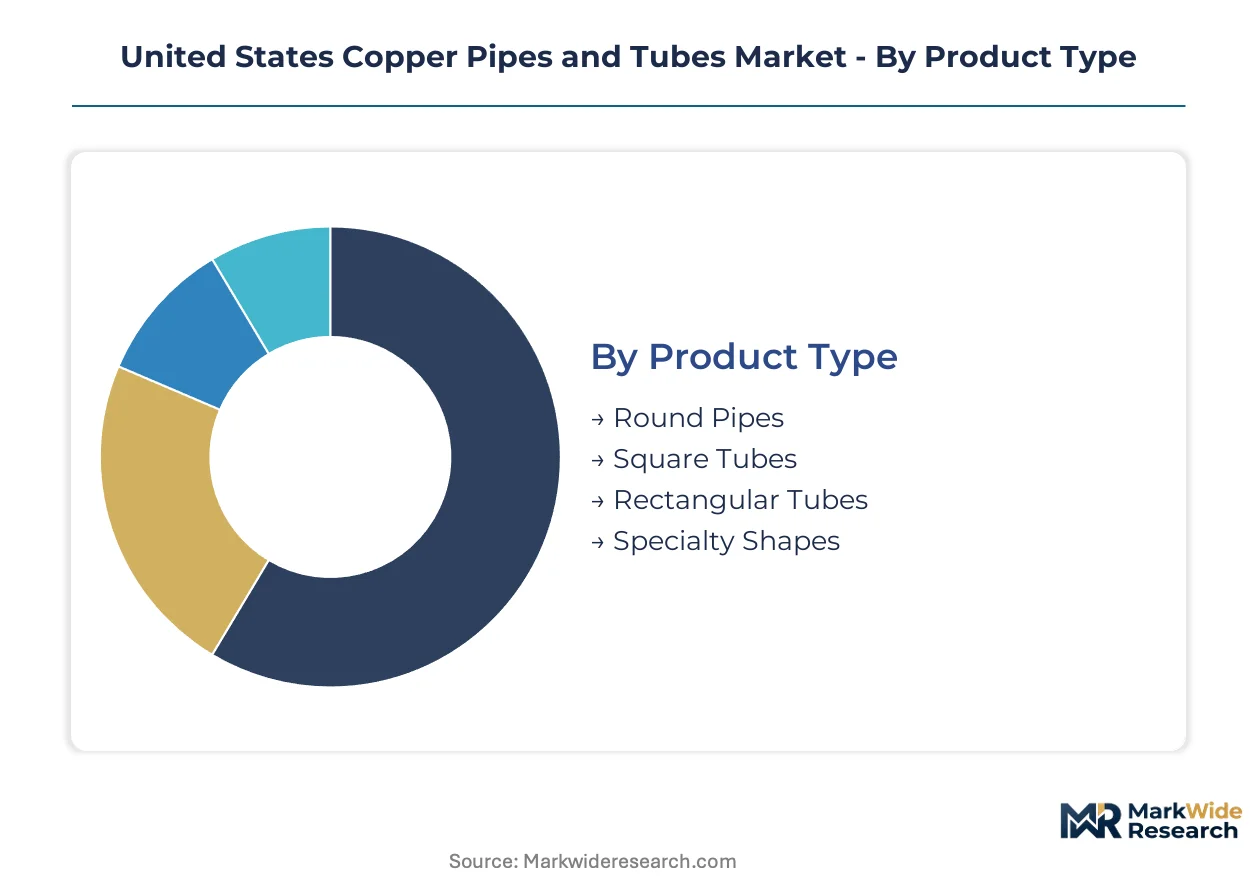
Segmentation in the United States copper pipes and tubes market reveals distinct procurement rhythms across product geometries and end-use specifications. Contractors and distributors navigate divergent inventory cycles depending on whether demand originates from standardized plumbing rough-in or custom industrial fabrication.
Product Type:
Round pipes turn inventory fastest through wholesale distribution channels, while specialty shapes sit longest due to custom die requirements and project-specific ordering patterns.
- Round Pipes:Seamless and welded hollow cylinders manufactured from UNS C12200 or C12000 alloy, typically ranging from 1/4 inch to 1 inch nominal diameter. Residential plumbing contractors across Texas and Florida specify these for potable water distribution, driven by EPA Lead and Copper Rule compliance mandates that favor certified copper over polymer alternatives in municipal retrofit programs.
- Square Tubes:Four-sided hollow profiles with uniform wall thickness engineered for structural and architectural applications. Commercial construction projects in Arizona and Nevada specify these for exposed mechanical chases and decorative column cladding, constrained by longer lead times from domestic redraw facilities with limited square-die capacity.
- Rectangular Tubes:Elongated hollow profiles with asymmetric aspect ratios serving HVAC duct transitions and electrical conduit enclosures.
- Specialty Shapes:Custom-extruded or drawn profiles including oval, teardrop, and finned configurations for heat exchanger and aerospace applications.
Round pipes dominate installed base. Specialty shapes are where expansion concentrates.
Application:
Plumbing applications generate the highest volume throughput, yet HVAC commands tighter specification tolerances and longer contract horizons that stabilize fabricator margins.
- Plumbing:Potable water distribution and drainage systems in residential and commercial buildings. Sun Belt housing starts in Florida, Texas, and Arizona are expanding specification of copper rough-in systems as local building codes maintain stricter fire-resistance standards than national baselines, though PEX substitution pressure persists in cost-sensitive single-family segments.
- HVAC:Refrigerant line sets, condensate drains, and hydronic heating distribution networks. Thermal conductivity requirements combined with EPA Section 608 leak-rate standards are preserving copper specification for commercial and residential air-conditioning installations across the Southeast and Southwest.
- Electrical:Grounding conductors, bus bars, and transformer windings where conductivity and corrosion resistance are critical.
- Industrial Manufacturing:Process piping, heat exchanger tubing, and fluid transfer systems in chemical processing and food equipment.
Plumbing anchors volume demand. HVAC is climbing the fastest.
End User:
Construction procurement operates on seasonal cyclicality tied to housing starts and commercial project awards, while automotive and aerospace demand follows model-year and defense contract rhythms with opposite timing.
- Construction:Residential, commercial, and infrastructure building contractors specifying copper for plumbing, HVAC, and architectural applications. Regional buying cooperatives in Texas and Arizona are consolidating procurement for independent plumbing wholesalers, creating direct mill-access channels that bypass legacy two-step distribution markups.
- Automotive:Brake lines, fuel injection tubing, and thermal management systems where corrosion resistance and formability are essential.
- Aerospace:High-performance alloy tubing for fuel, hydraulic, and environmental control systems subject to stringent material certification requirements.
- Electronics:Heat sinks, connectors, and semiconductor packaging substrates leveraging copper's thermal and electrical properties.
Construction commands the largest share. Electronics is gaining share fastest.
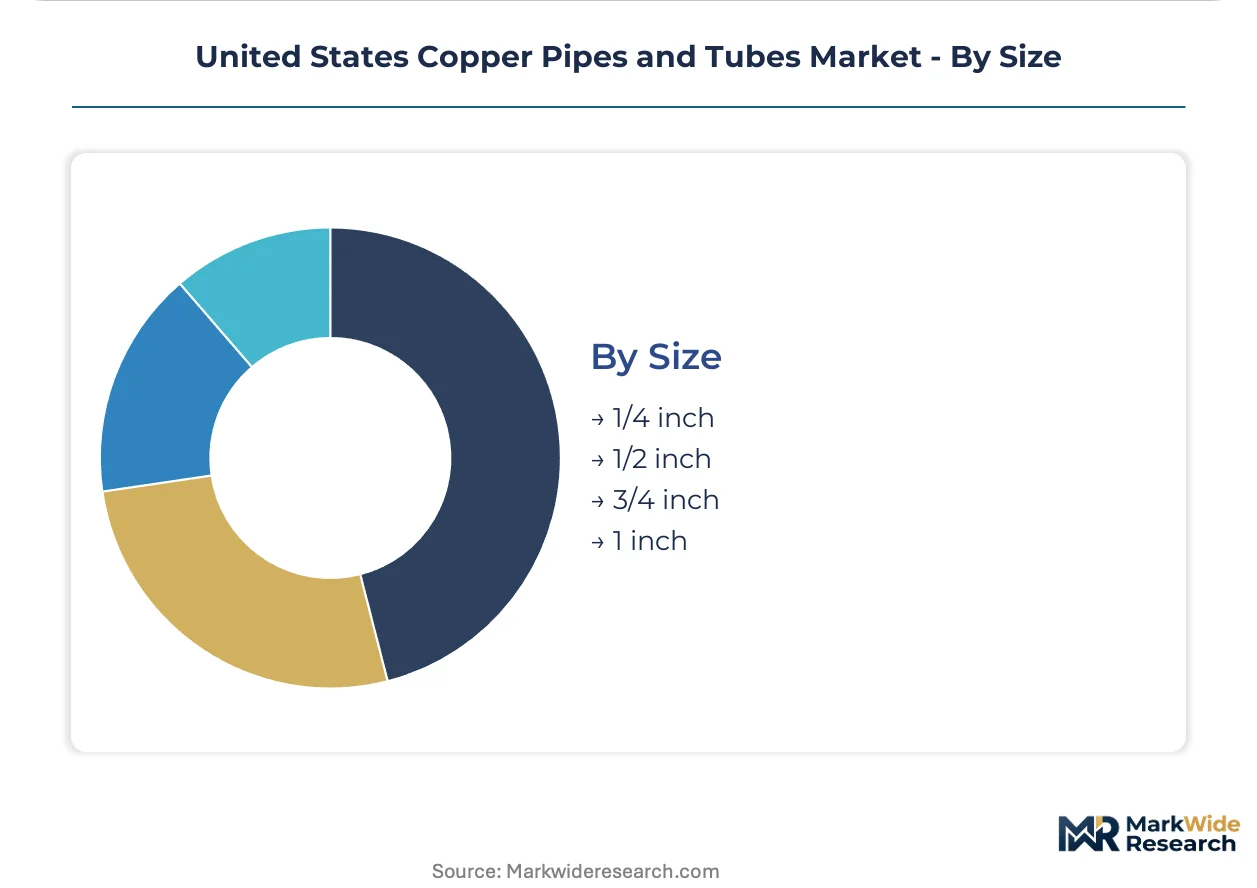
Size:
Mid-range diameters move through distribution most rapidly due to broad applicability across residential and light commercial systems, while the smallest and largest sizes serve narrower specification niches.
- 1/2 inch:Standard diameter for residential potable water distribution and residential HVAC refrigerant lines. Mechanical contractors in Sun Belt markets specify this diameter for multifamily rough-in work where lot uniformity reduces field fitting waste.
- 3/4 inch:Primary diameter for commercial plumbing mains and larger residential branch lines. Municipal retrofit programs across the Southwest are specifying this size for service line replacements under EPA Lead and Copper Rule revisions.
- 1/4 inch:Refrigerant line sets for residential air-conditioning systems and instrumentation tubing.
- 1 inch:Commercial plumbing risers, fire suppression systems, and industrial process piping.
1/2 inch holds the deepest installed base. 3/4 inch is where specification expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's deepwater access and rail intermodal terminals underpin copper tube distribution across the South Central United States, connecting Gulf Coast melt capacity to inland mechanical contractors.
Southwest
Arizona and Nevada construction markets drive specification of rectangular copper tubes for exposed HVAC chases and architectural cladding. Local building codes in Phoenix and Las Vegas mandate fire-resistant materials for high-rise mechanical systems. Redraw facilities in the Southwest reduce freight exposure for construction customers serving the Sun Belt retrofit wave.
Southeast
Florida housing starts and commercial HVAC replacements concentrate demand for half-inch and three-quarter-inch copper refrigerant lines. EPA Section 608 leak-rate standards preserve copper specification for R-22 system replacements across Georgia and the Carolinas. Miami-Dade and Atlanta metropolitan contractors specify continuous-cast product for multifamily projects requiring lot uniformity.
Texas
The state's independent plumbing wholesalers consolidate procurement through regional buying cooperatives that negotiate direct mill contracts. Texas building codes maintain stricter fire-resistance standards than national baselines, expanding copper rough-in specification for new residential construction. Houston and Dallas-Fort Worth mechanical contractors anchor volume demand for municipal service line replacements under EPA Lead and Copper Rule revisions.
West Coast
California's Title 24 energy efficiency standards and seismic building codes shape copper tube specification for commercial HVAC and hydronic heating systems. Los Angeles and San Francisco Bay Area construction markets prioritize NSF/ANSI 61 certified products for potable water infrastructure in healthcare and educational verticals. Pacific Northwest electronics manufacturers consume specialty copper shapes for thermal management substrates.
Midwest
Industrial manufacturing clusters in Ohio and Illinois sustain demand for process piping and heat exchanger tubing through long-term alloy contracts. Chicago and Detroit area automotive suppliers specify corrosion-resistant copper tubing for brake lines and fuel injection systems. Great Lakes logistics networks connect domestic melt-and-cast producers to just-in-time delivery contracts with heavy equipment manufacturers.
United States Copper Pipes and Tubes Market Key Industry Players
On the supply side, the industry is consolidating around integrated producers with captive casting operations and redraw specialists competing on geographic proximity. Two strategic archetypes dominate: vertically integrated alloy producers controlling upstream melt capacity, and regional fabricators leveraging mill-direct relationships with mechanical contractors. Competitive moves concentrate on backward integration into brass and copper alloy production, and cooperative procurement structures that bypass legacy distribution tiers.
Among domestic integrated producers, Mueller Industries and Cerro Flow Products exemplify the captive-supply archetype, while Wieland Group anchors the continuous-casting technology tier. These three occupy positions that reflect divergent paths to margin control—upstream integration versus process innovation versus regional logistics optimization.
| Leading Market Players |
|---|
| Cambridge-Lee Industries |
| Golden Dragon Precise Copper Tube Group |
| Mueller Industries |
| Luvata |
| Kobe Steel |
| Wieland Group |
| NIBCO |
| Lawton Tubes |
| Cerro Flow Products |
| Others |
Cost & Logistics Intelligence
East Tennessee's integrated copper alloy production cluster concentrates captive melt-and-cast capacity that feeds downstream pricing power to redraw specialists serving Sun Belt mechanical contractors. London Metal Exchange copper pricing volatility compresses fabricator margins and destabilizes long-term contract negotiations with municipal procurement officers.
Pricing Analysis
Volume-discount tiering structures separate NSF/ANSI 61 certified premium product from standard commercial-grade and uncertified economy alternatives. Price differentiation rests on certification grade and geographic delivery cost, with continuous-cast product commanding modest premiums for dimensional consistency. Cost compression in the economy tier intensifies as PEX substitution pressure forces copper fabricators to absorb alloy surcharge volatility. Residential plumbing contractors exhibit highest price sensitivity, while healthcare and educational construction verticals prioritize compliance documentation over unit economics.
Supply Chain Analysis
Supply-chain finance facilities from regional buying cooperatives extend payment terms to independent plumbing wholesalers, compressing cash conversion cycles. Domestic production draws from Arizona, Tennessee, and Illinois manufacturing clusters. Raw material dependencies center on copper cathode, zinc alloying agents, and phosphorus deoxidizers. Single-source vulnerability concentrates in continuous casting equipment suppliers. Distribution runs through mill-direct relationships with mechanical contractors and cooperative procurement channels bypassing legacy two-step markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Lead and Copper Rule revisions are accelerating specification turnover across potable water infrastructure, creating a regulatory inflection that favors certified copper alternatives over polymer systems in municipal retrofit programs.
For Market Incumbents: Build a certification moat by deepening NSF/ANSI 61 laboratory partnerships and in-house metallurgical testing protocols that emerging PEX suppliers cannot replicate. Secure backward integration into captive brass and copper alloy production to buffer London Metal Exchange volatility. Anchor capacity in Texas and Arizona distribution corridors where regional buying cooperatives aggregate contractor demand.
For New Entrants and Emerging Players: Establish a beachhead in commercial HVAC refrigerant line segments where thermal conductivity requirements and EPA Section 608 leak-rate standards preserve copper specification against polymer encroachment. Target Sun Belt municipal service line replacement programs under EPA compliance mandates. Lead with continuous-cast product uniformity and mill-direct freight optimization to displace legacy redraw specialists.
For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle play because aging R-22 system retirements and lead service line infrastructure obsolescence generate sustained demand visibility. Acquire redraw specialists with established laboratory partnerships and geographic proximity to Southwest construction markets. Monitor EPA enforcement intensity and state plumbing code amendments as inflection indicators for copper's competitive position against cross-linked polyethylene alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Production | Mueller Industries and Cerro Flow Products control captive melt capacity that buffers London Metal Exchange volatility. |
| NSF/ANSI 61 Certification Investment | NIBCO and Cambridge-Lee Industries capture healthcare and educational specification share through third-party laboratory partnerships. |
| Regional Buying Cooperative Expansion | Texas and Arizona member-owned entities negotiate direct mill contracts that compress delivered cost versus legacy distribution. |
| Continuous Casting Technology Deployment | Wieland Group reduces solidification defects and improves dimensional consistency for high-volume multifamily projects. |
| Southwest Redraw Facility Positioning | Cerro Flow Products operates redraw facilities that reduce freight exposure for construction customers serving Sun Belt retrofit demand. |
Research Approach
A standing panel of mechanical contractors, independent plumbing wholesalers, municipal procurement officers, and metallurgical laboratory directors provided ongoing calibration across the study period. Primary interviews with EPA regulatory affairs specialists and Sun Belt building code officials combined with secondary validation from SEC 10-K filings, American Copper Council production statistics, and customs trade data. Bottom-up volume estimates from distributor point-of-sale systems triangulated against top-down alloy consumption figures from domestic melt capacity reports.
Scenario-bracketing around EPA enforcement intensity and copper price volatility bands shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product geometry, application specification, end-user procurement rhythm, and regional building code stringency. CAGRs derived from regression analysis of housing starts, commercial HVAC replacement cycles, and municipal infrastructure award data. Alloy surcharge volatility and PEX substitution elasticity served as key forecast inputs.
Sensitivities concentrate around EPA Lead and Copper Rule implementation timelines and London Metal Exchange copper pricing deviation from baseline assumptions. Forecasts reflect documented assumptions regarding Sun Belt construction activity and continuous casting technology adoption curves. Macroeconomic contraction, regulatory delay, or breakthrough polymer thermal conductivity performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Europe PVC Pipes Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market