
 Pneumatic Fittings Market | 2026-2036
Pneumatic Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Fittings Market Analytics
Multi-source procurement for precision-machined brass and stainless steel bodies is pivoting toward regional foundry partnerships as OEMs reduce exposure to single-country supply. Festo leverages captive manufacturing in Europe and Asia to sustain component consistency across its valve-fitting systems. SMC Corporation anchors its position through deep distribution control in Japanese and Chinese automation markets. Parker Legris competes on polymer-to-metal hybrid expertise that extends its reach into food-grade and pharmaceutical cleanroom environments.
Pneumatic fittings are mechanical connectors designed to join sections of tubing, hose, or pipe within compressed air systems, typically rated for operating pressures between 0 and 16 bar and manufactured through CNC machining, hot forging, or injection molding depending on base material. Their primary purpose is to maintain leak-free air transfer while enabling rapid assembly, disassembly, and directional control in automated machinery. Push-to-Connect fittings dominate volume in automotive and general manufacturing lines where tool-free installation reduces downtime, while Stainless Steel variants command premium positioning in pharmaceutical cleanrooms and food processing plants where washdown protocols and corrosion resistance define specification sheets. Plastic fittings, though lower in absolute margin per unit, are capturing expanded share in lightweight pneumatic circuits for electronics assembly where weight reduction and chemical inertness outweigh metal durability requirements.
ISO 4414 safety standards for pneumatic systems, REACH substance restrictions on leaded brass alloys, and China's GB/T 7306 thread specifications collectively shape material selection, surface treatment requirements, and cross-border component interoperability for suppliers serving multinational OEMs. FDA compliance for food-contact surfaces and EU MDR traceability obligations further narrow the supplier base in hygienic applications where documentation burden favors established manufacturers with dedicated regulatory affairs functions. Stakeholders must monitor how evolving PFAS restrictions and carbon-border adjustment mechanisms reshape total cost equations for brass and polymer feedstock sourcing across their supplier portfolios.
Market Dynamics
REACH substance restrictions on leaded brass alloys are forcing material substitutions across European supply chains, compressing margins for foundries dependent on traditional machining grades while opening specification windows for stainless steel and engineered polymer alternatives.
Growth Catalysts
- Automotive assembly expansion:OEMs in Mexico, Germany, and Vietnam are scaling pneumatic infrastructure to support electric vehicle production lines and battery module assembly.
- REACH compliance mandates:Europe's tightened material specifications are accelerating certified supplier consolidation, favoring manufacturers with dedicated regulatory affairs and traceability systems.
- Electronics localization:Southeast Asian manufacturing corridors in Vietnam and Thailand are drawing pneumatic component demand from semiconductor and consumer electronics OEMs relocating supply chains.
Market Restraints
- Copper and zinc price volatility:Brass feedstock costs fluctuate with London Metal Exchange pricing, exposing mid-tier foundries to margin compression without long-term hedging instruments.
- Single-source machining concentration:Precision CNC capacity for high-tolerance stainless steel bodies concentrates in southern German and northern Italian supplier clusters, creating geographic vulnerability.
- Polymer substitution ceiling:Engineered plastics cannot match metal pressure ratings above 10 bar, limiting penetration in heavy-duty automation and compressed air distribution headers.
Strategic Opportunities
- Vietnam manufacturing corridors:Electronics and automotive OEM localization is outpacing domestic pneumatic component supply, creating import substitution windows for regional production facilities.
- EU carbon border adjustment:The CBAM mechanism rewards low-carbon brass and polymer sourcing, advantaging suppliers with verified Scope 3 emissions documentation.
- Pharmaceutical cleanroom standards:EU MDR traceability obligations and FDA washdown protocols are narrowing supplier pools, premiumizing stainless steel fittings with full batch documentation.
Industry Challenges
- Multi-standard threading compatibility:Engineers must reconcile ISO 4414 safety specifications with China's GB/T 7306 thread forms and legacy NPT inventories in retrofit environments.
- PFAS contamination screening:Emerging restrictions on fluorinated polymer sealants require reformulation of O-ring compounds and validation of alternative elastomer performance in high-cycle applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Fittings Market |
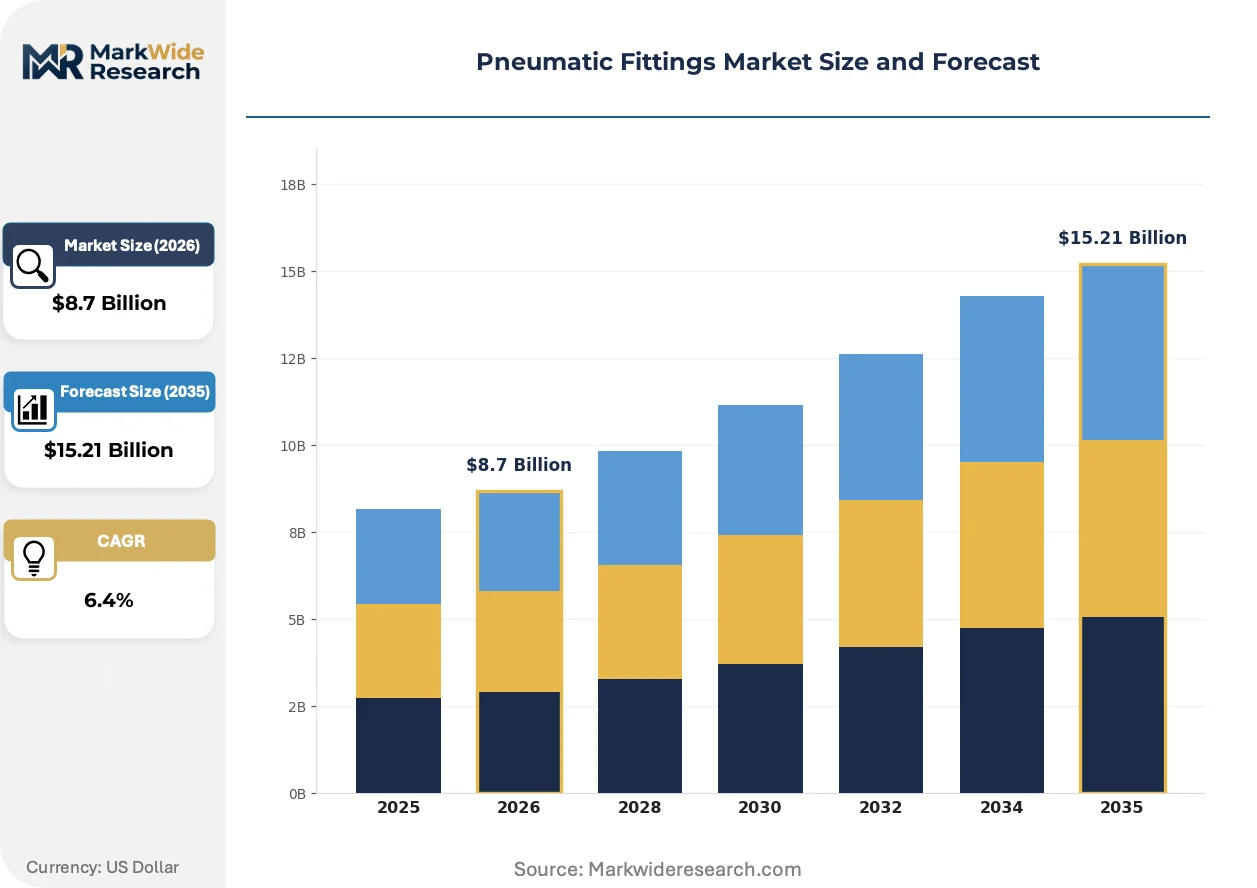
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-to-Connect, Barbed, Compression, Flared Material: Brass, Stainless Steel, Plastic, Aluminum Connection Type: Threaded, Quick Disconnect, Push-fit, Flanged Application: Automotive, Manufacturing, Food Processing, Pharmaceuticals |
| Companies Covered | Festo, SMC Corporation, Parker Legris, IMI Norgren, Bosch Rexroth AG, Eaton, Metal Work, Pneumax S.p.A., Ingersoll Rand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Fittings Market Evolving Landscape
Material science advances and regulatory tightening are converging to reshape component specifications, with suppliers racing to certify alternatives before compliance deadlines eliminate legacy formulations from approved vendor lists.
Hybrid polymer-to-metal fitting architectures are unifying the installation speed of push-to-connect systems with the pressure tolerance of brass bodies. Food processing OEMs in Denmark and the Netherlands are piloting these configurations for clean-in-place environments. The technology is unifying previously separate specification tracks for chemical resistance and mechanical durability, collapsing dual-inventory requirements into single-SKU procurement.
China's GB standards evolution is narrowing thread form tolerances and mandating nickel-free surface treatments for brass components in potable water adjacent applications. Domestic foundries in Zhejiang and Guangdong provinces are retooling plating lines to meet chromium-VI elimination timelines. Exporters serving multinational OEMs face parallel compliance burdens, maintaining separate production runs for REACH-restricted European shipments and GB-compliant domestic Chinese sales.
Buyer concentration among automotive tier-one suppliers is compressing quotation cycles and unbundling after-sales service from hardware contracts. Procurement teams at German and Japanese OEMs now demand predictive maintenance data packages alongside fitting deliveries. This behavioral shift is most visible in Mexico's Querétaro and Guanajuato automotive clusters, where line-down cost penalties have shifted supplier selection criteria toward inventory proximity and technical response speed over unit price.
Pneumatic Fittings Market Segmentation
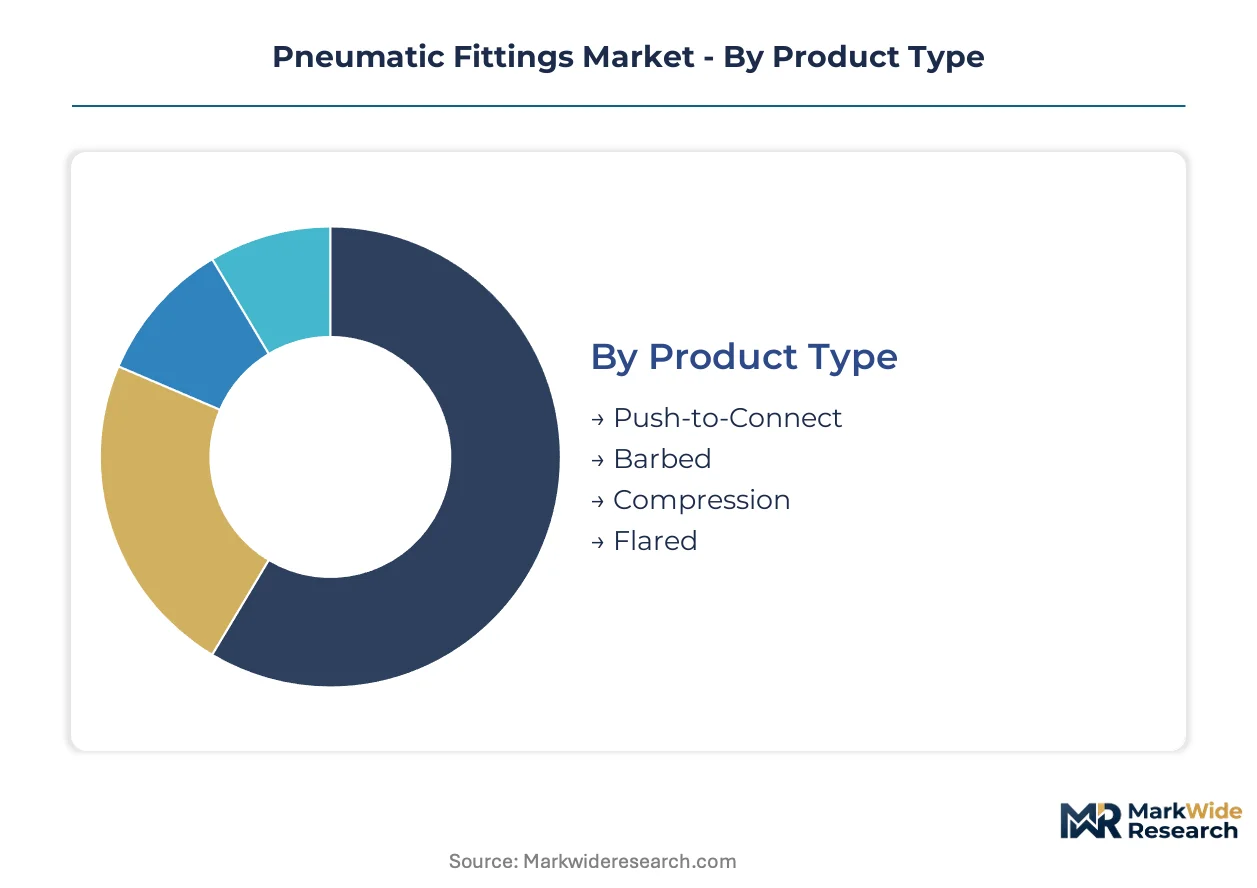
Pneumatic fitting specifications diverge sharply across end-use environments, with pressure ratings, material compatibility, and regulatory compliance requirements driving procurement decisions. Buyers segment their supplier portfolios by installation speed, corrosion resistance, and documentation burden rather than unit cost alone.
Product Type:
Installation labor cost and line downtime tolerance determine which connection technology buyers specify.
- Push-to-Connect:Tool-free assembly using collet-and-gripper mechanisms enables sub-30-second tube changes without thread sealants. Automotive assembly lines in Mexico's Querétaro cluster specify these for robotic cell reconfiguration where every minute of downtime carries six-figure penalties. REACH-compliant nickel-free brass bodies dominate European procurement.
- Barbed:Serrated shank designs grip flexible tubing through friction and hose clamp reinforcement, tolerating vibration in mobile pneumatic systems. Construction equipment OEMs in Germany's Baden-Württemberg region favor barbed configurations for outdoor compressors where thermal cycling degrades threaded seals.
- Compression:Ferrule-and-nut assemblies deliver metal-to-metal sealing for high-pressure circuits above 10 bar. Stainless steel variants serve pharmaceutical cleanrooms requiring FDA-validated surface finishes.
- Flared:Conical seat geometries distribute stress across tube walls for leak-free joints in vibration-intensive environments. Heavy machinery hydraulic-pneumatic hybrids in Vietnam's manufacturing corridors specify flared connections for excavator and forklift systems.
Push-to-Connect leads on scale; Barbed leads on momentum in mobile equipment applications.
Material:
Corrosion exposure, pressure requirements, and regulatory substance restrictions narrow viable material options for each application environment.
- Brass:Copper-zinc alloys machine precisely to ISO 4414 tolerances and accept nickel or chrome plating for oxidation resistance. REACH substance restrictions on leaded grades are forcing European foundries toward bismuth-substituted machinability additives. German automotive tier-ones now mandate full material composition certificates.
- Stainless Steel:Austenitic grades withstand caustic washdown cycles and maintain surface integrity under FDA and EU MDR traceability protocols. Danish and Dutch food processing OEMs specify 316L bodies with electropolished finishes for clean-in-place systems.
- Plastic:Glass-reinforced polyamide and PBT offer chemical inertness and 40-60% weight reduction versus metal equivalents. Electronics assembly in Thailand's Eastern Economic Corridor specifies plastic push-to-connect fittings for pick-and-place equipment where vibration damping matters more than pressure tolerance.
- Aluminum:Anodized extrusions balance machinability with corrosion resistance for lightweight distribution manifolds. Aerospace ground support equipment in France specifies aluminum for portable compressed air carts where every kilogram affects maneuverability.
Brass retains volume leadership; Stainless Steel climbs fastest on pharmaceutical and food-grade certification requirements.
Connection Type:
Thread form standardization and reconfiguration frequency dictate which mechanical interface engineers specify.
- Threaded:Tapered and parallel thread forms per GB/T 7306, NPT, and BSPP standards dominate permanent installations. China's domestic OEMs increasingly specify nickel-free surface treatments to satisfy both GB standards and export REACH requirements.
- Quick Disconnect:Spring-loaded sleeve mechanisms enable single-hand coupling under pressure. Automotive maintenance bays across Germany specify ISO 4414-compliant quick disconnects for diagnostic equipment swap-outs.
- Push-fit:Collet retention without threaded engagement suits temporary pneumatic circuits and prototyping environments. Electronics contract manufacturers in Vietnam favor push-fit for short-run assembly line trials.
- Flanged:Bolted face seals handle high-flow distribution headers where vibration would loosen threaded joints. Steel mills in India's Maharashtra state specify flanged stainless connections for pneumatic actuator lines near blast furnaces.
Threaded connections dominate installed base; Quick Disconnect gains share fastest in service-intensive environments.
Application:
Cleanroom classification, washdown protocols, and production line speed requirements create distinct specification clusters.
- Automotive:Battery module assembly and electric powertrain production lines demand rapid reconfiguration capabilities. OEMs in Mexico, Germany, and Vietnam specify push-to-connect systems with predictive maintenance data packages to avoid line-down penalties.
- Manufacturing:General automation spans packaging, material handling, and assembly with pressure ratings from 6 to 16 bar. Southeast Asian electronics corridors in Vietnam and Thailand drive demand for lightweight plastic and aluminum configurations.
- Food Processing:Clean-in-place protocols and FDA food-contact surface requirements mandate 316L stainless steel with full batch traceability. Dutch and Danish OEMs pilot hybrid polymer-to-metal architectures to unify chemical resistance with mechanical durability.
- Pharmaceuticals:EU MDR traceability obligations and washdown sterilization cycles restrict supplier pools to manufacturers with dedicated regulatory affairs functions. Electropolished stainless fittings with full documentation command substantial premiums over standard industrial grades.
Automotive leads on absolute volume; Pharmaceuticals expands most quickly on regulatory-driven supplier consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Querétaro's automotive corridor anchors pneumatic fitting demand as OEMs expand electric vehicle assembly across Mexico, Germany, and Vietnam. Each geography presents distinct regulatory and supply chain configurations that reshape procurement patterns for precision-machined components.
Mexico
Automotive OEMs in Querétaro and Guanajuato specify push-to-connect systems with predictive maintenance data packages to avoid line-down penalties. The country's automotive manufacturing regulations align with USMCA origin requirements for North American supply chains. Guanajuato's battery module assembly plants drive demand for rapid-reconfiguration pneumatic infrastructure.
Germany
Baden-Württemberg's automotive tier-ones now mandate full material composition certificates for brass components under REACH substance restrictions. ECHA's tightened specifications on leaded alloys are forcing foundries toward bismuth-substituted machinability additives. Stuttgart's electric powertrain production lines compress quotation cycles and unbundle after-sales service from hardware contracts.
Vietnam
Electronics contract manufacturers in Vietnam's Northern Key Economic Zone favor push-fit configurations for short-run assembly line trials. The country's national technical regulations on pneumatic equipment thread forms create compliance complexity for multinational suppliers. Ho Chi Minh City's manufacturing corridors draw pneumatic component demand from semiconductor OEMs relocating supply chains.
China
Zhejiang and Guangdong foundries retool plating lines to meet GB standards evolution mandating nickel-free surface treatments for brass components. SAMR's chromium-VI elimination timelines compress margin recovery windows for exporters maintaining separate production runs. Domestic OEMs increasingly specify surface treatments satisfying both GB compliance and export REACH requirements.
Thailand
Electronics assembly in Thailand's Eastern Economic Corridor specifies plastic push-to-connect fittings for pick-and-place equipment where vibration damping matters more than pressure tolerance. The country's industrial standards agency tightens material specifications for automation components in line with ASEAN harmonization initiatives. Rayong's consumer electronics OEMs localize supply chains faster than domestic pneumatic component capacity expands.
Pneumatic Fittings Market Competitive Landscape
Global majors compete with regional champions across certification depth and geographic proximity to automotive clusters. The vendor base stratifies into three tiers: integrated automation conglomerates with captive fitting production, specialized pneumatic component houses with dedicated regulatory affairs functions, and regional fabricators serving price-sensitive industrial maintenance markets. Dominant competitive moves include backward integration into brass foundry capacity and strategic partnerships with predictive maintenance software providers.
Within the integrated automation tier, Festo and SMC Corporation exemplify manufacturers sustaining component consistency across multi-continental valve-fitting systems. Parker Legris occupies a position among polymer-to-metal hybrid specialists extending reach into food-grade and pharmaceutical cleanroom environments. IMI Norgren anchors the British-German axis of pneumatic component supply with deep distribution control in European automation markets. Bosch Rexroth AG represents the hydraulics-pneumatics convergence archetype leveraging industrial automation platform breadth.
| Leading Market Players |
|---|
| Festo |
| SMC Corporation |
| Parker Legris |
| IMI Norgren |
| Bosch Rexroth AG |
| Eaton |
| Metal Work |
| Pneumax S.p.A. |
| Ingersoll Rand |
| Others |
Value Network & Pricing Analysis
EU carbon border adjustment mechanisms gate both qualified supply and premium-tier pricing access for pneumatic fitting manufacturers, rewarding suppliers with verified Scope 3 emissions documentation while compressing margins for foundries without carbon accounting infrastructure. Brass feedstock costs fluctuate with London Metal Exchange pricing, exposing mid-tier European foundries to margin compression without long-term hedging instruments.
Pricing Analysis
Copper and zinc price pass-through dynamics dominate pneumatic fitting economics, with brass feedstock volatility compressing margins for unhedged foundries while stainless steel variants command sustained premiums. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-validated pharmaceutical grades from REACH-compliant industrial brass and unbranded regional maintenance stock. Pricing pressure stems from automotive OEM procurement teams unbundling after-sales service from hardware contracts in Mexico's Querétaro cluster. Tier-one automotive buyers exhibit lowest price sensitivity due to line-down cost penalties, while maintenance procurement in Southeast Asian electronics corridors drives aggressive unit-cost negotiation.
Supply Chain Analysis
REACH and GB standards certification gates supplier qualification, restricting approved vendor lists to manufacturers with dedicated regulatory affairs functions and full material composition certificates. Precision CNC capacity for high-tolerance stainless steel bodies concentrates in southern Germany and northern Italy, while brass foundry operations anchor in Zhejiang and Guangdong provinces. Feedstock dependencies span copper-zinc alloys, austenitic stainless grades, and glass-reinforced polyamide resins. Single-source machining concentration creates geographic vulnerability for pharmaceutical and food-grade specification tiers. Distribution runs through authorized distributor networks with technical service capabilities, bypassing commodity hardware channels for certified industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pneumatic fittings function as a stable compounder anchored by automotive assembly line automation, where electric vehicle production expansion sustains predictable demand for rapid-reconfiguration infrastructure across Mexico, Germany, and Vietnam.
For Market Incumbents: Lock in regulatory certification depth before ECHA's leaded brass restrictions eliminate legacy formulations from approved vendor lists. Backward integration into captive brass foundry capacity in Vietnam's Northern Key Economic Zone insulates margin pressure from London Metal Exchange volatility. Deepen predictive maintenance data partnerships with German automotive tier-ones to defend against hardware commoditization. For New Entrants and Emerging Players: The mid-tier pricing gap between Festo-SMC premium positioning and unbranded regional maintenance stock creates entry space for certified regional specialists. Vietnam's electronics contract manufacturers present the most penetrable demand cluster, with localization outpacing domestic pneumatic component supply. Lead with REACH-compliant nickel-free brass configurations and 48-hour technical response guarantees to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap pneumatic component houses because regulatory documentation burdens favor scaled regulatory affairs functions over fragmented regional fabricators. Five-to-ten year viability rests on carbon-border compliance infrastructure and pharmaceutical certification depth. Watch for EU MDR enforcement intensity as the inflection signal separating premium-validated suppliers from commodity industrial grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Foundry Capacity | Captive supply of REACH-compliant alloys insulates margin pressure from London Metal Exchange volatility in German automotive supply chains. |
| Predictive Maintenance Data Partnership | Hardware-software bundling with Querétaro automotive OEMs defends against procurement unbundling and service commoditization. |
| GB Standards Dual-Certification Investment | Parallel REACH and GB compliance enables single-production-run efficiency for Zhejiang exporters serving multinational OEMs. |
| Regional Manufacturing Footprint in Vietnam | Proximity to Northern Key Economic Zone electronics corridors captures import substitution demand from semiconductor OEM localization. |
| Pharmaceutical Cleanroom Certification Pathway | EU MDR traceability infrastructure opens premium positioning in Danish and Dutch food processing OEM pilot programs. |
Research Methodology
Bottom-up automotive and electronics assembly modeling reconciled against top-down brass and stainless steel supply tracking forms the analytical core of this study. Primary interviews with plant engineers at Mexican automotive OEMs, procurement leads at German tier-one suppliers, regulatory affairs directors at European foundries, and maintenance directors at Thai electronics contract manufacturers combined with secondary validation from ECHA substance restriction filings, SAMR GB standards evolution notices, London Metal Exchange pricing data, and USMCA automotive origin certification records. Triangulation across stakeholder input and trade documentation ensures cross-verified demand and supply estimates.
Historical trendline analysis of pneumatic infrastructure investment patterns across automotive assembly expansion corridors established baseline growth parameters. Segmentation modeling spans product type, material grade, connection technology, and application environment across the projection horizon. CAGRs derive from fitted trend extrapolation adjusted for regulatory compliance cost step-changes and regional manufacturing localization rates. Industry-specific forecast inputs include electric vehicle production line reconfiguration frequency and pharmaceutical cleanroom capital expenditure cycles.
Caveats apply where ECHA enforcement intensity, copper price volatility, or PFAS restriction timelines could materially shift the outlook for material substitution trajectories and supplier consolidation patterns. A model refresh is warranted upon material change in carbon-border adjustment mechanism implementation scope or ASEAN harmonization initiative progression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Saudi Arabia PE Pipes Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Perfusion Tubing Systems Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Global Tracer Wires Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
Oman PVC Pipes Market
Pipes and Tubes
Stainless Steel Welded Pipes Market
Pipes and Tubes
HDPE Corrugated Pipe Market