
 Phosphorus Based Catalyst Market | 2026-2036
Phosphorus Based Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphorus Based Catalyst Market Analytics
Market Context
China's expanding petrochemical corridor is reconfiguring regional supply dynamics for phosphorus based catalyst precursors. BASF SE leverages backward integration into phosphorus trichloride feedstocks to secure cost-advantaged positions in homogeneous catalyst grades. Clariant AG anchors its competitiveness through specialized manufacturing of supported catalysts for polymerization applications.
Technical Definition and Segment Structure
Phosphorus based catalysts comprise coordination compounds, organophosphine ligands, and phosphoric acid derivatives that accelerate selective chemical transformations through Lewis base or transition metal complexation mechanisms, typically operating at 50-200°C with turnover frequencies exceeding 10,000 hr-1 in industrial hydrogenation loops. Heterogeneous catalysts dominate volume consumption in fluid catalytic cracking units, while homogeneous catalysts command premium pricing in pharmaceutical asymmetric synthesis where enantioselectivity requirements exceed 99%. Supported catalysts are gaining share in hydrocracking applications as refiners seek to extend catalyst cycle lengths beyond 36 months.
Regulatory Framework and Outlook
EPA hazardous waste classifications and REACH substance restrictions are tightening handling protocols for white phosphorus derivatives, directly elevating compliance costs for catalyst formulators serving North American and European chemical manufacturers. China's MEE emission standards for phosphorus-containing effluents are forcing Yangtze Basin producers to adopt closed-loop recovery systems. Stakeholders must weigh capital allocation between regulatory-compliant capacity in mature jurisdictions and cost-optimized expansion in Southeast Asian chemical parks.
Market Dynamics
REACH substance restrictions on white phosphorus derivatives are compressing supplier margins in Europe while accelerating capital flight to Southeast Asian chemical parks with looser environmental enforcement. This regulatory asymmetry is restructuring competitive positioning across the catalyst value chain.
Growth Catalysts
- Metallocene polymerization:East Asian petrochemical complexes are scaling organophosphorus ligand consumption for single-site catalyst systems producing high-performance polyolefins.
- EPA hazardous waste reclassification:Stricter handling protocols for phosphorus trichloride are consolidating demand among certified formulators with captive waste treatment infrastructure.
- Hydrocracking cycle extension:Refiners in the US Gulf Coast are adopting supported phosphorus catalysts to push regeneration intervals past 36 months, locking in long-term supply contracts.
Market Restraints
- Feedstock concentration:Phosphorus rock processing capacity clusters in China and Morocco, exposing catalyst manufacturers to export quota volatility and freight cost spikes.
- Substitution by zeolites:Fluid catalytic cracking operators are trialing rare-earth exchanged zeolite systems to reduce phosphorus effluent treatment burdens.
- REACH authorization timelines:ECHA's extended review periods for novel phosphorus ligands are delaying commercialization of next-generation asymmetric hydrogenation catalysts by 18-24 months.
Strategic Opportunities
- Vietnam's chemical park expansion:Phu My industrial zone developers are offering 10-year tax holidays to catalyst formulators relocating from Yangtze Basin facilities facing MEE emission crackdowns.
- Bio-based ligand platforms:Chiral phosphine synthesis from renewable terpene feedstocks is opening pathways to EU Green Deal-compliant catalyst grades.
- Digital twin deployment:Catalyst lifecycle modeling software is enabling predictive regeneration scheduling, creating service-revenue streams distinct from product sales.
Industry Challenges
- Organometallic synthesis expertise:The specialized skill set for air-sensitive phosphine ligand production is concentrating among retiring cohorts in Germany and Japan with inadequate knowledge transfer protocols.
- Legacy refinery integration:Hydrocracker revamps to accommodate higher-activity phosphorus catalysts require simultaneous furnace and separator modifications, complicating project execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphorus Based Catalyst Market |
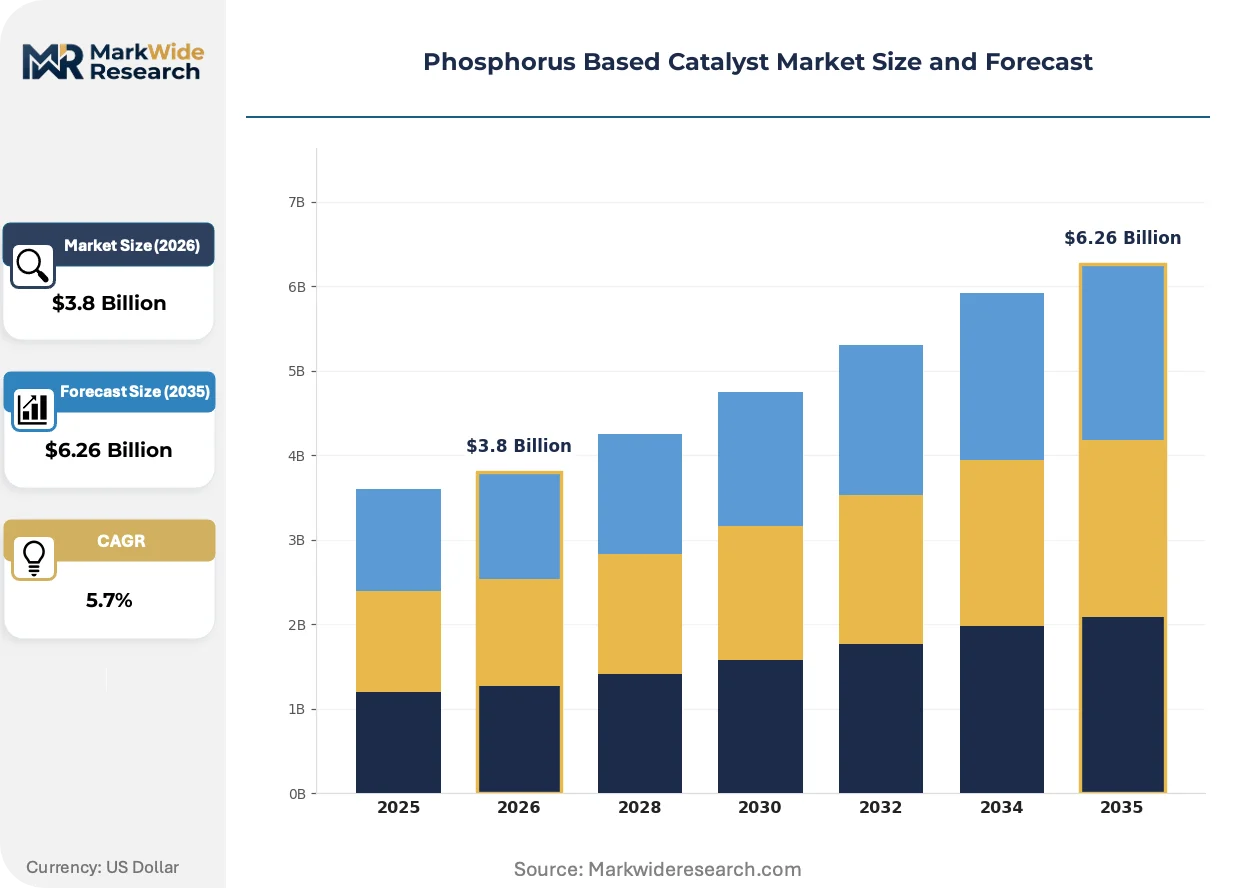
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heterogeneous Catalysts, Homogeneous Catalysts, Supported Catalysts, Bulk Catalysts Application: Petrochemicals, Chemical Synthesis, Pharmaceuticals, Agrochemicals End User: Chemical Manufacturers, Refining Industry, Agricultural Sector, Research Institutions Technology: Catalytic Cracking, Hydrocracking, Oxidation, Hydrogenation |
| Companies Covered | BASF SE, Clariant AG, Johnson Matthey, Haldor Topsoe A/S, Albemarle Corporation, Evonik Industries AG, W. R. Grace & Co.-Conn., LANXESS, ICL Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphorus Based Catalyst Market Evolving Landscape
Computational catalyst design and closed-loop phosphorus recovery are converging to reshape how manufacturers develop, deploy, and retire catalytic systems. These shifts are compressing development cycles while tightening environmental accountability.
Machine learning models trained on DFT calculations are virtualizing the ligand screening process that previously required months of wet-lab synthesis. Pharmaceutical manufacturers in Switzerland and Massachusetts are adopting these in-silico pipelines to cut asymmetric hydrogenation catalyst development from 18 months to under 6. This compression is virtualizing the traditional competitive moat of large experimental chemistry teams, enabling mid-scale specialists to compete for complex chiral synthesis contracts.
China's MEE is enforcing phosphorus discharge limits in the Yangtze River Delta that exceed prior national standards by 40%. Catalyst producers in Jiangsu and Zhejiang provinces are installing acid-recovery crystallizers and membrane filtration systems at capital costs exceeding $12 million per facility. Smaller formulators without balance-sheet capacity for these upgrades are exiting or selling to state-owned chemical conglomerates with project finance access.
Refinery procurement departments are unbundling catalyst supply from technical service contracts that historically ran 5-7 years. Buyers in the US Gulf Coast and Rotterdam-Antwerp corridor are now sourcing homogeneous catalysts through spot markets while retaining third-party consultants for reactor optimization. This bifurcation is most visible in hydroprocessing applications, where established suppliers face margin pressure on both product and service lines simultaneously.
Phosphorus Based Catalyst Market Segmentation
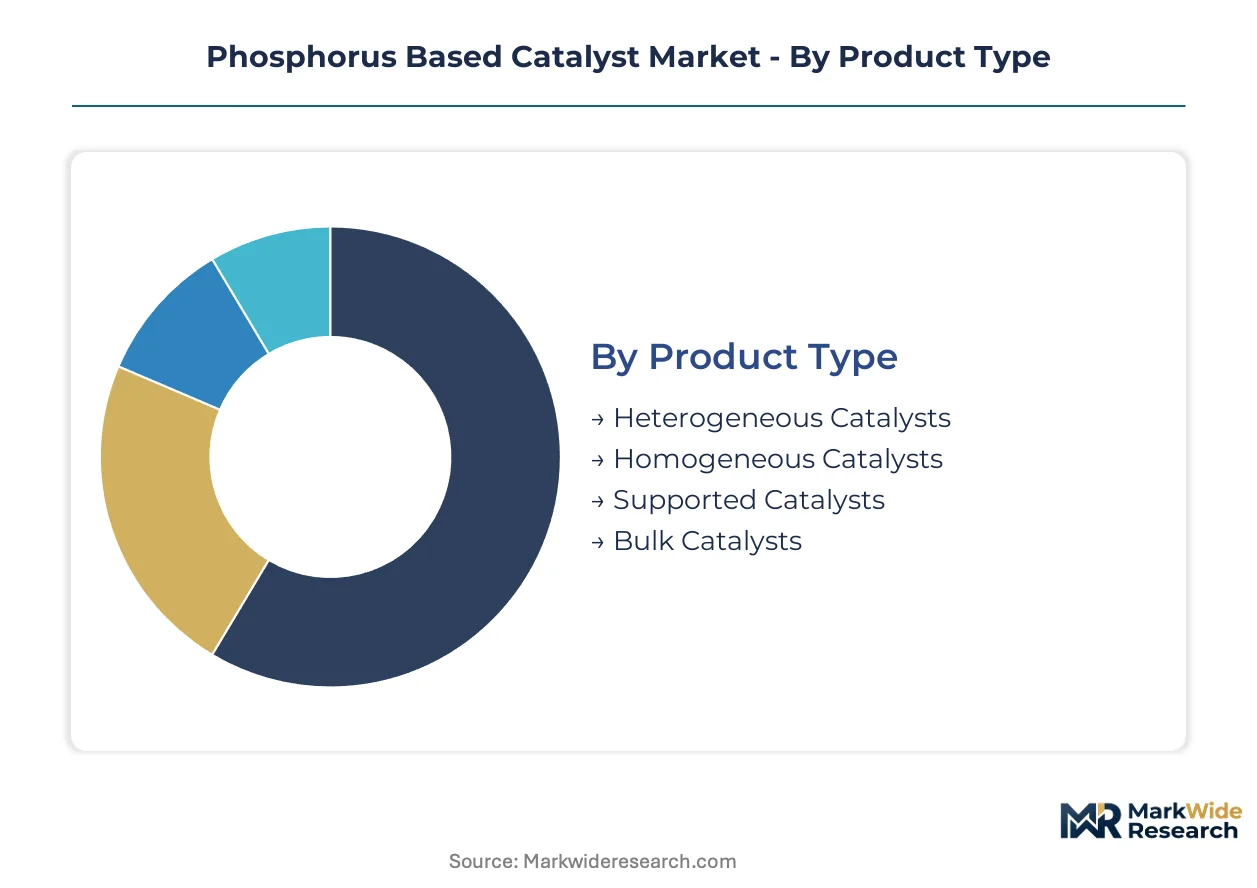
Phosphorus based catalysts serve radically different performance requirements across fluid catalytic cracking units and pharmaceutical asymmetric synthesis suites. Segmentation reveals how homogeneous systems command premium pricing for enantioselectivity above 99%, while heterogeneous grades dominate volume consumption in refinery hydroprocessing. Understanding these divides clarifies where formulation expertise concentrates versus where commodity scale prevails.
Product Type:
Use-case spectrum spans continuous-flow refinery operations demanding mechanical durability through batch pharmaceutical processes requiring molecular precision.
- Heterogeneous Catalysts:Solid-phase systems with phosphorus active sites immobilized on alumina or silica supports enable fluidized bed operation at 450-550°C in FCC units. Demand concentrates in US Gulf Coast refineries where regenerability and attrition resistance drive procurement decisions against rising rare-earth zeolite competition.
- Homogeneous Catalysts:Soluble organophosphine ligands complexed with rhodium or palladium centers operate in liquid-phase hydrogenation with turnover frequencies exceeding 10,000 hr-1. Swiss and Massachusetts pharmaceutical manufacturers drive specification intensity for chiral ligands where single-enantiomer purity requirements exceed regulatory thresholds.
- Supported Catalysts:Phosphorus-modified zeolites and mesoporous silicas for hydrocracking applications where cycle length extension beyond 36 months justifies higher upfront catalyst costs.
- Bulk Catalysts:Unsupported metal phosphides and phosphates used in base chemical production where cost-per-active-site economics favor simple formulation architectures.
Established volume favors heterogeneous systems in refinery FCC and hydrocracking; emerging adoption favors homogeneous catalysts in pharmaceutical asymmetric synthesis and metallocene polymerization.
Application:
Cost tier stratification separates commodity-scale petrochemical throughput from kilogram-scale pharmaceutical active ingredient production.
- Petrochemicals:Organophosphorus ligands for metallocene single-site catalysts producing high-performance polyolefins with narrow molecular weight distribution. East Asian complexes along China's Yangtze River Delta are expanding procurement fastest as polyethylene capacity additions outpace other regions.
- Pharmaceuticals:Chiral phosphine ligands for asymmetric hydrogenation in statin and antiviral synthesis where regulatory filing requirements lock in catalyst specifications for product lifecycle duration.
- Chemical Synthesis:Phosphoric acid derivatives and phosphine oxides for fine chemical intermediates including agrochemical precursors and specialty polymer additives.
- Agrochemicals:Phosphorus trichloride-derived catalysts for herbicide and fungicide active ingredient manufacture, with demand tied to seasonal planting patterns and glyphosate formulation trends.
Margin compression concentrates in agrochemical and bulk chemical synthesis; pricing power accumulates in pharmaceutical applications with locked-in regulatory specifications.
End User:
Customer type diversity ranges from integrated oil majors with captive catalyst regeneration facilities to contract research organizations sourcing gram quantities for route scouting.
- Chemical Manufacturers:Specialty and fine chemical producers operating batch hydrogenation and carbonylation units with catalyst consumption tied to product campaign schedules and multipurpose reactor utilization rates.
- Refining Industry:Hydrocracker and FCC unit operators in Rotterdam-Antwerp and US Gulf Coast corridors seeking 36-plus month catalyst cycles to minimize turnaround frequency and lost production.
- Agricultural Sector:Pesticide formulators and active ingredient producers with procurement patterns synchronized to Northern Hemisphere planting seasons and inventory build cycles.
- Research Institutions:Universities and national laboratories screening novel phosphorus ligand architectures for academic publication and patent filing prior to commercial licensing.
Volume concentration sits with refining industry procurement; technology trajectory leadership emerges from research institution pipelines feeding licensed production.
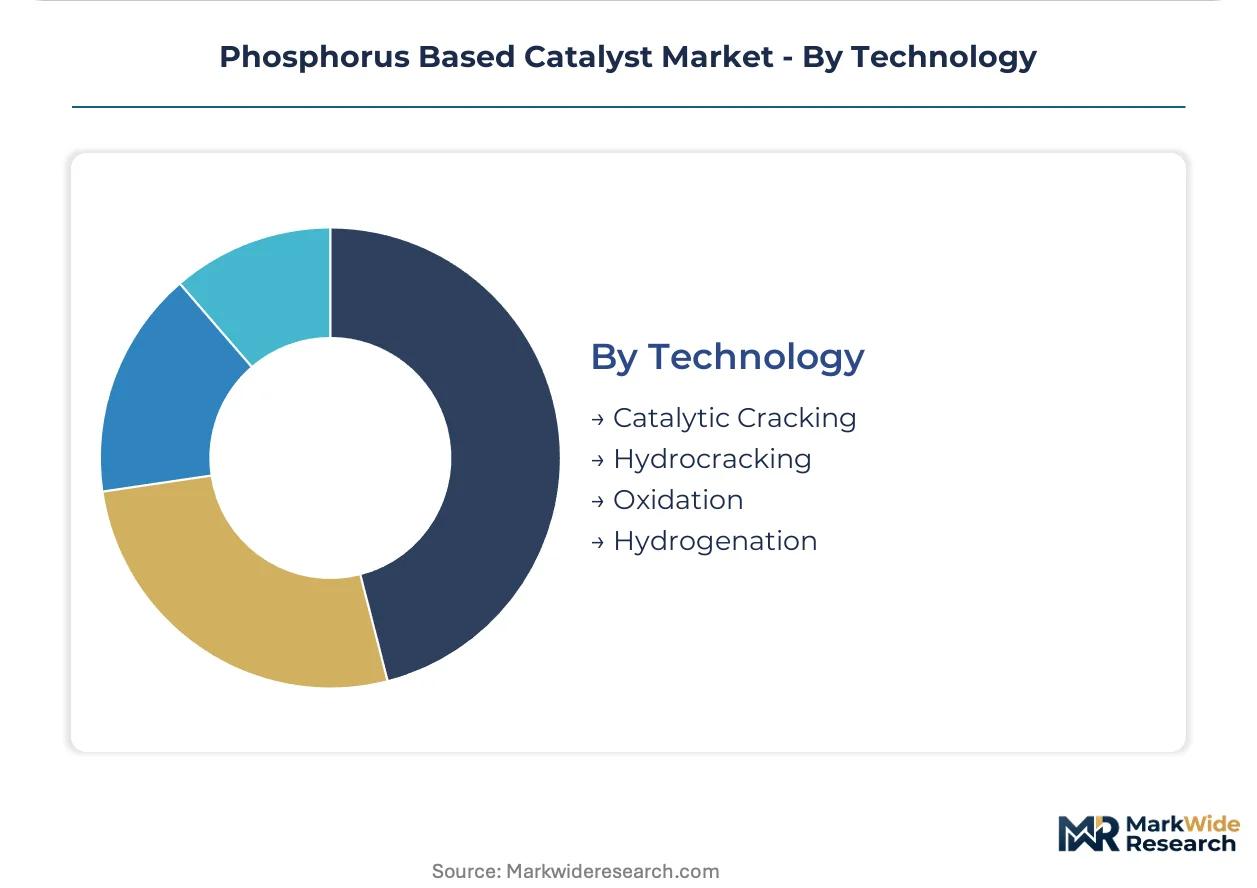
Technology:
Maturity gradients separate century-old catalytic cracking from emerging oxidation protocols for biomass-derived feedstock valorization.
- Catalytic Cracking:Phosphorus-modified zeolite Y systems for vacuum gas oil conversion to lighter fractions, facing substitution pressure from rare-earth exchanged alternatives under tighter phosphorus effluent regulations.
- Hydrocracking:Ni-Mo or Co-Mo sulfides promoted by phosphorus for heavy vacuum gas oil and deasphalted oil upgrading, with supported catalyst formulations gaining share for extended cycle operation.
- Hydrogenation:Homogeneous and heterogeneous phosphorus-ligated systems for nitroarene reduction, alkene saturation, and carbonyl compounds including pharmaceutical intermediate manufacture.
- Oxidation:Tungsten and molybdenum phosphorus heteropolyacids for epoxidation and sulfoxidation reactions in fine chemical production with emerging application in bio-based platform chemical synthesis.
Technology investment flows toward hydrocracking cycle extension and pharmaceutical hydrogenation selectivity; catalytic cracking faces mature demand with regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE emission standards in China are forcing phosphorus catalyst producers to install closed-loop recovery systems at capital costs exceeding $12 million per facility. This regulatory pressure is accelerating facility relocations to Southeast Asian chemical parks with more permissive environmental frameworks.
China
Organophosphorus ligand consumption for metallocene single-site catalysts is scaling fastest in Yangtze River Delta petrochemical complexes. MEE phosphorus discharge limits now exceed prior national standards by 40%, driving Jiangsu and Zhejiang formulators toward acid-recovery crystallizers or exit. Smaller producers without balance-sheet capacity are selling to state-owned chemical conglomerates with project finance access.
United States
US Gulf Coast refiners are adopting supported phosphorus catalysts to push hydrocracker regeneration intervals past 36 months. EPA hazardous waste reclassifications for phosphorus trichloride are consolidating demand among certified formulators with captive waste treatment infrastructure. Houston and Port Arthur procurement departments are unbundling catalyst supply from historical 5-7 year technical service contracts.
Germany
Specialized manufacturing of homogeneous catalyst grades concentrates in Ludwigshafen and Leverkusen chemical corridors. REACH authorization timelines for novel phosphorus ligands are extending commercialization delays for next-generation asymmetric hydrogenation catalysts by 18-24 months. ECHA substance restrictions on white phosphorus derivatives are compressing supplier margins while accelerating capital flight.
Switzerland
Pharmaceutical manufacturers in Basel are deploying machine learning models trained on DFT calculations to virtualize ligand screening processes. Swissmedic regulatory filing requirements lock in catalyst specifications for product lifecycle duration, creating pricing power for chiral phosphine suppliers. The country's dual-track chemical-pharma ecosystem sustains premium homogeneous catalyst demand.
Vietnam
Phu My industrial zone developers are offering 10-year tax holidays to catalyst formulators relocating from Yangtze Basin facilities. Vietnam's chemical park expansion is capturing displaced capacity from Chinese producers facing MEE crackdowns. The Southeast Asian hub is emerging as a cost-optimized alternative for commodity-grade phosphorus catalyst manufacturing.
Phosphorus Based Catalyst Market Competitive Landscape
Vertically integrated chemical conglomerates and specialized catalyst formulators split the market along purity-grade and application-complexity lines. The vendor base clusters around three strategic archetypes: backward-integrated feedstock owners, application-specific formulation specialists, and refinery service-integrated suppliers. Dominant competitive moves include geographic relocation to Southeast Asian chemical parks and portfolio diversification into bio-based ligand platforms compliant with EU Green Deal frameworks.
Among European-based chemical conglomerates, BASF SE and Clariant AG exemplify contrasting strategic positions within the catalyst value chain. BASF SE anchors the backward-integrated archetype through captive phosphorus trichloride feedstock positions, while Clariant AG occupies the specialized manufacturing tier for supported catalyst systems. Johnson Matthey represents the Anglo-Dutch service-integrated model with historical refinery technical contracting relationships. These three entities collectively illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific product-market outcomes.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Johnson Matthey |
| Haldor Topsoe A/S |
| Albemarle Corporation |
| Evonik Industries AG |
| W. R. Grace & Co.-Conn. |
| LANXESS |
| ICL Group |
| Others |
Value Network & Pricing Analysis
Yangtze River freight corridors linking Jiangsu and Zhejiang production clusters to Shanghai port terminals impose cost differentials that compound with REACH compliance burdens to stratify pricing power across European and Southeast Asian supply alternatives.
Pricing Analysis
Geographic price spreads between Yangtze Basin manufacturers and Vietnam's Phu My industrial zone exceed cost-of-compliance differentials for homogeneous catalyst grades. Three-tier pricing structure across pharmaceutical-certified, refinery-grade, and bulk chemical tiers reflects certification intensity and volume scale. Pricing pressure stems from rare-earth zeolite substitution in fluid catalytic cracking, compressing margins for phosphorus-modified alternatives. Agrochemical formulators exhibit highest price sensitivity due to seasonal demand volatility, while pharmaceutical manufacturers lock in specifications regardless of cost.
Supply Chain Analysis
Tariff exposure between China and key export destinations concentrates risk for phosphorus trichloride feedstock flows. Manufacturing capacity clusters in China, Morocco, and Germany, with white phosphorus processing anchored in Chinese and Moroccan phosphate rock deposits. Catalyst production draws from phosphorus trichloride, organophosphine intermediates, and rhodium group metal precursors. Single-source vulnerability concentrates in Chinese export quota administration for phosphorus derivatives. Distribution runs through regional chemical distributors serving refinery procurement departments and pharmaceutical manufacturer direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphorus based catalyst demand sits in early-cycle expansion as metallocene polymerization capacity additions across East Asia accelerate organophosphorus ligand adoption beyond replacement rates.
For Market Incumbents: Pre-empt rare-earth zeolite substitution in catalytic cracking by accelerating supported catalyst formulations for hydrocracking cycle extension. Secure captive phosphorus trichloride positions through upstream partnerships in Morocco to offset Chinese export quota volatility. Prioritize MEE-compliant facility upgrades in Yangtze Basin or complete relocations to Vietnam before emission enforcement tightens further.
For New Entrants and Emerging Players: Pursue bio-based chiral phosphine synthesis from renewable terpene feedstocks to capture EU Green Deal-compliant pharmaceutical demand. Target Vietnam's Phu My industrial zone for commodity-grade homogeneous catalyst manufacturing benefiting from 10-year tax holidays. Enter through digital twin-enabled catalyst lifecycle service contracts rather than product-only sales to bypass established supplier relationships.
For Investors and Strategic Acquirers: Specialized homogeneous catalyst formulators with Swissmedic-locked pharmaceutical specifications represent priority acquisition targets given pricing power durability. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Watch ECHA REACH authorization timelines for novel phosphorus ligands as the signal indicating whether next-generation asymmetric hydrogenation catalysts achieve commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Trichloride | BASF SE's captive feedstock positions secure cost-advantaged homogeneous catalyst supply against quota volatility. |
| Relocation to Southeast Asian Chemical Parks | Vietnam's Phu My zone captures displaced Yangtze Basin capacity facing MEE emission crackdowns. |
| Digital Twin Deployment | Predictive regeneration scheduling creates service-revenue streams distinct from commoditized catalyst sales. |
| Bio-Based Ligand Platform Development | Chiral phosphine synthesis from terpene feedstocks opens EU Green Deal-compliant pathways. |
| Long-Term Refinery Service Contracts | US Gulf Coast hydrocracker operators seek 36-plus month cycle guarantees locking in supply relationships. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings, and ECHA substance registration databases preceded structured interviews with catalyst plant managers, refinery procurement leads, pharmaceutical process chemists, and specialty chemical distribution channel partners. Bottom-up volume estimates triangulated against top-down industry association data from ACC and Cefic. Primary fieldwork validated secondary assumptions on capacity utilization and pricing trajectories.
Assumptions held fixed include regulatory enforcement intensity in China and Europe, while feedstock cost volatility and substitution technology penetration were modeled as scenario variables across the analysis window. Segmentation dimensions incorporated product type, application tier, end-user category, and regional production hub. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with metallocene polymerization capacity buildout and pharmaceutical pipeline composition as key forecast inputs.
Sensitivities concentrate around ECHA authorization timeline extensions and Chinese MEE enforcement escalation as revision triggers. Forecasts reflect assumptions on regulatory continuity and technology substitution rates without claiming predictive certainty. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Environmental Catalysts Market
Catalysts
Global Zeolites Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Refinery Catalyst Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Industrial Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Polymer Catalyst Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Inorganic Catalyst Market
Catalysts
Heterogeneous Catalyst Market