
 Europe PVC Pipes Market | 2026-2036
Europe PVC Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe PVC Pipes Market Intelligence
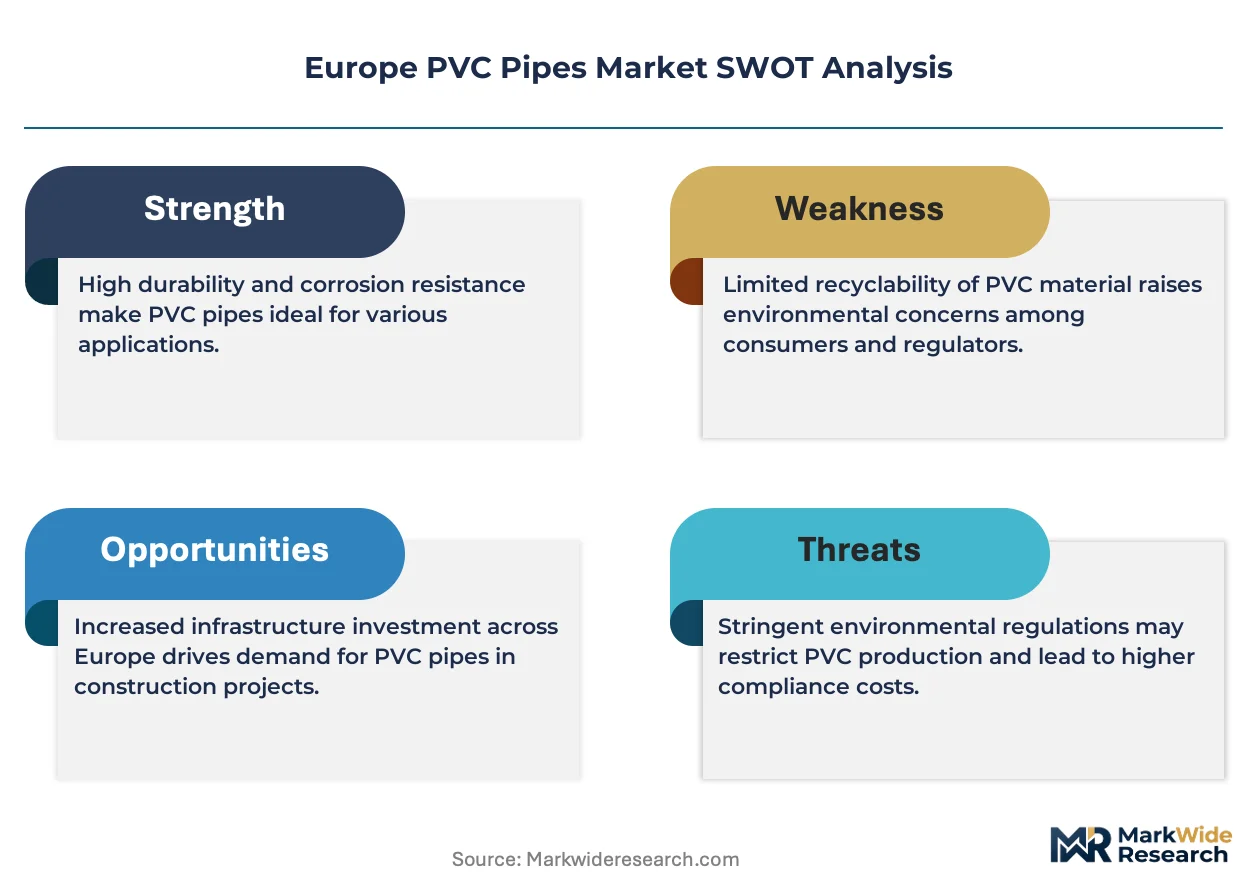
Consolidation among municipal water utilities is recalibrating procurement patterns across the Europe PVC Pipes Market. Pipelife International GmbH leverages its Austrian manufacturing footprint to anchor supply contracts with centralized purchasing consortia in Germany and Austria. REHAU AG + Co competes through specialized pressure pipe systems engineered for district heating crossover applications. Georg Fischer AG sustains its position via backward integration into chlor-alkali feedstock production, insulating margin structures from vinyl chloride monomer volatility.
Europe PVC Pipes comprise thermoplastic conduit systems extruded from polyvinyl chloride resin compounded with stabilizers, plasticizers, and impact modifiers, typically manufactured through twin-screw extrusion at temperatures between 160°C and 200°C, designed primarily for pressurized fluid conveyance and gravity-flow drainage infrastructure. Pressure Pipes dominate value capture due to stricter safety certification requirements and higher compound specifications for potable water transmission networks. Drainage Pipes represent the volume anchor in residential construction applications, though margin compression intensifies amid standardization of small-diameter formats. Sewage Pipes command premium positioning where municipal specifications mandate ring stiffness classes above SN8 for deep-burial installations.
REACH registration obligations and the EU Green Deal circularity protocols are tightening permissible additive chemistries and mandating recycled-content thresholds in public procurement tenders. CE marking under the Construction Products Regulation enforces harmonized performance declarations for pressure-bearing applications, creating compliance barriers for non-European suppliers. ECHA's ongoing restriction assessments for legacy stabilizer systems are forcing reformulation investments across compounders and extruders. Stakeholders must monitor the trajectory of EU taxonomy alignment requirements and their cascading impact on green financing eligibility for infrastructure projects specifying PVC pipe systems.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's circular economy mandates are compressing formulation timelines while opening procurement pathways for recycled-content PVC systems across municipal water infrastructure programs.
Growth Catalysts
- Municipal water infrastructure renewal:Germany and France are expanding procurement of large-diameter pressure pipes for potable water transmission networks, with centralized purchasing consortia consolidating demand volumes.
- EU Green Deal circularity protocols:Mandatory recycled-content thresholds in public procurement tenders are accelerating substitution of conventional materials with reformulated PVC compounds containing post-industrial recyclate.
- District heating crossover applications:Specialized pressure pipe systems engineered for thermal distribution networks are capturing incremental demand from energy utility operators in Central European markets.
Market Restraints
- Vinyl chloride monomer price volatility:Feedstock cost swings compress margin structures for extruders lacking backward integration into chlor-alkali production.
- ECHA restriction assessments:Ongoing evaluations of legacy stabilizer systems under REACH Article 69 are forcing compounders into costly reformulation investments with uncertain approval timelines.
- Concrete and ductile iron substitution:Municipal specifications in select Eastern European markets retain incumbent materials for deep-burial sewage applications with ring stiffness requirements above SN8.
Strategic Opportunities
- Polish municipal water consolidation:Underpenetrated regional utilities present white space for large-diameter pressure pipe suppliers capable of meeting CE marking harmonized performance declarations.
- Hydrogen-ready pipeline infrastructure:Convergence of PVC pressure pipe systems with hydrogen distribution testing protocols opens certification pathways for gas network operators.
- Digital twin integration:Embedding sensor-ready conduit architectures during extrusion creates value-added positioning for smart city infrastructure tenders specifying real-time leak detection.
Industry Challenges
- Reformulation chemistry expertise scarcity:Compounders face recruitment friction for polymer scientists capable of stabilizing recycled-content formulations under tightened additive chemistries.
- CE marking certification timeline compression:Notified body backlogs for Construction Products Regulation harmonized performance declarations are extending time-to-market for new pressure pipe specifications.
- Legacy infrastructure integration complexity:Socket joint compatibility between new PVC systems and existing asbestos-cement networks requires custom fabrication protocols that strain project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe PVC Pipes Market |
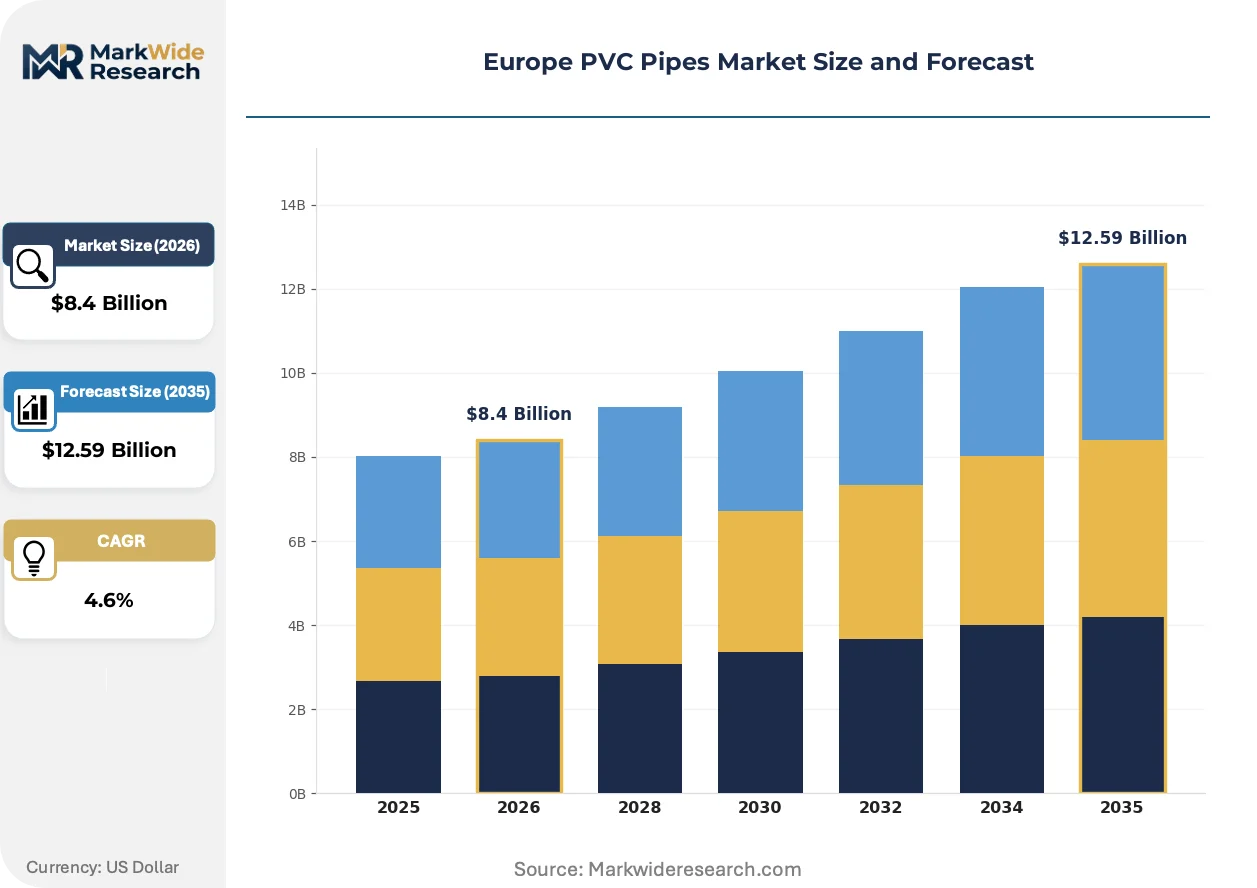
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pipes, Pressure Pipes, Drainage Pipes, Sewage Pipes Application: Construction, Agriculture, Water Supply, Waste Management End User: Residential, Commercial, Industrial, Municipal Size: Small Diameter, Medium Diameter, Large Diameter, Extra Large Diameter |
| Companies Covered | Pipelife International GmbH, REHAU AG + Co, Georg Fischer AG, TUBAOPLAST-CAVINOR S.A., Naylor Industries plc, Wavin N.V., Tessenderlo Group, Genuit Group, Polypipe Group plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe PVC Pipes Market Strategic Shifts & Innovations
Formulation chemistry advances and digital infrastructure requirements are reshaping competitive positioning across extrusion operations, with regulatory compliance costs becoming a selective force on facility investment decisions.
Co-extruded multi-layer pressure pipe architectures incorporating virgin PVC outer skins bonded to recycled-content cores are converging with municipal procurement specifications mandating circular material quotas. Water utilities in the Netherlands and Belgium are piloting these systems for non-potable distribution networks. This technology convergence is compressing price premiums for conventional virgin formulations while creating tiered supplier qualifications based on recyclate traceability systems.
REACH registration obligations are tightening permissible additive chemistries across stabilizer and plasticizer categories, with ECHA's restriction roadmap forcing compounders into calcium-zinc and organic-based alternatives ahead of legacy lead and tin system phase-outs. Extruders serving potable water applications face the steepest compliance gradients. Pressure pipe segments with direct human contact mandates are responding through accelerated Notified Body engagement and anticipatory formulation stockpiling.
Centralized procurement consortia in Germany and Austria are consolidating specification-setting authority previously dispersed across municipal engineering departments, compressing vendor qualification cycles while raising batch documentation requirements. Framework agreements spanning multi-year horizons are displacing project-by-project tendering for trunk infrastructure. This behavioral shift is most visible in large-diameter pressure pipe categories where Pipelife International GmbH has anchored supply contracts through Austrian manufacturing proximity.
Europe PVC Pipes Market Segmentation
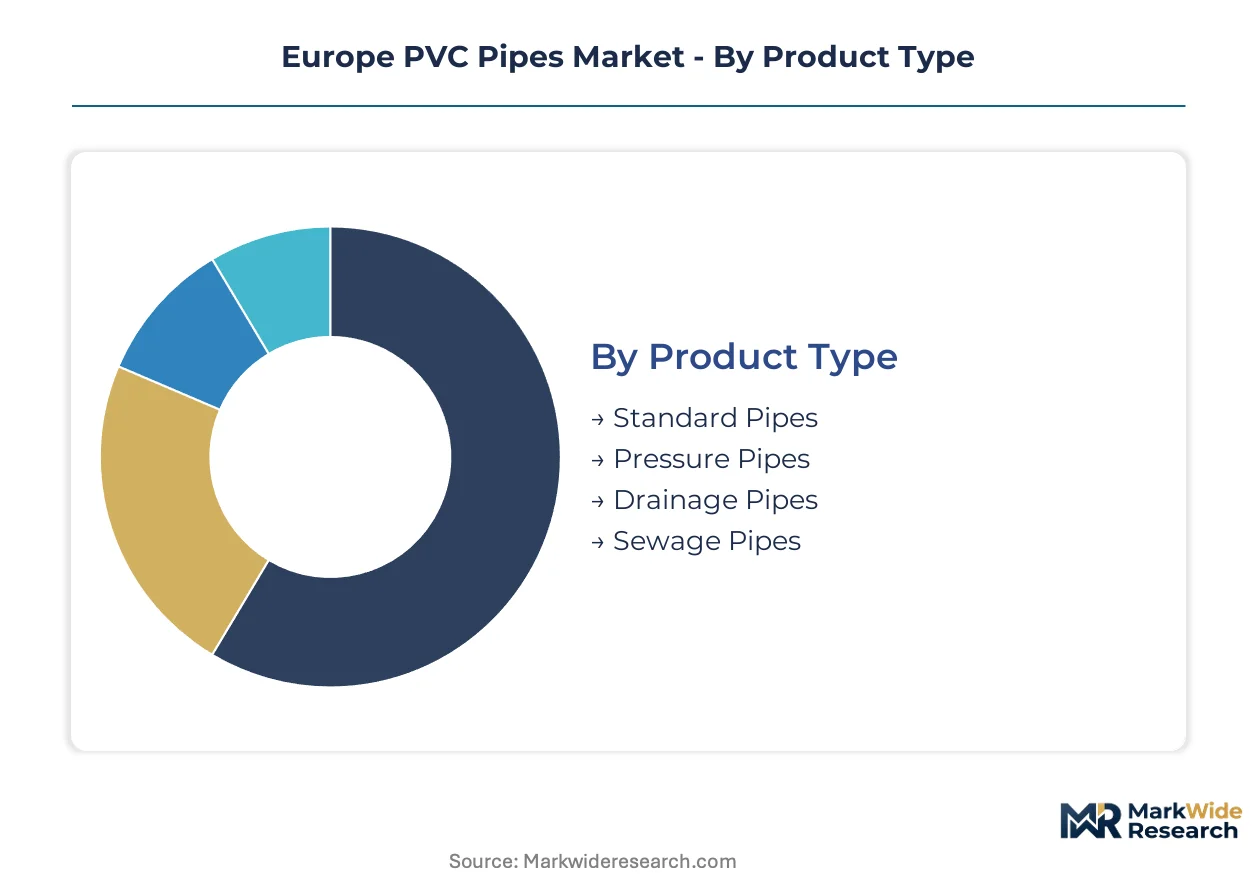
Segmentation in the Europe PVC Pipes Market reveals divergent margin structures across product tiers and application contexts. Procurement specifications vary sharply between municipal infrastructure programs and residential construction, creating distinct competitive arenas for extruders.
Product Type:
Pressure Pipes command premium positioning through stricter safety certification requirements, while Drainage Pipes anchor volume throughput in residential applications.
- Pressure Pipes:Extruded from higher-specification PVC compounds with enhanced stabilizer packages for potable water transmission. Municipal water utilities in Germany and France concentrate procurement of large-diameter formats for trunk infrastructure renewal programs. CE marking under the Construction Products Regulation enforces harmonized performance declarations that elevate compliance costs.
- Drainage Pipes:Manufactured for gravity-flow applications with lower compound specifications and reduced additive loadings. Residential construction across Poland and the Netherlands drives volume absorption, though standardization of small-diameter formats intensifies margin compression. REACH-compliant calcium-zinc stabilizer systems are displacing legacy chemistries in this segment.
- Sewage Pipes:Engineered for deep-burial installations with ring stiffness classes above SN8, commanding specification premiums where municipal mandates apply.
- Standard Pipes:General-purpose extrusions serving non-critical applications with minimal regulatory overlay, competing primarily on unit economics.
Today's leader: Pressure Pipes. Tomorrow's challenger: Sewage Pipes.
Application:
Municipal procurement concentrates in water infrastructure renewal, while agricultural deployment expands through irrigation modernization schemes.
- Water Supply:Transmission and distribution networks for potable water represent the highest-specification application tier. Centralized purchasing consortia in Germany and Austria are consolidating demand volumes for large-diameter pressure pipe systems.
- Construction:Residential and commercial building drainage systems absorb high volumes of small-diameter and medium-diameter formats, with CE marking requirements varying by installation depth and load-bearing specifications.
- Waste Management:Sewage collection and treatment infrastructure demands enhanced ring stiffness formulations for deep-burial resilience.
- Agriculture:Irrigation and drainage networks in Spain and Italy utilize pressure-rated systems for water distribution efficiency.
Water Supply dominates value capture. Construction anchors volume throughput.
End User:
Municipal specifications drive premium tier demand, while residential construction absorbs standardized formats at compressed margins.
- Municipal:Water utilities and sanitation authorities specify certified pressure pipe systems with full batch documentation and recyclate traceability. Framework agreements spanning multi-year horizons are displacing project-by-project tendering.
- Residential:Single-family and multi-unit housing construction consumes drainage and sewage pipes through distributor channels, with procurement decisions driven by contractor price sensitivity.
- Commercial:Office, retail, and hospitality developments require balanced pressure and drainage capabilities with moderate specification complexity.
- Industrial:Manufacturing facilities and processing plants demand corrosion-resistant systems for chemical drainage and process water applications.
Municipal leads specification intensity. Residential leads unit volume.
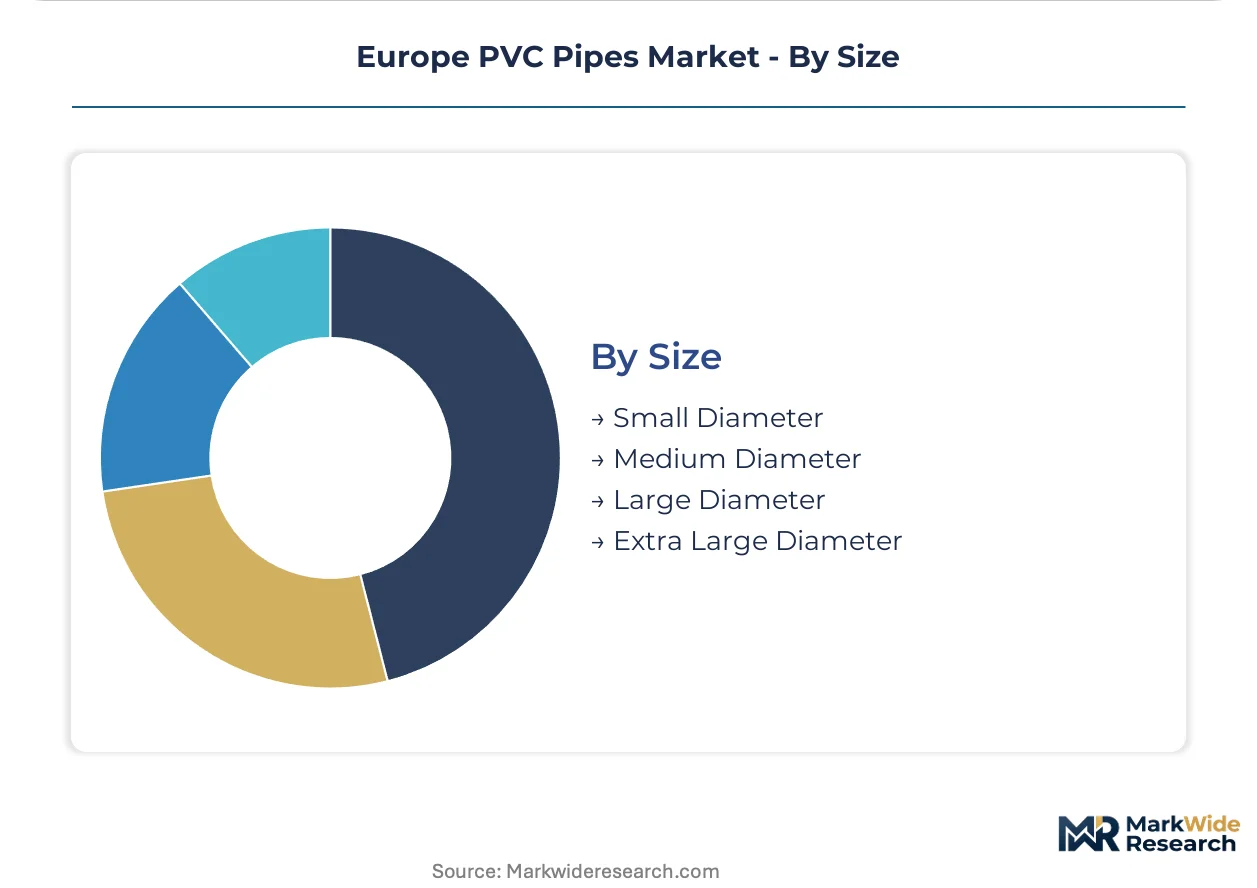
Size:
Large-diameter formats concentrate procurement authority among centralized consortia, while small-diameter pipes distribute through fragmented contractor channels.
- Large Diameter:Pressure-rated trunk infrastructure pipes above 315mm outer diameter serve municipal water transmission networks. Manufacturing proximity to Central European demand centers provides logistics advantages for Austrian and German extruders.
- Small Diameter:Residential drainage and sewage connections below 110mm outer diameter compete through distributor stock-and-sell relationships with minimal technical differentiation.
- Medium Diameter:Distribution mains and building service connections spanning 110mm to 315mm outer diameter balance specification requirements with volume scalability.
- Extra Large Diameter:Specialized trunk infrastructure formats exceeding 500mm outer diameter require dedicated extrusion capacity and project-specific fabrication protocols.
Large Diameter commands procurement consolidation. Small Diameter commands channel fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates municipal procurement authority through centralized water utility consortia, while Poland absorbs volume through residential construction expansion and underpenetrated regional infrastructure networks.
Germany
Municipal water utilities in North Rhine-Westphalia and Bavaria are consolidating large-diameter pressure pipe procurement through multi-year framework agreements. The EU Green Deal's circular economy mandates are tightening recycled-content thresholds for public tenders. Manufacturing clusters in Lower Saxony and Baden-Württemberg are retrofitting extrusion lines for co-extruded multi-layer architectures.
France
Paris and Lyon metropolitan utilities are accelerating trunk infrastructure renewal programs for potable water transmission networks. REACH registration obligations are forcing compounders into calcium-zinc stabilizer reformulations ahead of legacy system phase-outs. Industrial concentration in Auvergne-Rhône-Alpes is shifting toward specialized pressure pipe systems for district heating crossover applications.
Netherlands
Water utilities in the Randstad region are piloting recycled-content PVC formulations for non-potable distribution networks. CE marking under the Construction Products Regulation enforces harmonized performance declarations that elevate compliance barriers. The Eindhoven manufacturing corridor is developing sensor-ready conduit architectures for smart city infrastructure integration.
Poland
Residential construction in Warsaw and Kraków is driving drainage pipe volume absorption through distributor stock-and-sell channels. Municipal water consolidation in underpenetrated regional utilities is creating white space for large-diameter pressure pipe suppliers. Silesian industrial zones are attracting extrusion capacity investments targeting Central European logistics advantages.
Italy
Agricultural irrigation modernization in Emilia-Romagna and Lombardy is expanding pressure-rated system deployment for water distribution efficiency. ECHA's ongoing restriction assessments for legacy stabilizer systems are compressing formulation timelines for compounders serving potable applications. Manufacturing clusters in Veneto are specializing in corrosion-resistant systems for chemical drainage applications.
Europe PVC Pipes Market Key Industry Players
German and Austrian producers anchor the premium-tier municipal procurement vector; Italian and Spanish specialists hold position in agricultural and residential drainage segments. The vendor base organizes around three strategic archetypes: backward-integrated chlor-alkali producers insulating margin structures from feedstock volatility, multi-national extrusion houses leveraging manufacturing proximity to centralized purchasing consortia, and regional specialists capturing distributor-channel volume in fragmented construction markets. Competitive intensity is concentrating through framework agreement consolidation and anticipatory formulation investments ahead of REACH restriction deadlines.
Among German and Austrian-based fabricators, Pipelife International GmbH exemplifies the manufacturing-proximity archetype through Austrian production positioning, REHAU AG + Co occupies a specialist tier for pressure system engineering, and Georg Fischer AG represents backward-integrated feedstock control. These three entities collectively illustrate how geographic anchoring, technical specialization, and upstream integration are reshaping vendor qualification dynamics across municipal tender processes.
| Leading Market Players |
|---|
| Pipelife International GmbH |
| REHAU AG + Co |
| Georg Fischer AG |
| TUBAOPLAST-CAVINOR S.A. |
| Naylor Industries plc |
| Wavin N.V. |
| Tessenderlo Group |
| Genuit Group |
| Polypipe Group plc |
| Others |
Cost & Logistics Intelligence
CE marking tier divergence between municipal pressure pipe specifications and residential drainage commodities manifests in divergent margin architectures across German and Austrian manufacturing clusters. Municipal procurement concentrates pricing power among backward-integrated compounders serving centralized water utility consortia, while distributor-channel drainage pipes compete through unit-cost minimization and logistics proximity to Polish construction markets.
Pricing Analysis
Capacity additions in Poland and Silesian industrial zones are reshaping price floors for small-diameter drainage formats through proximity advantages to residential construction demand. Three-tier pricing structure across CE-certified pressure systems, REACH-compliant standard grades, and unmarked economy extrusions separates municipal framework agreements from contractor spot purchases. Cost compression in drainage segments intensifies as calcium-zinc stabilizer reformulations elevate compound costs without corresponding specification premiums. Residential contractors exhibit highest price sensitivity, while municipal procurement teams prioritize batch documentation and recyclate traceability over unit economics.
Supply Chain Analysis
CE marking and REACH registration obligations gate qualified supplier status for municipal pressure pipe tenders, concentrating extrusion capacity in Germany, Austria, and the Netherlands. Feedstock dependence on chlor-alkali production from Rijnmond and Ludwigshafen complexes, combined with vinyl chloride monomer imports from Belgian crackers, creates exposure to energy cost volatility. Single-source vulnerability emerges where centralized purchasing consortia lock multi-year framework agreements with Austrian-based manufacturers. Distribution runs through water utility procurement departments for large-diameter formats, while drainage pipes flow through building materials distributors serving Polish and Dutch residential contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market hinge on co-extruded multi-layer architectures that monetize recycled-content mandates through premium positioning, while reformulation chemistry expertise scarcity creates defensive moats for early REACH-compliant compounders.
For Market Incumbents: Anticipate ECHA restriction timelines by stockpiling calcium-zinc and organic-based stabilizer formulations ahead of legacy lead system phase-outs. Anchor position through backward integration into chlor-alkali feedstock production to insulate margin structures from vinyl chloride monomer volatility, while embedding sensor-ready conduit architectures during extrusion to capture smart city infrastructure premiums. For New Entrants and Emerging Players: Begin with underpenetrated Polish regional utilities where municipal water consolidation has not yet centralized procurement authority. Target large-diameter pressure pipe specifications requiring CE marking harmonized performance declarations as the most penetrable tier, leveraging manufacturing proximity to Silesian industrial zones and multi-year framework agreement displacement of incumbent Austrian suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where reformulation chemistry expertise scarcity intersects with REACH compliance deadline compression, favoring acquisition of compounders with anticipatory stabilizer investments and established Notified Body relationships. Focus on mid-cap extruders with captive recyclate traceability systems and municipal framework agreement anchoring as priority targets. Watch ECHA restriction assessment announcements as inflection indicators for accelerated vendor qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | Captive vinyl chloride monomer supply insulates margin structures from energy-driven cost volatility. |
| Co-Extruded Multi-Layer Architecture Deployment | Virgin outer skin bonded to recycled-content core meets EU Green Deal circularity procurement mandates. |
| REACH-Compliant Stabilizer Reformulation | Calcium-zinc and organic-based alternatives ahead of ECHA lead system restrictions preserve municipal tender eligibility. |
| Sensor-Ready Conduit Architecture Integration | Embedded leak detection capability positions extruders for smart city infrastructure framework agreements. |
| Centralized Procurement Consortium Engagement | Multi-year framework agreements with German and Austrian water utilities displace project-by-project tendering. |
Research Approach
Bottom-up municipal infrastructure modeling reconciled against top-down extrusion capacity tracking forms the analytical core of this study. Primary interviews with plant managers at German and Austrian manufacturing clusters, procurement leads at centralized water utility consortia, and technical R&D directors at compounder operations combined with secondary validation from ECHA restriction assessment filings, CE marking Notified Body registries, and EU Green Deal circular economy procurement guidelines. Customs data on vinyl chloride monomer trade flows and municipal tender aggregation databases enabled triangulation between supply-side capacity and demand-side specification evolution.
Input-output matrices across pressure pipe, drainage pipe, sewage pipe, and standard pipe categories, segmented by diameter tier and end-use application, drove volume and value projections throughout the forecast period. CAGRs derived from municipal infrastructure renewal pipeline analysis, residential construction permit trajectories, and REACH compliance cost pass-through assumptions. Hydrogen-ready pipeline certification pathways and digital twin integration adoption curves informed scenario-weighted outputs.
Several conditions sit outside the modeled scope, including abrupt ECHA restriction timeline acceleration, municipal budget freezes from macroeconomic shocks, and breakthrough substitution by composite materials in deep-burial sewage applications. Forecasts reflect assumptions on REACH registration compliance rates and circularity mandate enforcement consistency. A model refresh is warranted upon material change in ECHA stabilizer restriction announcements or EU taxonomy alignment requirements for green financing eligibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Polyethylene Pipes Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Industrial Draft Tube Crystallizer Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market