
 Global Copper Pipes and Tubes Market | 2026-2036
Global Copper Pipes and Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Copper Pipes and Tubes Market Foresight
Aftermarket service revenue for installation and maintenance of copper piping networks is rewriting profitability expectations across the value chain. Mueller Industries leverages vertical integration across tube fabrication and brass fitting production to capture margin pools that pure-play manufacturers cannot access. Wieland Group anchors its position through R&D intensity in alloy optimization for corrosion-resistant tubing. Golden Dragon Precise Copper Tube Group dominates volume production of seamless coils for air-conditioning OEMs across Asia.
Copper pipes and tubes are hollow cylindrical conductors fabricated from copper or copper alloys, typically ranging from 6 mm to 273 mm in outer diameter, produced through extrusion, drawing, or welding processes depending on wall thickness and application requirements. Their primary industrial purpose centers on fluid transport, thermal exchange, and gas distribution where copper's thermal conductivity and antimicrobial properties outperform alternative metallic and polymer substitutes. Seamless pipes command premium positioning in high-pressure refrigeration and medical gas systems where joint integrity is non-negotiable, while welded pipes occupy cost-sensitive plumbing and fire protection segments. HVAC systems represent the fastest-growing application dimension as heat pump deployment accelerates across temperate climates, with mechanical contractors driving specification decisions that favor annealed surface treatments for improved bendability during field installation.
The EPA's SNAP program and F-Gas Regulation in Europe are restricting hydrofluorocarbon refrigerants, forcing equipment redesigns that require larger-diameter copper tubing and modified coil geometries to accommodate lower-global-warming-potential alternatives. China's MEE enforces dual carbon goals through updated GB standards that mandate higher efficiency ratings for air-conditioning equipment, directly translating to increased copper intensity per unit of cooling capacity. Japan's METI refrigerant transition roadmap and JIS standards for pressure-rated tubing create parallel compliance obligations for suppliers serving the replacement market. Stakeholders must monitor refrigerant chemistry shifts and corresponding tube diameter specifications to avoid stranded inventory and misaligned capacity investments.
Market Dynamics
The copper pipes and tubes market is being fundamentally restructured by refrigerant chemistry transitions mandated across major economies, forcing simultaneous redesigns of tube diameters, coil geometries, and pressure ratings throughout the HVAC supply chain.
Growth Catalysts
- Heat pump deployment mandates:China's GB standards and MEE enforcement of dual carbon goals are accelerating copper intensity per unit of cooling capacity across residential and commercial installations.
- F-Gas Regulation phase-down:Europe's hydrofluorocarbon restrictions are driving equipment redesigns requiring larger-diameter tubing and modified heat exchanger configurations.
- Southeast Asian manufacturing clusters:Appliance production scaling in Vietnam, Thailand, and Indonesia is concentrating demand for seamless coils and precision-drawn tubing.
Market Restraints
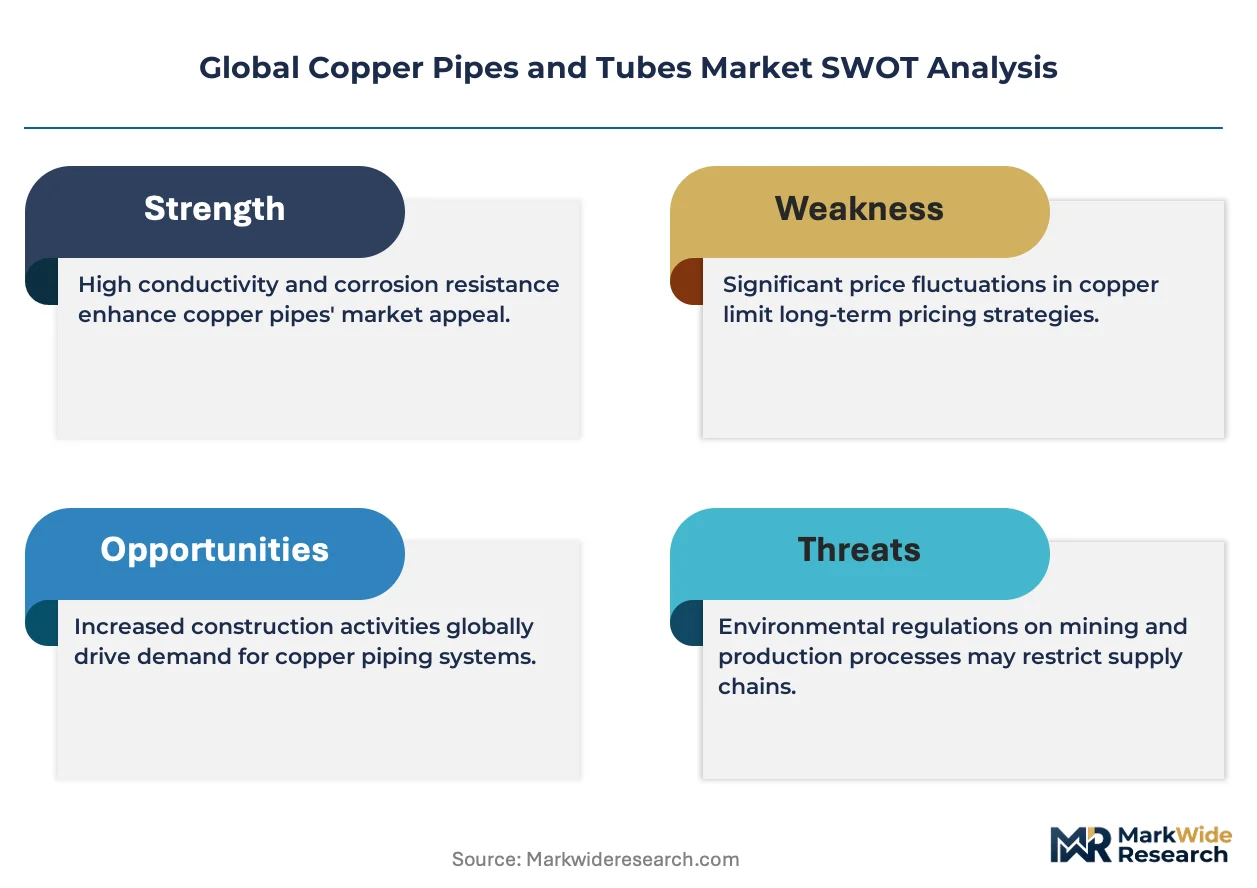
- Copper price volatility:LME copper futures expose fabricators to margin compression when cathode prices spike, forcing hedging costs onto working capital.
- Concentrated smelter supply:Chilean and Peruvian concentrate output disruptions transmit directly to tube mill feedstock availability in Asia and Europe.
- Cross-linked polyethylene substitution:PEX tubing captures residential plumbing share where code authorities permit polymer alternatives for non-potable applications.
Strategic Opportunities
- India's PLI scheme for HVAC components:Domestic manufacturing incentives are creating greenfield capacity opportunities for precision tube suppliers serving the subcontinent's cooling demand.
- Medical gas infrastructure:Hospital construction in the Middle East and Southeast Asia requires antimicrobial copper tubing for oxygen and vacuum systems.
- Refrigerant transition service bundling:Contractors are unbundling installation from equipment sales, creating aftermarket revenue pools for tube replacement and system retrofitting.
Industry Challenges
- Pressure-rated certification timelines:JIS and GB pressure vessel approvals require 12-18 month testing cycles that delay product launches in replacement markets.
- Skilled brazing technician scarcity:Field installation quality depends on certified welders whose training pipelines have not kept pace with heat pump deployment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Copper Pipes and Tubes Market |
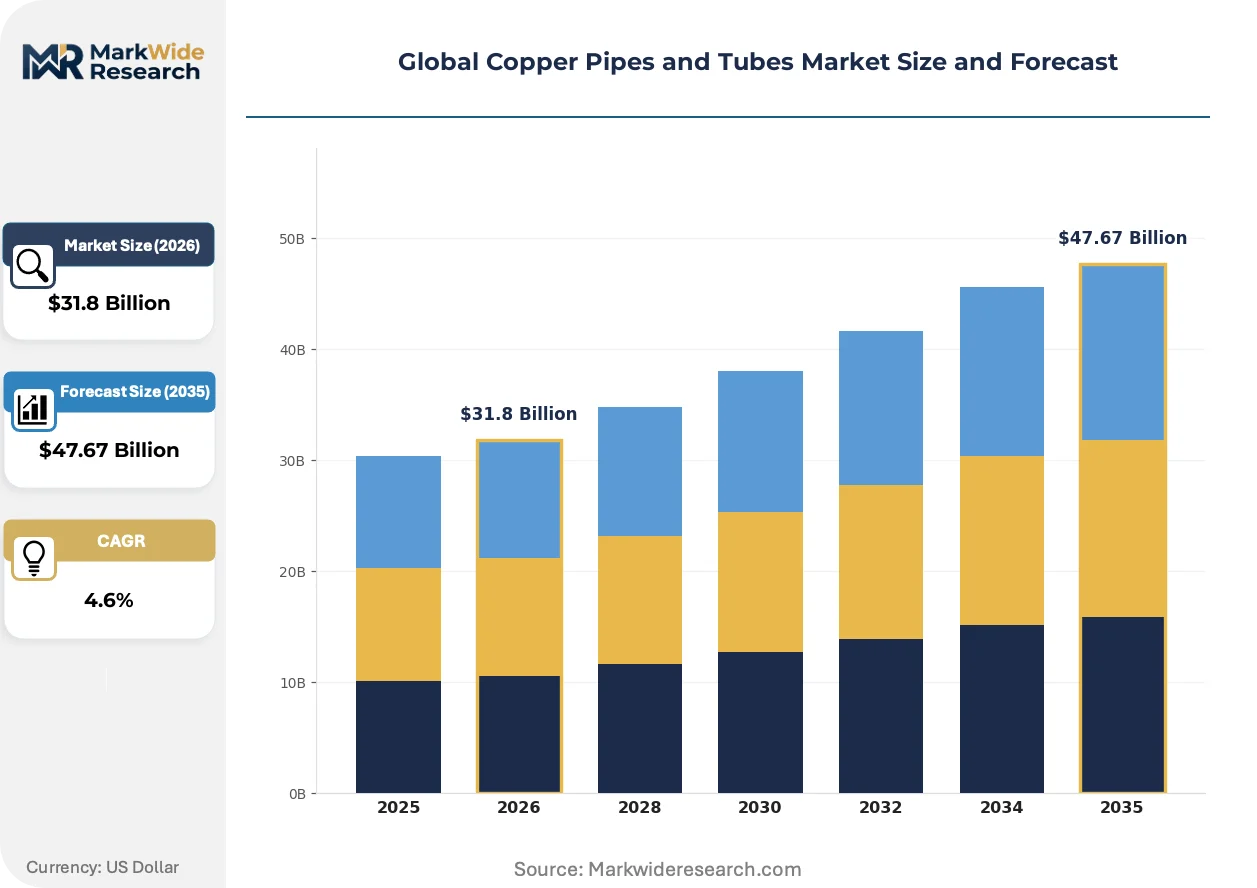
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $47.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Pipes, Welded Pipes, Tubes, Coils, Rods Application: Plumbing Systems, HVAC Systems, Refrigeration, Gas Distribution, Fire Protection End User Industry: Construction Firms, Mechanical Contractors, Appliance Manufacturers, Energy Providers, Marine Fabricators Surface Treatment: Annealed, Electroplated, Cold Drawn, Polished, Coated |
| Companies Covered | KME Group, Cerro Flow Products, Mueller Industries, Cambridge-Lee Industries, Kobe Steel, Wieland Group, Golden Dragon Precise Copper Tube Group, Aurubis, Hailiang Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Copper Pipes and Tubes Market Shifts & Advancements
Digital process control and predictive quality systems are penetrating tube fabrication, while regulatory refrigerant transitions and buyer consolidation are compressing specification cycles across the value chain.
Inline eddy current testing combined with machine vision defect detection is digitizing quality assurance in seamless tube mills. Japanese and German OEMs are mandating digital batch traceability for heat pump coils. This capability compression is eliminating manual inspection stations and reducing warranty claims from field failures.
The EPA's SNAP program restrictions on high-global-warming-potential refrigerants are forcing North American HVAC manufacturers to validate new tube alloys and internal surface treatments for compatibility with R-454B and R-32. Equipment redesigns are expanding demand for larger-diameter drawn tubes that accommodate lower-pressure alternative refrigerants.
Mechanical contractors in the United States are consolidating purchasing through national distribution agreements, displacing regional stocking distributors. This channel compression favors tube mills with direct EDI integration and consignment inventory programs. The shift is most visible in commercial new construction where national HVAC contractors specify approved vendor lists.
Global Copper Pipes and Tubes Market Segmentation
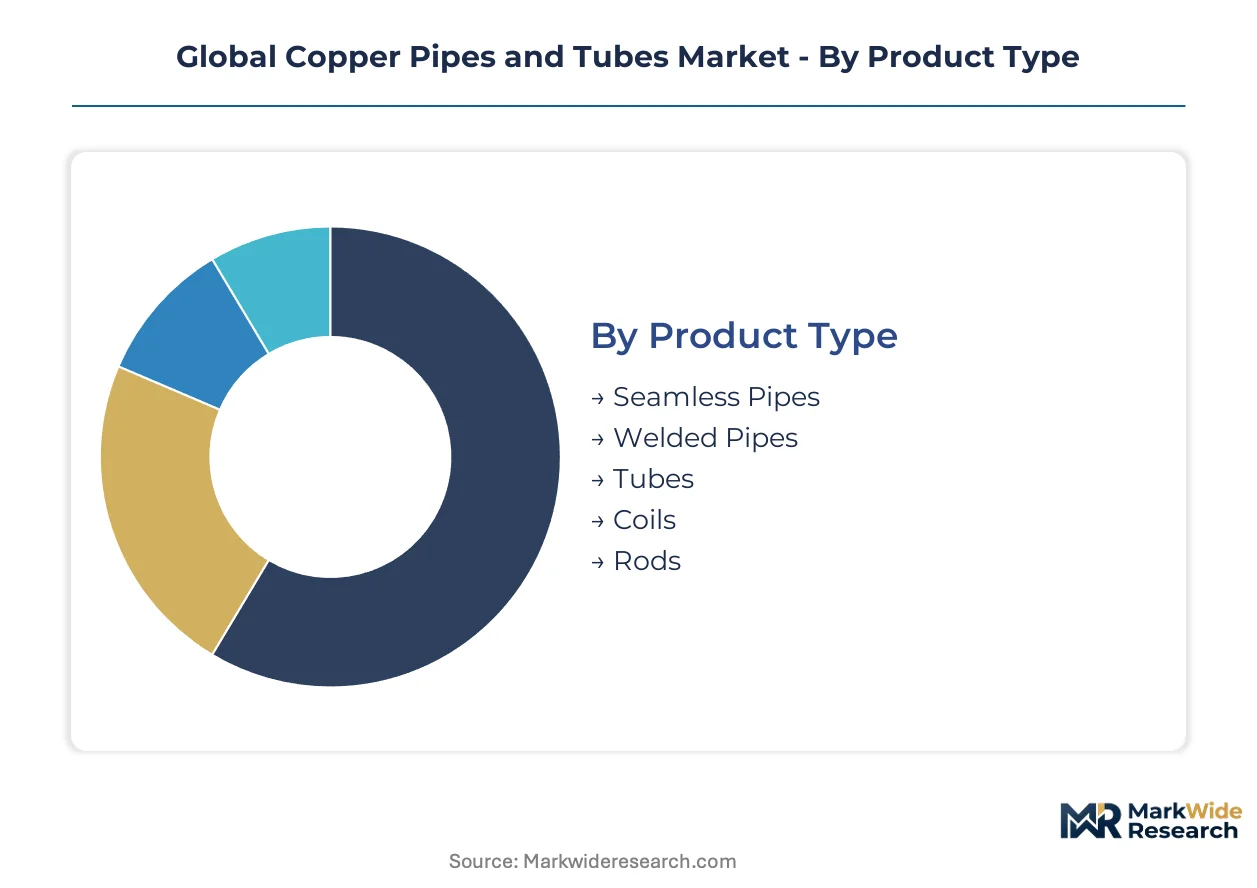
Copper pipe and tube specifications fragment across pressure ratings, surface finishes, and dimensional tolerances that dictate field performance. Procurement decisions in this market hinge on matching product categories to installation constraints and regulatory compliance obligations across HVAC, plumbing, and industrial gas systems.
Product Type:
Mature forming technologies dominate high-volume segments while emerging processes reshape precision applications.
- Seamless Pipes:Extruded and drawn to final dimensions without longitudinal welds, seamless pipes withstand pressure cycling in refrigeration circuits and medical gas networks. Demand concentrates in heat pump manufacturing clusters across China and Japan where GB and JIS pressure vessel standards mandate joint-free construction for safety-critical circuits.
- Welded Pipes:Longitudinally seam-welded from strip stock, these products serve cost-sensitive plumbing and fire suppression installations where pressure requirements stay below 150 psi. Residential construction in Southeast Asian markets drives specification volumes for standard-diameter welded product.
- Tubes:Precision-drawn tubing in straight lengths serves instrumentation and process piping where tight diameter tolerances prevent flow restriction.
- Coils:Continuous annealed coils enable field bending without cracking, dominating air-conditioning line set installations across commercial rooftops.
- Rods:Solid round stock feeds machining operations for fitting bodies and valve components rather than fluid transport.
Seamless pipes handle the majority of throughput; coils are expanding most quickly on share as heat pump deployment accelerates.
Application:
Cost tier stratification separates commodity plumbing from premium thermal exchange systems.
- HVAC Systems:Heat pump coils and refrigerant line sets require annealed copper tubing with internal cleanliness standards that prevent compressor damage. China's MEE enforcement of dual carbon goals through updated GB efficiency standards is directly expanding copper intensity per unit of cooling capacity across residential and commercial installations.
- Refrigeration:Commercial cold storage and transport refrigeration operates on pressure-rated seamless tubing compatible with R-454B and R-32 refrigerants under EPA SNAP restrictions. Equipment redesigns for lower-global-warming-potential chemistry are forcing larger-diameter tube specifications throughout the cold chain.
- Plumbing Systems:Potable water distribution in multi-family construction specifies Type L and Type M drawn tubing where code authorities still prohibit PEX alternatives for certain riser applications.
- Gas Distribution:Natural gas and medical oxygen systems specify cleaned and capped tubing with certified pressure test documentation for joint integrity verification.
- Fire Protection:Sprinkler systems utilize thin-wall welded pipe where standing water pressure requirements remain modest compared to process applications.
HVAC systems command the highest value per kilogram; refrigeration is climbing the fastest as cold chain infrastructure scales.
End User Industry:
Customer type fragmentation creates divergent procurement patterns across project-based and continuous manufacturing demand.
- Appliance Manufacturers:Air-conditioning and heat pump OEMs in Vietnam, Thailand, and Indonesia source precision coils through consignment inventory programs tied to seasonal production ramps.
- Mechanical Contractors:Field installation crews specify annealed coils for bendability during retrofit projects, driving aftermarket replacement demand independent of new equipment sales.
- Construction Firms:Commercial general contractors procure welded pipe through national distribution agreements that displace regional stocking distributors.
- Energy Providers:District heating networks and geothermal installations require corrosion-resistant alloys for buried service lines.
- Marine Fabricators:Shipbuilding yards specify naval brass alloys for seawater cooling systems with enhanced corrosion resistance.
Appliance manufacturers consume the greatest tonnage; mechanical contractors are gaining share fastest through service bundling.
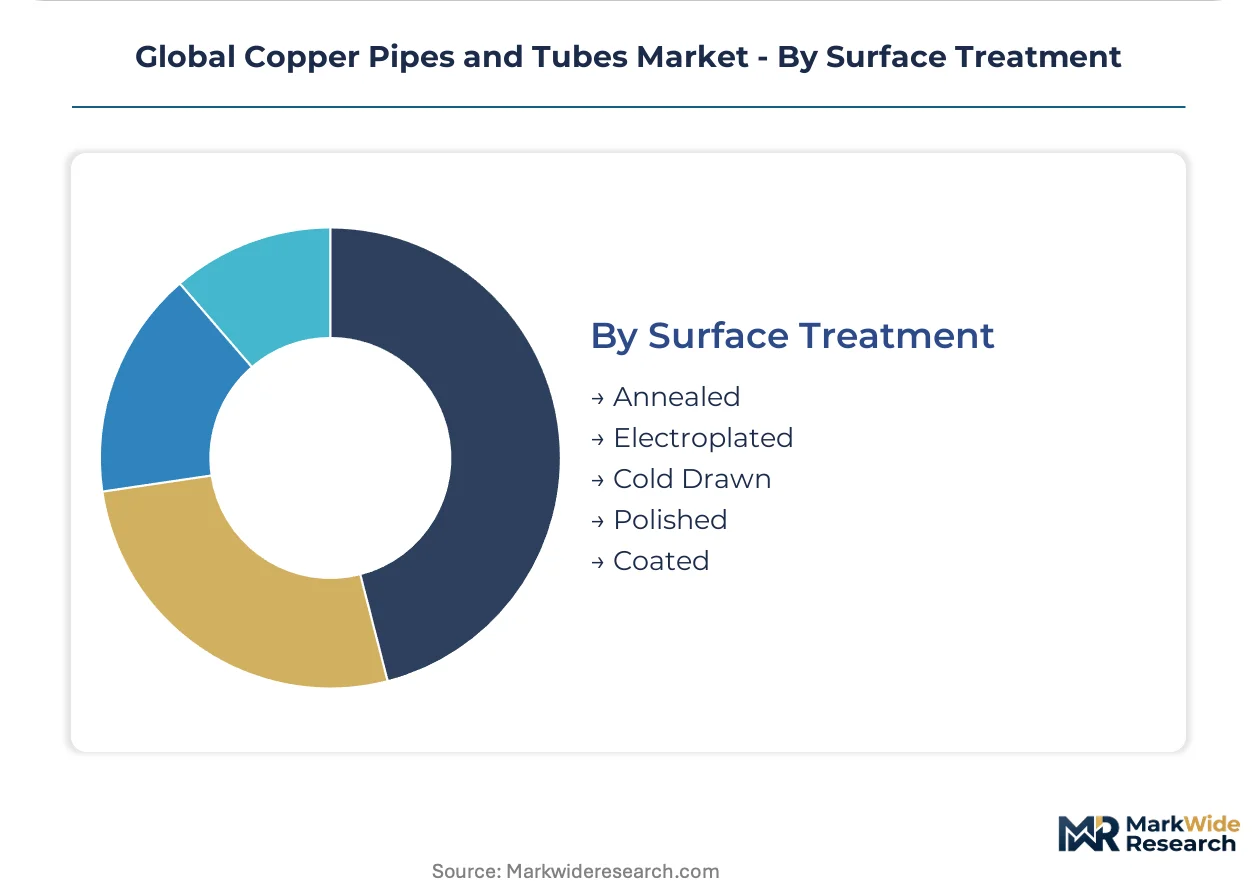
Surface Treatment:
Volume concentration sits with standard mill finishes while margin pools shift toward specialized preparations.
- Annealed:Heat-softened tubing enables tight-radius bending without wall thinning or cracking, essential for field-fabricated HVAC line sets where prefabrication is impractical.
- Cold Drawn:Work-hardened surface finish delivers precise dimensional control for instrument tubing and hydraulic applications.
- Electroplated:Tin or nickel coatings prevent galvanic corrosion in mixed-metal assemblies and aggressive water chemistries.
- Polished:Mirror finishes serve sanitary process piping in pharmaceutical and food equipment where surface roughness controls bacterial adhesion.
- Coated:Polymer or lacquer barriers protect against atmospheric corrosion during extended outdoor storage prior to installation.
Annealed treatment handles the majority of volume; coated products are expanding most quickly for corrosion protection in humid climates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes copper tubing primarily for heat pump manufacturing, while the United States deploys equivalent tonnage through aftermarket service networks for existing building stock. Germany and Japan concentrate demand in precision refrigeration systems, diverging from Southeast Asia's appliance export orientation. India's infrastructure build-out is shifting toward domestic HVAC production, altering traditional import patterns.
China
Heat pump deployment mandates under MEE enforcement of dual carbon goals are accelerating copper intensity per unit of cooling capacity. Updated GB standards for air-conditioning efficiency ratings directly translate to larger-diameter tubing specifications. Manufacturing clusters in Guangdong and Zhejiang provinces are scaling seamless coil production for both domestic installation and export to European heat pump OEMs.
United States
Aftermarket service revenue for copper piping replacement and system retrofitting is expanding faster than new equipment sales. EPA SNAP program restrictions on hydrofluorocarbon refrigerants are forcing equipment redesigns requiring modified tube geometries. Mechanical contractors in Texas and Florida are consolidating purchasing through national distribution agreements that favor direct mill relationships.
Germany
F-Gas Regulation phase-down schedules are driving cold chain infrastructure investments requiring pressure-rated seamless tubing. ECHA compliance obligations for refrigerant chemistry shifts are compressing specification cycles for tube suppliers. Industrial fabricators in North Rhine-Westphalia are developing corrosion-resistant alloys for district heating network expansions.
Japan
METI refrigerant transition roadmaps are creating parallel compliance obligations for pressure-rated tubing in replacement markets. JIS certification timelines requiring 12-18 month testing cycles are delaying product launches for foreign suppliers. Manufacturing concentration in the Chubu region around Nagoya serves precision heat pump coil demand for domestic and Southeast Asian appliance OEMs.
India
PLI scheme incentives for HVAC component manufacturing are creating greenfield capacity opportunities for precision tube suppliers. BIS efficiency mandates for cooling equipment are expanding domestic copper intensity requirements. Industrial corridors in Gujarat and Tamil Nadu are attracting tube mill investments to serve subcontinent cooling demand growth.
Global Copper Pipes and Tubes Market Competitive Landscape
Capability concentration sits with alloy optimization specialists; scale advantage sits with volume producers of seamless coils for appliance OEMs. The vendor base separates into three tiers: integrated fabricators controlling brass fitting production, precision-drawn specialists serving medical and refrigeration applications, and commodity welded pipe producers for construction plumbing. Competitive positioning depends on backward integration into cathode supply and forward integration into distribution networks.
Among integrated fabricators, Mueller Industries exemplifies the margin-capture archetype through in-house production of tube and fitting combinations. Wieland Group occupies a position within the specialty alloy tier, while Golden Dragon Precise Copper Tube Group anchors the high-volume seamless coil segment serving Asian appliance manufacturers. KME Group and Aurubis represent European-based fabricators with smelter integration, whereas Cerro Flow Products and Cambridge-Lee Industries sit within the North American distribution-focused tier. Kobe Steel exemplifies the diversified industrial conglomerate model, and Hailiang Group represents Chinese-scale production capacity.
| Leading Market Players |
|---|
| KME Group |
| Cerro Flow Products |
| Mueller Industries |
| Cambridge-Lee Industries |
| Kobe Steel |
| Wieland Group |
| Golden Dragon Precise Copper Tube Group |
| Aurubis |
| Hailiang Group |
| Others |
Supply & Pricing Matrix
Copper cathode volatility from Chilean and Peruvian concentrate disruptions determines both margin compression severity for tube mills and the geographic clustering of fabrication capacity near Asian smelter networks. LME futures exposure forces fabricators to embed hedging costs into contract structures while concentrating premium pricing power among integrated producers with captive cathode supply.
Pricing Analysis
Long-term offtake agreements dominate procurement between appliance OEMs and seamless coil suppliers, insulating volume buyers from spot cathode spikes while compressing margins for mills locked into fixed-price contracts. Pricing stratifies across premium, standard, and economy tiers based on JIS/GB pressure certification levels and annealed surface treatment quality. Cost compression in the welded pipe segment is intensifying because PEX substitution in residential plumbing constrains pricing power for non-certified producers. Mechanical contractors exhibit highest price sensitivity for standard-diameter line sets, whereas medical gas infrastructure projects demonstrate lowest sensitivity due to antimicrobial specification requirements.
Supply Chain Analysis
Copper concentrate feedstock draws from Chile, Peru, and Indonesian smelter complexes, with cathode output from Chinese and Japanese refineries feeding tube mill operations across Guangdong and Zhejiang provinces. Tube fabrication rests on cathode supply, zinc alloying additions for brass fittings, and polymer coating chemistries for corrosion protection. Single-source vulnerability concentrates in Chilean concentrate disruptions transmitting directly to Asian mill feedstock availability. Distribution runs through national HVAC distribution agreements displacing regional stocking distributors, with consignment inventory programs dominating appliance OEM supply relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerant chemistry transitions mandated by EPA SNAP and F-Gas Regulation are forcing simultaneous equipment redesigns across three continents, compressing specification cycles and rewarding suppliers with rapid alloy validation capabilities.
For Market Incumbents: Harden market position through backward integration into cathode supply and captive brass fitting production that pure-play fabricators cannot replicate. Accelerate JIS and GB pressure vessel certification investments to compress 12-18 month approval timelines before foreign competitors gain replacement market access. Threat substitution from PEX tubing in residential plumbing demands channel control through national distribution agreements that lock out regional competitors. For New Entrants and Emerging Players: India's PLI scheme for HVAC components offers the most penetrable white-space opportunity, with greenfield precision tube capacity attracting domestic manufacturing incentives in Gujarat and Tamil Nadu industrial corridors. Medical gas infrastructure across Middle Eastern hospital construction presents a second entry vector where antimicrobial copper specifications command premium positioning. A go-to-market angle bundling refrigerant transition retrofit services with tube replacement captures aftermarket revenue pools independent of new equipment sales cycles. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors alloy optimization specialists with R&D intensity in corrosion-resistant formulations and rapid refrigerant compatibility validation. Long-term viability centers on suppliers capable of serving dual carbon goal enforcement across Chinese GB standards and European F-Gas phase-down schedules simultaneously. The signal to watch is JIS certification backlog clearance rates as an indicator of which foreign suppliers will unlock Japanese replacement market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Supply | Captive copper concentrate sourcing insulates margin compression from LME volatility spikes. |
| JIS/GB Pressure Vessel Certification Investment | Accelerated testing cycles unlock replacement market access in Japan and China before competitors. |
| Refrigerant Compatibility R&D Program | Alloy validation for R-454B and R-32 chemistry secures specification wins during EPA SNAP redesigns. |
| Consignment Inventory Programs | Direct EDI integration with Vietnamese and Thai appliance OEMs displaces regional distributors. |
| Medical Gas Infrastructure Partnership | Antimicrobial tubing supply agreements with Middle Eastern hospital construction projects build premium positioning. |
Research Methodology
Operator-level perspectives from tube mill procurement directors, HVAC mechanical contractors, appliance OEM supply chain managers, and refrigerant equipment engineers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings from integrated fabricators, and GB/JIS standards documentation from Chinese and Japanese regulatory repositories. Bottom-up volume modeling from individual application segments triangulated against top-down cathode consumption estimates from smelter industry disclosures.
Scenario-bracketing around refrigerant transition timelines and dual carbon goal enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, surface treatment grade, application pressure rating, and regional manufacturing cluster. CAGRs derived from installed base expansion rates for heat pump deployment, cross-referenced against copper intensity per unit of cooling capacity under updated efficiency mandates. Industry-specific forecast inputs incorporated MEE enforcement patterns for Chinese GB standards and EPA SNAP program implementation pacing.
Practitioners should monitor Chilean concentrate supply disruptions, JIS certification backlog clearance rates, and PEX code adoption in residential plumbing for early signals of forecast revision triggers. Forecasts reflect assumptions regarding refrigerant chemistry transition adherence and dual carbon goal enforcement continuity. Material shifts in smelter supply concentration or regulatory phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Global Tracer Wires Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
GRE Pipes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Polyethylene Pipes Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Stainless Steel Plumbing Pipes and Fittings Market
Pipes and Tubes
Galvanized Iron Pipes Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Steel Pipes and Tubes Market