
 Global Butt Weld Fittings Market | 2026-2036
Global Butt Weld Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Butt Weld Fittings Market Analysis
Buyer concentration among downstream petrochemical operators is recalibrating procurement leverage across the supply base. Tenaris leverages integrated seamless pipe and fitting production to capture bundled project awards. Georg Fischer sustains European market presence through advanced automation in stainless steel fabrication. Bonney Forge anchors North American positioning with forged specialty grades for high-pressure service.
Butt weld fittings are permanent pipe connection components manufactured with matching beveled ends for full-penetration welding, typically produced to ASME B16.9 dimensional tolerances and ASTM material specifications for pressure containment integrity. Carbon steel elbows dominate volume shipments across standard pressure classes, while stainless steel reducers command premium positioning in corrosive process environments. Alloy steel tees capture specialized demand in elevated-temperature power generation circuits where creep resistance governs material selection.
ASME Boiler and Pressure Vessel Code, ASTM International material standards, and EU Pressure Equipment Directive shape product certification requirements and market access conditions across manufacturing and import jurisdictions. EPA emissions regulations and OSHA process safety management standards influence end-user maintenance schedules and replacement part demand cycles. Stakeholders must monitor evolving hydrogen infrastructure standards and their implications for fitting material specifications and testing protocols.
Market Dynamics
Integrated seamless pipe producers are consolidating procurement leverage across the Gulf Coast petrochemical corridor, reshaping how project awards flow through the supply base. This concentration is compressing margins for standalone fitting fabricators while rewarding backward-integrated suppliers with bundled contract access.
Growth Catalysts
- ASME B31.3 Process Piping Code Updates:The American Society of Mechanical Engineers expanded corrosion allowance requirements for sour service environments, accelerating replacement cycles in offshore platforms and refineries.
- Hydrogen Infrastructure Deployment:Hydrogen pipeline pilot projects across Germany, the Netherlands, and Japan are generating demand for 316L stainless steel fittings rated for embrittlement resistance at elevated pressures.
- Shale Gas Processing Expansion:Permian Basin NGL fractionation capacity additions are pulling carbon steel elbow and tee volumes through Texas and Louisiana fabrication channels.
Market Restraints
- Nickel Price Volatility:Stainless steel feedstock costs swing with London Metal Exchange nickel futures, compressing margin predictability for alloy fitting producers serving chemical processing clients.
- Chinese Mill Overcapacity:State-subsidized carbon steel fitting exports from Hebei and Shandong provinces are crowding price-sensitive Middle East and Southeast Asian procurement tenders.
- ASME Certification Backlogs:Third-party inspection queue delays at Authorized Inspection Agencies are extending lead times for pressure-boundary components destined for North American power projects.
Strategic Opportunities
- India Petrochemical Buildout:Reliance Industries and Indian Oil Corporation are expanding Jamnagar and Paradip refinery complexes, creating demand for super-duplex stainless steel fittings in desalination and process loops.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in is incentivizing European end-users to source fittings from domestic or low-carbon-intensity suppliers, rewarding electric-arc-furnace-based fabricators.
- Additive Manufacturing Convergence:Powder-bed fusion printing of nickel-alloy geometries is enabling on-demand production of obsolete fitting configurations for maintenance, repair, and operations procurement.
Industry Challenges
- Welding Inspector Certification Scarcity:AWS Certified Welding Inspector credential holders are concentrated among retiring demographics, constraining quality assurance throughput at fabrication shops.
- Legacy ERP Integration Friction:Tier-2 fitting distributors face data migration costs when connecting inventory systems to operator digital-twin platforms for automated reordering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Butt Weld Fittings Market |
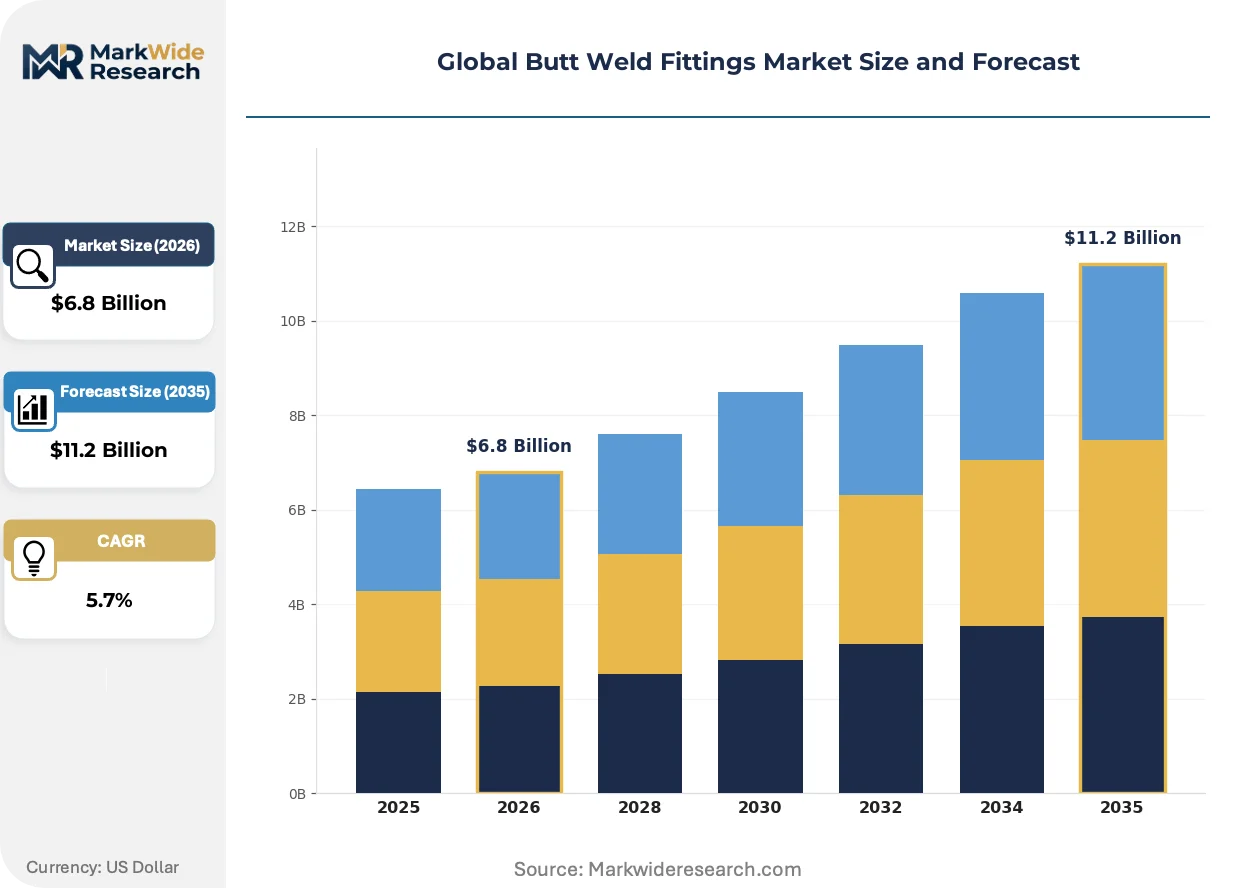
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elbows, Tees, Reducers, Caps Material: Carbon Steel, Stainless Steel, Alloy Steel, PVC End User: Oil & Gas, Power Generation, Water Treatment, Chemical Processing Installation: Onshore, Offshore, Industrial, Commercial |
| Companies Covered | Bonney Forge, Georg Fischer, Swagelok, CCTF, Merit Brass, Tenaris, Aalberts, Olet, Victaulic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Butt Weld Fittings Market Emerging Trajectories
Digital thread technologies are penetrating quality assurance workflows, compressing inspection cycle times while raising traceability requirements across the supply chain. These shifts are redrawing competitive boundaries between automated fabricators and legacy job shops.
Robotic orbital welding systems are automating repetitive pipe spool fabrication in controlled shop environments, reducing rework rates and labor dependency. Offshore fabrication contractors in Singapore and South Korea are deploying these cells at scale for FPSO module construction. The technology is automating skilled welder redeployment toward field installation sites where automation remains technically constrained.
REACH Annex XIV authorization requirements for hexavalent chromium surface treatments are forcing conversion to trivalent passivation chemistries across European stainless steel fitting supply chains. Surface treatment houses in Germany and Italy are absorbing capital costs for process line conversions. High-purity pharmaceutical and semiconductor end-use segments are driving specification tightening fastest, rejecting any residual hexavalent chromium detection in supplier certificates of analysis.
Consolidated procurement portals operated by supermajor oil companies are displacing traditional distributor relationships for standard pressure-class carbon steel fittings. Engineering-procurement-construction firms are routing purchase orders through integrated supply chain platforms that bypass independent stocking distributors. This channel compression is most visible in Saudi Aramco's IKTVA-localized procurement system and similar operator-mandated vendor rationalization programs across the Middle East.
Global Butt Weld Fittings Market Segmentation
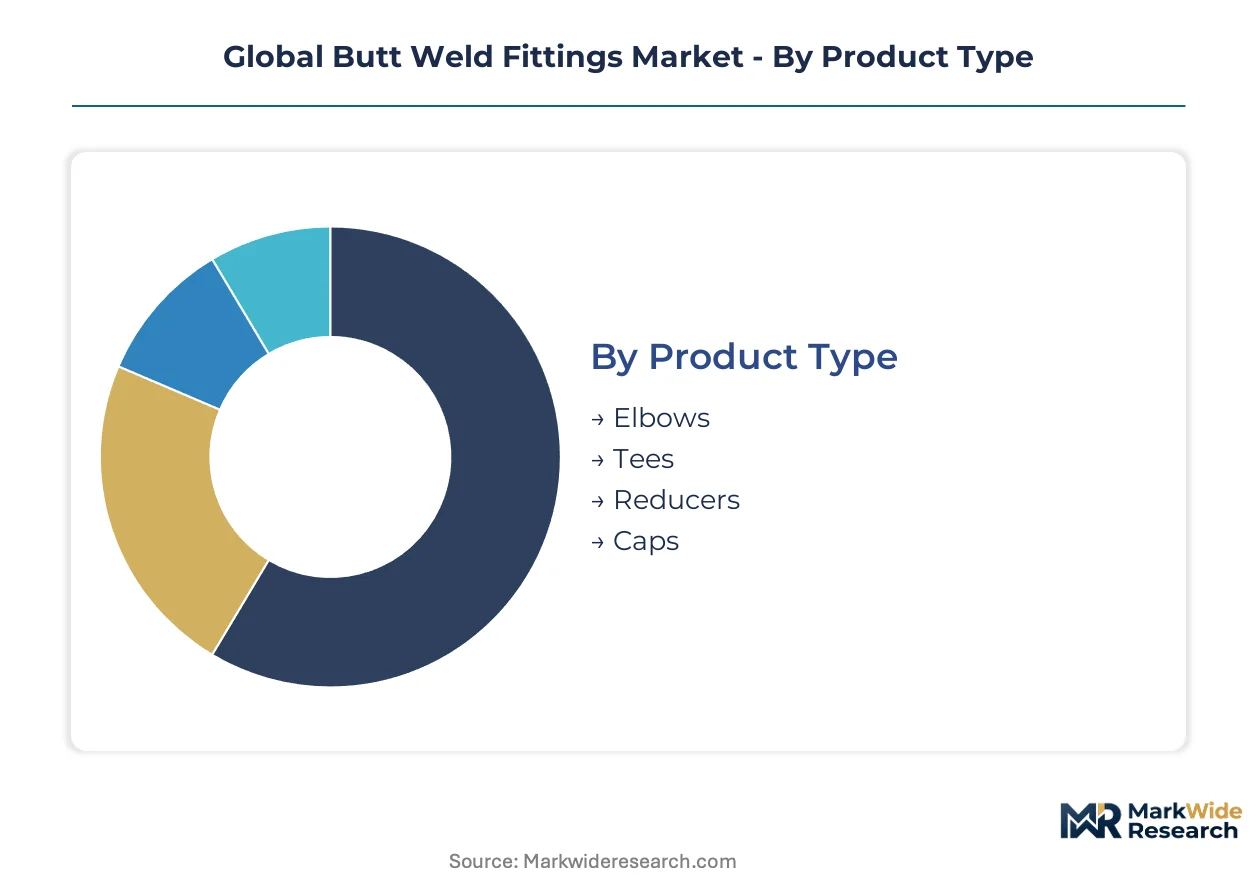
Butt weld fitting specifications diverge sharply across pressure classes, corrosion environments, and welding protocols. Procurement teams segment sourcing strategies to match material performance against total lifecycle cost rather than unit price alone.
Product Type:
Capital intensity clusters in complex geometries requiring multi-axis forging or seamless extrusion capabilities.
- Elbows:Manufactured in 45-degree and 90-degree configurations with long-radius and short-radius geometries per ASME B16.9. Permian Basin shale gas processing plants are absorbing carbon steel elbow volumes for NGL fractionation header systems.
- Tees:Branch connections forged from solid billets or fabricated from welded plate for large diameters. Power generation utilities in Japan specify alloy steel tees for ultra-supercritical steam circuits where creep resistance dominates material selection.
- Reducers:Concentric and eccentric profiles for pipe diameter transitions in process piping.
- Caps:Hemispherical and flat-head closures for pipeline termination and pressure vessel nozzles.
Elbows absorb the bulk of installed capacity; reducers are expanding most quickly in offshore sour service applications.
Material:
Raw material cost tiers separate commodity carbon grades from corrosion-resistant alloys with nickel content premiums.
- Carbon Steel:ASTM A234 WPB specification dominates standard pressure piping with weldability and cost efficiency. Gulf Coast petrochemical corridor operators specify carbon steel for non-corrosive hydrocarbon transport where coating systems provide adequate protection.
- Stainless Steel:304L and 316L grades resist chloride-induced pitting in chemical process environments. German hydrogen pipeline pilot projects are pulling 316L volumes for embrittlement-resistant high-pressure service.
- Alloy Steel:Chrome-molybdenum compositions for elevated-temperature creep resistance.
- PVC:Thermoplastic alternatives for low-pressure corrosive fluid handling in water treatment.
Carbon steel commands the largest fabrication throughput; stainless steel shows the steepest expansion trajectory in hydrogen infrastructure deployment.
End User:
Customer concentration patterns concentrate procurement leverage among integrated energy majors with multi-year framework agreements.
- Oil & Gas:Upstream production, midstream pipelines, and downstream refining operations require pressure-boundary integrity across sour and sweet service classifications. Saudi Aramco's IKTVA procurement system is consolidating vendor bases for standard carbon steel fittings across Saudi Arabia's expansion projects.
- Power Generation:Thermal, nuclear, and renewable energy facilities specify materials for steam cycle efficiency and radiation resistance. Indian thermal power utilities are sourcing alloy steel fittings for ultra-supercritical unit upgrades under CEA efficiency mandates.
- Water Treatment:Desalination and municipal filtration systems specify duplex stainless grades.
- Chemical Processing:Specialty chemical and petrochemical producers demand corrosion-resistant alloys for aggressive process streams.
Oil and gas operators represent the dominant demand pool; power generation is gaining share fastest in Asia-Pacific capacity additions.
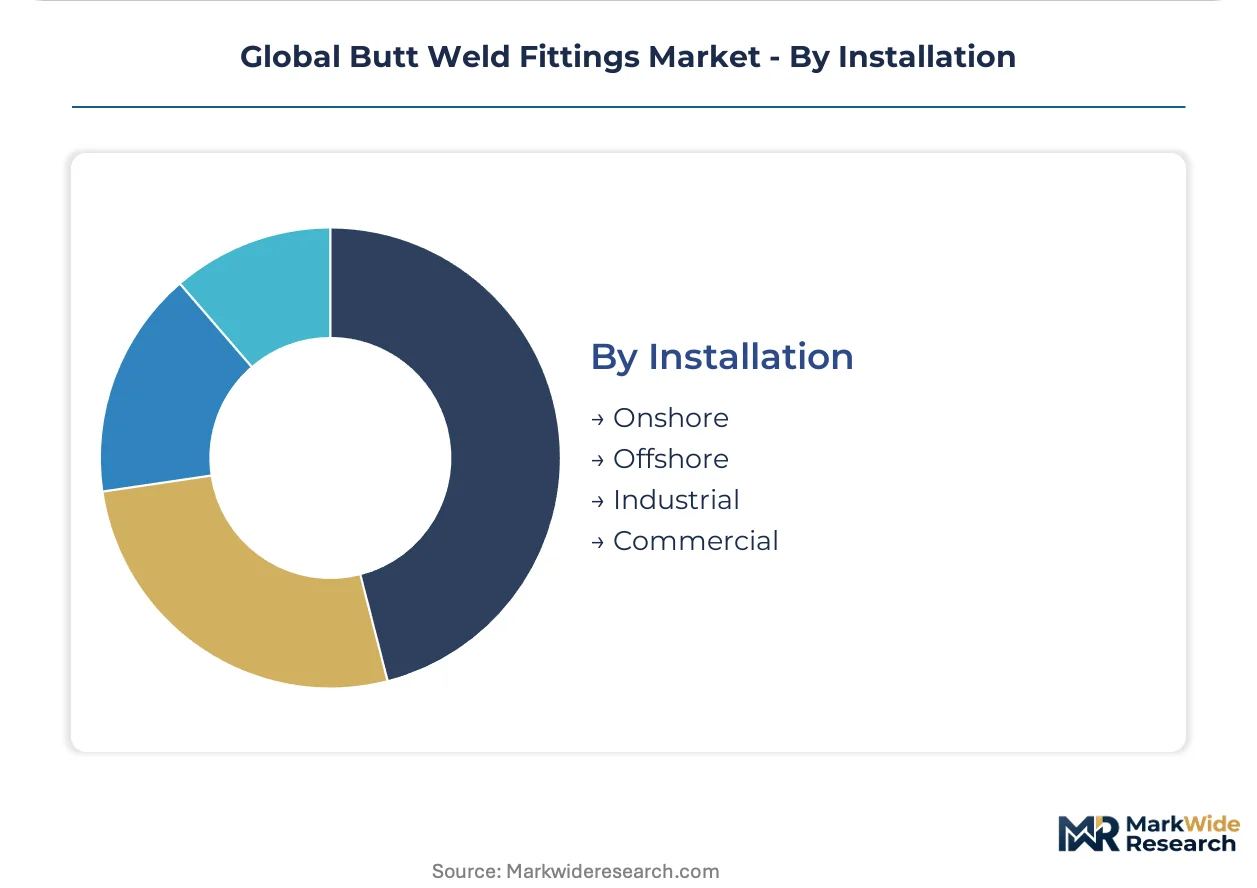
Installation:
Application environments dictate inspection protocols, traceability requirements, and logistics complexity.
- Onshore:Pipeline construction and process plant fabrication in controlled yard environments with automated welding accessibility. US Gulf Coast module fabrication yards are deploying robotic orbital welding cells for carbon steel spool production.
- Offshore:Platform and subsea installations require enhanced toughness specifications and stringent dimensional tolerances for remote welding. Singapore and South Korean fabrication contractors are scaling FPSO module production with pre-fabricated fitting assemblies.
- Industrial:Manufacturing facility process piping with scheduled maintenance windows.
- Commercial:Building services and HVAC applications with lower pressure classifications.
Onshore installations absorb the majority of shipment volumes; offshore applications command the highest specification premiums and quality assurance overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Gulf Coast petrochemical operators concentrate procurement leverage through consolidated framework agreements, pulling carbon steel fitting volumes through Texas and Louisiana fabrication channels. German hydrogen pipeline pilot projects and Indian refinery expansions are redrawing regional demand gravity.
United States
Permian Basin NGL fractionation capacity additions and Corpus Christi LNG export terminal construction are absorbing carbon steel elbow and tee volumes. OSHA process safety management standards influence maintenance schedules and replacement part demand cycles across Gulf Coast process plants. Houston-area module fabrication yards deploy robotic orbital welding cells for carbon steel spool production.
Germany
Hydrogen pipeline pilot projects across the industrial Rhine-Ruhr corridor are generating demand for 316L stainless steel fittings rated for embrittlement resistance. REACH Annex XIV authorization requirements for hexavalent chromium surface treatments force conversion to trivalent passivation chemistries across stainless steel fitting supply chains. Surface treatment houses in North Rhine-Westphalia absorb capital costs for process line conversions.
India
Reliance Industries and Indian Oil Corporation expand Jamnagar and Paradip refinery complexes, creating demand for super-duplex stainless steel fittings in desalination and process loops. CEA efficiency mandates drive Indian thermal power utilities to source alloy steel fittings for ultra-supercritical unit upgrades. Gujarat and Maharashtra industrial corridors concentrate fabrication capacity for domestic project supply.
Saudi Arabia
Saudi Aramco's IKTVA-localized procurement system consolidates vendor bases for standard carbon steel fittings across Kingdom expansion projects. The country's national oil company routes purchase orders through integrated supply chain platforms that bypass independent stocking distributors. Eastern Province industrial cities anchor fabrication capacity for domestic content requirements.
Japan
Power generation utilities specify alloy steel tees for ultra-supercritical steam circuits where creep resistance governs material selection. METI hydrogen infrastructure roadmaps drive demand for embrittlement-resistant fitting specifications. Chubu and Kansai industrial regions concentrate precision fabrication capacity for domestic energy projects.
Global Butt Weld Fittings Market Vendor Landscape
North American fabricators anchor one tier; European specialists hold differentiated positioning in corrosion-resistant alloys. The supply base fragments across seamless pipe producers with captive fitting operations, standalone forging houses, and regional distributors. Three archetypes dominate: backward-integrated seamless pipe producers, stainless steel automation specialists, and forged specialty grade houses. Capacity expansion and vendor rationalization programs represent the dominant competitive moves reshaping procurement channels.
Among the named fabricators, Tenaris, Georg Fischer, and Bonney Forge exemplify contrasting strategic positions. Tenaris represents the backward-integrated archetype leveraging seamless pipe and fitting production for bundled project awards. Georg Fischer occupies a position as a European automation specialist sustaining market presence through advanced stainless steel fabrication capabilities. Bonney Forge anchors North American positioning as a forged specialty grade house for high-pressure service applications. These three companies illustrate how geographic origin and production technology differentiation segment competitive terrain.
| Leading Market Players |
|---|
| Bonney Forge |
| Georg Fischer |
| Swagelok |
| CCTF |
| Merit Brass |
| Tenaris |
| Aalberts |
| Olet |
| Victaulic |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed Chinese producers and family-owned European mid-caps anchor divergent pricing disciplines across carbon steel and alloy fitting tiers. Gulf Coast petrochemical operators exploit procurement leverage through consolidated framework agreements, while stainless steel fabricators pass nickel volatility through to chemical processing clients.
Pricing Analysis
High-volume carbon steel elbows trade on thin margins through contract offtake arrangements, while specialty alloy tees capture premium positioning through ASME certification tiers and embrittlement-resistant material specifications. Three-tier pricing structure across premium super-duplex grades, standard 316L stainless, and commodity WPB carbon separates procurement strategies by corrosion environment and pressure class. Cost compression in standard pressure-class fittings intensifies because Chinese state-subsidized exports crowd Middle East tender markets. Downstream petrochemical operators show greatest price sensitivity on replacement cycles, whereas hydrogen infrastructure developers prioritize material performance over unit cost.
Supply Chain Analysis
Seamless billet supply rests on integrated mills in China, India, and Italy, with specialty nickel-alloy feedstock concentrated among Austrian and German producers. Raw material flows draw from London Metal Exchange-traded nickel, scrap steel recovery networks, and chrome-molybdenum ingot specialists. Single-source vulnerability concentrates in seamless extrusion capacity for large-diameter tees and crosses. Distribution runs through supermajor-operated procurement portals that displace independent stocking distributors across Saudi Arabia, the United States, and select European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic orbital welding systems are displacing manual pipe spool fabrication, compressing labor dependency while raising quality assurance throughput requirements. This technology transition rewards fabricators with automated cell deployment and punishes legacy job shops dependent on retiring welding inspector demographics.
For Market Incumbents: Acquire distressed robotic welding cell assets in Singapore and South Korea to consolidate FPSO module fabrication capacity. Defensive positioning requires backward integration into seamless billet supply and ASME certification investment at Authorized Inspection Agencies to bypass third-party inspection queue delays. Threats from Chinese mill overcapacity and nickel price volatility demand captive raw material sourcing. For New Entrants and Emerging Players: Engineering-procurement-construction firms represent the most penetrable channel partner type for additive-manufactured nickel-alloy fitting geometries serving maintenance, repair, and operations procurement. White-space targets concentrate in obsolete fitting configuration production for legacy pipeline systems and hydrogen infrastructure deployment across Germany, Japan, and the Netherlands. Go-to-market positioning emphasizes on-demand powder-bed fusion printing against traditional forging lead times. For Investors and Strategic Acquirers: Distressed-cycle entries favor electric-arc-furnace-based fabricators with low-carbon-intensity positioning ahead of EU Carbon Border Adjustment Mechanism phase-in. Long-term viability hinges on hydrogen infrastructure material specifications and corrosion-resistant alloy demand from desalination buildouts. Watch ASME hydrogen pipeline code development as the critical inflection indicator for embrittlement-resistant fitting standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seamless Billet Supply | Tenaris and integrated pipe producers capture bundled project awards across Gulf Coast petrochemical corridors. |
| Robotic Orbital Welding Cell Deployment | Singapore and South Korean fabricators reduce rework rates for FPSO module construction. |
| ASME Hydrogen Infrastructure Certification Investment | Early movers secure positioning for 316L stainless embrittlement-resistant specifications in German pilot projects. |
| Additive Manufacturing Capability Buildout | Powder-bed fusion enables on-demand production of obsolete geometries for maintenance procurement. |
| EU Carbon Border Adjustment Mechanism Compliance | Electric-arc-furnace fabricators gain preferential access to European end-user procurement. |
Methodological Framework
Document review covered ASME Boiler and Pressure Vessel Code filings, ASTM International material standards, EPA emissions enforcement records, and EU Pressure Equipment Directive implementation guidance, complemented by interviews with fabrication plant managers, petrochemical procurement leads at Gulf Coast operators, Authorized Inspection Agency technical directors, and distribution channel partners. Secondary validation drew from customs and trade data, SEC 10-K disclosures from listed pipe producers, and project development databases tracking NGL fractionation capacity additions. Bottom-up shipment volume estimates triangulated against top-down petrochemical capital expenditure forecasts.
Segment-level outputs across the projection horizon reflect modeled demand for carbon steel, stainless steel, and alloy grades by pressure class, corrosion environment, and end-use industry. The analytical framework incorporated hydrogen infrastructure deployment timelines, refinery expansion project pipelines, and power generation capacity addition schedules as industry-specific forecast inputs. CAGRs derived from regression analysis against historical shipment correlations with petrochemical fixed asset investment cycles.
Caveats apply where nickel price volatility, Chinese export subsidy policy shifts, or ASME certification backlog resolution could materially shift the outlook. Forecasts reflect assumptions regarding Permian Basin NGL fractionation completion rates and hydrogen pipeline pilot project conversion to commercial scale. A small set of named triggers—London Metal Exchange nickel futures trajectory, Saudi Aramco IKTVA vendor rationalization pace, and EPA process safety management enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
PVC Pipes Market
Pipes and Tubes
Polyethylene Pipes Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Europe Copper Pipes and Tubes Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Cryogenic Pipes Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Stainless Steel Plumbing Pipes Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Saw Pipes Market