
 Hot Dip Galvanized Steel Pipe Market | 2026-2036
Hot Dip Galvanized Steel Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Dip Galvanized Steel Pipe Market Analysis
Modular bundling of corrosion-protection packages is decoupling from standard pipe procurement, forcing buyers to evaluate coating warranties separately from base steel specifications. ArcelorMittal leverages its integrated zinc smelting capacity to control coating cost volatility across European project pipelines. POSCO anchors its competitive position through high-grade automotive-grade galvanizing lines repurposed for industrial pipe exports. Nucor competes via electric arc furnace flexibility, enabling rapid alloy adjustments for custom coating adhesion requirements.
Hot dip galvanized steel pipe consists of carbon steel tubing immersed in molten zinc at approximately 450°C, forming a metallurgically bonded zinc-iron alloy layer typically 50-85 microns thick that provides sacrificial corrosion protection for 50-100 years in atmospheric exposure. The primary commercial purpose centers on extending service life in outdoor structural, fluid conveyance, and foundation applications where replacement costs exceed initial material premiums. Welded pipe configurations dominate volume throughput due to lower per-ton processing energy, though seamless variants command margin pools in high-pressure oil and gas gathering systems where wall uniformity determines safety certification. Water distribution applications sustain the largest end-use footprint, while structural segments in seismic-zone construction are absorbing thicker-coating specifications.
ASTM A53 and EN 10255 standards govern dimensional and coating weight tolerances, with China's SAMR enforcing GB/T 3091 compliance for domestic infrastructure tenders and India's BIS mandating IS 4736 zinc adhesion tests for municipal water projects. EPA stormwater regulations in the United States indirectly shape demand by specifying minimum pipe lifecycles for buried drainage assets. Stakeholders must monitor divergence between regional coating-thickness mandates and the actual corrosion rates recorded in coastal versus inland installations to align inventory specifications with warranty risk.
Market Dynamics
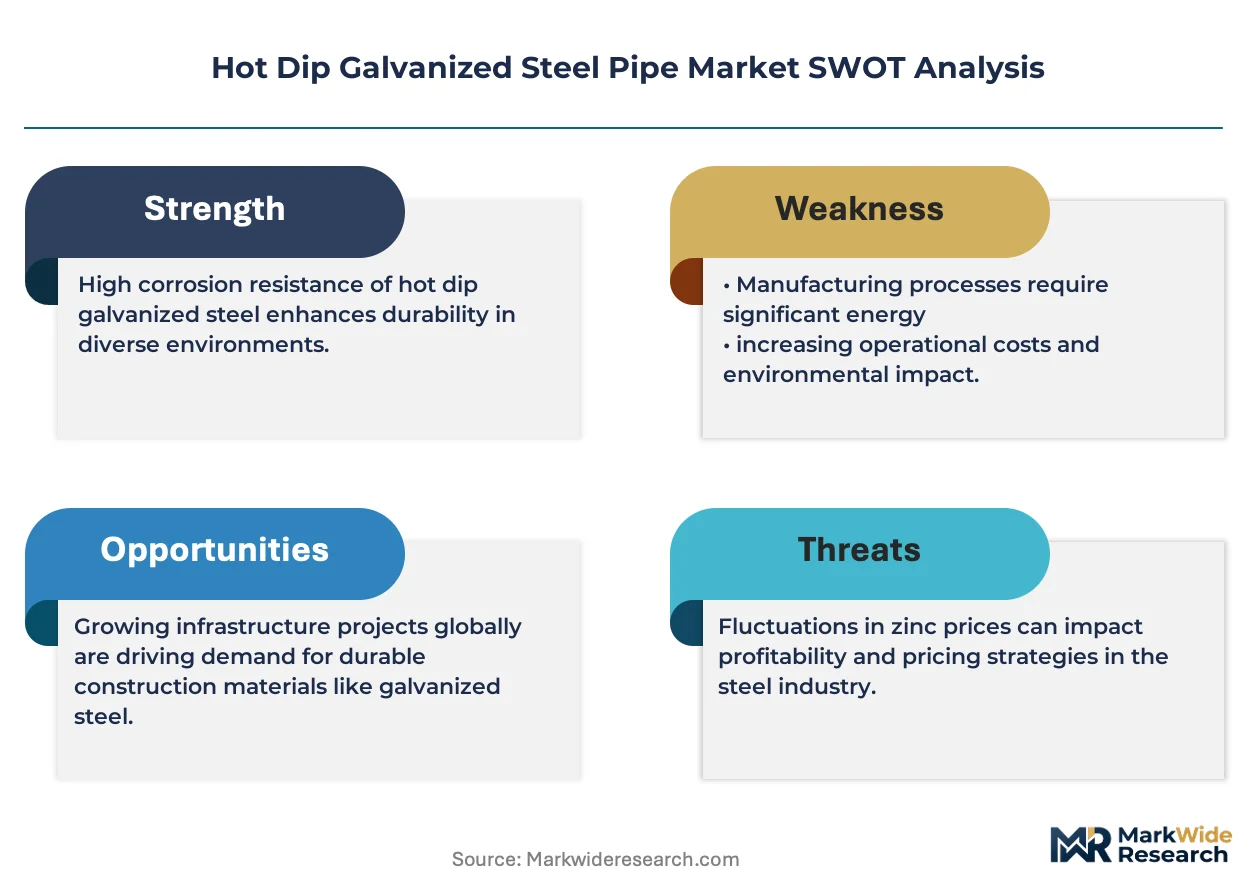
Lifecycle durability mandates are decoupling construction procurement from first-cost optimization, forcing buyers to evaluate total ownership economics against upfront material premiums.
Growth Catalysts
- India's PLI scheme for specialty steel:The production-linked incentive framework redirects public infrastructure procurement toward domestic galvanized pipe manufacturers, accelerating localization of supply chains for water distribution and structural applications.
- EU F-Gas Regulation tightening:Industrial emission thresholds are elevating compliance requirements for coating facilities, advantaging producers with integrated zinc recovery and closed-loop processing capabilities.
- Seismic-zone construction codes:Building authorities in Japan and California are mandating thicker zinc coatings for structural piping, expanding specification tiers beyond standard atmospheric protection grades.
Market Restraints
- Zinc price volatility:Concentration of refined zinc smelting in China and Peru exposes coating cost structures to concentrate supply disruptions and LME price swings.
- Polymer composite substitution:Reinforced thermoplastic piping is capturing share in low-pressure water distribution where burial depth and soil chemistry permit non-metallic alternatives.
- GB/T 3091 compliance divergence:China's domestic coating thickness mandates for infrastructure tenders create technical barriers for exporters meeting ASTM A53 or EN 10255 specifications.
Strategic Opportunities
- Modular corrosion-protection bundling:Warranty unbundling from base steel procurement creates service revenue streams for coating specialists managing lifecycle performance guarantees.
- Automotive-grade galvanizing line repurposing:Excess capacity in high-grade continuous galvanizing is migrating toward industrial pipe exports, elevating surface quality benchmarks.
- Coastal infrastructure replacement cycles:Salt-laden atmospheric exposure in Southeast Asian port expansions is accelerating recoating and replacement demand beyond standard 50-year design lives.
Industry Challenges
- Coating adhesion certification timelines:India's BIS IS 4736 zinc adhesion testing protocols extend qualification periods for municipal water project participation, compressing bidding windows.
- Alloy adjustment capex intensity:Electric arc furnace flexibility requires continuous investment in ladle metallurgy stations to meet custom silicon content specifications for coating bond strength.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Dip Galvanized Steel Pipe Market |
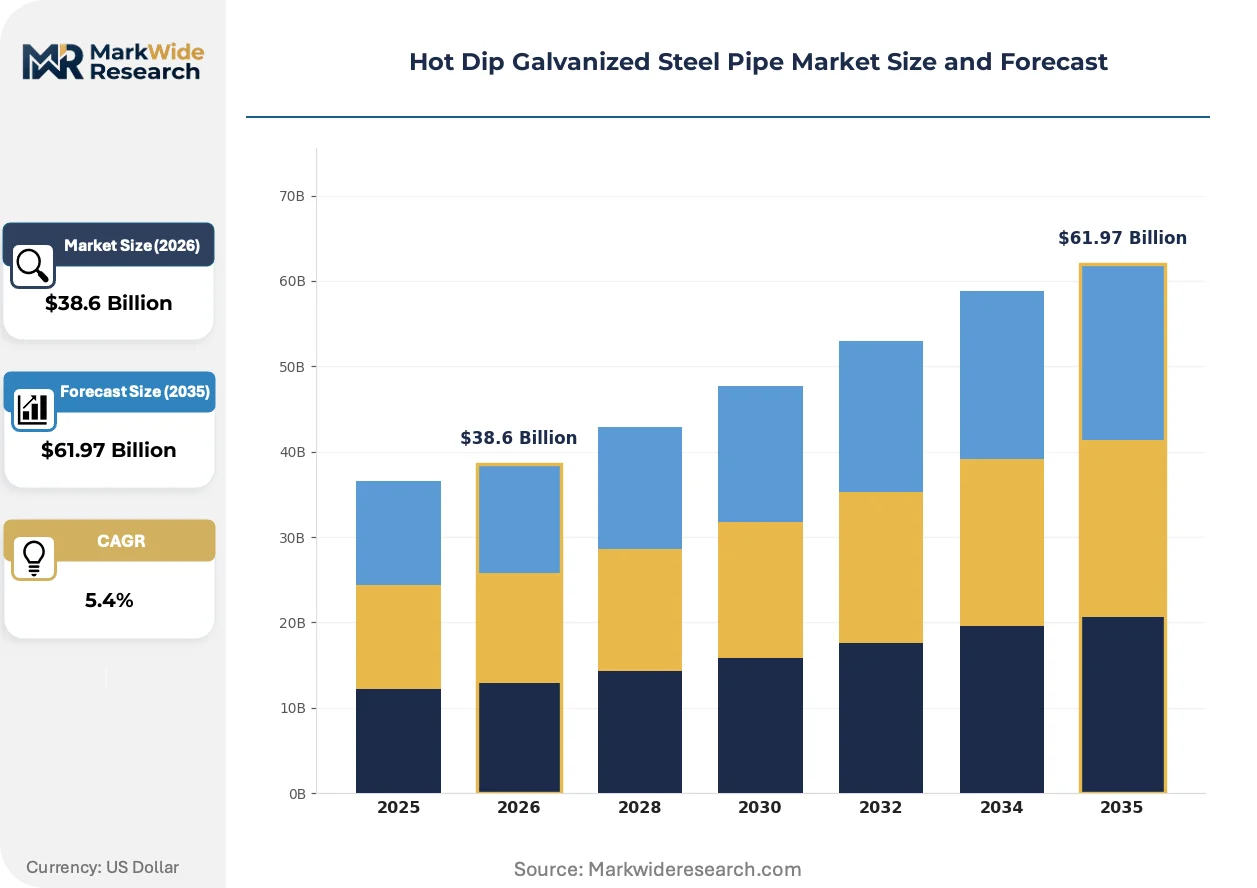
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Welded, Double Submerged Arc Welded, Electric Resistance Welded End User: Construction, Infrastructure, Oil & Gas, Water Supply Application: Water Distribution, Gas Distribution, Structural, Industrial Technology: Hot Dip Galvanizing, Electrogalvanizing, Cold Rolled, Pre-Galvanized |
| Companies Covered | ArcelorMittal, POSCO, Nippon Steel Corporation, United States Steel Corporation, JFE Steel Corporation, Nucor, China Baowu Steel Group, Tata Steel, Tenaris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Dip Galvanized Steel Pipe Market Emerging Trajectories
Digital coating thickness monitoring and predictive corrosion modeling are compressing warranty risk assessment cycles, enabling real-time specification adjustments during project execution.
Inline electromagnetic gauging is integrating with continuous hot-dip lines to provide micron-level zinc layer uniformity data. Water utilities in Germany and Australia are adopting these verification protocols for buried asset management. The technology is integrating quality assurance directly into procurement contracts, reducing post-installation inspection costs.
The EU's F-Gas Regulation is mandating closed-loop fume capture and zinc recovery systems for coating operations above threshold capacity. Industrial facilities in Poland and Italy are retrofitting ventilation infrastructure to meet 2027 compliance deadlines. High-volume exporters to European project pipelines face capital reallocation toward emission-controlled processing.
Buyers are unbundling coating warranties from base steel specifications, creating parallel negotiation tracks for material and protection performance. Municipal procurement departments in Texas and Maharashtra are piloting separate vendor qualification for zinc application versus steel sourcing. This bifurcation is most visible in public infrastructure tenders where lifecycle cost modeling dominates award criteria.
Hot Dip Galvanized Steel Pipe Market Segmentation
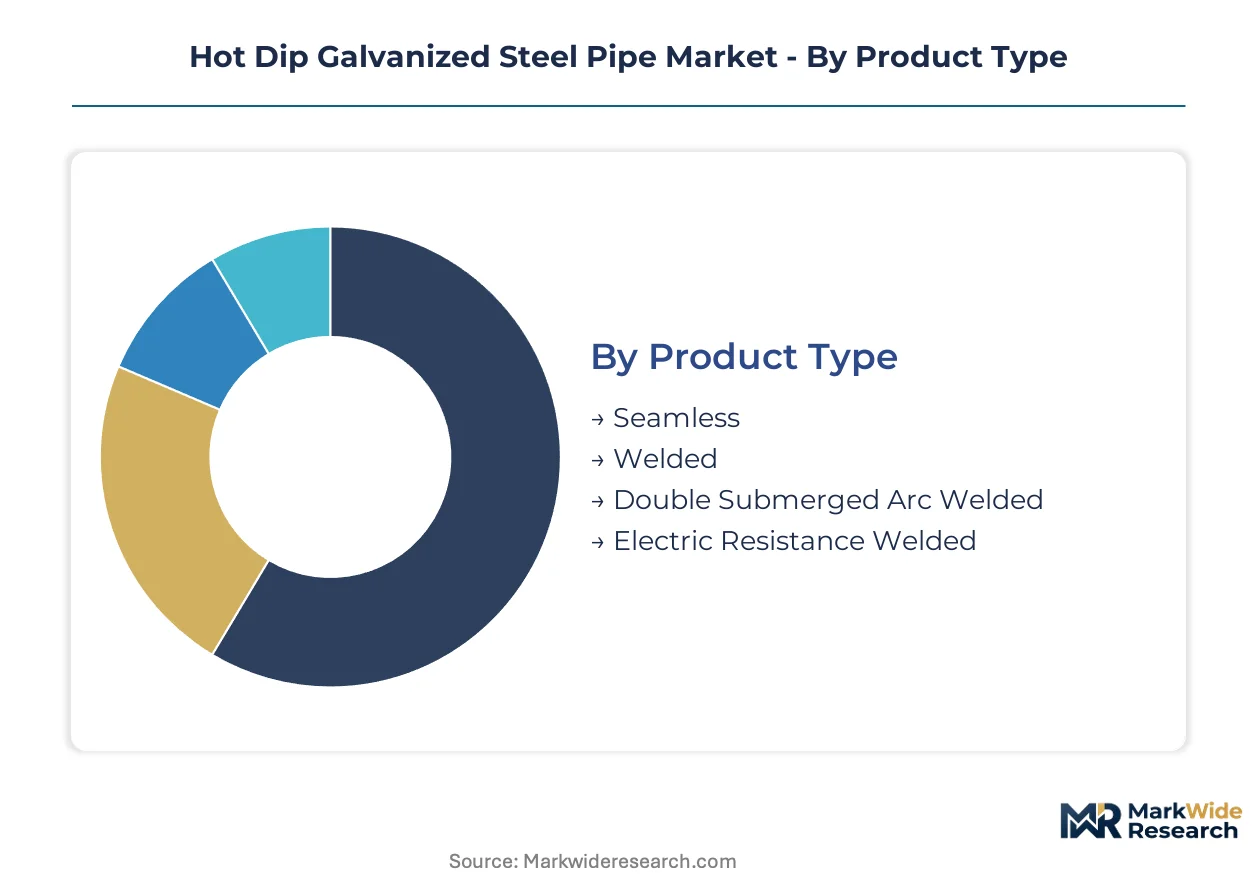
Segmentation in hot dip galvanized steel pipe procurement determines specification tiers that separate lifecycle-critical infrastructure from replaceable assets. Buyers navigate coating thickness, weld integrity, and corrosion resistance grades that align with 50-100 year design horizons versus shorter-cycle commercial applications.
Product Type:
Replacement cycles and pressure requirements dictate product selection, with seamless variants commanding premium positioning in safety-critical installations while welded configurations dominate volume throughput.
- Seamless:Manufactured from solid billets without longitudinal welds, delivering uniform wall thickness for high-pressure containment. Oil and gas gathering systems in the Permian Basin and North Sea anchor demand, driven by API 5L certification requirements for sour service environments.
- Welded:Formed from coiled strip with longitudinal or spiral seams, offering lower per-ton energy intensity in processing. Water distribution networks across India and the United States absorb the majority of welded tonnage, with municipal procurement favoring ASTM A53 compliance for buried asset longevity.
- Double Submerged Arc Welded:Spiral-seam construction with deep penetration welding for large-diameter transmission lines.
- Electric Resistance Welded:High-frequency induction welding for precision dimensional tolerances in mechanical tubing applications.
Volume placements concentrate in Welded configurations; the faster expansion belongs to Seamless as offshore project specifications tighten.
End User:
Cost tier differentiation separates specification-intensive buyers from price-sensitive procurement, with public infrastructure mandates driving coating thickness premiums above commercial construction baselines.
- Construction:Structural framing and foundation piling for commercial and residential buildings, where seismic codes in Japan and California mandate thicker zinc coatings for atmospheric exposure protection. Lifecycle cost modeling in public tenders increasingly weights 75-year replacement avoidance over first-cost savings.
- Infrastructure:Bridges, highways, and port facilities requiring extended service intervals in corrosive environments. India's Dedicated Freight Corridor and Vietnam's port expansions specify 85-micron coating minimums, with BIS and TCVN compliance gates filtering supplier qualification.
- Oil & Gas:Gathering, transmission, and processing infrastructure with sour gas compatibility requirements.
- Water Supply:Municipal distribution and treatment plant piping with potable water certification needs.
Volume placements concentrate in Construction; Infrastructure claims the steepest specification escalation trajectory as coastal exposure mandates proliferate.
Application:
Margin structure follows corrosion severity, with buried and marine exposures commanding coating warranty premiums above standard atmospheric service tiers.
- Water Distribution:Buried potable and non-potable conveyance systems where soil chemistry and stray current exposure determine coating performance. German water utilities leverage inline electromagnetic gauging for micron-level thickness verification, embedding quality assurance directly into procurement contracts.
- Structural:Exposed framing, handrails, and support columns in commercial and industrial facilities. Australia's coastal infrastructure replacement programs specify 100-micron zinc coatings for salt-laden atmospheric exposure, compressing standard 50-year design lives in port-adjacent installations.
- Gas Distribution:Medium and low-pressure urban utility networks with polyethylene transition fitting requirements.
- Industrial:Process piping, conveyor systems, and equipment supports in manufacturing environments.
Volume placements concentrate in Water Distribution; Structural applications are climbing the fastest as seismic code revisions propagate across Pacific Rim construction authorities.
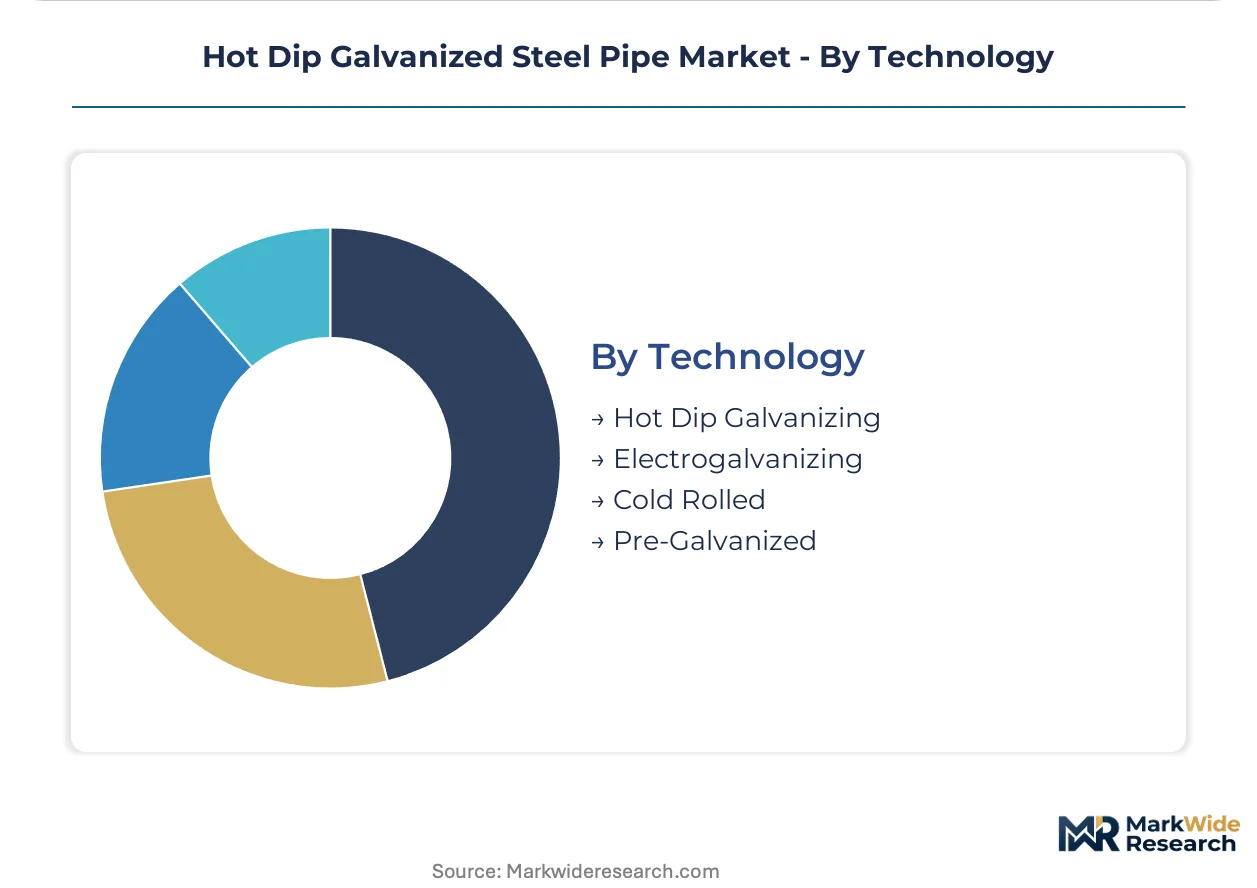
Technology:
Supply concentration in coating capability separates integrated producers from toll-processing dependent competitors, with emission-controlled hot dip lines capturing regulatory-compliant market share.
- Hot Dip Galvanizing:Immersion of cleaned steel in molten zinc at 450°C, forming metallurgically bonded zinc-iron alloy layers. The EU's F-Gas Regulation mandates closed-loop fume capture for facilities above threshold capacity, advantaging Polish and Italian producers with retrofitted ventilation infrastructure.
- Electrogalvanizing:Electrodeposition of thin zinc layers for automotive and precision applications with surface quality requirements.
- Cold Rolled:Forming of uncoated strip for subsequent post-fabrication galvanizing.
- Pre-Galvanized:Continuous coating of coil stock before pipe forming, with seam exposure requiring touch-up protocols.
Volume placements concentrate in Hot Dip Galvanizing; Electrogalvanizing gains share fastest in automotive-grade line repurposing for industrial pipe exports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Dedicated Freight Corridor and port modernization projects concentrate galvanized pipe procurement in infrastructure corridors where the PLI scheme redirects public tenders toward domestic manufacturers.
India
Municipal water distribution networks and Dedicated Freight Corridor construction absorb the majority of regional tonnage. BIS mandates IS 4736 zinc adhesion testing for public infrastructure tenders, compressing supplier qualification timelines. Maharashtra and Gujarat host the densest fabricator clusters, with Mumbai-Pune and Ahmedabad-Vadodara industrial corridors serving as procurement hubs for coastal infrastructure projects.
China
Domestic infrastructure investment and export-oriented manufacturing sustain coating line utilization across the Yangtze and Pearl River Delta regions. SAMR enforces GB/T 3091 coating thickness compliance for state-funded tenders, creating technical barriers for ASTM-certified exporters. Tianjin and Tangshan steel clusters concentrate hot-dip capacity serving both domestic construction and Southeast Asian export pipelines.
United States
Permian Basin oil gathering systems and municipal water replacement programs drive specification-intensive procurement. EPA stormwater regulations indirectly mandate minimum pipe lifecycles for buried drainage assets, elevating coating warranty requirements. Texas and Louisiana host the primary fabrication clusters, with Houston-area processors serving Gulf Coast petrochemical and port infrastructure projects.
Germany
Water utility asset management and industrial plant construction sustain demand for precision-coated mechanical tubing. The EU F-Gas Regulation mandates closed-loop fume capture for coating facilities above threshold capacity, advantaging producers with retrofitted ventilation infrastructure. The Ruhr industrial region and Bavarian manufacturing corridors concentrate emission-compliant processing capacity for Central European project pipelines.
Japan
Seismic-zone building codes and offshore wind foundation projects thicken zinc coating specifications beyond standard atmospheric grades. METI oversees JIS standards compliance for structural applications in high-corrosion environments. The Chubu and Kansai industrial regions anchor domestic production, with Nagoya-Osaka fabricators serving Pacific Rim export markets.
Hot Dip Galvanized Steel Pipe Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across coating capability tiers, with integrated zinc smelting operations separating cost-stable producers from toll-processing dependent competitors. Market structure tilts toward scale-driven consolidation among steel majors with captive galvanizing lines, while regional fabricators occupy specification-niche positions in municipal water and seismic-code segments. Three archetypes dominate: integrated steel-galvanizing conglomerates, coating-specialist toll processors, and electric-arc-furnace flex producers. Capacity expansion and emission-control retrofitting constitute the dominant competitive moves as regulatory deadlines approach.
Among integrated steel majors, ArcelorMittal and POSCO exemplify the smelter-integrated archetype controlling coating cost volatility through captive zinc supply. Nucor occupies a position within the electric-arc-furnace flex tier, enabling rapid alloy adjustments for custom coating adhesion requirements. These three anchors represent divergent strategic postures: European integrated control, Asian high-grade line repurposing, and North American furnace flexibility.
| Leading Market Players |
|---|
| ArcelorMittal |
| POSCO |
| Nippon Steel Corporation |
| United States Steel Corporation |
| JFE Steel Corporation |
| Nucor |
| China Baowu Steel Group |
| Tata Steel |
| Tenaris |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance mandates gate qualified supply access and premium-tier pricing power, as emission-controlled coating facilities capture specification-intensive procurement while toll-dependent processors face margin compression from retrofit capital requirements.
Pricing Analysis
Margin tightening in standard-grade welded pipe reflects zinc price volatility from Chinese and Peruvian smelting concentration. Three-tier pricing structure across API-certified seamless, ASTM A53 municipal-grade welded, and economy commercial framing separates specification premiums. Cost-down pressure on economy tiers accelerates because polymer composite substitution captures low-pressure water distribution share. Municipal procurement departments show least price sensitivity due to lifecycle cost modeling mandates.
Supply Chain Analysis
Refurbishment flows from coastal infrastructure replacement cycles in Vietnam and Australia feed secondary zinc recovery streams, extending raw material circularity. Primary supply concentrates in China, India, and Japan, with Tianjin-Tangshan and Mumbai-Pune clusters anchoring hot-dip capacity. Coating operations draw from refined zinc ingots, carbon steel coil, and flux chemicals, exposing cost structures to LME price swings. Single-source vulnerability in Peruvian zinc concentrate creates supply chain risk. Distribution runs through project-specific direct contracting for infrastructure pipelines and distributor networks for commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emission-compliant coating capacity scarcity props pricing power, as EU F-Gas Regulation deadlines compress qualified supplier pools and extend lead times for infrastructure procurement.
For Market Incumbents: Acquire closed-loop fume capture infrastructure to defend specification-compliant market share against emerging toll processors facing 2027 retrofit deadlines. Consolidate zinc smelting backward integration to isolate coating cost volatility from LME swings. Prioritize BIS IS 4736 certification investment for India's Dedicated Freight Corridor procurement gates. For New Entrants and Emerging Players: Begin with automotive-grade galvanizing line repurposing for industrial pipe exports, targeting Germany and Australia's precision-coated mechanical tubing white space. Maharashtra's municipal water replacement programs offer the most penetrable geography. Pursue separate vendor qualification for zinc application versus steel sourcing as procurement departments unbundle coating warranties. For Investors and Strategic Acquirers: BIS adhesion testing protocol expansion is the leading indicator that India's infrastructure localization will accelerate domestic manufacturer valuation premiums. Five-to-ten year viability favors integrated steel-galvanizing conglomerates with captive zinc supply over toll-processing specialists. Monitor EU F-Gas Regulation enforcement actions as inflection signal for emission-compliant capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Smelting | ArcelorMittal's captive supply isolates coating cost volatility from LME price swings. |
| Emission-Controlled Capacity Expansion | Polish and Italian retrofitting investments capture EU F-Gas Regulation-compliant market share. |
| Automotive-Grade Line Repurposing | POSCO's high-grade continuous galvanizing elevates surface quality benchmarks for industrial exports. |
| Modular Corrosion-Protection Bundling | Separate warranty negotiation tracks create service revenue streams for coating specialists. |
| Electric Arc Furnace Flexibility Investment | Nucor's ladle metallurgy stations enable rapid silicon content adjustments for custom coating adhesion. |
Methodological Framework
Independent corroboration across coating facility operators, municipal procurement officers, and zinc smelting executives underwrites the qualitative findings in this analysis. Primary interviews with plant managers at hot-dip galvanizing lines, procurement leads at water utilities, distribution channel partners in industrial corridors, and technical R&D directors for coating adhesion protocols combined with secondary validation. Secondary sources include customs and trade data for steel pipe flows, SEC 10-K filings from integrated steel majors, BIS certification registries, and EU emission compliance databases. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical coating line utilization and infrastructure tender awards structured the forecast window across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry, application corrosion severity, coating technology compliance level, and regional regulatory cluster. CAGRs derived from regression analysis against zinc price elasticity and infrastructure investment cycles. Industry-specific inputs incorporate BIS qualification timelines and F-Gas Regulation compliance thresholds.
Underlying measurement precision varies by segment; emission-compliant capacity and API-certified seamless pipe carry tighter precision than economy commercial framing. Forecasts reflect assumptions about regulatory enforcement continuity and infrastructure budget allocation patterns. Practitioners should monitor BIS testing protocol expansion and EU F-Gas retrofit completion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Stainless Steel Welded Pipes Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Global Tracer Wires Market
Pipes and Tubes
Global Hydraulic Thermoplastic Hose and Couplings Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Industrial Draft Tube Crystallizer Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
Steel Tubes Market