
 Solar Testing Equipment Market | 2026-2036
Solar Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Testing Equipment Market Analytics
IEC 61215 qualification for crystalline silicon terrestrial photovoltaic modules is bifurcating the competitive landscape into certified laboratory providers and field-service specialists. TÜV Rheinland leverages its accredited testing network across multiple continents to anchor premium certification contracts. Keysight Technologies specializes in precision electrical characterization instruments that dominate R&D procurement cycles. Chroma ATE Inc. competes on automated solar simulator production lines with integrated IV curve tracing capabilities.
Solar testing equipment comprises instruments that measure photovoltaic conversion efficiency, spectral response, and long-term degradation under simulated or natural irradiance conditions, typically operating across 200–1200 nm wavelength ranges with uncertainty budgets below ±2%. These systems enable manufacturers to verify module output before warranty-backed deployment and allow installers to validate field performance against nameplate ratings. Product type segmentation shows solar simulators capturing the largest revenue pool due to capital intensity, while IV curve testers represent the fastest-expanding category driven by utility-scale commissioning protocols. End user demand concentrates among certification bodies facing backlog pressures from IEC standard revision cycles, with research institutions occupying a narrower but higher-margin niche for next-generation cell architectures.
FDA oversight applies to medical-grade photovoltaic applications, while EPA guidelines influence end-of-life testing protocols for cadmium telluride thin-film modules in the United States; Europe's REACH and RoHS frameworks restrict hazardous substances in testing instrument components, reshaping supplier qualification requirements. India's BIS mandates compulsory registration for imported solar testing equipment under its electronics and IT goods order, creating localized calibration obligations. Stakeholders must monitor evolving IEC standard drafts and regional certification reciprocity agreements to anticipate equipment refresh cycles and geographic market entry sequencing.
Market Dynamics
Utility-scale solar farm developers are tightening procurement specifications for IEC 61215 validation systems as module warranty periods extend beyond 25 years, forcing equipment suppliers to recalibrate uncertainty budgets and accelerate certification throughput.
Growth Catalysts
- China's Manufacturing Concentration:Photovoltaic module production clustering in Jiangsu and Anhui provinces is pulling metrology equipment demand toward East Asian calibration hubs with localized service capabilities.
- REACH Substance Restrictions:Europe's RoHS and REACH frameworks are mandating hazardous substance testing in cadmium telluride thin-film modules, expanding end-of-life protocol instrumentation requirements.
- Perovskite Tandem Cell R&D:Next-generation cell architecture development is driving spectral response measurement demand across 300-1200 nm ranges with sub-1% uncertainty requirements.
Market Restraints
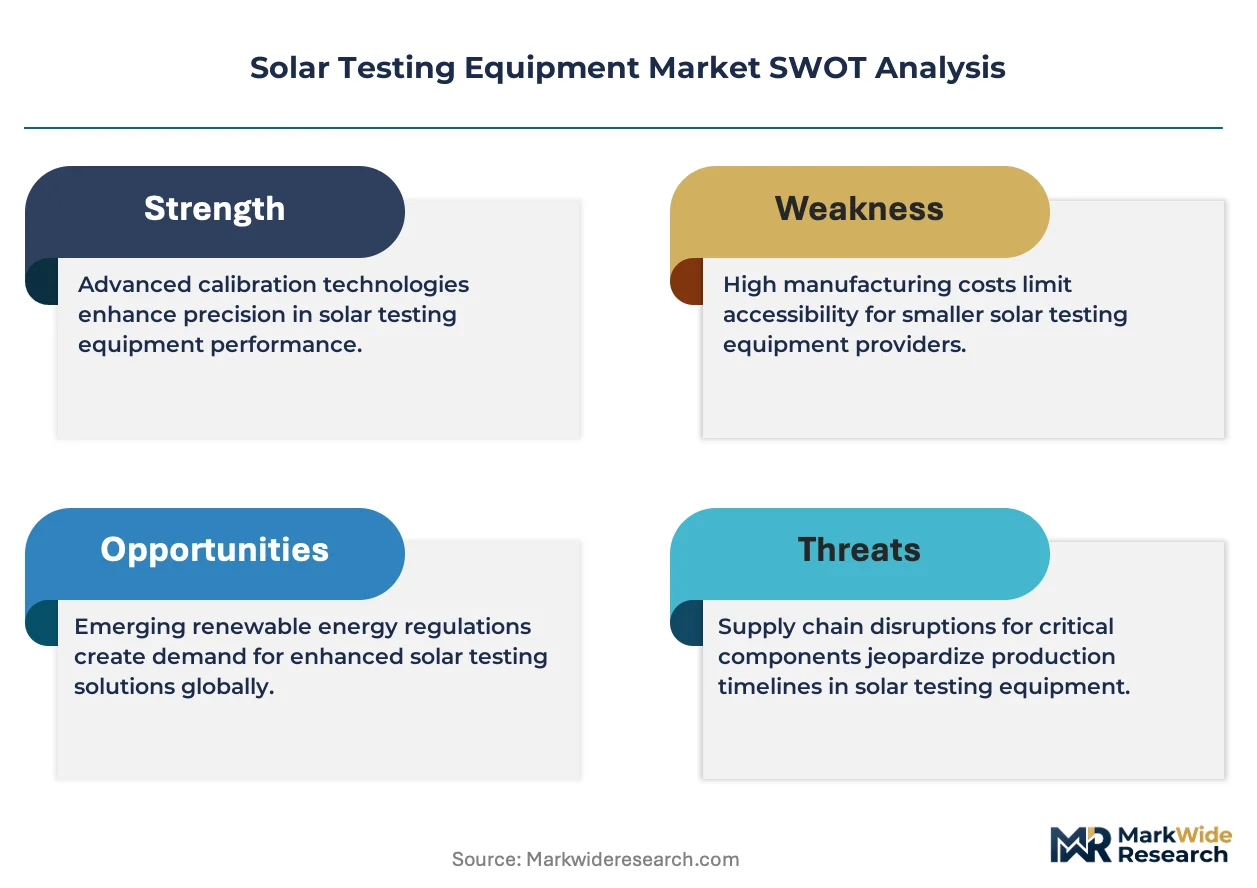
- Xenon Lamp Supply Concentration:Solar simulator light source manufacturing concentrates among Japanese and German specialty lamp producers, creating input cost volatility and lead time exposure.
- Accreditation Backlogs:IEC 61215 revision cycles are stretching TÜV Rheinland and DEKRA certification queues beyond 18 months, compressing equipment utilization rates for laboratory providers.
- Field-Service Substitution:Portable IV curve testers with cloud-based analytics are displacing laboratory-based flash testing for post-installation validation, threatening capital-intensive simulator demand.
Strategic Opportunities
- India's BIS Localization Mandate:Compulsory registration for imported electronics under the electronics and IT goods order is creating captive calibration infrastructure demand among domestic certification bodies.
- Agrivoltaic Dual-Use Arrays:Bifacial module testing under variable albedo conditions is emerging as a specialized application requiring multi-irradiance sensor configurations.
- AI-Integrated Defect Detection:Machine vision convergence with electroluminescence imaging is enabling automated micro-crack identification at production-line speeds.
Industry Challenges
- Spectroradiometer Calibration Expertise:Shortage of technicians capable of maintaining NIST-traceable spectral irradiance standards is constraining laboratory expansion timelines.
- Legacy Simulator Retrofit Complexity:Upgrading 10-year-old steady-state solar simulators to meet updated IEC 60904-9 Class A+ uniformity specifications requires complete optical bench replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Testing Equipment Market |
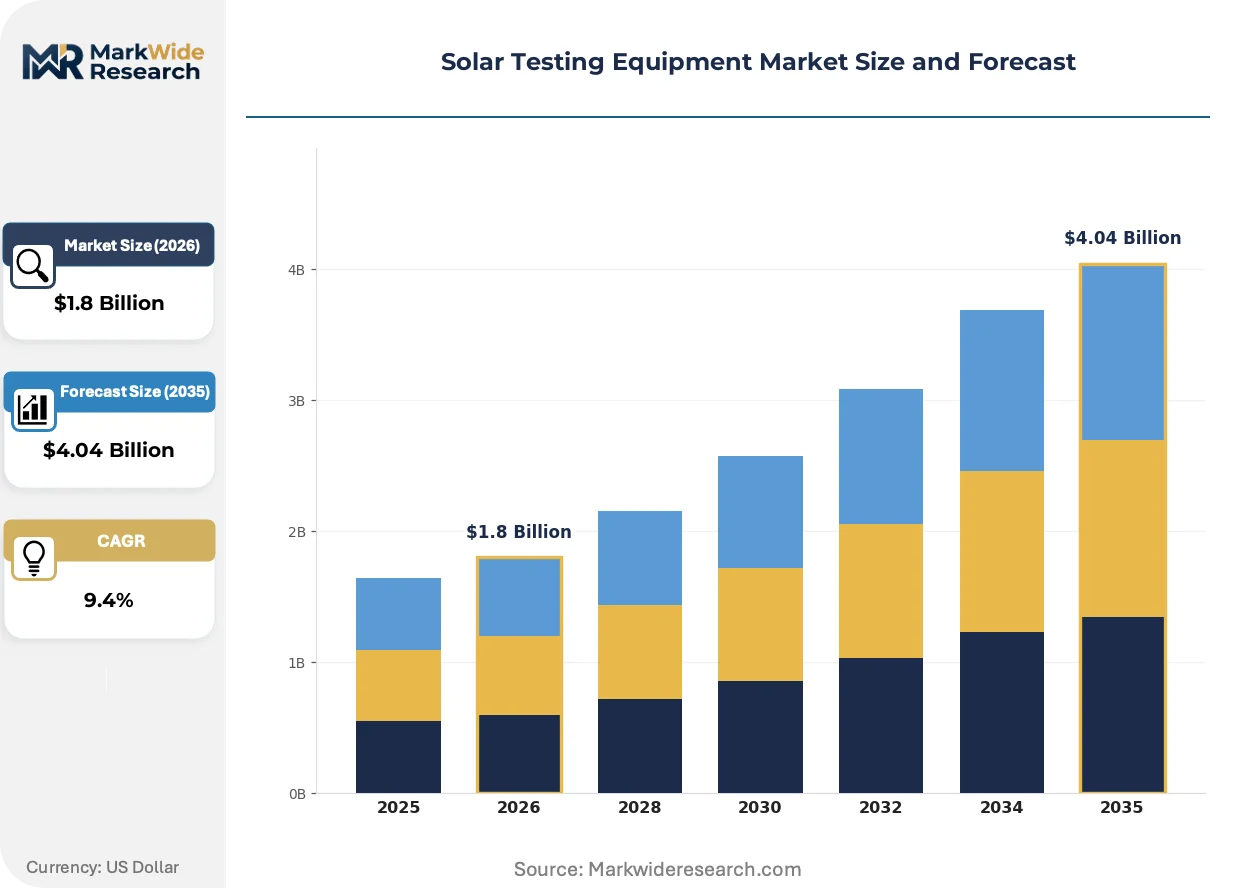
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IV Curve Tester, Solar Simulator, Pyranometer, Reflectometer End User: Manufacturers, Installers, Research Institutions, Certification Bodies Application: Quality Control, Performance Testing, Research & Development, Certification Technology: Photovoltaic Testing, Thermal Testing, Electrical Testing, Optical Testing |
| Companies Covered | TÜV Rheinland, SGS SA, Keysight Technologies, National Instruments, Tektronix Inc., Fluke Corporation, Chroma ATE Inc., Megger Group, Seaward Electronic Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Testing Equipment Market Evolving Landscape
LED-based solar simulators with programmable spectral tuning are compressing capital expenditure requirements while expanding test protocol flexibility for heterojunction and TOPCon cell architectures.
Pulsed LED solar simulators with microsecond-level pulse shaping are displacing traditional xenon flash systems in high-throughput production line applications. Tier-1 module manufacturers in Southeast Asia are adopting these systems to reduce lamp replacement costs and eliminate thermal drift artifacts during IV curve acquisition. The technology is displacing incumbent flash architectures by enabling continuous spectral adjustability without hardware swaps.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in climate chamber coolants, forcing environmental testing equipment suppliers to retrofit thermal cycling systems with CO2-based refrigeration. Module durability testing laboratories in Germany and the Netherlands are absorbing capital costs for compliant chamber upgrades. Crystalline silicon bifacial modules with polymer backsheet materials are most affected, as extended damp-heat protocols require precise humidity control.
Leasing arrangements for portable electroluminescence inspection systems are displacing outright purchase models among independent commissioning engineers. European and North American utility-scale project financiers now require third-party EL documentation before final payment release, expanding the addressable base of field-service providers. This pattern is most visible in Texas and Rajasthan, where gigawatt-scale project pipelines exceed in-house testing capacity.
Solar Testing Equipment Market Segmentation
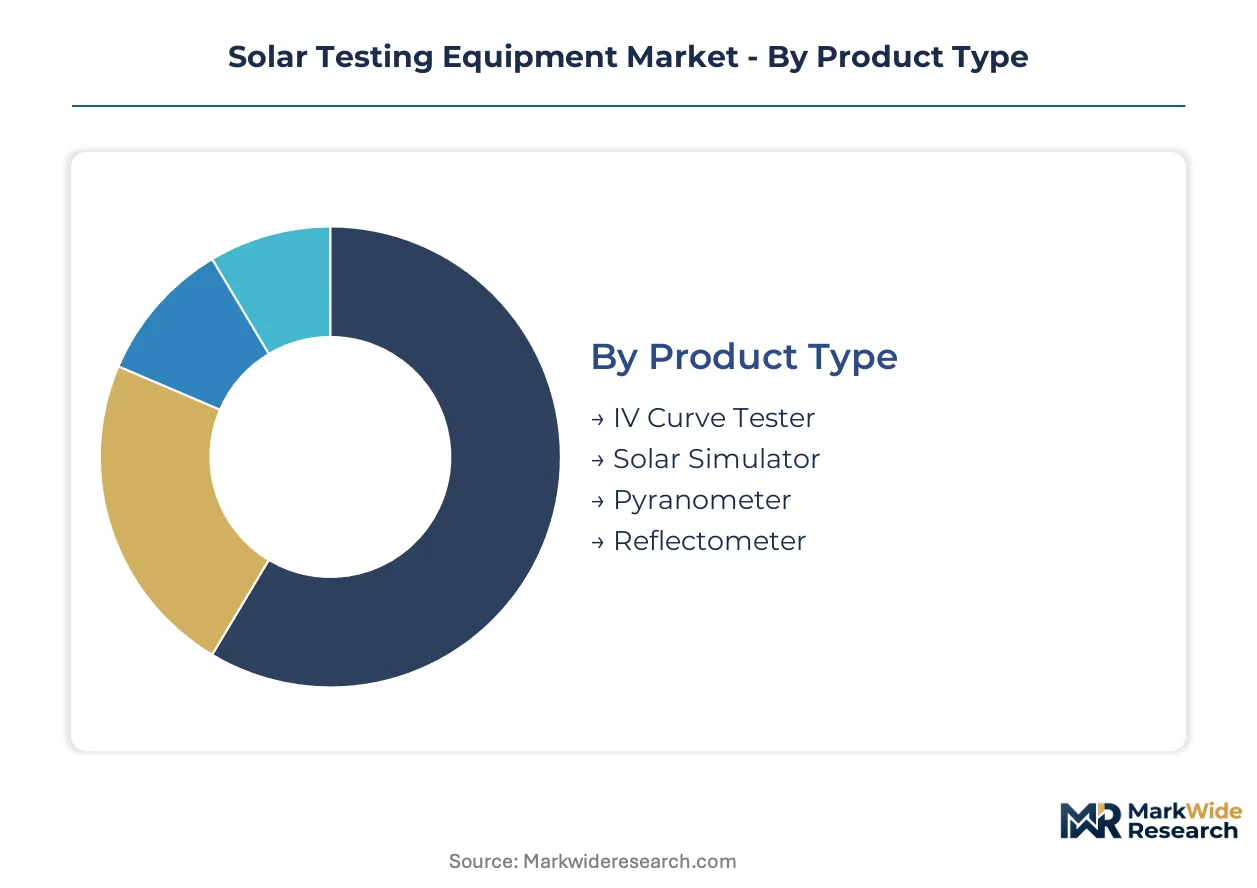
Equipment buyers segment procurement by validation protocol, with IEC 61215 certification requirements driving divergent specifications across laboratory and field-service deployments. Margin pools concentrate where uncertainty budgets tighten below ±1% and throughput demands compress test cycles.
Product Type:
Capital intensity and lamp replacement economics concentrate margin pools in continuous-output systems serving high-volume manufacturing lines.
- Solar Simulator:These systems replicate AM1.5G spectral irradiance across 1000 W/m² standard test conditions using xenon arc or solid-state sources. Demand clusters among tier-1 module manufacturers in Jiangsu province seeking Class A+ uniformity for bifacial cell qualification. Capital costs and optical bench complexity sustain premium pricing tiers.
- IV Curve Tester:Precision source-measurement units capture current-voltage characteristics from open-circuit to short-circuit conditions with microsecond resolution. Utility-scale commissioning engineers in Texas and Rajasthan are expanding portable unit procurement as financiers mandate field validation documentation. Cloud-integrated analytics are displacing laboratory flash testing for post-installation verification.
- Pyranometer:Thermopile-based radiometers measure plane-of-array irradiance with cosine-corrected angular response for meteorological station networks.
- Reflectometer:Spectrophotometric instruments quantify front-surface and rear-surface reflectance losses for anti-reflective coating optimization.
The dominant share belongs to Solar Simulator, while IV Curve Tester is closing the gap fastest.
End User:
Procurement authority shifts toward entities bearing warranty liability, with certification backlog pressures reshaping equipment utilization economics.
- Certification Bodies:Accredited laboratories execute IEC 61215 and IEC 61646 qualification sequences with NIST-traceable calibration chains. TÜV Rheinland and DEKRA facilities in Germany and the Netherlands face 18-month queue stretching, forcing capital expansion into pulsed LED architectures. REACH substance restrictions mandate hazardous material screening for cadmium telluride thin-film modules.
- Manufacturers:Production-line integration demands sub-second cycle times with automated handling for cell-to-module progression. Southeast Asian tier-1 producers are retrofitting steady-state simulators with LED sources to eliminate thermal drift artifacts during heterojunction cell testing. Perovskite tandem R&D programs require spectral tunability across 300-1200 nm ranges.
- Research Institutions:National laboratories and university consortia pursue next-generation architectures with sub-1% uncertainty requirements.
- Installers:Field-service providers deploy portable electroluminescence and IV tracing equipment for commissioning documentation.
Certification Bodies command the largest equipment budgets, though Manufacturers are expanding procurement most aggressively.
Application:
Protocol standardization creates volume concentration where test sequences repeat across high-throughput production environments.
- Quality Control:Inline defect detection combines electroluminescence imaging with machine vision for micro-crack identification at production-line speeds. AI-integrated systems are penetrating Southeast Asian manufacturing hubs as labor cost arbitrage diminishes. Automated pass-fail sorting reduces manual inspection headcount.
- Certification:Third-party validation for warranty-backed deployment requires complete IEC 61215 sequence execution including thermal cycling and damp-heat exposure. Europe's F-Gas Regulation is forcing CO2-based refrigeration retrofits in German and Dutch environmental testing chambers. Bifacial modules with polymer backsheets face extended humidity protocols.
- Performance Testing:Field validation compares actual output against nameplate ratings under variable irradiance conditions.
- Research & Development:Spectral response and quantum efficiency mapping support next-generation cell architecture development.
Quality Control absorbs the highest equipment unit volumes, with Certification generating the steepest expansion trajectory.
Technology:
Measurement modality specialization deepens as cell architectures diversify beyond standard crystalline silicon.
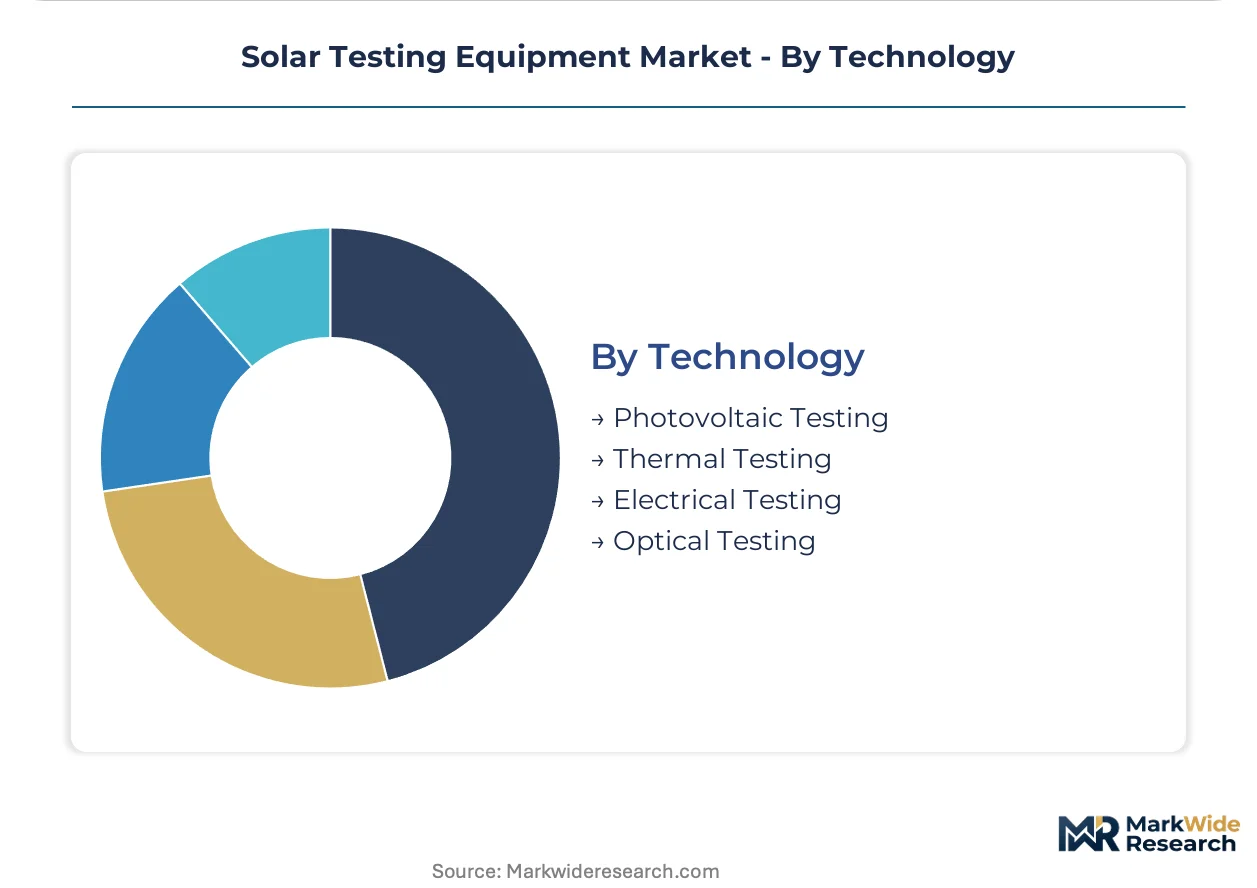
- Photovoltaic Testing:Conversion efficiency validation under simulated and natural irradiance dominates capital allocation. China's manufacturing concentration in Anhui and Jiangsu provinces is pulling metrology demand toward East Asian calibration hubs with localized service capabilities. Bifacial testing under variable albedo conditions requires multi-irradiance sensor configurations.
- Electrical Testing:Precision source-measurement and impedance spectroscopy characterize contact resistance and recombination losses. India's BIS compulsory registration for imported electronics is creating captive calibration infrastructure demand among domestic certification bodies. Leasing arrangements for portable systems are displacing outright purchase among independent commissioning engineers.
- Thermal Testing:Infrared thermography and lock-in thermography identify hot-spot formation and junction temperature distribution.
- Optical Testing:Spectral response and quantum efficiency mapping quantify photon-to-electron conversion across wavelength ranges.
Photovoltaic Testing holds the foundational position, while Electrical Testing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certification bodies and tier-1 module manufacturers concentrate equipment procurement across four distinct geographies, each shaped by local regulatory mandates and manufacturing clustering patterns.
China
Photovoltaic module production in Jiangsu and Anhui provinces drives metrology equipment demand toward East Asian calibration hubs with localized service capabilities. The country's MIIT standards and GB certification frameworks mandate domestic testing infrastructure for export-bound modules. Tier-1 manufacturers in Suzhou and Hefei are retrofitting steady-state simulators with LED sources to eliminate thermal drift artifacts during heterojunction cell qualification.
Germany
TÜV Rheinland and DEKRA facilities face 18-month certification queue stretching, forcing capital expansion into pulsed LED architectures. Europe's F-Gas Regulation phases down hydrofluorocarbon use in climate chamber coolants, compelling CO2-based refrigeration retrofits in environmental testing laboratories. Module durability testing clusters in Cologne and Munich absorb capital costs for compliant chamber upgrades serving bifacial polymer backsheet protocols.
United States
Utility-scale commissioning engineers in Texas expand portable IV curve tester procurement as project financiers mandate field validation documentation before final payment release. FDA oversight applies to medical-grade photovoltaic applications, while EPA guidelines influence end-of-life testing protocols for cadmium telluride thin-film modules. Independent engineers in the ERCOT region face gigawatt-scale project pipelines exceeding in-house testing capacity.
India
BIS mandates compulsory registration for imported solar testing equipment under its electronics and IT goods order, creating localized calibration obligations among domestic certification bodies. The CEA's grid interconnection standards drive utility-scale commissioning protocol adoption. Rajasthan's gigawatt-scale solar parks pull field-service provider expansion toward Jaipur and Jodhpur industrial corridors.
Japan
Xenon lamp supply concentration among Japanese specialty lamp producers creates input cost volatility for solar simulator manufacturers serving domestic and export markets. METI's renewable energy targets accelerate module production line automation investments. Equipment calibration expertise concentrates in Osaka and Nagoya industrial zones supporting NIST-traceable spectral irradiance standards.
Solar Testing Equipment Market Competitive Landscape
Player mix skews toward accredited certification laboratories and precision instrumentation specialists, with the vendor base organizing around three strategic tiers. Premium-tier positions concentrate among multi-continent accredited testing networks anchoring IEC qualification contracts. Mid-tier competition intensifies among automated production-line integrators competing on throughput optimization. Technology specialists occupy narrower positions around spectral response measurement and next-generation cell architecture validation. Dominant competitive moves include geographic expansion into East Asian calibration hubs and technology licensing agreements for pulsed LED simulator architectures.
Among Germany-based accredited testing networks, TÜV Rheinland exemplifies the multi-continent laboratory archetype anchoring premium certification contracts. Keysight Technologies occupies a position within precision electrical characterization instrumentation, representing the R&D procurement cycle specialist. Chroma ATE Inc. sits within the automated production-line integrator tier, exemplifying capital equipment suppliers competing on manufacturing throughput optimization.
| Leading Market Players |
|---|
| TÜV Rheinland |
| SGS SA |
| Keysight Technologies |
| National Instruments |
| Tektronix Inc. |
| Fluke Corporation |
| Chroma ATE Inc. |
| Megger Group |
| Seaward Electronic Ltd. |
| Others |
Value Network & Pricing Analysis
Capital utilization rates above 80% in Japanese and German xenon lamp foundries concentrate pricing power among specialty light-source producers, compressing margin pools for solar simulator manufacturers while establishing rigid price floors for Class A+ uniformity systems. Tier-1 module producers in Jiangsu province absorb these input premiums through multi-year service contracts that bundle calibration labor with equipment lease payments.
Pricing Analysis
Cost-plus contracts with xenon lamp price indexation dominate procurement for steady-state solar simulators, with TÜV Rheinland and DEKRA laboratories accepting 15-20% lamp replacement cost pass-through clauses. Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable certified systems from field-service portable units and refurbished legacy equipment. Pricing pressure stems from LED-based simulator displacement of xenon architectures in Southeast Asian production lines. Certification bodies exhibit lowest price sensitivity due to accreditation-backed revenue streams, while independent commissioning engineers in Texas and Rajasthan prioritize lease-based portable IV curve testers.
Supply Chain Analysis
Inventory buffers for xenon arc lamps stretch beyond six months as Japanese and German specialty producers operate on build-to-order cycles with limited safety stock. Manufacturing concentrates in China, Japan, and Germany, with optical bench fabrication anchored in Suzhou and Nagoya industrial zones. Critical component dependencies include xenon arc lamps, NIST-traceable reference cells, and thermopile-based pyranometer sensors. Single-source vulnerability concentrates in xenon lamp supply, where Ushio and Osram control 70% of Class A+ spectral output capacity. Distribution runs through direct OEM relationships for tier-1 manufacturers and certified distributor networks for field-service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat business where IEC accreditation entrenchment creates switching costs that lock certification bodies into multi-year equipment refresh cycles. Network effects concentrate in East Asian calibration hubs where localized service capabilities compound customer retention.
For Market Incumbents: Consolidate accredited laboratory networks through selective acquisition of regional certification bodies facing 18-month queue backlogs, particularly in Germany and the Netherlands. Expand captive xenon lamp inventory positions to buffer against Japanese supply concentration. Prioritize pulsed LED simulator R&D to preempt field-service substitution threats from portable IV curve testers with cloud analytics. For New Entrants and Emerging Players: Differentiate on spectral tunability for perovskite tandem cell architectures, targeting national laboratory R&D procurement with sub-1% uncertainty specifications. Penetrate India's BIS-mandated calibration infrastructure buildout through joint ventures with domestic certification bodies in Jaipur and Jodhpur. Deploy leasing-first commercialization for portable electroluminescence systems among independent commissioning engineers in ERCOT and Rajasthan solar corridors. For Investors and Strategic Acquirers: Automated production-line integrators with LED simulator architectures represent the most defensible acquisition target archetype, given their exposure to Southeast Asian tier-1 manufacturer capex cycles. Long-term viability hinges on regulatory entrenchment depth rather than technology differentiation alone. Monitor IEC standard revision draft releases as the critical inflection signal for equipment refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| LED Simulator Architecture Licensing | Pulsed LED systems displace xenon flash in Jiangsu province production lines, eliminating thermal drift artifacts. |
| East Asian Calibration Hub Expansion | Localized service capabilities in Suzhou and Hefei capture MIIT-mandated domestic testing infrastructure demand. |
| Perovskite Spectral Response Capability | 300-1200 nm tunability addresses national laboratory R&D procurement with sub-1% uncertainty requirements. |
| India BIS Joint Venture Formation | Compulsory registration mandates create captive calibration infrastructure opportunities in Jaipur industrial corridors. |
| Portable EL System Leasing Platform | Cloud-integrated analytics displace laboratory flash testing for Texas and Rajasthan commissioning engineers. |
Research Methodology
The analysis maps solar simulator, IV curve tester, pyranometer, and reflectometer sub-sectors, each validated through certification laboratory directors, tier-1 manufacturer procurement leads, field-service commissioning engineers, and national laboratory research scientists. Primary interview data triangulates against secondary sources including IEC standard revision drafts, BIS compulsory registration orders, F-Gas Regulation compliance disclosures, and EIA utility-scale project development databases. Bottom-up equipment unit estimates and top-down market value reconstructions cross-validate through manufacturer shipment disclosures and certification body capex filings.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon, with segmentation modeled by product type, end user, application, and technology dimensions plus regional regulatory framework clusters. CAGRs derive from logistic growth curve fitting anchored to IEC standard revision cycles and manufacturing capacity expansion timelines. Industry-specific forecast inputs include xenon lamp replacement cost trajectories, LED simulator adoption curves in Southeast Asia, and BIS localization mandate implementation pacing.
Material uncertainties — IEC standard revision delays, xenon lamp supply disruptions, and perovskite commercialization timelines — sit outside the modeled envelope and could compress or extend equipment refresh cycles. Forecasts reflect documented assumptions regarding accreditation backlog persistence and regional regulatory reciprocity stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Fibrin Degradation Product (Fndp) Assays Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Electrical Testing Equipment Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Steel Testing Equipment Market