
 Gas Pipe Fittings Market | 2026-2036
Gas Pipe Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Pipe Fittings Market Analysis
API 5L and ISO 15590-2 grade specifications is bifurcating the competitive landscape into premium certified and standard commodity tiers. Parker Hannifin Corporation leverages its fluid systems expertise to dominate aerospace-adjacent gas fitting applications. MUELLER WATER PRODUCTS anchors municipal utility contracts through backward integration into iron foundry operations. Swagelok Company differentiates via precision instrumentation-grade fittings for high-purity gas delivery.
Gas pipe fittings are mechanical joining devices engineered to connect, terminate, control, or change the direction of piping in pressurized gas systems, typically rated for pressures from 150 psi to over 2,500 psi depending on material class and end-use. Stainless steel variants dominate upstream oil and gas infrastructure where sour gas service demands ASTM A182 F316 corrosion resistance. Threaded connection types retain volume leadership in residential and light commercial heating applications due to installer familiarity and field serviceability. Welded configurations represent the fastest-expanding segment in industrial fuel distribution as operators prioritize leak integrity over maintenance access.
EPA methane regulations and DOT PHMSA pipeline safety standards mandate material traceability and pressure-testing protocols that elevate procurement specifications for distribution utilities. The EU F-Gas Regulation and CE marking requirements under the Pressure Equipment Directive shape export competitiveness for North American manufacturers serving European industrial end users. Stakeholders must monitor evolving hydrogen blending specifications that could disqualify legacy brass and copper alloys from next-generation gas grid retrofits.
Market Dynamics
EPA methane emission standards and DOT PHMSA pipeline safety mandates are forcing material traceability upgrades across North American gas distribution networks, compressing procurement cycles for certified corrosion-resistant fittings while disqualifying legacy brass alloys from hydrogen-blending infrastructure.
Growth Catalysts
- EPA methane regulations:Tightened emission standards compel utilities to replace aging cast iron and unprotected steel infrastructure with stainless steel and advanced composite fittings rated for sour gas service.
- Gulf Coast petrochemical corridor:Pipeline replacement cycles intensify demand for high-pressure welded configurations as operators prioritize leak integrity over field serviceability in concentrated industrial zones.
- Hydrogen blending specifications:Emerging grid retrofit standards create pull-through demand for ASTM A182 F316 and specialized alloy fittings capable of handling hydrogen embrittlement risks in next-generation fuel networks.
Market Restraints
- Nickel and molybdenum price volatility:Stainless steel input costs fluctuate with mining supply disruptions, squeezing margin structures for fitting manufacturers locked into long-term municipal utility contracts.
- Foundry capacity concentration:Ductile iron and carbon steel casting operations cluster in specific industrial regions, creating geographic supply vulnerability during extreme weather or energy price spikes.
- Legacy brass alloy obsolescence:Dezinification susceptibility in older copper-zinc formulations threatens installed base replacement economics as hydrogen compatibility testing disqualifies traditional residential fitting materials.
Strategic Opportunities
- EU F-Gas Regulation alignment:CE marking compliance under the Pressure Equipment Directive opens export pathways for North American manufacturers serving European industrial gas distribution and chemical processing end users.
- Instrumentation-grade precision demand:Semiconductor and pharmaceutical clean gas applications require ultra-high-purity surface finishes and orbital weld compatibility, creating premium pricing tiers distinct from commodity threaded products.
- Integrated smart monitoring convergence:Pressure sensor embedding and IoT-enabled leak detection integration transform passive fittings into data nodes, enabling recurring revenue service models for infrastructure operators.
Industry Challenges
- Orbital welding technician scarcity:Industrial fuel distribution operators face certified welder shortages as welded configurations displace threaded connections, extending project timelines and inflating installation labor costs.
- Multi-standard certification complexity:Simultaneous compliance with API 5L, ISO 15590-2, and ASME B31.8 creates documentation burdens that delay product launches and inflate third-party testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Pipe Fittings Market |
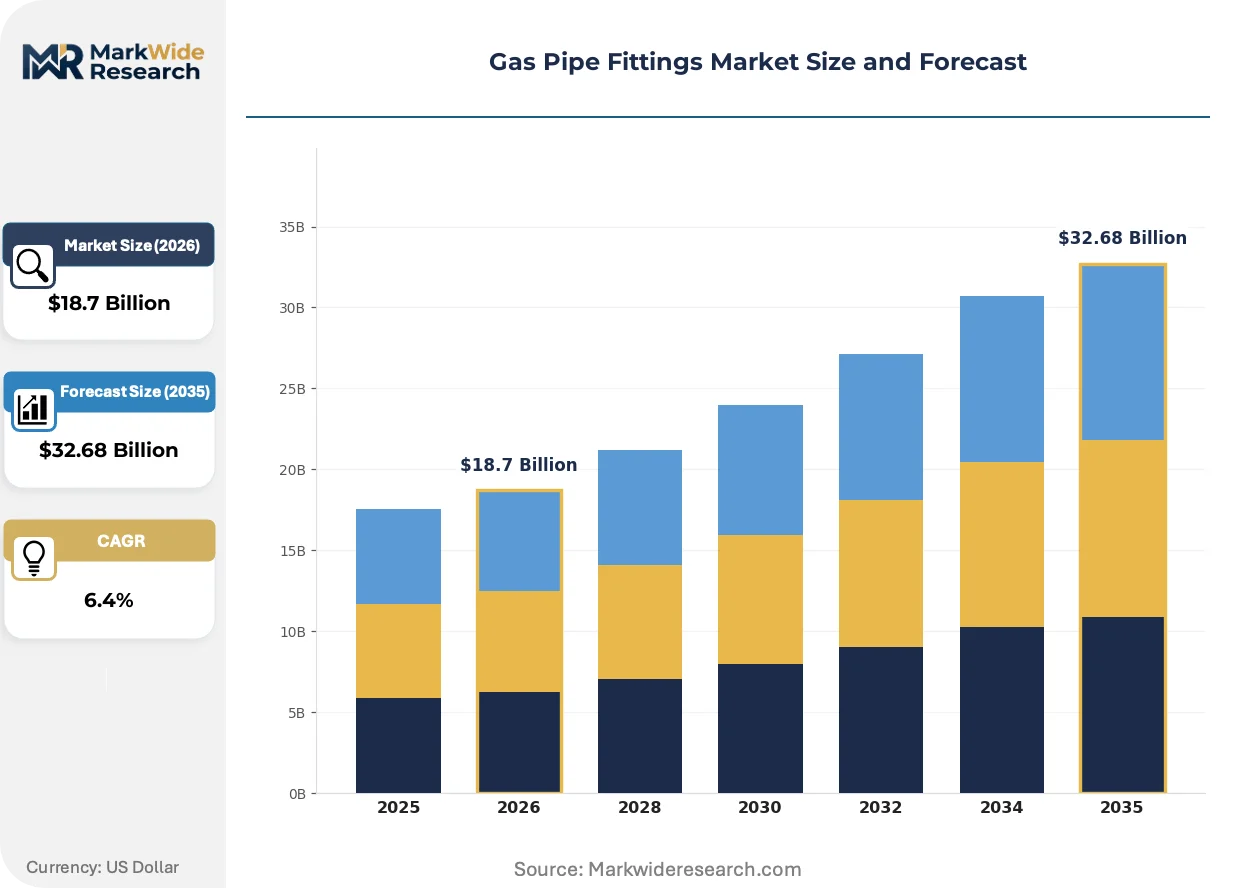
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Stainless Steel, PVC, Copper, Brass Connection Type: Threaded, Welded, Flanged, Socket Weld End User: Residential, Commercial, Industrial, Utilities Application: Heating, Cooking, Fuel Distribution, Pipeline Transport |
| Companies Covered | Parker Hannifin Corporation, Charlotte Pipe, MUELLER WATER PRODUCTS, Victaulic Company, GF Piping Systems, Swagelok Company, Plasson USA, JM Eagle, Honeywell International Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Pipe Fittings Market Emerging Trajectories
Material science advances and regulatory pressure are bifurcating the competitive landscape into premium certified tiers and commodity standard offerings, with hydrogen infrastructure readiness emerging as the decisive technical differentiator.
Composite-reinforced polymer fittings are fragmenting the corrosion protection segment for medium-pressure distribution networks. Water utilities and municipal gas operators in coastal regions adopt these lightweight alternatives to eliminate cathodic protection systems. The technology is fragmenting supplier bases as specialized composite manufacturers bypass traditional metal foundry channels.
DOT PHMSA integrity management rules now mandate inline inspection compatibility and material traceability for Class 3 and Class 4 gas pipelines. Operators must maintain decade-long documentation chains linking specific fitting batches to installation locations and pressure test records. Distribution utilities in the United States respond by consolidating supplier lists to vendors with captive metallurgical testing laboratories.
Specification-driven procurement now dominates large utility accounts as engineering departments centralize technical standards. Master service agreements with pre-approved material grades displace spot purchasing through distributor networks. This concentration is most visible across integrated gas utilities in the southeastern United States where procurement functions have absorbed field engineering authority.
Gas Pipe Fittings Market Segmentation
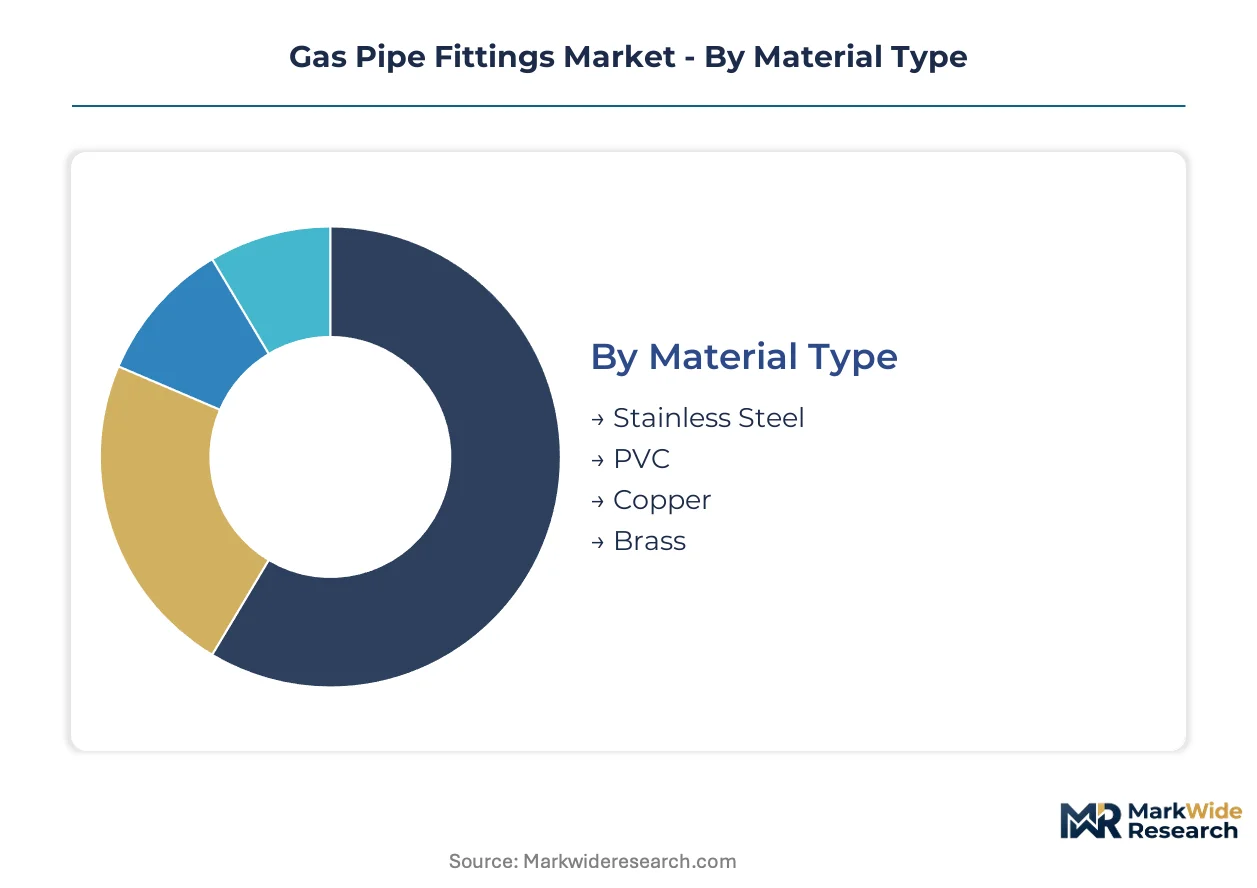
Material specifications and connection geometries determine regulatory compliance trajectories across gas pipe fittings procurement. ASTM certification grades and pressure ratings segment vendor capabilities into distinct competitive tiers that shape utility engineering specifications.
Material Type:
EPA methane regulations and DOT PHMSA pipeline safety mandates bifurcate material selection between corrosion-resistant certified grades and legacy formulations facing obsolescence.
- Stainless Steel:ASTM A182 F316 and F304 grades deliver sour gas service resistance required for hydrogen-blending infrastructure. Gulf Coast petrochemical operators specify these alloys for replacement cycles prioritizing leak integrity over decades-long service life.
- Brass:Traditional copper-zinc alloys dominate residential heating connections due to installer familiarity and field serviceability. Dezinification susceptibility and hydrogen embrittlement testing failures threaten this segment's viability in next-generation grid retrofits.
- Copper:Type K and L soft copper tubing remains specified for indoor fuel distribution in jurisdictions permitting brazed joints.
- PVC:Thermoplastic formulations serve low-pressure outdoor distribution where cathodic protection elimination outweighs pressure rating limitations.
Established volume favors brass; emerging adoption favors stainless steel.
Connection Type:
Installation labor economics and orbital welding technician scarcity concentrate demand growth toward configurations minimizing field certification requirements.
- Threaded:NPT and BSPT tapered connections retain dominance in residential and light commercial heating applications. Field serviceability without specialized equipment sustains this segment despite pressure limitations below 300 psi in most municipal codes.
- Welded:Butt-weld and socket-weld configurations are climbing the fastest in industrial fuel distribution as operators prioritize leak integrity. API 5L and ASME B31.8 compliance documentation creates supplier consolidation toward vendors with captive metallurgical laboratories.
- Flanged:ASME B16.5 standardized flange pairs enable maintenance access in high-pressure pipeline transport segments.
- Socket Weld:Compact geometry suits instrumentation-grade applications in semiconductor clean gas delivery where orbital weld compatibility is mandatory.
Threaded connections anchor replacement revenue; welded configurations capture new-build specification authority.
End User:
Procurement centralization patterns concentrate purchasing power across integrated utility accounts while fragmenting commercial project specifications.
- Utilities:Master service agreements with pre-approved material grades displace spot purchasing through distributor networks. Southeastern United States gas distribution operators have absorbed field engineering authority into centralized procurement functions.
- Industrial:Petrochemical corridor operators in Texas and Louisiana drive demand for high-pressure welded configurations. Pipeline replacement cycles intensify specification-driven procurement with decade-long material traceability requirements.
- Residential:HVAC contractor familiarity with threaded brass fittings sustains volume despite regulatory pressure for material upgrades.
- Commercial:Mixed-use developments generate specification complexity combining residential-grade accessibility with industrial-grade pressure requirements.
Utility consolidation favors long-term contracting; industrial project timing favors spot market responsiveness.
Application:
Pressure rating requirements and fluid compatibility specifications segment procurement into distinct engineering disciplines with minimal supplier overlap.
- Fuel Distribution:Medium-pressure municipal networks require inline inspection compatibility and material traceability documentation. DOT PHMSA integrity management rules mandate decade-long batch linking to installation locations.
- Pipeline Transport:Class 3 and Class 4 gas pipelines demand ASME B31.8 compliance with pressure-testing protocols exceeding 2,500 psi. Coastal corrosion protection drives composite-reinforced polymer adoption for cathodic protection elimination.
- Heating:Residential and commercial boiler connections prioritize field serviceability and installer training continuity over maximum pressure ratings.
- Cooking:Commercial kitchen gas line specifications emphasize quick-disconnect safety mechanisms and flexible connector compatibility.
Pipeline transport commands premium pricing; heating applications sustain volume manufacturing scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for ductile iron and carbon steel castings clusters in specific industrial regions, creating geographic supply vulnerability during extreme weather or energy price spikes. The United States anchors procurement volume through utility infrastructure expansion, while Germany and China concentrate precision manufacturing capabilities for specialized alloys.
United States
EPA methane regulations and DOT PHMSA pipeline safety mandates compel utilities to replace aging cast iron infrastructure with stainless steel fittings. The Gulf Coast petrochemical corridor drives replacement cycles for high-pressure welded configurations. Texas and Louisiana operators prioritize leak integrity over field serviceability in concentrated industrial zones.
Germany
EU F-Gas Regulation alignment and CE marking requirements under the Pressure Equipment Directive shape export competitiveness for industrial gas distribution. The country's precision engineering base serves semiconductor and pharmaceutical clean gas applications requiring ultra-high-purity surface finishes. Bavaria and Baden-Württemberg host specialized manufacturers with captive metallurgical testing laboratories.
China
GB standards and MIIT industrial policy guide domestic procurement specifications for medium-pressure municipal networks. The Yangtze River Delta and Pearl River Delta concentrate composite-reinforced polymer manufacturing for cathodic protection elimination in coastal corrosion environments. State-owned utilities consolidate supplier lists toward vendors with decade-long material traceability documentation.
India
BIS certification requirements and the PLI scheme for manufacturing infrastructure accelerate domestic foundry modernization for carbon steel castings. Maharashtra and Gujarat petrochemical operators drive specification-driven procurement for hydrogen-blending infrastructure. The country's national gas grid expansion creates pull-through demand for ASTM A182 F316 grade corrosion-resistant fittings.
Japan
METI energy transition policy and JIS standards mandate hydrogen compatibility testing for next-generation fuel network retrofits. The Kanto and Kansai industrial corridors concentrate demand for instrumentation-grade precision fittings in semiconductor manufacturing. Tokyo-area utilities centralize procurement functions with pre-approved material grades displacing spot purchasing.
Gas Pipe Fittings Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized fluid systems engineers. The vendor base separates into three strategic tiers: premium certified alloy specialists, integrated utility contractors, and commodity standard fabricators. Competitive moves center on backward integration into iron foundry operations and strategic partnerships for composite-reinforced polymer technology licensing.
Within the premium certified tier, Parker Hannifin Corporation and Swagelok Company exemplify precision instrumentation-grade positioning. MUELLER WATER PRODUCTS anchors the integrated utility contractor archetype through in-house production of iron castings. Charlotte Pipe and Victaulic Company occupy positions across the commodity-to-specialist spectrum, with geographic naming conventions suggesting North American operational bases. GF Piping Systems represents the European multinational structure, while Plasson USA indicates Israeli-origin manufacturing with United States market presence. Honeywell International Inc exemplifies the diversified conglomerate archetype with industrial automation adjacencies.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Charlotte Pipe |
| MUELLER WATER PRODUCTS |
| Victaulic Company |
| GF Piping Systems |
| Swagelok Company |
| Plasson USA |
| JM Eagle |
| Honeywell International Inc |
| Others |
Supply Flow & Price Mechanics
Composite-reinforced polymer substitution for metal castings in coastal distribution networks simultaneously redraws supplier geography toward specialized polymer manufacturers and compresses pricing power for traditional foundry operators locked into long-term municipal utility contracts.
Pricing Analysis
EPA methane emission standards dictate the pricing tier structure across the Gas Pipe Fittings Market by mandating ASTM A182 F316 certification for hydrogen-blending infrastructure. Three-tier pricing structure across premium certified, standard industrial, and commodity residential levels separates vendors with captive metallurgical laboratories from spot-market fabricators. Cost compression in commodity brass fittings is intensifying because dezinification susceptibility disqualifies legacy alloys from next-generation grid retrofits. Municipal utilities exhibit lowest price sensitivity due to master service agreement consolidation, while residential HVAC contractors remain most responsive to per-unit cost differentials.
Supply Chain Analysis
China and India anchor carbon steel and ductile iron casting supply for medium-pressure municipal networks, while Germany and Japan concentrate precision stainless steel fabrication for instrumentation-grade applications. Foundry operations draw from nickel and molybdenum feedstock vulnerable to mining supply disruptions in Indonesia and the Philippines. Single-source vulnerability concentrates in Gulf Coast petrochemical corridor procurement, where hurricane-season logistics chokepoints interrupt just-in-time delivery schedules. Distribution runs through consolidated direct-contract channels for utility accounts and fragmented distributor networks for residential project spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen infrastructure readiness represents a technological inflection that will bifurcate vendor viability within a high-growth disruption framework across the Gas Pipe Fittings Market.
For Market Incumbents: Shield installed base relationships by accelerating backward integration into captive metallurgical testing laboratories that satisfy DOT PHMSA decade-long traceability mandates. Absorb field engineering authority into centralized procurement functions to lock out commodity competitors from master service agreement renewals before hydrogen compatibility testing disqualifies additional legacy material grades. For New Entrants and Emerging Players: Differentiate on composite-reinforced polymer technology licensing for coastal corrosion protection applications where cathodic protection elimination outweighs pressure rating trade-offs. Target water utility accounts in hurricane-prone regions with lightweight alternative solutions that bypass traditional metal foundry channels entirely. Pursue white-label manufacturing partnerships with established infrastructure operators lacking in-house polymer engineering capabilities. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors precision-certified alloy specialists with hydrogen embrittlement testing capabilities over commodity brass fabricators facing obsolescence. Long-term viability over the next decade hinges on ASTM A182 F316 production capacity and CE marking compliance for European export pathways. Monitor EPA enforcement intensity around methane emission standards as the decisive inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallurgical Testing | Captive laboratories satisfy DOT PHMSA decade-long material traceability mandates for Class 3 and Class 4 pipelines. |
| Hydrogen Compatibility Certification Investment | ASTM A182 F316 qualification opens specification-driven procurement for next-generation fuel network retrofits. |
| Composite-Reinforced Polymer Technology Licensing | Lightweight alternatives eliminate cathodic protection systems in coastal corrosion environments for municipal water utilities. |
| CE Marking Compliance Pathway Development | Pressure Equipment Directive alignment unlocks export pathways for North American manufacturers serving European industrial end users. |
| Integrated Smart Monitoring Convergence | Pressure sensor embedding transforms passive fittings into IoT-enabled data nodes with recurring revenue service models. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade databases, EPA enforcement records, and API certification registries. Utility procurement directors, petrochemical plant engineers, municipal pipeline maintenance supervisors, and distributor channel managers provided operational perspective across the value chain. Bottom-up demand modeling from installation project databases triangulates against top-down supply capacity assessments from foundry and polymer manufacturing records.
Segmentation dimensions modeled include material grade tier, connection geometry type, end-user procurement centralization level, application pressure rating, and regional regulatory framework cluster across the projection horizon. CAGRs derive from replacement cycle timing analysis, infrastructure investment pipeline tracking, and material substitution elasticity estimates. Hydrogen blending specification evolution and nickel-molybdenum price volatility indices feed directly into forecast sensitivity ranges.
Material uncertainties — nickel and molybdenum supply disruptions, EPA methane regulation enforcement intensity shifts, orbital welding technician availability constraints — sit outside the modeled envelope. Forecasts reflect assumptions around utility infrastructure investment continuity and hydrogen grid retrofit standardization timing. Recalibration cycles align with material shifts in DOT PHMSA integrity management rule amendments and EU F-Gas Regulation revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Agricultural Pipes and Tubes Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
Stainless Steel Plumbing Pipes and Fittings Market
Pipes and Tubes
Kuwait PVC Pipes Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
Oman PVC Pipes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market