
 Silk Protein Market | 2026-2036
Silk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Silk Protein Market Analysis
Subscription-based raw material supply programs is shifting how biopolymer buyers secure silk protein volumes. AMSilk GmbH leverages its recombinant spider silk platform to anchor long-term offtake agreements with industrial partners. Bolt Threads competes through its Microsilk fermentation technology, sustaining production scale without traditional sericulture constraints. Croda International Plc specializes in cosmetic-grade silk derivatives, dominating formulation channels across European personal care brands.
Silk protein comprises fibroin and sericin polypeptides extracted from Bombyx mori cocoons, with fibroin containing heavy-chain, light-chain, and glycoprotein fractions that self-assemble into beta-sheet crystalline structures conferring tensile strength exceeding steel by weight. These proteins serve as biocompatible scaffolds for tissue engineering, moisture-retention matrices for topical applications, and oxygen-barrier films for active packaging. Silk fibroin powder leads product type revenue due to established pharmaceutical excipient qualifications, while liquid silk concentrates in food additive applications where clean-label texture modification commands formulation priority. Skincare application segments attract margin concentration as peptide-grade sericin isolates achieve cosmeceutical price premiums over technical-grade alternatives.
FDA biomaterial guidance and EPA chemical substance notifications shape U.S. market entry requirements for novel silk-derived inputs, while REACH registration obligations in Europe enforce toxicological dossier standards on imported protein concentrates. China's GB standards for food-grade biopolymers and NMPA medical device classifications create parallel compliance tracks for domestic and export-oriented manufacturers. Stakeholders must monitor regulatory divergence between cosmetic, food, and pharmaceutical classification pathways as silk protein applications cross traditional sector boundaries.
Market Dynamics
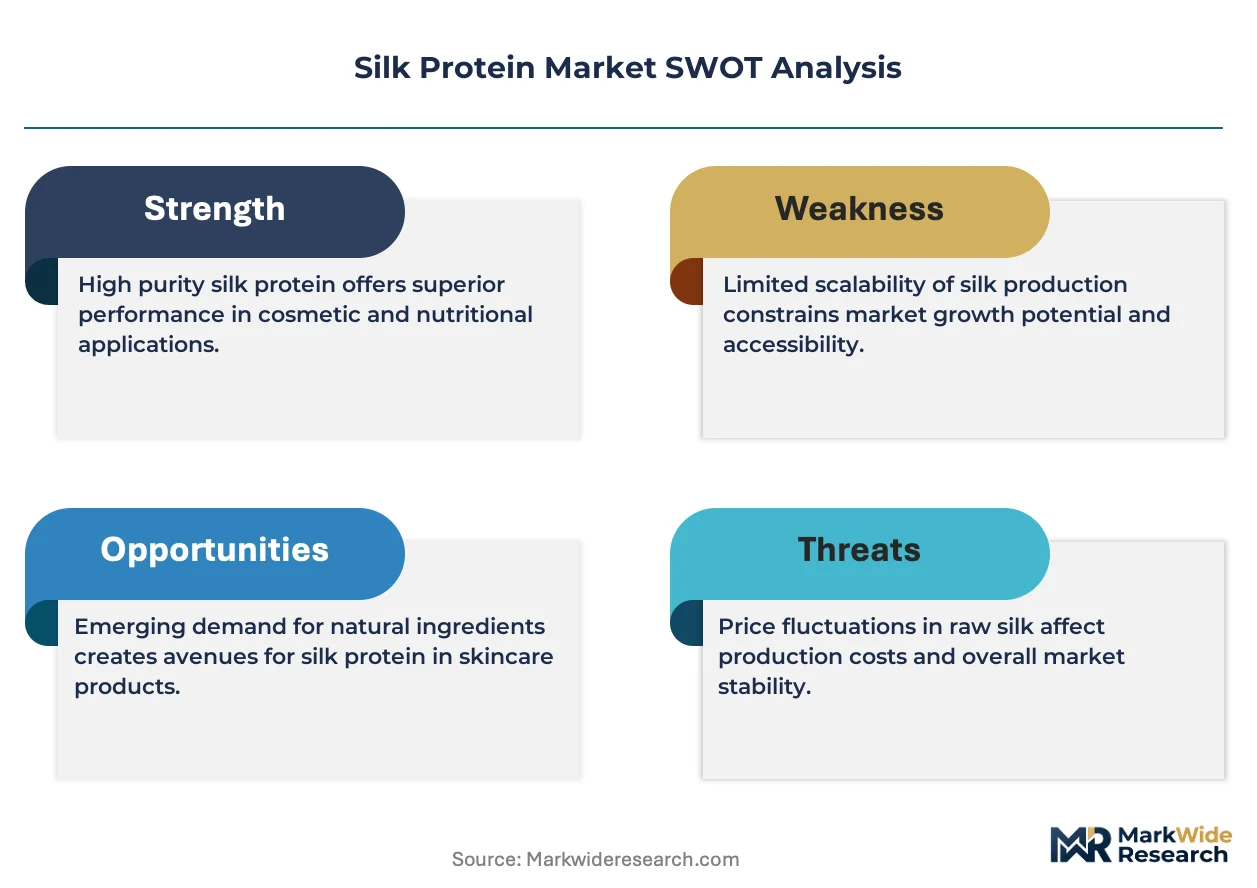
Recombinant fermentation platforms are decoupling silk protein supply from traditional sericulture, redrawing competitive boundaries between mulberry-dependent extraction and microbial production systems.
Growth Catalysts
- REACH toxicological dossier requirements:European purity benchmarks are filtering technical-grade suppliers, consolidating formulation-grade channels for compliant producers.
- Cosmeceutical peptide isolation:Sericin-derived bioactive fractions command premium positioning in regenerative skincare, pulling investment toward downstream purification capabilities.
- Zhejiang sericulture clustering:China's concentrated cocoon supply chains enable integrated biopolymer processing at scale unmatched by fragmented global alternatives.
Market Restraints
- Mulberry leaf input volatility:Climate stress on Bombyx mori feedstock exposes traditional extraction to seasonal yield compression and price instability.
- FDA biomaterial classification friction:Cross-sector applications trigger divergent pathway requirements, elongating time-to-market for novel silk-derived medical devices.
- Petroleum-based barrier film competition:Synthetic oxygen-barrier substrates maintain cost advantages in active packaging, constraining silk protein penetration.
Strategic Opportunities
- India's PLI scheme for biopolymers:Production-linked incentives are attracting fermentation infrastructure investment outside China's sericulture dominance.
- Food-grade texture modification:Clean-label positioning in plant-based meat matrices offers formulation partnerships with alternative protein brands.
- ISO 10993 biocompatibility harmonization:Converging international medical device standards reduce multi-market certification burden for scaffold suppliers.
Industry Challenges
- Beta-sheet crystallization control:Batch-to-batch mechanical property variance in fibroin scaffolds complicates pharmaceutical excipient qualification.
- Dual-use export classification:Silk protein's overlap between cosmetic and medical applications triggers jurisdictional ambiguity in customs processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silk Protein Market |
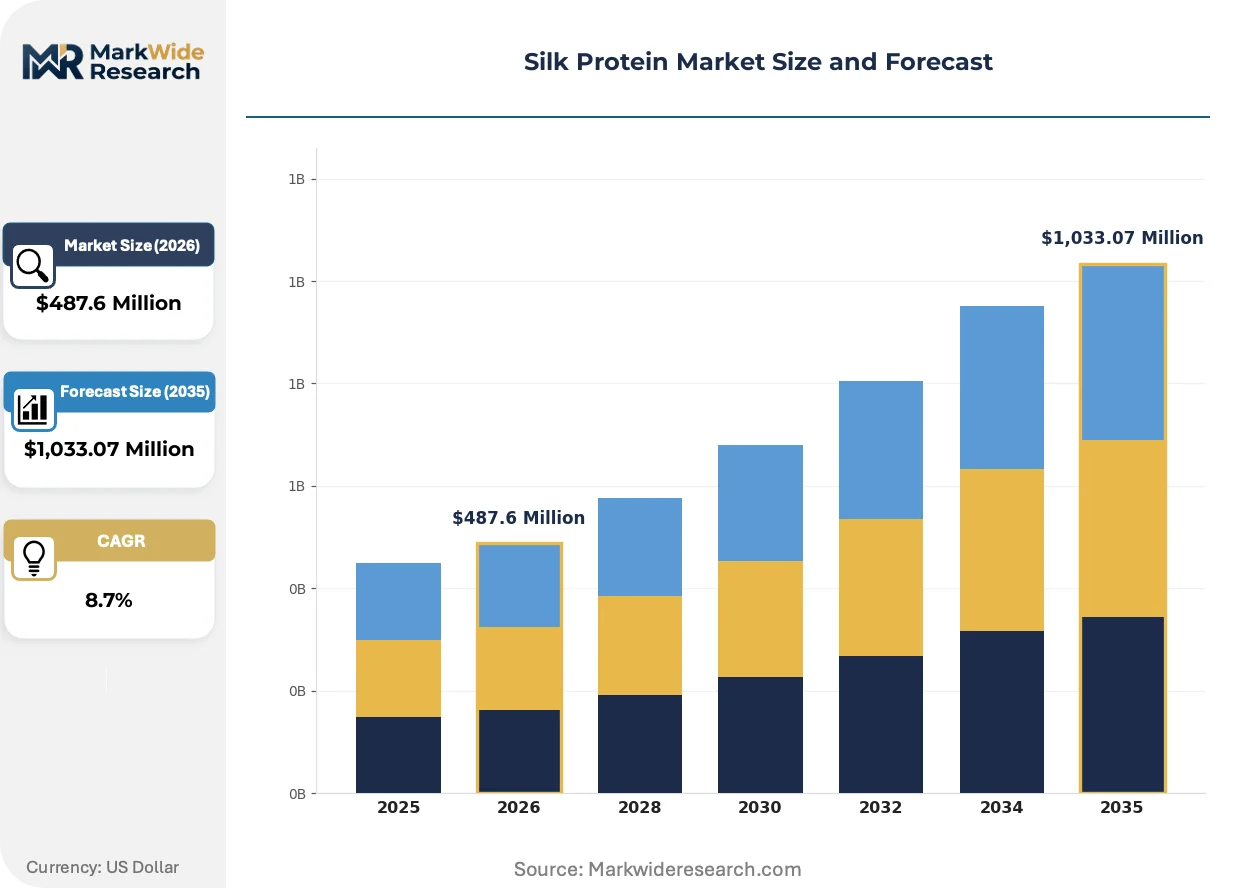
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silk Fibroin, Silk Sericin, Gelatin Silk, Liquid Silk End User: Cosmetics, Food, Pharmaceutical, Textile Application: Skincare, Food Additive, Drug Delivery, Biodegradable Packaging Form: Powder, Liquid, Sheet, Gel |
| Companies Covered | Kraig Biocraft Laboratories, LANXESS, AMSilk GmbH, SEIWA KASEI Co., Ltd., Huzhou Aotesi Biochemical, Spiber, Croda International Plc, Evonik, Bolt Threads, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silk Protein Market Emerging Trajectories
Biomanufacturing scale-up is compressing the cost curve for non-sericulture silk, while regulatory clarity on biomaterial classifications accelerates cross-sector application development.
Microbial silk production is unifying pharmaceutical purity standards with industrial volume economics. Biotech platforms now match fibroin molecular weights to end-use mechanical requirements. Contract manufacturers in Germany and the United States are installing dedicated fermentation lines for medical-grade output.
EU MDR substance disclosure rules are tightening traceability for implant-grade materials. Device manufacturers must document protein source and processing history through supply chains. Swissmedic and TGA are aligning with EMA guidance, creating transatlantic certification reciprocity pressure.
Long-term offtake contracting is displacing spot purchasing for industrial volumes. Tier-one personal care brands now secure multi-year recombinant silk allocations directly from bioproduction facilities. This pattern concentrates procurement power among formulation houses with forecast visibility extending beyond traditional agricultural cycles.
Silk Protein Market Segmentation
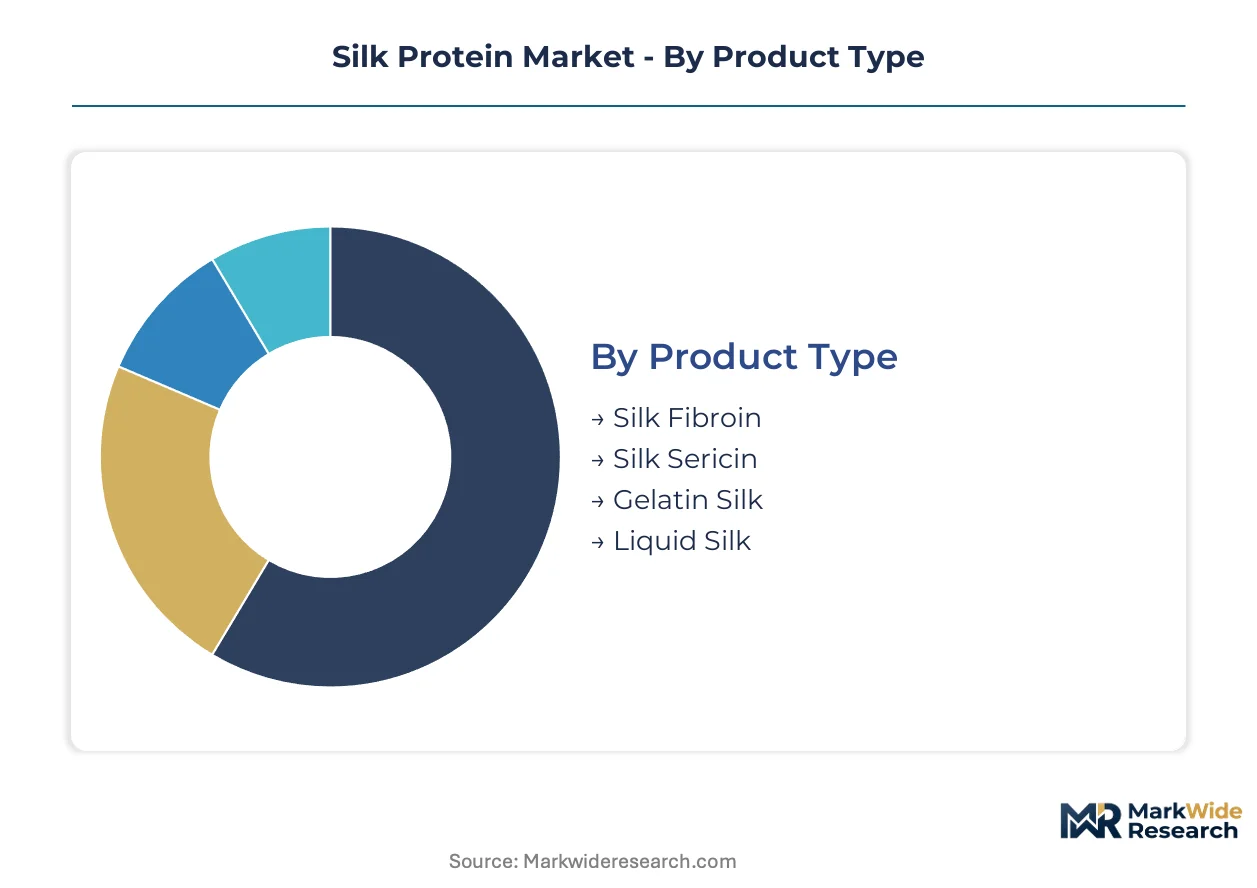
Silk protein segmentation reflects divergent purity requirements across pharmaceutical, cosmetic, and food channels. Each category channels raw biopolymer through distinct qualification pathways that reshape supplier economics and procurement patterns.
Product Type:
Supply concentration in Zhejiang province favors fibroin-dominant extraction, yet recombinant platforms are redrawing competitive boundaries for sericin and liquid variants.
- Silk Fibroin:Heavy-chain and light-chain polypeptides self-assemble into beta-sheet crystalline structures. Heavy-chain fractions exceeding 350 kDa molecular weight anchor tissue engineering scaffolds in Boston and Basel medical device clusters, constrained by batch-to-batch crystallization variance.
- Silk Sericin:Glue protein surrounding fibroin filaments contains serine-rich hydrophilic domains. Peptide-grade isolates command cosmeceutical premiums in Seoul and Paris formulation houses, pulled by regenerative skincare positioning.
- Gelatin Silk:Hydrolyzed fibroin fragments suit food-grade texture applications.
- Liquid Silk:Concentrated aqueous suspensions enable clean-label formulation without reconstitution steps.
Today's leader: Silk Fibroin. Tomorrow's challenger: Silk Sericin.
End User:
Margin stratification across end-use channels concentrates investment toward qualification-heavy pharmaceutical and premium cosmetic segments over commodity textile outlets.
- Cosmetics:Peptide-grade sericin and hydrolyzed fibroin dominate premium skincare lines. European REACH compliance filters technical-grade suppliers, consolidating formulation-grade channels for ECHA-registered producers.
- Pharmaceutical:Excipient-grade fibroin scaffolds and drug delivery matrices require ISO 10993 biocompatibility certification. FDA biomaterial guidance elongates time-to-market for novel medical devices.
- Food:Clean-label texture modification in plant-based matrices attracts alternative protein brand partnerships.
- Textile:Technical-grade fibroin serves functional fiber finishing with lower purity thresholds.
Cosmetics and pharmaceutical segments capture margin concentration. Food applications are expanding most quickly.
Application:
Application-level demand maps directly onto regulatory jurisdiction, with skincare and drug delivery triggering cosmetic versus medical device classification friction.
- Skincare:Moisture-retention matrices and anti-aging peptide formulations leverage sericin hydrophilicity. Premium positioning in Japanese and German personal care markets pulls investment toward downstream purification.
- Drug Delivery:Fibroin nanoparticles and hydrogels enable controlled-release formulations. NMPA medical device classifications in China create parallel compliance tracks for domestic and export-oriented scaffold suppliers.
- Food Additive:Clean-label emulsification and texture modification in alternative protein products.
- Biodegradable Packaging:Oxygen-barrier films compete against petroleum-based substrates on cost.
Skincare dominates current revenue. Drug delivery shows steepest expansion trajectory.
Form:
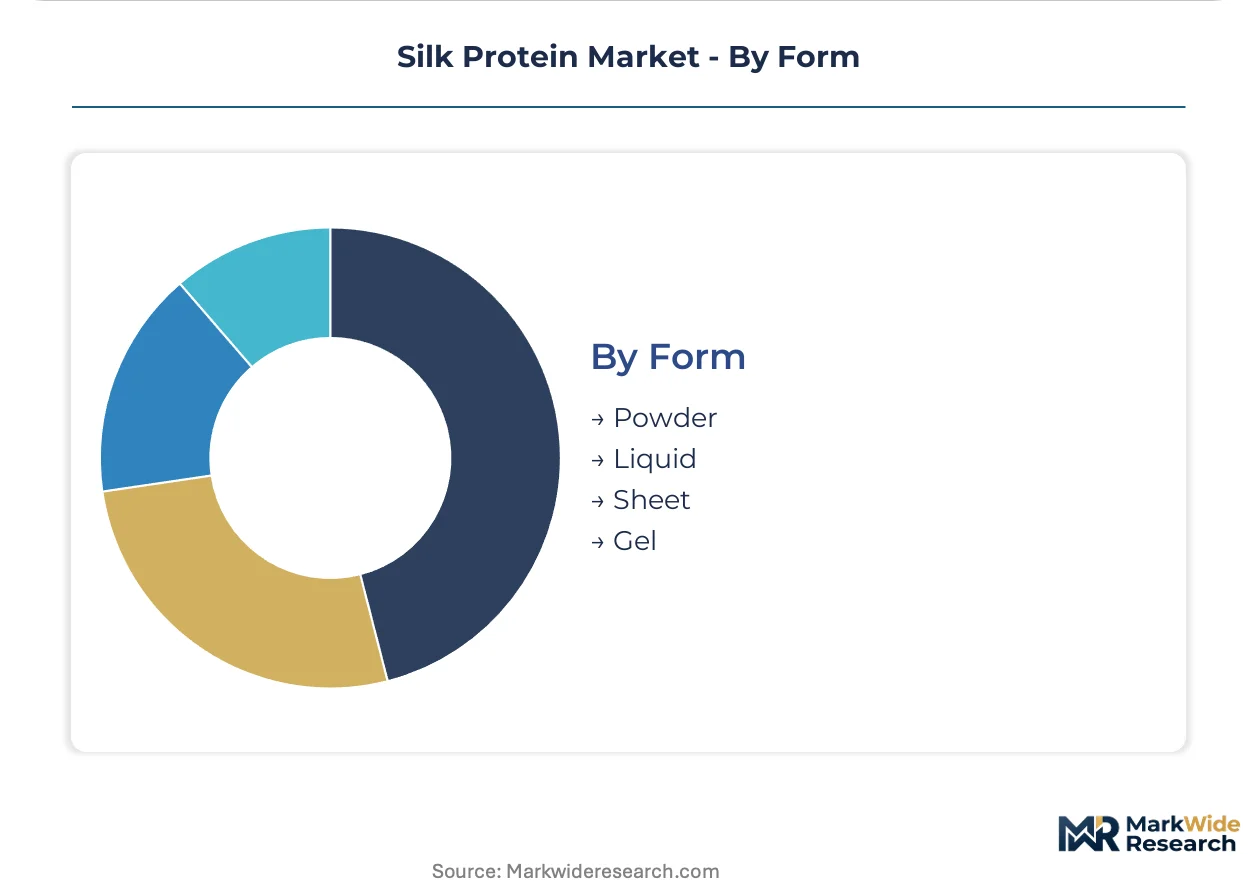
Form selection determines supply chain configuration, with powder qualification anchoring pharmaceutical channels and liquid concentrates enabling just-in-time cosmetic formulation.
- Powder:Lyophilized fibroin with defined particle size distribution suits excipient manufacturing. Established pharmaceutical qualifications in USP-NF and EP monographs anchor procurement contracts.
- Liquid:Aqueous silk protein concentrates enable clean-label food additive formulation without reconstitution. Texture modification partnerships with plant-based meat brands concentrate demand.
- Sheet:Pre-formed matrices for wound dressing and tissue engineering applications.
- Gel:Hydrogel formulations for topical delivery and scaffold seeding protocols.
Powder form locks in pharmaceutical procurement. Liquid form is gaining share fastest in food channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Zhejiang sericulture clusters dominate mulberry-dependent extraction, while Germany's recombinant fermentation infrastructure anchors non-traditional supply. Regulatory divergence between REACH dossier requirements and FDA biomaterial guidance shapes competitive positioning across manufacturing bases.
China
Zhejiang province concentrates cocoon processing for fibroin extraction, feeding downstream biopolymer facilities. NMPA medical device classifications create dual compliance tracks for domestic consumption versus export-oriented pharmaceutical scaffolds. Hangzhou and Jiaxing host integrated sericulture-to-biopolymer operations unmatched in production scale.
Germany
Recombinant silk fermentation capacity clusters around Munich and Heidelberg biotech corridors. ECHA REACH registration obligations enforce toxicological dossier standards that filter technical-grade imports, consolidating formulation-grade channels for compliant domestic producers. AMSilk GmbH anchors long-term offtake contracting with industrial partners from this base.
United States
FDA biomaterial guidance and EPA chemical substance notifications shape market entry for novel silk-derived inputs. Boston and San Francisco medical device clusters demand ISO 10993 biocompatibility certification for fibroin scaffolds. Bolt Threads sustains Microsilk production scale without traditional sericulture constraints through domestic fermentation infrastructure.
Japan
Sericin peptide isolation for premium skincare concentrates in Osaka and Tokyo formulation houses. METI industrial standards and PMDA pharmaceutical classifications create segmented qualification pathways. SEIWA KASEI Co., Ltd. occupies established positions in cosmetic-grade silk derivative channels across domestic personal care brands.
India
PLI scheme production-linked incentives attract fermentation infrastructure investment outside Chinese sericulture dominance. CDSCO medical device regulations and FSSAI food-grade standards create parallel compliance frameworks. Karnataka and Maharashtra emerge as alternative biopolymer processing locations with growing contract manufacturing presence.
Silk Protein Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with recombinant platforms displacing traditional extraction in pharmaceutical channels while sericulture-dependent suppliers retain cosmetic formulation relationships. The market exhibits tiered concentration: fermentation-based innovators, integrated Chinese processors, and European formulation-grade specialists each occupy defended positions. Three archetypes dominate—biotech platforms decoupled from agricultural inputs, mulberry-clustered integrated producers, and downstream purification specialists serving premium skincare. Capacity expansion through dedicated fermentation lines and strategic partnerships for clean-label food additive formulation represent the dominant competitive moves.
Within the biotech platform tier, AMSilk GmbH and Bolt Threads exemplify recombinant production models that bypass traditional sericulture constraints. SEIWA KASEI Co., Ltd. anchors the cosmetic-grade specialist archetype with established positions in peptide isolation for premium skincare. Kraig Biocraft Laboratories represents the transitional hybrid model, maintaining sericulture linkages while developing enhanced silk variants through biotechnology. These three companies illustrate the competitive divergence between agricultural-dependent and fermentation-based supply architectures.
| Leading Market Players |
|---|
| Kraig Biocraft Laboratories |
| LANXESS |
| AMSilk GmbH |
| SEIWA KASEI Co., Ltd. |
| Huzhou Aotesi Biochemical |
| Spiber |
| Croda International Plc |
| Evonik |
| Bolt Threads |
| Others |
Supply Flow & Price Mechanics
Recombinant fermentation platforms are compressing cost curves while redrawing supply concentration away from mulberry-dependent extraction. This dual shift simultaneously weakens traditional sericulture pricing power and elevates microbial production facilities to volume leadership positions.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for pharmaceutical-grade fibroin. Contract-based long-term offtake agreements dominate industrial volumes, with price differentiation resting on ISO 10993 certification tier and molecular weight consistency. Cost compression in technical-grade sericin is intensifying because Zhejiang processors compete for cosmetic formulation contracts. Food additive buyers exhibit highest price sensitivity, while medical device scaffold procurement shows lowest elasticity due to qualification switching costs.
Supply Chain Analysis
Bioprocess engineering talent scarcity in Munich and Boston corridors constrains recombinant scale-up velocity. Supply concentrates in China, Germany, and the United States, with raw material dependencies spanning Bombyx mori cocoons, glucose feedstock, and chromatography resins. Single-source vulnerability runs through Zhejiang sericulture clusters exposed to climate stress. Distribution runs through formulation-grade chemical distributors for cosmetic channels and direct bioproduction contracts for pharmaceutical scaffolds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silk protein markets are entering a late-cycle quality phase where peptide-grade sericin specifications command sustainable premiums. Formulation houses now prioritize ECHA-registered supply over spot-priced technical alternatives.
For Market Incumbents: Hedge mulberry leaf input volatility by securing captive recombinant fermentation capacity in India or Germany. Anchor pharmaceutical channel control through ISO 10993 biocompatibility certification investments that elongate competitor qualification timelines. Defend against microbial platform entrants by locking multi-year cosmetic offtake with Seoul and Paris formulation houses.
For New Entrants and Emerging Players: Microbial sericin production at pharmaceutical purity tiers offers white-space entry against Zhejiang-dependent incumbents. Target India's PLI-supported fermentation infrastructure to bypass Chinese sericulture concentration. Lead go-to-market through clean-label food additive partnerships with plant-based meat brands seeking texture modification alternatives.
For Investors and Strategic Acquirers: Roll-up economics work for European cosmetic-grade purification specialists because REACH registration creates defensible moats against unqualified imports. Five-to-ten year viability hinges on biocompatibility certification reciprocity expanding across Swissmedic, TGA, and FDA jurisdictions. Monitor FDA biomaterial guidance harmonization progress as inflection signal for medical device scaffold valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Fermentation Scale-Up | AMSilk and Bolt Threads anchor pharmaceutical-grade output without sericulture constraints. |
| REACH Registration Investment | ECHA toxicological dossiers filter technical-grade imports, consolidating compliant European channels. |
| Long-Term Supply Agreement | Tier-one personal care brands secure multi-year recombinant allocations bypassing agricultural cycles. |
| Peptide-Grade Purification Capability | Downstream sericin isolation commands cosmeceutical premiums in Seoul and Paris formulation houses. |
| ISO 10993 Certification Pathway | Biocompatibility harmonization reduces multi-market burden for Boston and Basel medical device clusters. |
Methodological Framework
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each jurisdiction triangulated against secondary validation. Interviews with bioprocess engineering directors, cosmetic formulation chemists, pharmaceutical excipient procurement managers, and medical device regulatory affairs leads informed supply-side and demand-side assessments. Secondary sources included NMPA medical device filings, ECHA REACH registration databases, FDA biomaterial guidance documents, and FSSAI food-grade biopolymer standards. Bottom-up volume modeling across recombinant and sericulture production routes converged with top-down market sizing through trade flow analysis.
Granularity extended to product type, end user, application, and form dimensions, with additional modeling of molecular weight tier and certification grade for pharmaceutical channels. CAGRs were derived from segment-level volume trajectories weighted by purity-adjusted pricing. Forecast inputs incorporated PLI scheme implementation timelines, EU MDR substance disclosure rule phase-ins, and fermentation capacity expansion announcements from Munich and Heidelberg corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA biomaterial classification harmonization and climate stress on Zhejiang mulberry cultivation. Forecasts reflect documented assumptions on recombinant cost compression curves and regulatory reciprocity expansion. Material deviation in FDA guidance finalization or EU MDR enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Lithium Compound Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Sodium Stannate Market