
 Global Acetyls Market | 2026-2036
Global Acetyls Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acetyls Market Foresight
Market Context
Paint producers is pivoting toward low-VOC acetyl-based solvents as architectural coatings reformulate for stricter air quality standards. Celanese Corporation leverages its integrated methanol-to-acetic acid chain to control feedstock costs across Texas and Nanjing complexes. Eastman Chemical Company sustains leadership in cellulose ester derivatives through proprietary acetylation technology. BP plc anchors its acetyls position via the Hull acetic acid facility, which supplies European adhesive and coating compounders.
Technical Definition and Segment Structure
Acetyls comprise organic compounds containing the acetyl functional group (CH₃CO–), primarily manufactured through methanol carbonylation or acetaldehyde oxidation, with acetic acid serving as the foundational building block for anhydrides, esters, and cellulose derivatives across industrial chemistry. Vinyl acetate monomer dominates product type value generation due to its polymerization into emulsions for adhesives and paints, while ethyl acetate captures expanding share as a fast-evaporating solvent for flexible packaging inks. Pharmaceutical intermediates represent the fastest-growing application segment, driven by acetic anhydride demand for aspirin synthesis and active ingredient acetylation, whereas bulk tank packaging commands margin concentration through dedicated supply contracts with chemical plants.
Regulatory Frame and Outlook
The US EPA regulates acetic acid and anhydride emissions under the National Emission Standards for Hazardous Air Pollutants, while the EU REACH framework mandates registration and risk assessment for acetyl substance imports above one tonne annually. China's MEE enforces dual carbon goals that elevate energy efficiency requirements for coal-based acetic acid producers in Shandong and Jiangsu provinces. Stakeholders must monitor how carbon border adjustment mechanisms reshape cost competitiveness between Middle Eastern gas-based and Asian coal-based acetyl production routes.
Market Dynamics
Coal-to-acetic acid producers in China face mounting carbon intensity scrutiny under MEE dual carbon mandates, forcing capacity rationalization and feedstock switching toward natural gas and biomass routes that reshape global supply geography.
Growth Catalysts
- Waterborne coating reformulation:Paint manufacturers in India and Vietnam are substituting high-VOC solvents with acetyl esters to meet tightening architectural emissions standards. This pulls incremental acetic acid demand into Asian solvent blending facilities.
- REACH registration completion:European cellulose ester compounders secured full acetyl derivative dossier approvals, unlocking uninterrupted supply chains for pharmaceutical film coatings and cigarette filter tow.
- Methanol carbonylation yield improvements:Low-pressure rhodium-iodine catalysis now achieves selectivity above 99 percent, compressing unit production costs for acetic acid operators with integrated methanol supply.
Market Restraints
- Coal feedstock carbon pricing:Shandong and Jiangsu province acetic acid plants absorb rising carbon allowance costs under China's national ETS, eroding margin advantage versus Middle Eastern gas-based competitors.
- Acetic anhydride supply concentration:Three integrated chemical complexes control over 60 percent of merchant anhydride availability, creating bottleneck risk for aspirin and acetaminophen API manufacturers.
- Ethylene-vinyl acetate substitution in adhesives:Hot-melt formulators are testing metallocene polyolefin alternatives to reduce reliance on vinyl acetate monomer emulsion systems.
Strategic Opportunities
- Brazilian pharmaceutical manufacturing expansion:ANVISA's accelerated API approval pathways are attracting acetic anhydride investment for regional paracetamol and aspirin production serving Latin American markets.
- Bio-based acetic acid commercialization:Fermentation-derived acetic acid from wood waste feedstock qualifies for EU Green Deal sustainable chemistry procurement preferences in coating and adhesive applications.
- Direct-to-compounder bulk tank logistics:Dedicated rail and barge delivery systems bypass distributor markups for large adhesive and ink manufacturers in the US Gulf Coast corridor.
Industry Challenges
- Process control engineering scarcity:Methanol carbonylation unit operators face recruitment gaps for catalytic reaction optimization specialists, constraining debottlenecking timelines.
- Cellulose acetate tow certification delays:FDA Type II drug master file approvals for pharmaceutical-grade acetate flake extend qualification cycles for new supply sources.
- Legacy acetaldehyde oxidation asset stranding:European producers with dated ethylene-based acetic acid capacity confront retrofit economics against greenfield methanol carbonylation economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acetyls Market |
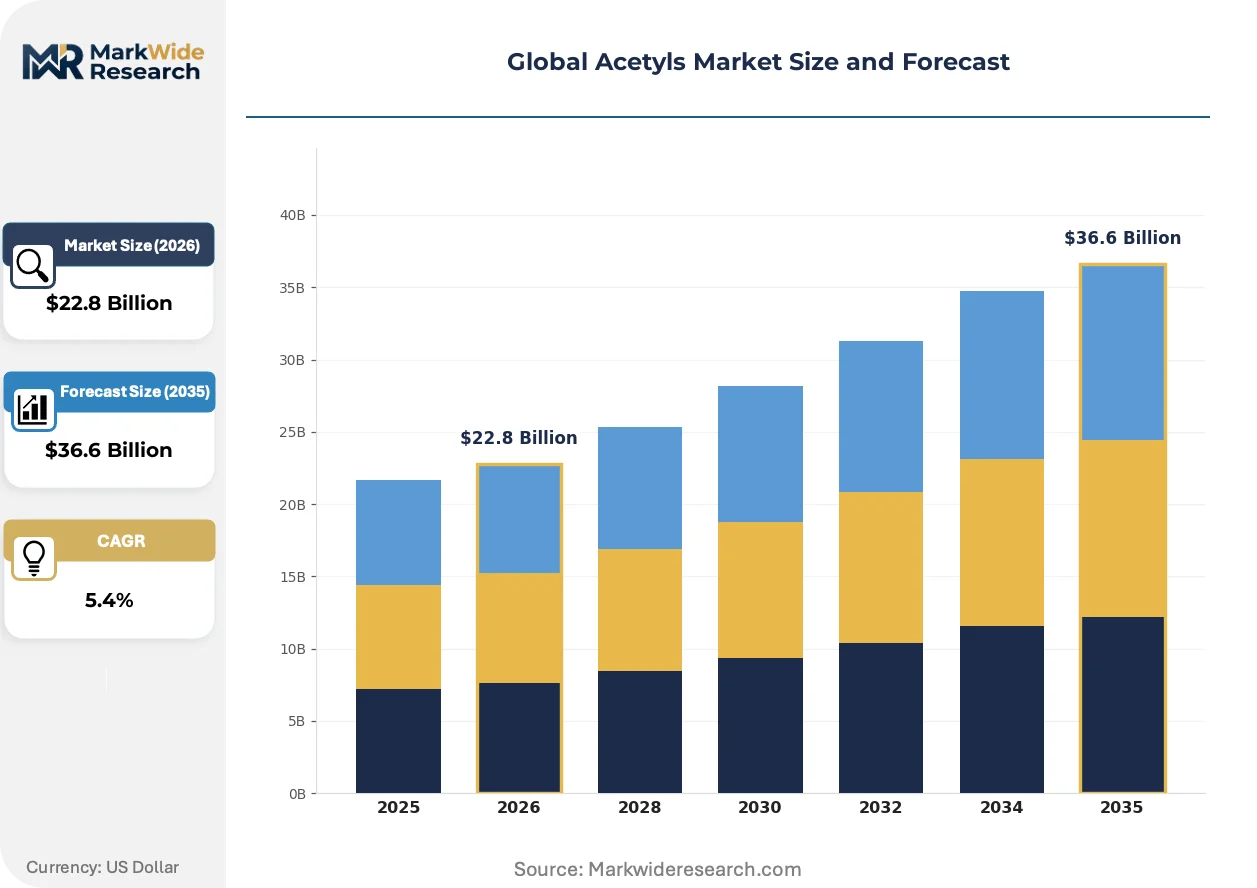
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $36.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Anhydride, Vinyl Acetate Monomer, Ethyl Acetate, Cellulose Acetate Application: Adhesives, Coatings, Solvents, Pharmaceutical Intermediates End User Industry: Textile Manufacturers, Paint Producers, Chemical Plants, Drug Formulators Packaging Type: Drums, Bulk Tanks, IBC Containers, Tankers |
| Companies Covered | Celanese Corporation, Eastman Chemical Company, LyondellBasell Industries Holdings B.V., BP plc, Wacker Chemie AG, Daicel Corporation, Dow Inc., SABIC, Saudi International Petrochemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acetyls Market Shifts & Advancements
Carbon accounting transparency is forcing acetyl supply chain restructuring, with buyers now requiring cradle-to-gate emissions documentation that favors low-carbon intensity production routes and penalizes coal-based chemistry.
Membrane-based acetic acid purification is overtaking traditional distillation sequences in new plant designs. This technology reduces steam consumption by 40 percent for concentration steps from dilute reactor output. Japanese engineering contractors are embedding these units into Southeast Asian greenfield projects, compressing energy intensity benchmarks that buyers now specify in tender documents.
EU F-Gas Regulation phase-down schedules are accelerating solvent selection reviews across European coating formulators. Acetyl esters with negligible global warming potential are displacing fluorinated solvents in precision electronics cleaning and aerospace coating applications. German automotive OEMs now mandate solvent sustainability scoring that elevates ethyl acetate and propyl acetate in approved material lists.
Specification consolidation among multinational paint manufacturers is compressing the number of approved acetyl solvent grades. Procurement teams at PPG, AkzoNobel, and Asian Paints now demand unified certificates of analysis across multiple production sites, forcing suppliers to harmonize quality systems. This standardization concentrates volume with integrated producers capable of multi-continent consistency.
Global Acetyls Market Segmentation
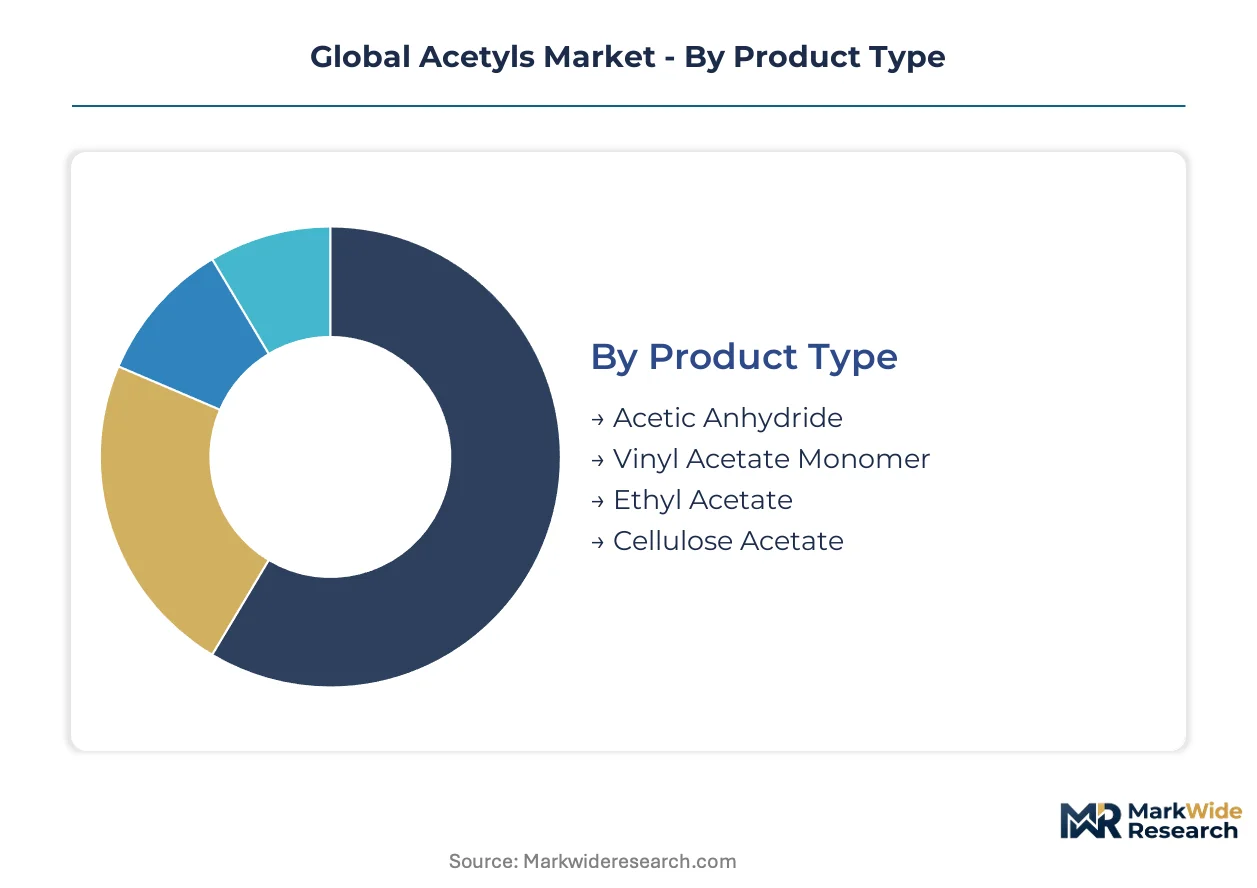
Acetyl derivatives serve divergent performance requirements across industrial chemistry, forcing suppliers to align product specifications with end-use purity standards and handling protocols. Segmentation reveals how vinyl acetate monomer and pharmaceutical intermediates pull capacity into fundamentally different margin structures and regulatory compliance regimes.
Product Type:
Buyers differentiate by molecular functionality and downstream processing intensity, with polymerization-grade monomers commanding distinct supply security terms versus reagent-grade anhydrides.
- Vinyl Acetate Monomer:Polymerizes into emulsion systems for waterborne adhesives and architectural coatings. Demand concentrates in India and Vietnam where paint producers reformulate for GB standard VOC compliance, pulling acetic acid into dedicated monomer trains.
- Acetic Anhydride:Serves as acetylating agent for aspirin synthesis and active pharmaceutical ingredient modification. Pharmaceutical manufacturers in Brazil and India absorb merchant supply under ANVISA and CDSCO accelerated approval pathways, creating bottleneck risk given production concentration.
- Ethyl Acetate:Fast-evaporating solvent qualifying for EU F-Gas replacement in electronics cleaning and flexible packaging inks.
- Cellulose Acetate:Derived from wood pulp acetylation for cigarette filter tow and pharmaceutical film coatings.
Volume sits with vinyl acetate monomer; growth tilts toward acetic anhydride.
Application:
Cost tier separation distinguishes commodity solvent sales from certified pharmaceutical-grade transactions with audit trail requirements.
- Pharmaceutical Intermediates:Acetic anhydride demand for paracetamol and aspirin API production climbs fastest under regulatory pressure for regional supply chain redundancy. CDSCO and ANVISA inspection protocols extend qualification timelines for new supply sources.
- Coatings:Waterborne architectural formulations in China and India substitute acetyl esters for high-VOC solvents under tightening MEE and state pollution control board mandates.
- Solvents:Ethyl acetate and propyl acetate displace fluorinated cleaning agents in German automotive OEM approved material lists.
- Adhesives:Vinyl acetate emulsion systems face substitution pressure from metallocene polyolefin hot-melt alternatives.
Margin concentrates in pharmaceutical intermediates; volume flows through coatings.
End User Industry:
Customer type determines contract structure, with multinational paint manufacturers imposing unified certificate of analysis requirements across multiple production sites.
- Paint Producers:PPG, AkzoNobel, and Asian Paints consolidate approved acetyl solvent grades, forcing suppliers to harmonize quality systems across Texas, Nanjing, and Rotterdam supply points. Procurement teams now mandate cradle-to-gate emissions documentation.
- Drug Formulators:Aspirin and acetaminophen API manufacturers face acetic anhydride supply concentration risk as three integrated complexes control majority merchant availability.
- Chemical Plants:Celanese and Eastman operate integrated methanol-to-derivatives chains capturing margin through feedstock cost control.
- Textile Manufacturers:Cellulose acetate fiber producers source flake under extended qualification cycles for FDA Type II drug master file compliance.
Procurement power concentrates with paint producers; technical barriers protect drug formulator supplier relationships.
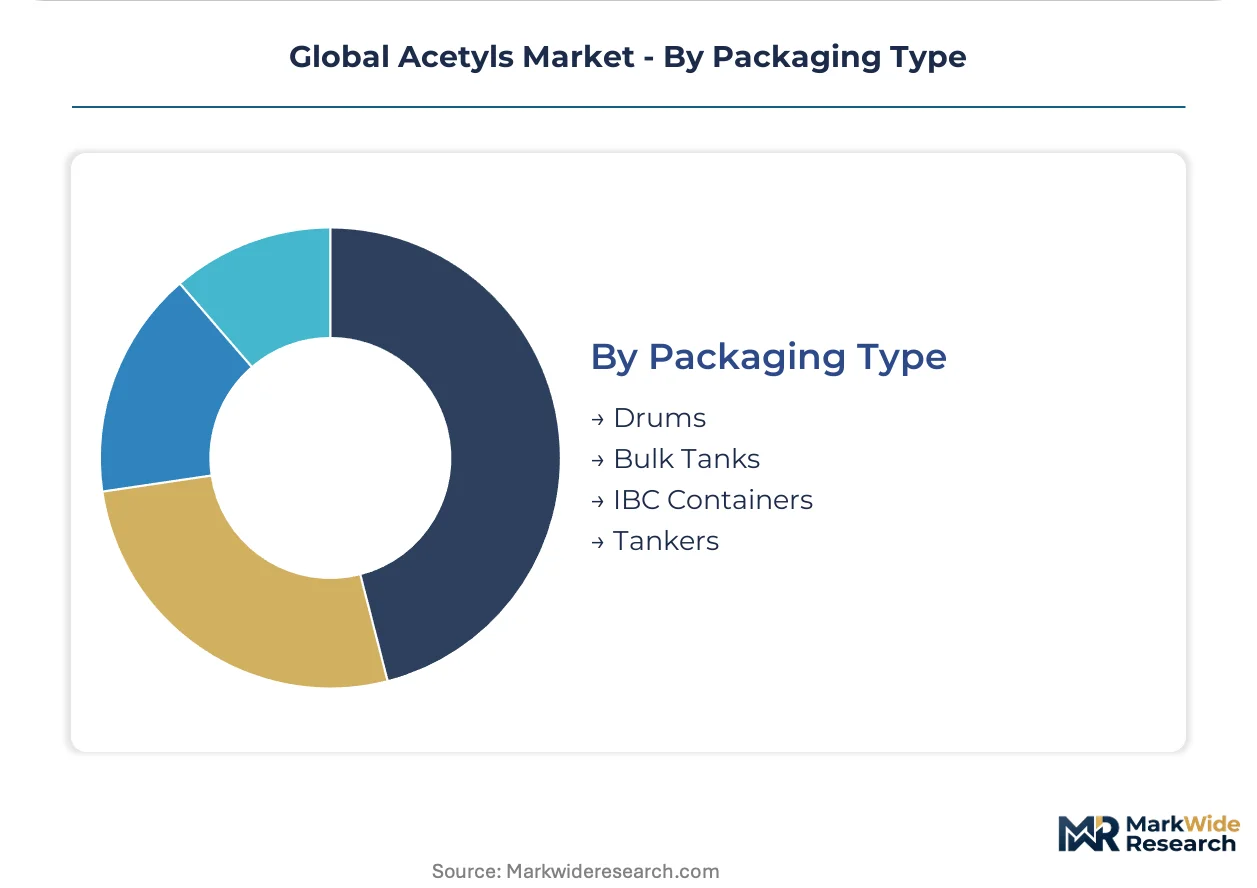
Packaging Type:
Supply concentration geography dictates logistics economics, with coastal chemical clusters favoring marine bulk delivery over drum repackaging.
- Bulk Tanks:Dedicated rail and barge systems serve US Gulf Coast adhesive and ink compounders, bypassing distributor markups through direct-to-manufacturer contracts. Hull and Nanjing facilities anchor Atlantic and Pacific bulk supply.
- Tankers:Deepwater vessels move acetic acid from Middle Eastern gas-based plants to European and Asian derivative manufacturers, reshaping competitiveness as EU carbon border adjustments phase in.
- Drums:Small-batch pharmaceutical and specialty coating applications require repackaging at regional distribution points.
- IBC Containers:Intermediate volumes serve mid-tier solvent blenders without dedicated tankage infrastructure.
Margin accumulates in bulk tanks; flexibility resides with drum packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in chemical manufacturing corridors concentrate acetyls capacity where feedstock integration and port access align. Tax incentives in coastal industrial parks accelerate methanol-to-acetic acid investments across Asia-Pacific and Middle Eastern production clusters.
China
Shandong and Jiangsu province chemical parks absorb rising carbon allowance costs under MEE dual carbon mandates, forcing coal-based acetic acid producers toward natural gas feedstock switching. GB standards on VOC emissions tighten formulation requirements for architectural coatings in Beijing and Shanghai metropolitan construction markets. The Yangtze River Delta cluster around Nanjing anchors integrated methanol carbonylation complexes serving domestic vinyl acetate monomer demand.
United States
Gulf Coast petrochemical corridors leverage shale gas economics for methanol-to-acetic acid production serving adhesive and coating compounders. EPA National Emission Standards for Hazardous Air Pollutants regulate acetic acid and anhydride emissions from Texas and Louisiana chemical facilities. Dedicated rail and barge bulk tank logistics bypass distributor markups for large solvent manufacturers concentrated along the Houston Ship Channel.
Germany
Automotive OEM sustainability scoring mandates elevate ethyl acetate and propyl acetate in approved material lists for precision electronics cleaning. EU F-Gas Regulation phase-down schedules accelerate solvent substitution reviews across coating formulators in Bavaria and Baden-Württemberg industrial regions. The Frankfurt-Rhine-Main chemical cluster serves pharmaceutical-grade acetic anhydride demand for regional API manufacturers under EMA inspection protocols.
India
Domestic chemical plants scale acetic anhydride output for pharmaceutical intermediate supply as CDSCO accelerates API approval pathways for paracetamol and aspirin production. State pollution control board mandates in Maharashtra and Gujarat push paint producers toward waterborne coating reformulation with acetyl ester solvents. The Mumbai-Pune industrial corridor concentrates vinyl acetate emulsion capacity serving construction sector adhesive demand.
Brazil
ANVISA accelerated API approval pathways attract acetic anhydride investment for regional pharmaceutical manufacturing serving Latin American markets. Import substitution policies elevate domestic acetic acid production for solvent blending facilities in São Paulo state chemical parks. The Camacari petrochemical complex in Bahia anchors acetyls derivative capacity for flexible packaging ink formulators.
Global Acetyls Market Competitive Landscape
Top-tier vendors anchor integrated methanol-to-derivatives chains, while mid-scale operators compete on regional feedstock access and specialty ester formulations. The market structure concentrates acetic anhydride merchant supply among three integrated chemical complexes controlling majority availability. Strategic archetypes include petrochemical conglomerates with backward methanol integration, cellulose ester specialists with proprietary acetylation technology, and regional gas-based producers leveraging carbon intensity advantages. Dominant competitive moves encompass capacity rationalization at coal-based legacy assets and membrane purification technology licensing for energy intensity reduction.
Within the integrated petrochemical tier, Celanese Corporation and Eastman Chemical Company exemplify archetypes of feedstock cost control through captive methanol supply and cellulose derivative specialization respectively. BP plc occupies a position representing European acetic acid production anchored at coastal facilities. These three entities demonstrate how geographic clustering around methanol sources and derivative demand centers shapes competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Celanese Corporation |
| Eastman Chemical Company |
| LyondellBasell Industries Holdings B.V. |
| BP plc |
| Wacker Chemie AG |
| Daicel Corporation |
| Dow Inc. |
| SABIC |
| Saudi International Petrochemical Company |
| Others |
Supply & Pricing Matrix
Methanol feedstock costs transmit directly from Gulf Coast shale gas corridors and Middle Eastern gas fields through acetic acid production tiers into pharmaceutical-grade anhydride premiums and commodity solvent spot markets. Carbon allowance pricing under China's national ETS and EU carbon border adjustment mechanisms now splits pricing bands between coal-based and gas-based production routes.
Pricing Analysis
Short lead-time premiums concentrate in pharmaceutical-grade acetic anhydride where CDSCO and ANVISA inspection protocols extend qualification timelines for new supply sources. Contract-based long-term offtake dominates vinyl acetate monomer procurement as paint manufacturers consolidate approved grades across PPG, AkzoNobel, and Asian Paints specifications. Price differentiation hinges on certification grade and volume scale, with FDA Type II drug master file compliance commanding substantial premiums over technical-grade material. Cost compression in commodity acetic acid is intensifying because Shandong and Jiangsu province producers absorb rising carbon allowance costs. Spot buyers in solvent blending exhibit highest price sensitivity; pharmaceutical API manufacturers show least sensitivity due to regulatory lock-in.
Supply Chain Analysis
Single-source vulnerability sits with merchant acetic anhydride availability where three integrated chemical complexes control majority supply. Production concentrates in China, the United States, and Saudi Arabia, with the Nanjing complex, Texas Gulf Coast corridor, and Jubail industrial city anchoring respective regional supply. Raw material dependencies draw from methanol feedstock, rhodium-iodine catalyst systems, and cellulose pulp for ester derivatives. Tariff exposure represents the dominant structural risk as EU carbon border adjustments phase in against Asian coal-based chemistry. Distribution runs through dedicated rail and barge bulk tank systems for US Gulf Coast adhesive compounders, with deepwater tankers serving transoceanic acetic acid movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
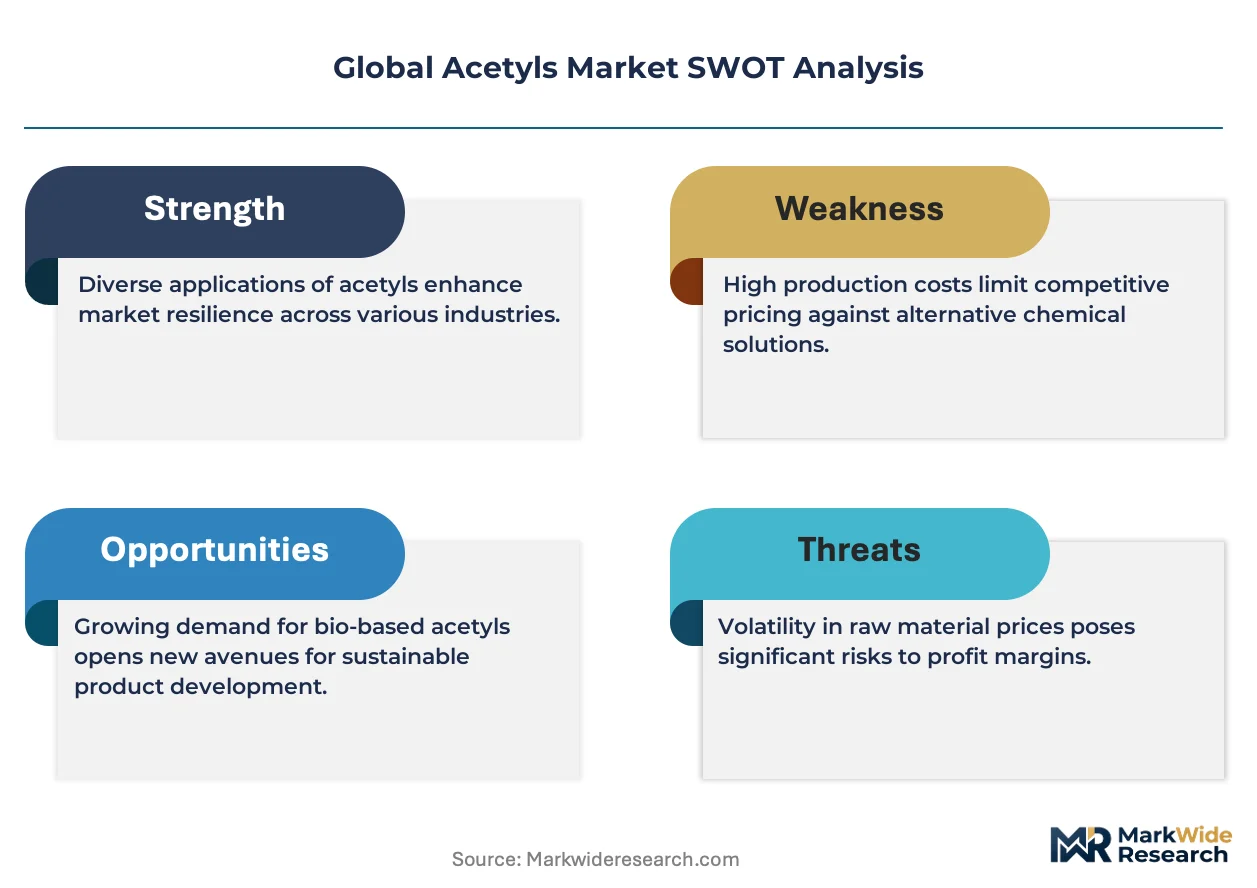
Acetic anhydride supply concentration creates a structural capacity bottleneck that props pricing power for qualified pharmaceutical-grade producers. This supply-constrained dynamic favors incumbents with regulatory certifications and integrated methanol chains.
For Market Incumbents: To counter metallocene polyolefin substitution pressure in hot-melt adhesives, Celanese and Eastman should accelerate membrane purification technology licensing for energy intensity reduction and secure backward integration into biomass-derived methanol for EU Green Deal compliance. Capacity addition in Brazilian chemical parks under ANVISA accelerated pathways offers geographic diversification against Chinese carbon pricing headwinds. For New Entrants and Emerging Players: Launch via direct-to-compounder bulk tank logistics bypassing distributor markups in the US Gulf Coast corridor where adhesive and ink manufacturers seek supply security. Brazilian pharmaceutical manufacturing expansion represents the most penetrable geography given ANVISA's accelerated API approval pathways and regional paracetamol demand growth. Bio-based acetic acid from wood waste feedstock offers a differentiated go-to-market angle for EU coating procurement preferences. For Investors and Strategic Acquirers: CDSCO approval of new acetic anhydride supply sources is the leading indicator that Indian pharmaceutical intermediate demand is structurally outpacing merchant capacity. Long-term viability centers on integrated methanol-to-derivatives chains with low-carbon intensity production routes. Acquisition targets should display captive methanol supply, multi-regional production footprints, and established regulatory dossiers under REACH and FDA Type II filings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Supply | Celanese captures feedstock cost control across Texas and Nanjing complexes against volatile spot methanol. |
| Green Manufacturing Transition | Fermentation-derived acetic acid from wood waste qualifies for EU Green Deal sustainable chemistry procurement preferences. |
| Long-term Supply Agreement | PPG and AkzoNobel consolidate approved acetyl solvent grades through unified certificate of analysis requirements. |
| Capacity Expansion | Indian chemical plants scale acetic anhydride output for CDSCO-accelerated paracetamol and aspirin API production. |
| Joint Venture | Japanese engineering contractors embed membrane purification units into Southeast Asian greenfield projects. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with plant managers, procurement leads at downstream paint and pharmaceutical manufacturers, distribution channel partners, and technical R&D directors with validation against SEC 10-K disclosures, Cefic chemical industry reports, and EPA emissions databases. Bottom-up capacity modeling triangulated against top-down demand aggregation across end-use industries.
Data-stream reconciliation across product type, application, end-use industry, and packaging format segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs derived from historical trajectory analysis modified by regulatory inflection points and feedstock switching economics. Industry-specific forecast inputs incorporated MEE dual carbon mandate implementation timelines and EU carbon border adjustment mechanism phase-in schedules.
Regulatory enforcement variability, feedstock price volatility, and substitution technology maturation are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding carbon pricing continuity and inspection protocol stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Thiocolchicoside Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Additive Masterbatch Market