
 Lithopone Market | 2026-2036
Lithopone Market Size, Share, and Industry Trends Forecast 2026-2036
Lithopone Market Analysis
The gap between premium-grade and commodity lithopone is restructuring procurement patterns across coatings supply chains. VB Technochemicals SA leverages captive barite sourcing to sustain margin stability in specialty grades. Venator Materials Plc anchors its position through sulfate-process expertise in high-purity segments. WuHu Loman Chemicals competes on volume scale in industrial-grade supply to domestic Asian markets.
Lithopone is a co-precipitated white pigment composed of zinc sulfide and barium sulfate, typically manufactured through controlled reaction of zinc sulfate with barium sulfide followed by calcination, filtration, and milling to achieve particle sizes between 0.3 and 0.5 microns. Its primary industrial purpose centers on providing opacity, brightness, and UV resistance in systems where titanium dioxide cost or performance constraints apply. Coating lithopone leads volume demand as architectural and industrial paint formulators seek partial TiO2 replacement, while masterbatch lithopone represents the fastest-growing segment as polymer processors adopt sulfate-compatible white concentrates. Premium grade commands the strongest margin pool due to stringent heavy metal limits in food-contact and toy-coating applications.
China's SAMR enforces GB standards limiting soluble barium and zinc migration in consumer-goods coatings, directly elevating qualification barriers for export-oriented producers. REACH registration requirements in Europe and EPA toxicity testing protocols in the United States further fragment market access by grade and end-use certification. Stakeholders must monitor evolving heavy metal thresholds across major importing jurisdictions to align R&D spending with shifting compliance premiums.
Market Dynamics
China's SAMR enforcement of GB standards on heavy metal migration is bifurcating supplier tiers, forcing coatings formulators to requalify pigment sources against stricter soluble barium and zinc thresholds or exit food-contact and toy-coating segments entirely.
Growth Catalysts
- REACH Registration Tiering:ECHA's differentiated dossier requirements for high-purity lithopone grades are accelerating consolidation among European coatings specialists seeking full substance compliance.
- Architectural Coatings Substitution:Paint formulators in China's Shandong-Jiangsu corridor are expanding lithopone loading rates to offset titanium dioxide cost volatility in exterior emulsion systems.
- Masterbatch Polymer Processing:Sulfate-process lithopone is displacing alternative white concentrates in polyolefin compounding lines where UV stability and dispersion uniformity command premium specifications.
Market Restraints
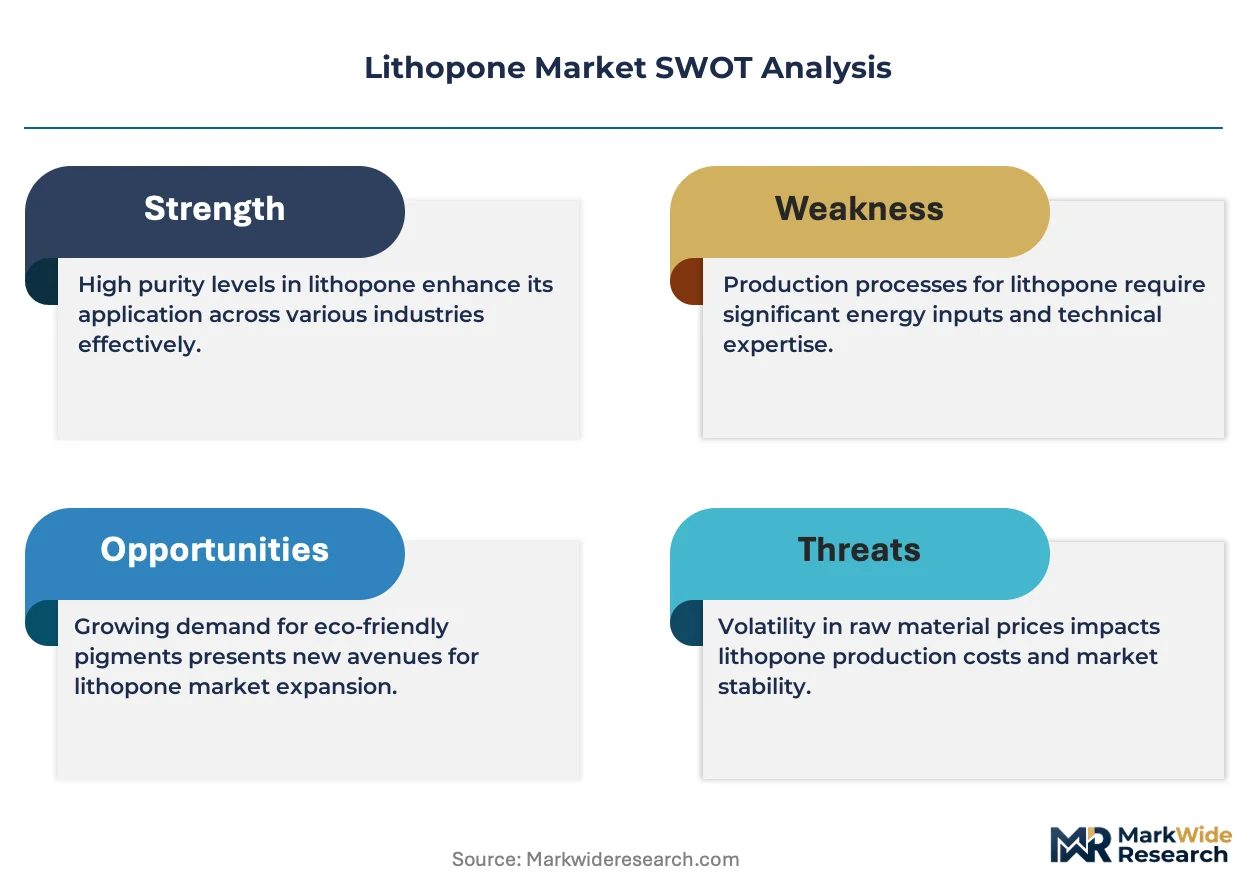
- Barite Supply Concentration:Captive sourcing of high-grade barium sulfate concentrates among three major chemical conglomerates limits independent pigment producers' margin flexibility.
- EPA Toxicity Testing Protocols:Extended 90-day inhalation study requirements for new lithopone entrants are compressing the viable supplier pool in US industrial coatings.
- Titanium Dioxide Price Recovery:Chloride-process TiO2 capacity restarts in select Gulf Coast facilities are partially reversing substitution economics in mid-tier architectural formulations.
Strategic Opportunities
- India PLI Scheme Alignment:Specialty chemicals incentives under India's production-linked incentive framework are attracting sulfate-process investment for domestic coatings supply.
- Food-Contact Certification Gap:Heavy metal migration testing protocols for direct-contact polymer applications remain underdeveloped, creating first-mover advantage for qualified pigment suppliers.
- Digital Color Matching Integration:Spectrophotometric formulation software is embedding lithopone opacity curves, enabling real-time substitution optimization in automated tinting systems.
Industry Challenges
- Calcination Energy Intensity:Natural gas-fired rotary kiln operations face escalating carbon accounting scrutiny under EU ETS Phase IV compliance timelines.
- Particle Size Distribution Control:Sub-0.3 micron milling consistency demands capital-intensive jet mill arrays that strain mid-tier producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithopone Market |
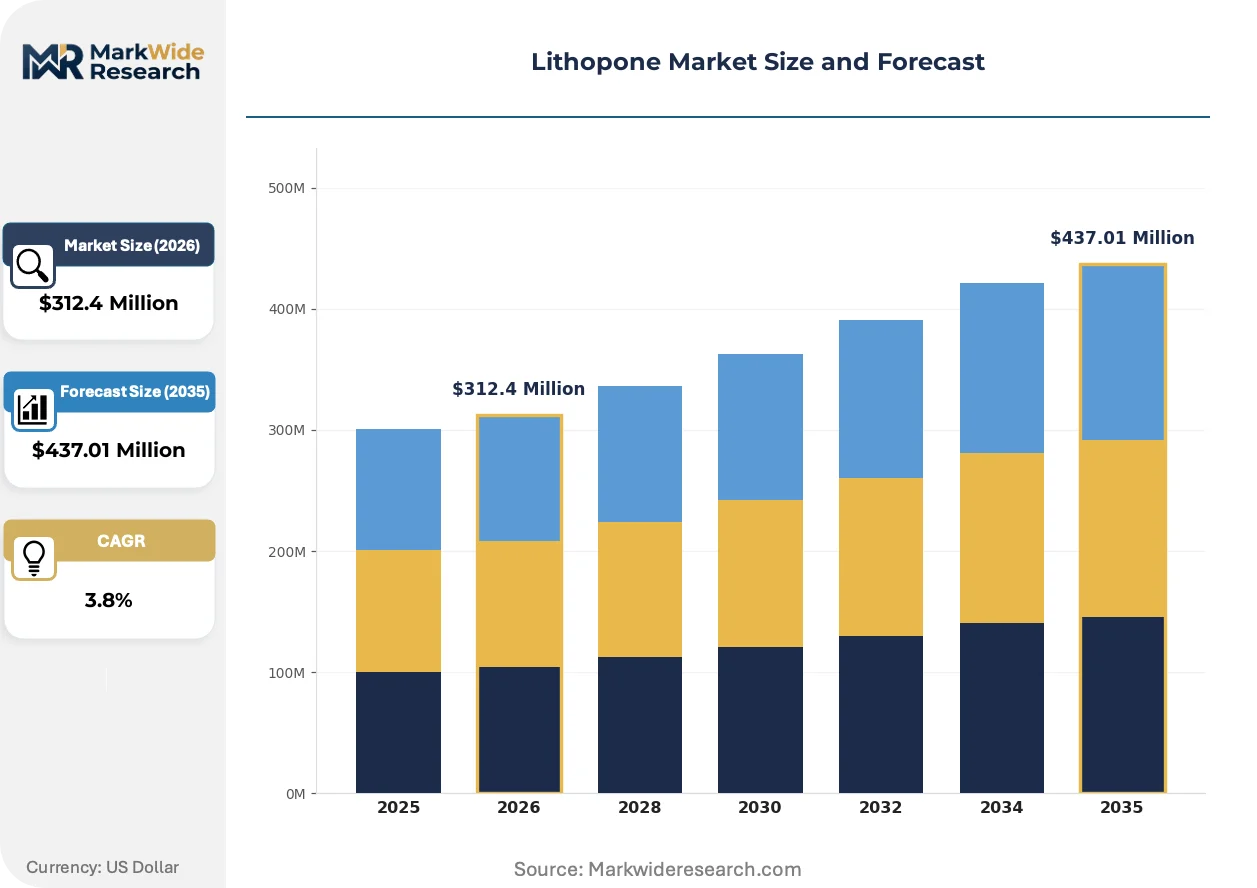
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Grade Lithopone, Industrial Lithopone, Coating Lithopone, Masterbatch Lithopone End Use Industry: Paints, Plastics, Rubber, Inks Grade: Standard Grade, Premium Grade, Specialty Grade, Others Packaging Type: Bag, Bulk, Drums, Jumbo Bags |
| Companies Covered | VB Technochemicals SA, Kremer Pigments, Anhui Union Titanium Enterprise Co., Ltd, Venator Materials Plc, American Elements, Zhengzhou Vidar Water Industrial Co., Ltd, Fengchen Group Co. Ltd., Langfang Pairs Horses Chemical Co. Ltd., WuHu Loman Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithopone Market Emerging Trajectories
Reformulation software and spectrophotometric systems are embedding lithopone opacity databases, enabling dynamic substitution algorithms that compress titanium dioxide loading decisions from weeks to real-time production adjustments.
Surface-modified lithopone grades with silane coupling agent treatments are integrating into high-shear masterbatch compounding lines. Polymer processors serving automotive interior specifications are adopting these modified pigments at accelerating rates. The technology is integrating dispersion stability metrics directly into compounder qualification protocols, compressing trial-batch cycles.
China's GB standards evolution on soluble heavy metal migration is tightening testing frequency requirements for export-oriented coatings facilities. SAMR inspection protocols now mandate third-party laboratory certification for each production lot destined for consumer goods applications. Toy-coating and food-contact segments are responding by segregating supply chains into dedicated high-purity production streams.
Coatings procurement teams are consolidating pigment specifications around dual-certified grades acceptable across multiple jurisdiction import regimes. Large architectural paint manufacturers are displacing fragmented multi-source strategies with preferred supplier frameworks. This concentration is most visible among German and Dutch formulators supplying cross-border EU retail chains.
Lithopone Market Segmentation
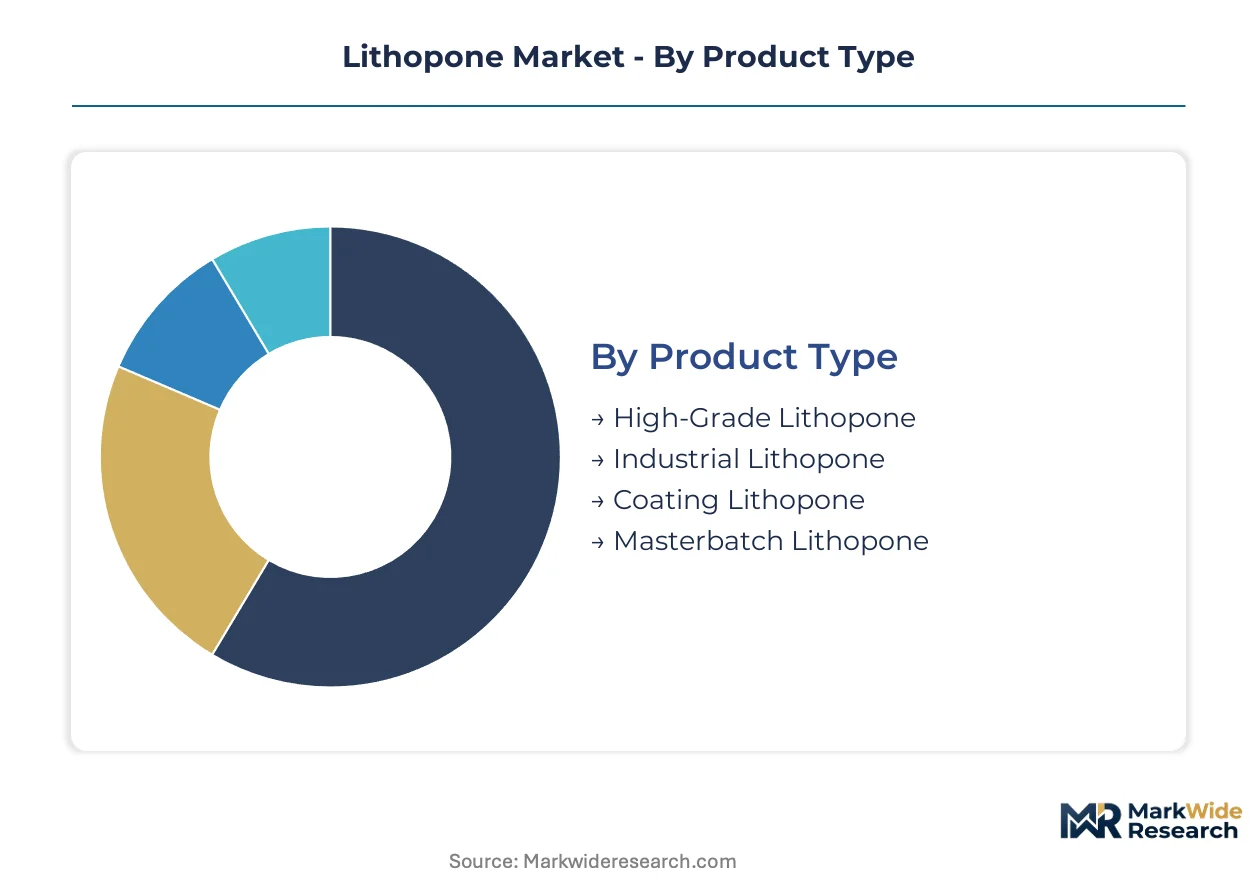
Lithopone's technical versatility creates distinct value pools across purity tiers and application formats. Formulators select grades based on heavy metal thresholds, dispersion requirements, and TiO2 substitution economics in specific end-use systems.
Product Type:
Customization intensity varies sharply across this category, from commodity volume grades to precision-engineered polymer concentrates.
- Coating Lithopone:Engineered for opacity and UV resistance in water-based and solvent-borne paint systems. Demand concentrates among architectural formulators in China's Shandong-Jiangsu corridor seeking partial titanium dioxide replacement in exterior emulsion coatings. SAMR's GB standards on soluble heavy metal migration are elevating qualification barriers for export-oriented production lots.
- Masterbatch Lithopone:Sulfate-process concentrates optimized for high-shear polyolefin compounding with superior dispersion uniformity. Polymer processors serving automotive interior specifications are adopting surface-modified grades at accelerating rates as UV stability requirements tighten.
- High-Grade Lithopone:Ultra-low heavy metal variants meeting food-contact and toy-coating certification protocols.
- Industrial Lithopone:Cost-optimized grades for general-purpose coatings and fillers where premium specifications are unnecessary.
Most installed capacity flows through Coating Lithopone. Expansion is steepest in Masterbatch Lithopone.
End Use Industry:
Application maturity determines margin structure, with established coatings segments competing against faster-evolving polymer processing demand.
- Paints:Dominates volume absorption across architectural, industrial, and automotive refinish formulations. Formulators in Asia-Pacific manufacturing corridors are expanding loading rates to offset titanium dioxide cost volatility.
- Plastics:Masterbatch compounding for polyolefin automotive components and consumer goods. Silane surface-modified lithopone is displacing alternative white concentrates where dispersion stability commands premium specifications.
- Rubber:White pigment reinforcement in tire sidewalls and technical rubber goods requiring UV aging resistance.
- Inks:Specialty lithopone grades for flexographic and gravure printing systems demanding fine particle distribution control.
Paints retains the largest share of consumption. Plastics demonstrates the most rapid demand acceleration.
Grade:
Certification tiering fragments supplier pools, with premium grades commanding substantial margin premiums over commodity alternatives.
- Premium Grade:Engineered to sub-0.3 micron particle size with stringent soluble barium and zinc limits. Food-contact and toy-coating applications in export-oriented Chinese facilities require third-party laboratory certification for each production lot under SAMR inspection protocols.
- Specialty Grade:Custom-formulated variants for specific polymer compatibility or optical performance targets. REACH registration tiering at ECHA is accelerating consolidation among European coatings specialists seeking full substance compliance for high-purity segments.
- Standard Grade:General-purpose lithopone for industrial coatings and fillers without consumer-goods contact requirements.
- Others:Niche formulations including experimental surface modifications and regional specification variants.
Premium Grade commands the strongest margin pool. Specialty Grade is climbing the fastest as qualification requirements proliferate.
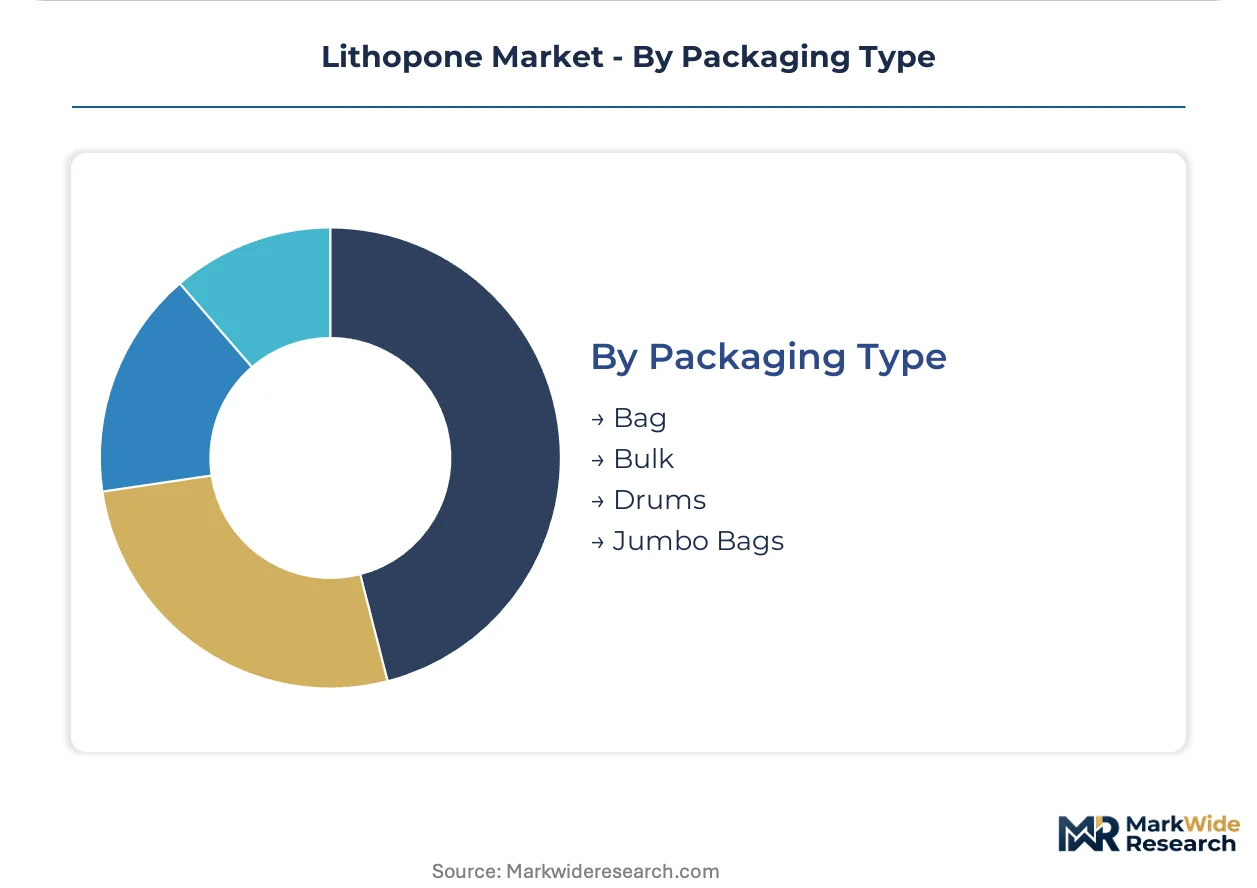
Packaging Type:
Logistics economics and handling automation requirements differentiate format selection across customer scale and geographic reach.
- Bulk:Tanker or silo delivery for large-scale coatings manufacturers with integrated pigment handling systems. India's PLI scheme incentives for specialty chemicals are attracting sulfate-process investment targeting domestic bulk supply to coatings producers.
- Jumbo Bags:Intermediate bulk containers for mid-tier formulators seeking reduced handling labor without full bulk infrastructure.
- Bags:Conventional 25-50 kg multiwall paper sacks for smaller batch operations and regional distributors.
- Drums:Steel or fiber containers for moisture-sensitive grades and specialty formulations requiring sealed storage.
Bulk dominates volume throughput for integrated manufacturers. Jumbo Bags are gaining share fastest among mid-tier processors automating material handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineering talent clusters in Germany's Rhine-Ruhr corridor and China's Yangtze Delta anchor lithopone formulation expertise. Process engineers with sulfate-calcination specializations concentrate in these regions, driving technical standards for high-purity grades.
China
Architectural coatings manufacturers in Shandong and Jiangsu provinces absorb the majority of regional lithopone volume. SAMR's GB standards on soluble barium and zinc migration enforce third-party laboratory certification for each export production lot. The eastern manufacturing corridor is requalifying pigment sources against stricter heavy metal thresholds or exiting food-contact segments entirely.
Germany
Coatings specialists serving cross-border EU retail chains consolidate procurement around dual-certified grades acceptable across multiple jurisdiction import regimes. ECHA's REACH registration tiering accelerates consolidation among formulators seeking full substance compliance for high-purity segments. The Rhine-Ruhr industrial belt hosts integrated pigment handling systems for bulk delivery to large-scale manufacturers.
United States
Industrial coatings formulators face compressed viable supplier pools as EPA toxicity testing protocols mandate extended 90-day inhalation studies for new lithopone entrants. Chloride-process TiO2 capacity restarts in select Gulf Coast facilities partially reverse substitution economics in mid-tier architectural formulations. The Southeast manufacturing belt balances TiO2 cost volatility against lithopone loading rate adjustments.
India
Specialty chemicals incentives under the PLI scheme attract sulfate-process investment targeting domestic coatings supply. Bulk infrastructure investments serve large-scale manufacturers with integrated pigment handling systems. The Gujarat-Maharashtra industrial corridor develops captive barite sourcing relationships to sustain margin stability in specialty grades.
Japan
Automotive interior polymer processors adopt surface-modified lithopone grades at accelerating rates as UV stability requirements tighten. METI oversight of chemical substance management aligns with REACH-equivalent standards for export-oriented production. The Nagoya industrial zone concentrates high-shear masterbatch compounding lines serving tier-1 automotive suppliers.
Lithopone Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the lithopone value chain. Integrated chemical conglomerates with captive barite sourcing sustain margin stability against independent pigment producers facing raw material concentration constraints. Three archetypes dominate: sulfate-process specialists leveraging technical expertise, volume-scale operators serving domestic Asian markets, and premium-grade purveyors targeting food-contact certification gaps. Competitive moves center on backward integration into barium sulfate concentrates and strategic partnerships with coatings formulators for real-time substitution optimization.
Within the premium-grade tier, VB Technochemicals SA and Venator Materials Plc exemplify positioning around stringent heavy metal limits and REACH registration compliance. WuHu Loman Chemicals occupies a volume-scale archetype serving industrial-grade demand across domestic Asian markets. These three anchors illustrate how supplier qualification requirements under China's SAMR protocols and ECHA's tiered dossier demands fragment competitive pools by certification tier rather than geography alone.
| Leading Market Players |
|---|
| VB Technochemicals SA |
| Kremer Pigments |
| Anhui Union Titanium Enterprise Co., Ltd |
| Venator Materials Plc |
| American Elements |
| Zhengzhou Vidar Water Industrial Co., Ltd |
| Fengchen Group Co. Ltd. |
| Langfang Pairs Horses Chemical Co. Ltd. |
| WuHu Loman Chemicals |
| Others |
Supply Flow & Price Mechanics
Captive barite sourcing among three major chemical conglomerates anchors both supply security and pricing power across premium lithopone tiers. This backward integration into high-grade barium sulfate concentrates insulates integrated producers from spot volatility while compressing margin flexibility for independent pigment manufacturers.
Pricing Analysis
Product-plus-certification bundling separates delivered pigment from compliance documentation costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by heavy metal certification stringency and REACH registration completeness. Cost compression in standard-grade supply is intensifying because chloride-process TiO2 restarts in US Gulf Coast facilities partially reverse substitution economics. Mid-tier architectural formulators exhibit highest price sensitivity, while food-contact certified buyers accept substantial premiums for lot-traceable documentation.
Supply Chain Analysis
Direct-to-coatings-manufacturer channels handle volume demand from Shandong-Jiangsu corridor formulators, while specialty distributors serve fragmented masterbatch compounders. Production gravity centers on China, Germany, and India as sulfate-process engineering talent clusters concentrate in Rhine-Ruhr and Yangtze Delta regions. Raw material sourcing draws from high-grade barite deposits, zinc sulfate refineries, and natural gas feedstock for calcination operations. Single-source vulnerability in barium sulfate concentrate supply creates structural exposure for non-integrated producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium-grade certification tiers as SAMR inspection protocols and ECHA REACH tiering elevate compliance premiums. TiO2 cost volatility sustains substitution-driven volume growth in mid-tier architectural coatings.
For Market Incumbents: Acquire captive barite mining assets or long-term offtake agreements to defend against raw material concentration risk. Expand high-purity calcination capacity in China's eastern manufacturing corridor to capture food-contact certification premiums. Consolidate around dual-certified grade portfolios acceptable across EU and Asia-Pacific import regimes. For New Entrants and Emerging Players: Begin with surface-modified lithopone grades for automotive interior masterbatch applications, where silane coupling agent expertise creates differentiation barriers. India's PLI scheme incentives for specialty chemicals offer penetrable white-space for sulfate-process investment. Target domestic bulk supply relationships with Gujarat-Maharashtra coatings manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale sulfate-process specialists because ECHA dossier requirements and SAMR inspection protocols fragment supplier pools by certification tier. Five-to-ten year viability favors producers with backward integration into barium sulfate concentrates and real-time formulation software partnerships. Watch TiO2 price recovery velocity as inflection indicator for substitution economics reversal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Mining | Captive concentrate supply insulates margin stability against raw material oligopoly concentration. |
| High-Purity Calcination Capacity Expansion | Additional kiln capacity in Shandong-Jiangsu corridor captures food-contact certification demand. |
| Surface Modification Technology Investment | Silane coupling agent R&D enables automotive interior masterbatch specification compliance. |
| Dual-Certification Grade Consolidation | REACH-GB aligned portfolios reduce requalification friction for cross-border coatings supply. |
| Real-Time Formulation Software Partnership | Spectrophotometric integration compresses TiO2 substitution decisions from weeks to production-line adjustments. |
Methodological Framework
Multiple input streams — plant manager interviews, procurement lead surveys, customs trade records, and SEC chemical sector filings — were reconciled to construct demand and supply estimates. Primary engagement with coatings formulators, masterbatch compounders, and sulfate-process engineering directors informed operational assumptions. Secondary validation drew from ECHA registration databases, SAMR inspection protocol documentation, and Cefic specialty chemicals reports. Bottom-up capacity modeling and top-down end-use consumption estimates were cross-checked for triangulation.
Data-stream reconciliation across grade tier, end-use industry, packaging format, and regional production hub dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segmented growth rate blending weighted by base-year consumption shares. Forecast inputs incorporated TiO2 price trajectory scenarios, GB standards evolution timelines, and PLI scheme incentive uptake rates across India and comparable jurisdictions.
Several conditions sit outside the modeled scope, including force majeure disruptions to barite concentrate supply, abrupt TiO2 technology breakthroughs, and unilateral regulatory threshold revisions. Forecasts reflect assumptions about sustained substitution economics and certification protocol stability. Periodic stress-testing of base assumptions against SAMR enforcement intensity and ECHA dossier acceptance rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
Chromatography Silica Resins Market
Specialty Compounds
Lentein Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Liquid Ammonium and Liquid Potassium Thiosulfate Market
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Acetyl Tyrosine Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
India Sealants Market