
 Potassium Monopersulfate (KMPS) Market | 2026-2036
Potassium Monopersulfate (KMPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Monopersulfate (KMPS) Market Analytics
Aftermarket service revenue for oxidation system maintenance is reshaping margin distribution across the KMPS value chain. Lanxess sustains strong positions in European industrial supply through captive peroxide chemistry integration. Mitsubishi Gas Chemical Company dominates Japanese pharmaceutical-grade KMPS production with exacting purity controls. Chemours Company leverages fluoropolymer-adjacent oxidation expertise to anchor North American industrial accounts.
Potassium monopersulfate is a white, crystalline, triple-salt peroxymonosulfate compound (2KHSO5·KHSO4·K2SO4) with an active oxygen content near 4.5%, manufactured through controlled electrolysis of potassium sulfate solutions and employed primarily as a powerful, halogen-free oxidizer and disinfectant across water treatment, electronics etching, and pool sanitation. Powder formulations lead volume shipments due to handling efficiency in bulk industrial oxidation, while tablet formats capture premium pricing in recreational water and aquaculture where dosing precision governs regulatory compliance. Water treatment applications absorb the fastest-growing demand segment as utilities confront tightening discharge limits on chlorinated organics.
EPA drinking water regulations and EU REACH chemical authorization frameworks jointly elevate KMPS against chlorine alternatives by restricting trihalomethane formation in treated effluent. China's MEE wastewater discharge standards and Japan's METI chemical substance reporting obligations further segment product grades across geographies. Buyers must monitor regulatory divergence between halogen-free oxidation mandates and emerging peroxide residual limits to secure formulation registrations ahead of compliance deadlines.
Market Dynamics
Halogen-free oxidation mandates across municipal water utilities are restructuring procurement specifications, forcing chlorine displacement at treatment facilities facing trihalomethane discharge limits.
Growth Catalysts
- EPA Stage 2 DBP Rule:Federal limits on chlorinated disinfection byproducts compel US municipal utilities to certify KMPS for primary oxidation duty.
- Electronics etching demand:Semiconductor fabrication in Taiwan and South Korea requires ultra-high-purity KMPS for wafer surface preparation without metallic contamination.
- Industrial water reuse intensity:China's MEE wastewater discharge standards for heavy manufacturing zones mandate closed-loop oxidation systems.
Market Restraints
- Potassium sulfate feedstock volatility:Electrolysis-grade K2SO4 supply concentrates in Chilean and German mining operations, exposing margins to fertilizer-market arbitrage.
- Peracetic acid substitution:Food and beverage processors in regulated markets pivot to PAA for CIP sanitation where residual oxygen specifications are less stringent.
- Active oxygen degradation:KMPS potency degrades 15-20% annually under ambient storage, constraining inventory positioning and working capital cycles.
Strategic Opportunities
- Aquaculture expansion in Vietnam:Shrimp farming operations lack oxidation infrastructure; tablet-format KMPS penetrates pond-dosing protocols ahead of chlorine regulation.
- EU F-Gas Regulation phase-down:Fluorinated oxidizer restrictions in cold-chain sanitation create substitution openings for KMPS in food logistics.
- On-site generation systems:Electrolytic KMPS synthesis units bypass transport-degradation losses for remote mining camps and offshore platforms.
Industry Challenges
- Electrochemical engineering scarcity:Peroxymonosulfate synthesis requires specialized anode design expertise concentrated in legacy chlor-alkali engineering pools.
- Multi-jurisdiction registration synchronization:Separate EPA, REACH, and NMPA substance dossiers demand 18-24 month compliance timelines for new formulation grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Monopersulfate (KMPS) Market |
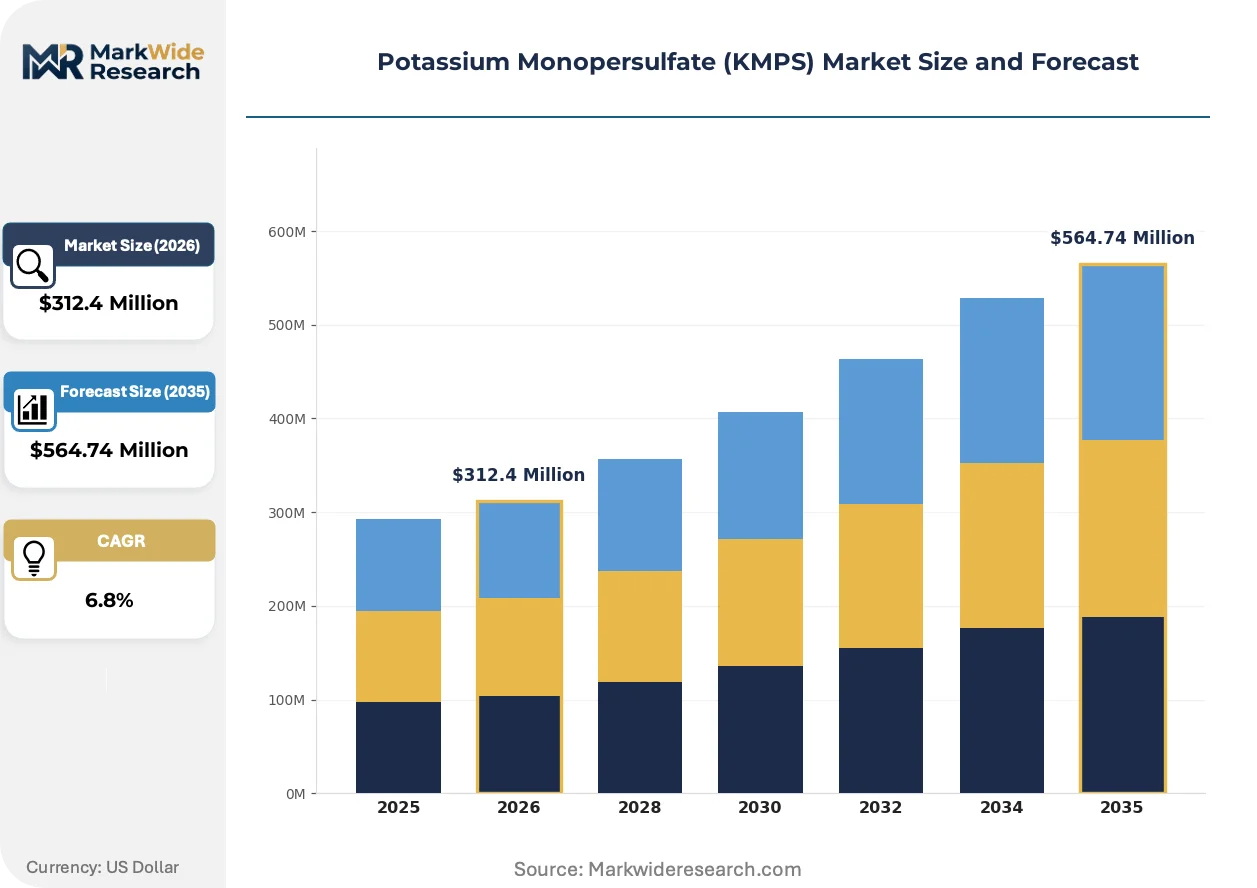
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Liquid, Tablets Application: Cleansing Agents, Disinfectants, Oxidizers, Water Treatment End User: Household, Industrial, Commercial, Agricultural Distribution Channel: Online Sales, Retail, Direct Sales, Distributors |
| Companies Covered | Shanghai Future Chemical, Haihang Industry, Lanxess, Chemours Company, Ansin Chemical, United Initiators, VR Persulfates, Mitsubishi Gas Chemical Company, Shangyu Jiehua Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Monopersulfate (KMPS) Market Evolving Landscape
Stabilized triple-salt formulations and precision-dosing hardware are converging to displace legacy oxidation chemistries in regulated water treatment environments.
Encapsulated KMPS granules with controlled-release coatings are rendering obsolete conventional powder handling systems at municipal treatment plants. Ohio and Pennsylvania utilities pilot these formats to eliminate dust exposure and dosing variance. The technology compresses operator training requirements while extending effective shelf life in humid climates.
EU REACH authorization timelines for peroxide-based substances are tightening substance volume tracking obligations across industrial supply chains. German chemical distributors now require downstream user declarations for KMPS tonnage thresholds. Electronics-grade specifications face heightened analytical documentation for trace metal content.
Specification-driven buying committees at North American water utilities now unbundle chemical supply from oxidation system maintenance contracts. Equipment OEMs capture recurring revenue streams while commodity suppliers compete on certified purity tiers. California and Texas municipalities lead this service-model transition.
Potassium Monopersulfate (KMPS) Market Segmentation
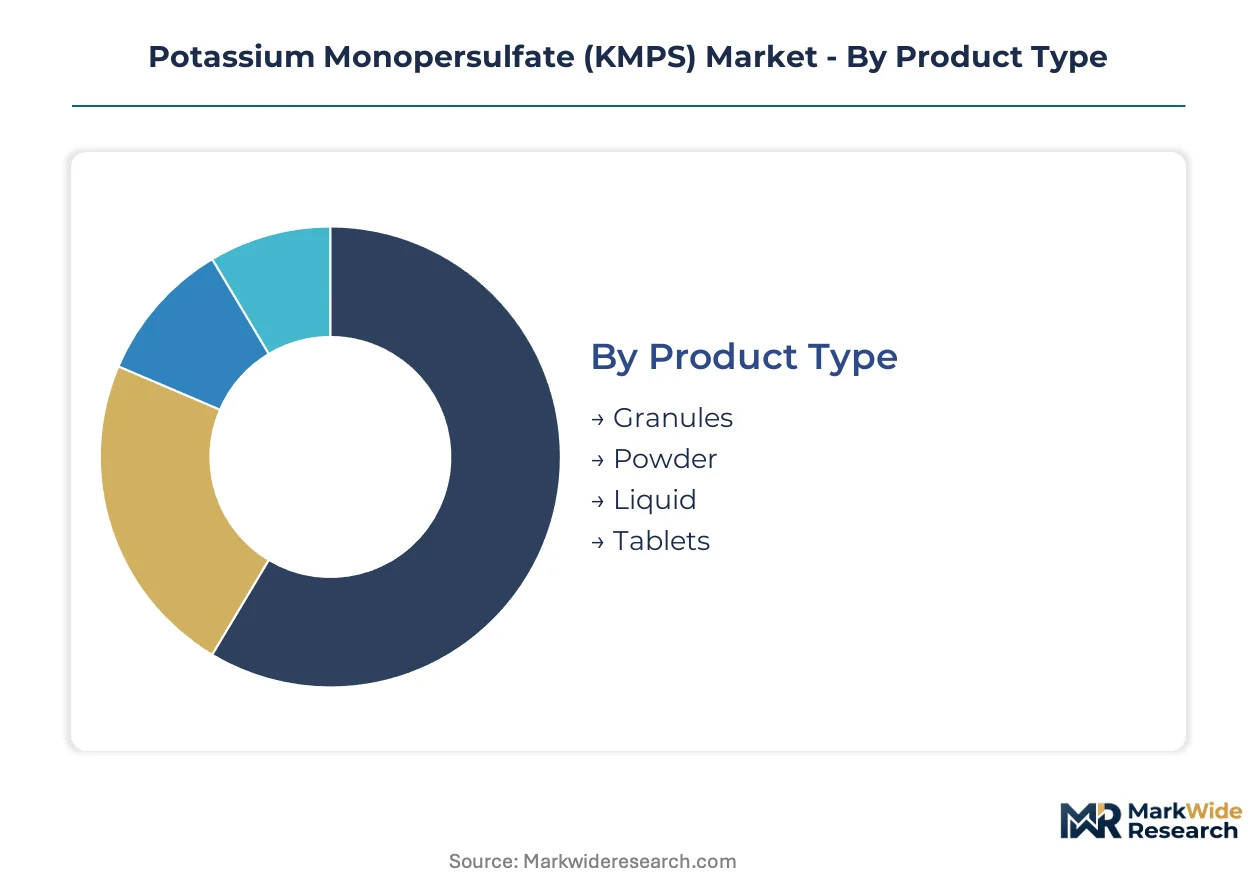
Segmentation in the KMPS market tracks how formulation formats, application intensity, and procurement channels diverge across regulatory environments and end-use specifications. Buyers select grades based on active oxygen stability, dosing precision requirements, and compliance documentation burdens.
Product Type:
The use-case spectrum spans bulk industrial oxidation requiring high-volume handling efficiency through precision-dosing formats for regulated recreational and food-contact applications.
- Powder:Free-flowing crystalline triple-salt with 4.5% active oxygen content, engineered for pneumatic conveying systems at municipal water treatment facilities. Demand concentrates in German and Chinese industrial utilities where bulk oxidation capacity governs procurement decisions against chlorine displacement mandates.
- Tablets:Compressed single-dose formats with controlled dissolution rates, manufactured to exacting dimensional tolerances for automated feeders. Recreational water facilities in Florida and Arizona specify tablet formats to meet EPA Stage 2 DBP Rule compliance with minimal operator training overhead.
- Granules:Intermediate particle size distribution for intermediate-scale oxidation systems requiring dust suppression without full encapsulation.
- Liquid:Pre-dissolved aqueous solutions for CIP sanitation in food processing where powder handling is restricted.
The dominant share belongs to Powder, while Tablets is closing the gap fastest.
Application:
Cost tier differentiation separates commodity oxidation from premium disinfection grades demanding certified purity documentation.
- Water Treatment:Primary oxidation duty at municipal utilities confronting trihalomethane discharge limits under EPA and EU frameworks. US and German utilities are expanding certified KMPS substitution for chlorine in surface water treatment trains.
- Oxidizers:Electronics-grade specifications for semiconductor wafer surface preparation, requiring sub-ppb metallic contamination controls. Taiwan and South Korean fabrication facilities specify ultra-high-purity grades for advanced node production.
- Disinfectants:Halogen-free sanitation for healthcare and food logistics applications where chlorinated byproduct formation is prohibited.
- Cleansing Agents:Formulated cleaning compounds combining KMPS with surfactant packages for industrial equipment maintenance.
Water Treatment commands the largest volume position, with Oxidizers expanding most quickly on electronics fabrication intensity.
End User:
Customer type determines specification stringency, with industrial accounts demanding certified supply chains and household segments prioritizing handling convenience.
- Industrial:Large-volume consumers including municipal utilities, semiconductor fabs, and mining operations requiring drum-scale shipments with chain-of-custody documentation. China's MEE wastewater standards are accelerating closed-loop oxidation system deployment across heavy manufacturing zones.
- Commercial:Swimming pool operators, hotels, and food service establishments specifying tablet formats for automated dosing compliance.
- Agricultural:Aquaculture pond operations in Vietnam and Indonesia adopting KMPS for shrimp farming oxidation protocols ahead of anticipated chlorine regulation.
- Household:Consumer packaged formats for residential pool maintenance and specialty cleaning applications.
Industrial end users absorb the majority volume, though Agricultural is gaining share fastest on aquaculture infrastructure buildout.
Distribution Channel:
Supply concentration shapes channel selection, with direct relationships dominating industrial procurement and intermediaries serving fragmented commercial accounts.
- Direct Sales:Long-term supply agreements between manufacturers and municipal utilities, semiconductor fabs, and large industrial water treatment operators. German and Japanese producers maintain dedicated technical service teams for direct account management.
- Distributors:Regional chemical distributors holding inventory positions for mid-scale industrial and commercial accounts, particularly in North American and European markets.
- Retail:Big-box and specialty pool supply stores carrying consumer-format tablets and granules for residential end users.
- Online Sales:E-commerce platforms serving small commercial accounts and household consumers with packaged formats.
Direct Sales retains the dominant position, while Distributors is climbing the fastest on specification-driven buying committee expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the lowest price elasticity, prioritizing certified purity and technical service over cost minimization. Chinese and Vietnamese procurement committees show higher sensitivity, driving volume consolidation around domestic suppliers.
United States
Municipal utilities in Ohio and Pennsylvania pilot encapsulated KMPS formats to eliminate dust exposure at treatment facilities. EPA Stage 2 DBP Rule enforcement compels chlorine displacement in surface water treatment trains. California and Texas municipalities unbundle chemical supply from oxidation system maintenance contracts.
Germany
Industrial water reuse intensity across heavy manufacturing zones sustains premium-grade KMPS absorption. EU REACH authorization timelines tighten substance volume tracking obligations for peroxide-based chemistries. The Rhine-Ruhr industrial corridor anchors closed-loop oxidation system deployment for chemical processing.
China
MEE wastewater discharge standards for heavy manufacturing zones mandate closed-loop oxidation infrastructure buildout. NMPA substance dossiers demand 18-24 month compliance timelines for new formulation grades. The Yangtze River Delta concentrates electronics-grade KMPS demand for semiconductor fabrication.
Japan
Ultra-high-purity KMPS specifications govern wafer surface preparation for advanced node semiconductor production. METI chemical substance reporting obligations segment product grades across domestic supply chains. The Osaka-Kyoto-Kobe manufacturing belt anchors pharmaceutical-grade production with exacting purity controls.
Vietnam
Shrimp farming operations lack oxidation infrastructure, creating penetration opportunities for tablet-format KMPS ahead of anticipated chlorine regulation. Aquaculture pond dosing protocols favor single-dose formats with minimal operator training requirements. The Mekong Delta region concentrates aquaculture infrastructure buildout.
Potassium Monopersulfate (KMPS) Market Competitive Landscape
Integrated peroxide chemistry specialists and regional electrolysis-grade manufacturers split the market into distinct capability tiers. Three to four producers control the majority of certified supply for municipal and electronics-grade specifications. Strategic archetypes include captive electrolysis operators, distributor-anchored regional suppliers, and fluoropolymer-adjacent oxidation specialists. Dominant competitive moves center on backward integration into potassium sulfate feedstock and on-site generation system licensing.
Within the integrated chemistry tier, Lanxess anchors European industrial supply through captive peroxide production. Mitsubishi Gas Chemical Company occupies a position exemplifying pharmaceutical-grade purity specialization. Chemours Company represents fluoropolymer-adjacent oxidation expertise serving North American industrial accounts.
| Leading Market Players |
|---|
| Shanghai Future Chemical |
| Haihang Industry |
| Lanxess |
| Chemours Company |
| Ansin Chemical |
| United Initiators |
| VR Persulfates |
| Mitsubishi Gas Chemical Company |
| Shangyu Jiehua Chemical |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese electrolysis-grade potassium sulfate production is compressing feedstock quotations and enabling aggressive pricing from domestic KMPS manufacturers, while European and Japanese suppliers maintain premium positions through purity certification and technical service bundling.
Pricing Analysis
Aftermarket oxidation system service contracts now generate lifetime value multiples exceeding raw chemical margins. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and industrial-grade tiers separates certified purity documentation from commodity oxidation supply. Cost compression in industrial powder formats is intensifying because Chinese producers are expanding electrolysis capacity ahead of demand absorption. Municipal utilities in Germany and Japan exhibit the lowest price sensitivity, prioritizing EPA and REACH compliance documentation over unit cost minimization.
Supply Chain Analysis
Potassium sulfate feedstock supply concentrates in Chilean mining operations and German chemical processing complexes, with electrolysis-grade material drawing from fertilizer-market arbitrage channels. KMPS synthesis rests on specialized anode engineering, peroxymonosulfate crystallization expertise, and halogen-free handling infrastructure. Single-source vulnerability in Chilean sulfate concentrate exposes margin stability to commodity agricultural demand swings. Distribution runs through direct technical service relationships for municipal and semiconductor accounts, with regional chemical distributors serving mid-scale industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
KMPS incumbents face a substitution defense against peracetic acid encroachment in food and beverage CIP sanitation, where residual oxygen specifications are less stringent and PAA cost positioning is improving.
For Market Incumbents: Harden backward integration into potassium sulfate feedstock through offtake agreements with Chilean mining operators or German chemical processors. Secure captive electrolysis capacity to isolate margin exposure from fertilizer-market volatility. Invest in on-site generation system licensing to capture recurring revenue streams from remote mining camps and offshore platforms facing transport-degradation losses.
For New Entrants and Emerging Players: Pursue aquaculture pond oxidation infrastructure in Vietnam's Mekong Delta region, where shrimp farming operations lack existing chlorine alternatives and tablet-format KMPS penetration remains minimal. Target single-dose format supply partnerships with regional distributors serving agricultural accounts ahead of anticipated chlorine regulation. Lead with automated dosing compliance and minimal operator training requirements as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment OEMs that have unbundled oxidation system maintenance from chemical supply contracts. Long-term viability favors producers with integrated peroxide chemistry capabilities and certified pharmaceutical-grade production infrastructure. Acquisition targets should demonstrate REACH and EPA registration dossier completeness. The signal to watch is municipal utility procurement committee specification shifts toward encapsulated granule formats with extended shelf life claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potassium Sulfate | Captive feedstock supply from Chilean or German sources isolates margin exposure from fertilizer-market arbitrage cycles. |
| On-Site Generation System Licensing | Electrolytic synthesis units at remote mining camps bypass KMPS potency degradation from ambient storage conditions. |
| Encapsulated Granule Format Development | Controlled-release coatings extend effective shelf life in humid climates and eliminate dust exposure liabilities. |
| REACH and EPA Registration Investment | Substance dossier completeness accelerates 18-24 month compliance timelines for new pharmaceutical-grade formulations. |
| Aquaculture Distribution Partnership | Tablet-format supply agreements in Vietnam penetrate shrimp farming oxidation protocols ahead of chlorine regulation. |
Research Methodology
A standing panel of municipal water treatment plant managers, semiconductor fab chemical engineers, aquaculture operations directors, and regional chemical distribution executives provided ongoing calibration against secondary validation sources. Primary fieldwork combined structured interviews with procurement leads at German industrial utilities and Taiwanese electronics manufacturers. Secondary sources included EPA enforcement databases, EU REACH substance volume tracking disclosures, Chinese MEE wastewater discharge standard filings, and customs trade data for potassium sulfate and peroxymonosulfate derivatives. Bottom-up segment sizing triangulated against top-down chemical industry capacity estimates.
Scenario-bracketing around regulatory enforcement intensity and feedstock cost volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included formulation format, application intensity, end-user specification tier, and regional regulatory cluster. CAGRs derived from electrolysis capacity expansion timelines, municipal chlorine displacement procurement cycles, and electronics fabrication node advancement patterns. Industry-specific forecast inputs incorporated EPA Stage 2 DBP Rule implementation pace and EU F-Gas Regulation phase-down substitution elasticities.
Sensitivities concentrate around potassium sulfate fertilizer-market arbitrage, REACH authorization timeline extensions, and semiconductor capital expenditure cyclicality. Forecasts reflect assumptions on regulatory enforcement consistency and feedstock supply concentration stability. Cross-checking against ACC industrial chemical production indices and Cefic specialty chemicals trade data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
Methyl Anthranilate Market