
 Polyimide Coatings Market | 2026-2036
Polyimide Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Polyimide Coatings Market Outlook
Aerospace thermal management is recalibrating demand patterns for polyimide coatings as next-generation engine compartments and satellite systems require higher service temperatures. DuPont leverages its fluoropolymer-polyimide hybrid expertise to anchor positions in wire enamel and flexible heater circuits. Toray Industries, Inc. sustains leadership in thin-film polyimide through captive precursor supply and proprietary casting lines. Kaneka Corporation specializes in photosensitive polyimide formulations that dominate semiconductor passivation layers in East Asian fabrication facilities.
Polyimide coatings are aromatic heterocyclic polymer films or liquid dispersions formed from dianhydride and diamine precursors through thermal or chemical imidization, delivering continuous service temperatures above 300°C with dielectric strength exceeding 200 kV/mm for electrical insulation and thermal protection. Liquid coatings dominate volume consumption in motor and transformer rewind applications where dip-and-bake processes remain cost-efficient, while thin film coatings command premium positioning in flexible printed circuit boards where dimensional stability under solder reflow determines yield rates. Solid coatings occupy a mature niche in compression-molded bearings and seals for industrial equipment.
FDA scrutiny of polymer extractables in medical device coatings, EPA restrictions on N-methyl-2-pyrrolidone solvent emissions, and REACH registration requirements for aromatic dianhydrides are elevating compliance costs and favoring producers with in-house environmental health and safety infrastructure. Stakeholders must monitor solvent-free UV-curable polyimide development and bio-based dianhydride feedstock trials, as these vectors will determine which formulation platforms retain access to European and North American OEM qualification lists.
Market Dynamics
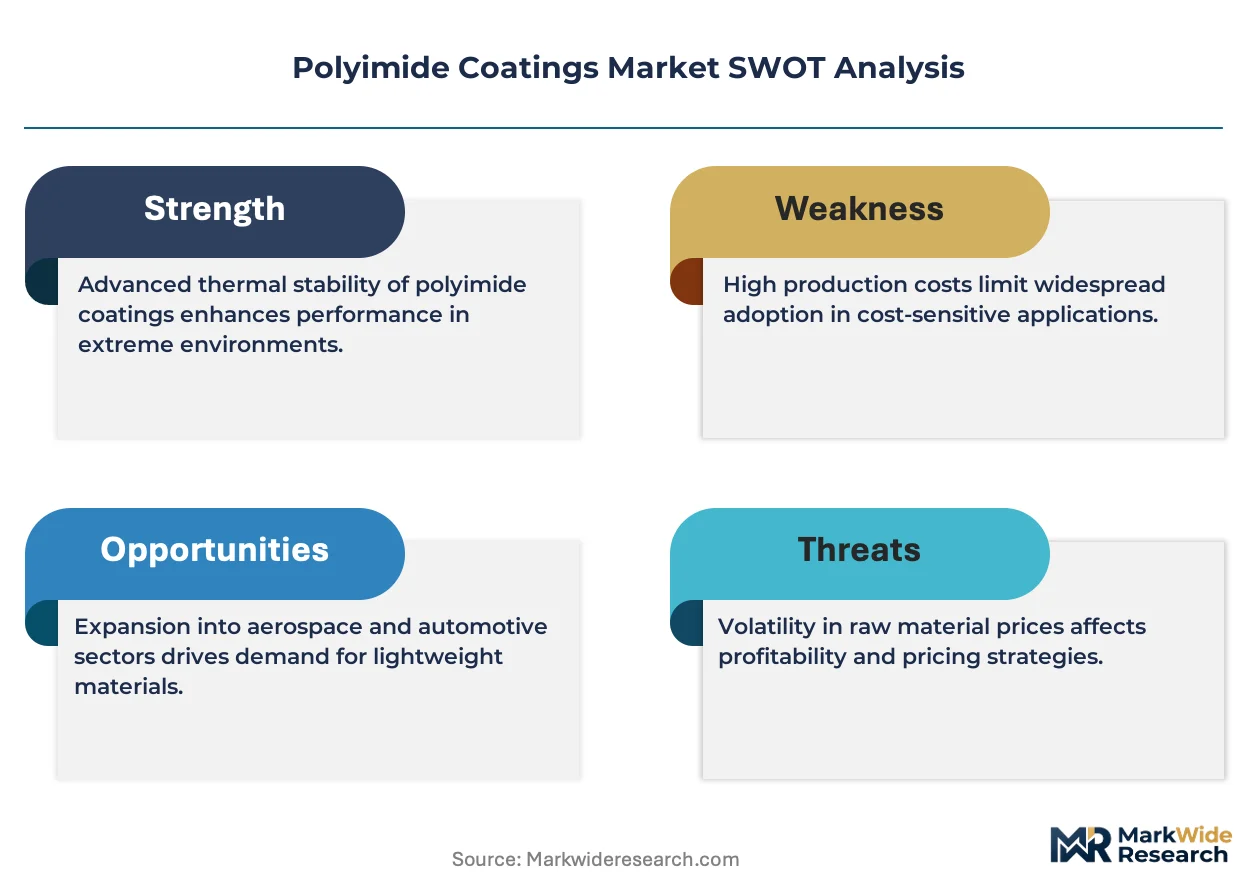
REACH compliance deadlines and EPA solvent emission caps are forcing reformulation of liquid polyimide coatings, compressing margins for producers lacking in-house environmental health and safety infrastructure while rewarding those with captive precursor supply chains.
Growth Catalysts
- Aerospace thermal management:Next-generation engine compartments and satellite systems demand service temperatures above 300°C, pulling volume toward high-performance wire enamel and thermal barrier formulations.
- China's domestic precursor scaling:Local electronics laminates and flexible circuit substrate producers are absorbing expanded polyimide capacity, reducing import dependency for dianhydride feedstocks.
- Semiconductor passivation layers:Photosensitive polyimide formulations dominate East Asian fabrication facilities as node shrinkage intensifies demand for planarization and stress-buffering dielectrics.
Market Restraints
- N-methyl-2-pyrrolidone solvent costs:EPA restrictions on NMP emissions elevate compliance expenditures for liquid coating producers without solvent recovery systems.
- Aromatic dianhydride supply concentration:Precursor production clusters in East Asia expose non-integrated formulators to freight volatility and tariff exposure.
- Ceramic coating substitution:Plasma-sprayed thermal barrier ceramics displace polyimide films in select turbine applications above 400°C service thresholds.
Strategic Opportunities
- Solvent-free UV-curable platforms:Elimination of thermal imidization cycles reduces energy intensity and qualifies coatings for European OEM sustainability scorecards.
- India's electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication create qualified demand for imported photosensitive polyimide precursors.
- Bio-based dianhydride feedstocks:Renewable-derived pyromellitic dianhydride trials align with EU Green Deal procurement mandates for circular material content.
Industry Challenges
- Imidization process engineering talent:Shortage of technicians skilled in thermal vs. chemical cyclization optimization constrains scale-up of novel formulation platforms.
- FDA extractables documentation:Medical device coating qualifications require 18-24 month stability studies, delaying revenue recognition for new entrants.
- Legacy dip-and-bake equipment incompatibility:Motor rewind shops resist capital conversion to spray or curtain coating systems optimized for low-viscosity formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyimide Coatings Market |
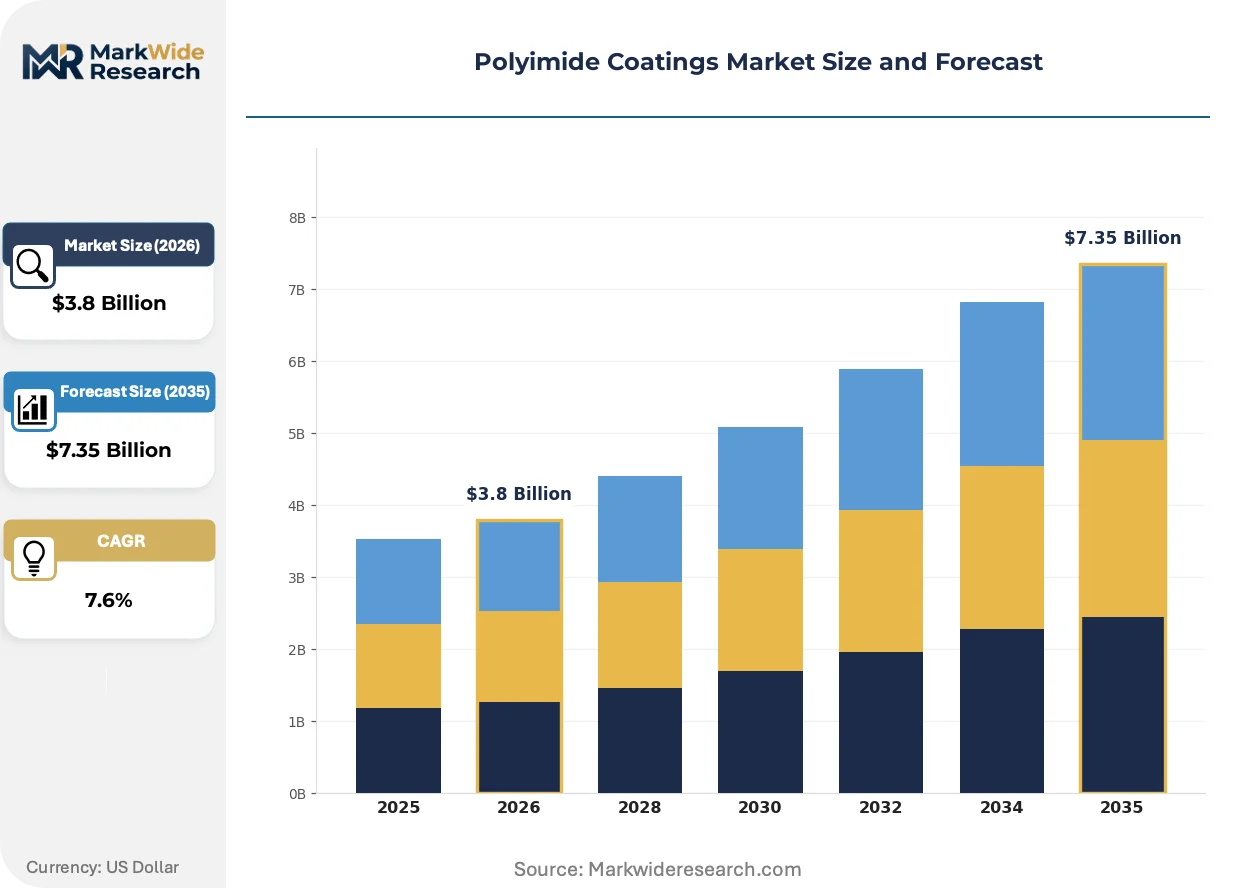
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Coatings, Solid Coatings, Powder Coatings, Thin Film Coatings Application: Aerospace, Electronics, Automotive, Industrial Form: Spray, Brush, Plating, Dip End User: Manufacturers, Contractors, Original Equipment Manufacturers, Research Institutions |
| Companies Covered | Ube Industries Ltd, Toray Industries, Inc., DuPont, Kaneka Corporation, Saint-Gobain, Mitsui Chemicals, Inc., PI Advanced Materials Co., Ltd., I.S.T Corporation, FLEXcon Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyimide Coatings Market Strategic Shifts
Reformulation chemistry and curing methodology are diverging sharply as environmental compliance tightens and end-use thermal requirements escalate. The field is fragmenting into solvent-free, waterborne, and hybrid cure platforms.
Waterborne polyimide dispersions are expanding into motor and transformer rewind applications where legacy solvent-based dip-and-bake processes face EPA emission quotas. Tier-1 automotive suppliers in Germany and Japan are piloting these systems for traction motor insulation. The technology is expanding into cost-sensitive industrial segments previously locked out by solvent-handling infrastructure requirements.
REACH registration requirements for aromatic dianhydrides are elevating documentation burdens for European compounders importing Chinese precursors. ECHA substance evaluation deadlines in 2025-2026 compress qualification timelines for new suppliers. Formulators with pre-registered feedstock portfolios are capturing share from competitors facing registration gaps.
Flexible circuit substrate buyers are consolidating qualified supplier lists around dimensional stability under multiple solder reflow cycles. Korean and Taiwanese PCB fabricators now specify CTE-matched coverlay films for high-layer-count builds. This specification creep favors producers with proprietary casting line control over film thickness uniformity.
Polyimide Coatings Market Segmentation
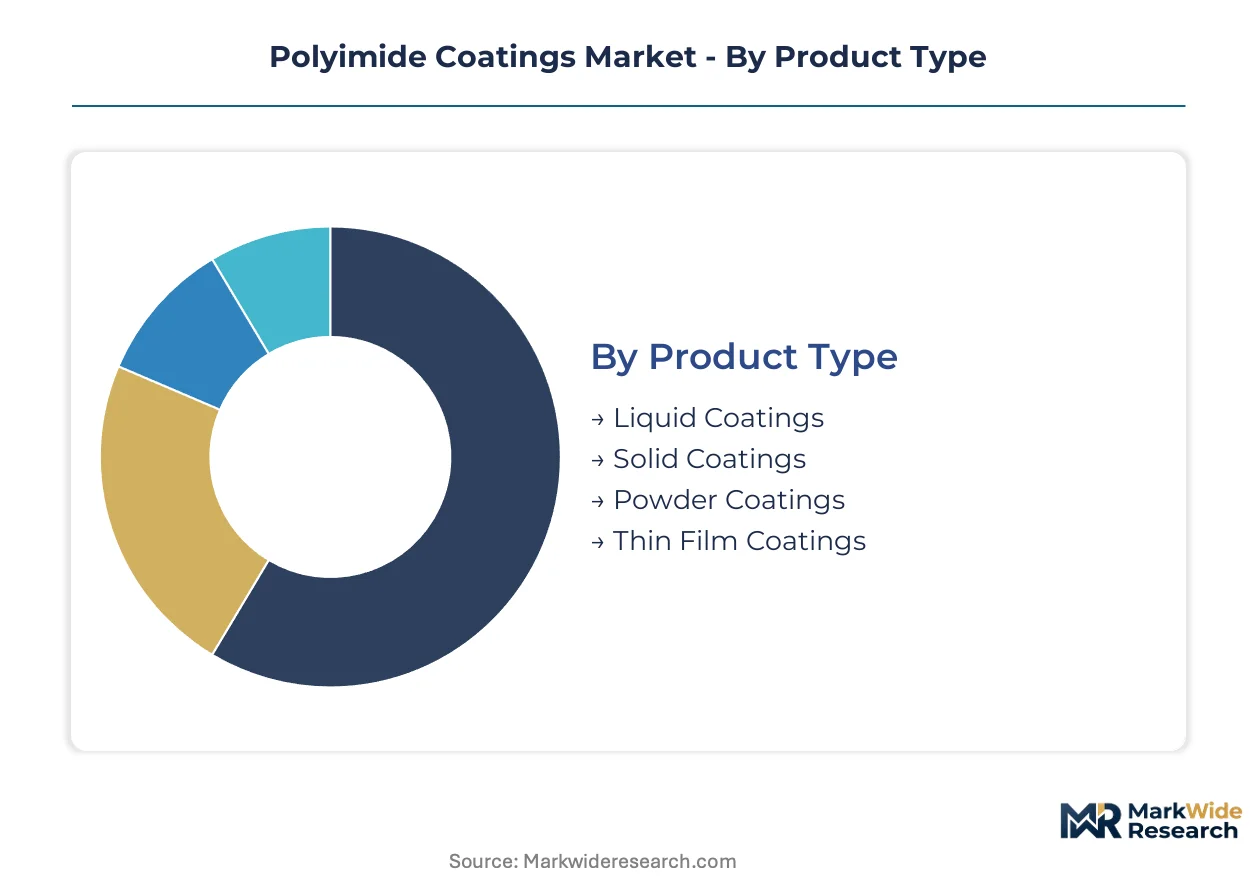
Polyimide coatings fragment across formulation physics, application method, and customer procurement sophistication. Each axis carries distinct margin structures and technical qualification barriers that determine supplier access.
Product Type:
Formulation chemistry dictates thermal ceiling, processing energy, and environmental compliance burden.
- Liquid Coatings:Solvent-borne or waterborne dispersions applied through dip-and-bake or spray processes. Motor and transformer rewind shops in the United States absorb volume despite EPA N-methyl-2-pyrrolidone emission caps elevating compliance costs for producers lacking solvent recovery infrastructure.
- Thin Film Coatings:Cast polyamic acid solutions thermally imidized into dimensionally stable films. Korean and Taiwanese flexible circuit fabricators specify CTE-matched coverlay films for high-layer-count PCB builds where solder reflow yield determines supplier qualification.
- Solid Coatings:Compression-molded or sintered forms for bearings and seals. Industrial equipment OEMs specify these for continuous service above 300°C where liquid film integrity degrades.
- Powder Coatings:Electrostatically applied thermosetting granules requiring post-cure imidization. Niche penetration in automotive under-hood components where solvent-free application meets assembly plant emission constraints.
Mature deployment sits with liquid coatings. Newer deployment is concentrated in thin film coatings.
Application:
End-use thermal requirements and regulatory exposure split the market into divergent qualification timelines.
- Electronics:Semiconductor passivation, flexible circuit substrates, and display backplanes. Photosensitive formulations dominate East Asian fabrication facilities as node shrinkage intensifies demand for planarization dielectrics with stress-buffering properties.
- Aerospace:Wire harness insulation, thermal barrier films, and satellite component protection. Next-generation engine compartments and satellite systems pull volume toward service temperatures above 300°C.
- Automotive:Traction motor insulation and battery thermal management. Tier-1 suppliers in Germany pilot waterborne systems as emission quotas tighten on legacy solvent processes.
- Industrial:Motor rewind, transformer insulation, and compression-molded seals. Cost-sensitive segments where dip-and-bake infrastructure amortization slows conversion to advanced formulation platforms.
Electronics commands premium positioning. Aerospace delivers steepest expansion trajectory as thermal requirements escalate.
Form:
Application method determines viscosity specification, equipment capital requirements, and coating uniformity control.
- Dip:Submersion coating for complex geometries in motor stator and transformer winding applications. Legacy equipment bases in industrial maintenance shops resist capital conversion despite energy inefficiency.
- Spray:Atomized deposition for large surface areas and repair operations. Automotive and aerospace MRO facilities favor this for field application flexibility.
- Brush:Manual application for prototype builds and touch-up repair. Research institutions and small-batch manufacturers specify this for formulation testing without process scale commitment.
- Plating:Electrophoretic deposition for conformal coating of conductive substrates. Emerging niche in MEMS and sensor packaging where thickness uniformity at sub-micron scale determines device performance.
Dip coating retains installed base dominance. Spray application is climbing the fastest as automotive and aerospace MRO volumes expand.
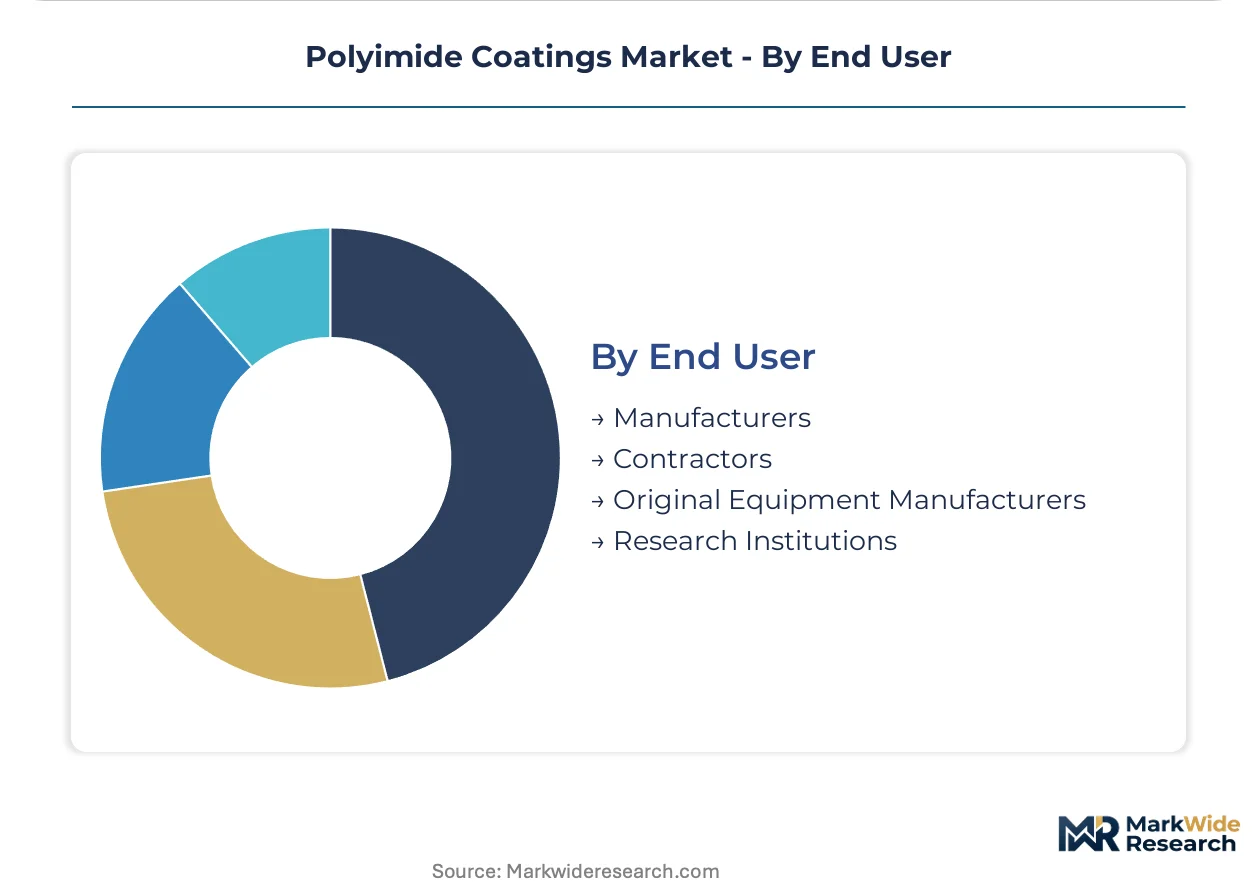
End User:
Procurement sophistication and technical specification authority separate volume buyers from specification influencers.
- Original Equipment Manufacturers:Automotive, aerospace, and electronics fabricators with captive materials engineering and supplier qualification teams. These entities gate market access through multi-year approval cycles and sustainability scorecards.
- Manufacturers:Tier-2 and Tier-3 component producers purchasing qualified formulations against OEM specifications. Price sensitivity intensifies as procurement consolidates around approved supplier lists.
- Contractors:Industrial maintenance and repair operations executing motor rewind and equipment refurbishment. Equipment legacy and technician training constraints limit formulation flexibility.
- Research Institutions:Universities and national laboratories screening novel chemistries and cure methodologies. Early-stage bio-based dianhydride and solvent-free UV-curable platform development originates here.
OEMs concentrate specification authority. Research institutions are gaining share fastest as formulation innovation cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhangjiagang Free Trade Zone and Shanghai Lingang Special Area concentrate polyimide precursor capacity expansion serving domestic electronics laminates and flexible circuit substrate producers.
China
Domestic dianhydride capacity scaling in Jiangsu and Zhejiang provinces absorbs expanded polyimide production for local PCB fabricators and display backplane manufacturers. MIIT dual carbon goals accelerate solvent-free formulation trials in Yangtze River Delta chemical parks. Suzhou and Wuxi industrial clusters host captive precursor supply chains reducing import dependency for electronics-grade polyimide.
United States
Aerospace wire harness insulation and satellite thermal barrier films drive procurement volumes from domestic formulators serving NASA and defense prime contractors. EPA N-methyl-2-pyrrolidone emission caps elevate compliance costs for liquid coating producers lacking solvent recovery infrastructure. Greater Boston and Huntsville aerospace corridors concentrate qualification activity for high-temperature service applications above 300°C.
Germany
Tier-1 automotive suppliers pilot waterborne polyimide systems for traction motor insulation under tightening emission quotas. KBA vehicle certification requirements and EU Green Deal circular content mandates favor producers with bio-based dianhydride feedstock development. Bavaria and Baden-Württemberg host industrial equipment OEMs specifying compression-molded polyimide bearings for continuous high-temperature service.
Japan
Photosensitive polyimide formulations dominate semiconductor passivation layers in East Asian fabrication facilities as node shrinkage intensifies planarization dielectric demand. METI technology roadmaps prioritize CTE-matched coverlay films for high-layer-count flexible circuit builds. Kansai and Kyushu industrial corridors concentrate casting line capacity for electronics-grade thin film production.
South Korea
Flexible circuit substrate fabricators consolidate qualified supplier lists around dimensional stability specifications under multiple solder reflow cycles. MFDS medical device coating documentation requirements extend qualification timelines for extractables testing. Seoul Capital Area and Busan-Ulsan corridors host PCB manufacturers driving CTE-matched coverlay film procurement.
Polyimide Coatings Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated precursor producers commanding premium positioning in thin film coatings while toll compounders serve cost-sensitive industrial dip-and-bake applications. Three archetypes dominate: captive precursor suppliers with proprietary casting technology, formulation houses dependent on imported dianhydride feedstocks, and regional compounders serving maintenance repair operations. Competitive moves concentrate on backward integration into precursor supply and technology licensing partnerships for solvent-free UV-curable platforms.
Among Japanese integrated producers, Toray Industries, Inc. and Kaneka Corporation exemplify the captive precursor archetype with proprietary casting line control. DuPont anchors the hybrid technology tier leveraging fluoropolymer-polyimide formulation expertise. Ube Industries Ltd represents the diversified chemical conglomerate model with upstream dianhydride production integration.
| Leading Market Players |
|---|
| Ube Industries Ltd |
| Toray Industries, Inc. |
| DuPont |
| Kaneka Corporation |
| Saint-Gobain |
| Mitsui Chemicals, Inc. |
| PI Advanced Materials Co., Ltd. |
| I.S.T Corporation |
| FLEXcon Company, Inc. |
| Others |
Value Chain & Pricing Dynamics
Aromatic dianhydride spot indices in East Asian chemical trading hubs cascade through three distinct pricing tiers, with electronics-grade thin film coatings commanding substantial premiums over industrial dip-and-bake formulations while REACH registration gaps compress margins for European compounders importing Chinese precursors.
Pricing Analysis
Short lead-time premiums of 15-25 percent separate qualified suppliers from spot-market buyers in aerospace wire enamel procurement. Three-tier pricing structure across electronics-grade, automotive-qualified, and industrial maintenance tiers reflects certification burden and captive precursor access. Cost compression in liquid coatings intensifies because EPA N-methyl-2-pyrrolidone compliance expenditures fall heaviest on non-integrated formulators. Motor rewind contractors exhibit highest price sensitivity, while semiconductor fabricators prioritize dimensional stability over unit cost.
Supply Chain Analysis
Refurbished casting line equipment and recovered solvent streams flow back into precursor production facilities, extending asset life cycles across Japanese and Korean integrated producers. China, Japan, and South Korea concentrate dianhydride manufacturing capacity, with pyromellitic dianhydride and oxydianiline drawing from petroleum-derived feedstocks and captive naphthalene cracking operations. Single-source vulnerability clusters around Jiangsu province precursor plants exposed to Yangtze River Delta environmental inspections. Distribution runs through qualified supplier lists maintained by OEM materials engineering teams, with direct mill relationships dominating electronics-grade thin film procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive precursor capacity constraints prop pricing power for integrated producers, as imidization process engineering talent scarcity limits scale-up of novel formulation platforms and sustains qualification barriers.
For Market Incumbents: Hedge against ceramic coating substitution in turbine applications above 400°C by deepening captive dianhydride supply and accelerating solvent-free UV-curable platform development. Lock in multi-year offtake agreements with Chinese PCB fabricators before domestic precursor capacity fully matures. Prioritize backward integration into pyromellitic dianhydride production to insulate margin structures from aromatic feedstock volatility.
For New Entrants and Emerging Players: Launch via toll-manufacturing partnerships targeting India's PLI scheme electronics manufacturing incentives, where qualified photosensitive polyimide precursor demand outstrips local supply. Penetrate waterborne motor rewind formulations in German automotive traction motor insulation, where emission quota tightening disadvantages legacy solvent-based incumbents. Pursue research institution licensing for bio-based dianhydride feedstock trials aligned with EU Green Deal procurement mandates.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Japanese formulators with pre-registered REACH portfolios and proprietary casting line control in Kyushu industrial corridors. Five-to-ten year viability hinges on qualification list persistence as OEM sustainability scorecards harden. Monitor ECHA substance evaluation deadlines as inflection indicators for European compounder consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dianhydride Precursors | Captive pyromellitic dianhydride supply insulates margins from East Asian feedstock volatility and tariff exposure. |
| Solvent-Free UV-Curable Platform Development | Elimination of thermal imidization cycles qualifies coatings for European OEM sustainability scorecards under EU Green Deal mandates. |
| Waterborne Formulation Scale-Up | EPA N-methyl-2-pyrrolidone emission caps favor low-VOC systems in German automotive traction motor insulation pilots. |
| India Electronics Manufacturing Partnership | PLI scheme incentives for semiconductor fabrication create qualified demand for imported photosensitive polyimide precursors. |
| Bio-Based Dianhydride Feedstock Trials | Renewable-derived pyromellitic dianhydride development aligns with EU circular content mandates for medical device coatings. |
Study Parameters
Independent corroboration across plant managers at polyimide coating facilities, procurement leads at aerospace and electronics OEMs, and distribution channel partners in East Asian chemical trading hubs underwrites the qualitative findings. Technical R&D directors at integrated precursor producers and regulatory affairs specialists navigating REACH registration requirements provided primary perspective. Secondary validation drew from customs and trade data, SEC 10-K filings of diversified chemical conglomerates, and ECHA substance evaluation databases. Bottom-up demand modeling across application segments triangulated against top-down capacity assessments from dianhydride production announcements.
Rate-of-change decomposition across the analysis window isolates volume growth from mix-shift and pricing components. Segmentation dimensions span formulation physics, application method, end-use thermal requirement, and regional production hub qualification status. CAGRs derive from installed base erosion rates in legacy dip-and-bake industrial equipment, penetration trajectories for waterborne systems in automotive traction motors, and yield improvement assumptions in high-layer-count flexible circuit builds. Forecast inputs incorporate MIIT dual carbon policy stringency scenarios and NASA satellite thermal barrier film procurement cycles.
REACH registration deadline slippage, ceramic coating substitution acceleration in turbine applications, and abrupt Yangtze River Delta environmental enforcement actions are the dominant revision risks. Forecasts embed assumptions about imidization process engineering talent pipeline recovery and solvent-free platform qualification timelines. Practitioners should monitor ECHA substance evaluation outcomes, EPA N-methyl-2-pyrrolidone rulemaking, and Chinese domestic precursor capacity utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Superacids Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
Acetyl Serine Market