
 North America Caustic Potash Market | 2026-2036
North America Caustic Potash Market Size, Share, and Industry Trends Forecast 2026-2036
North America Caustic Potash Market Intelligence
Technical-grade supply contracting is broadening the recurring revenue base for North American producers. Nutrien Ltd. leverages its integrated potash mining network to secure feedstock cost advantages across Saskatchewan and Manitoba. Occidental Chemical Corporation anchors its position through chlor-alkali co-production infrastructure along the US Gulf Coast. FMC Corporation differentiates via high-purity grades tailored to pharmaceutical and food-grade specifications.
Caustic potash, or potassium hydroxide with formula KOH and typical industrial concentrations of 45-50% by weight in liquid form, serves as a strong base for chemical synthesis, pH adjustment, and saponification processes. Flakes and liquid formats dominate volume flows into chemical manufacturing and water treatment, where bulk handling economics favor drum and IBC tote packaging. Food processing applications command premium positioning due to stringent FCC and NSF certification requirements that constrain supplier qualification.
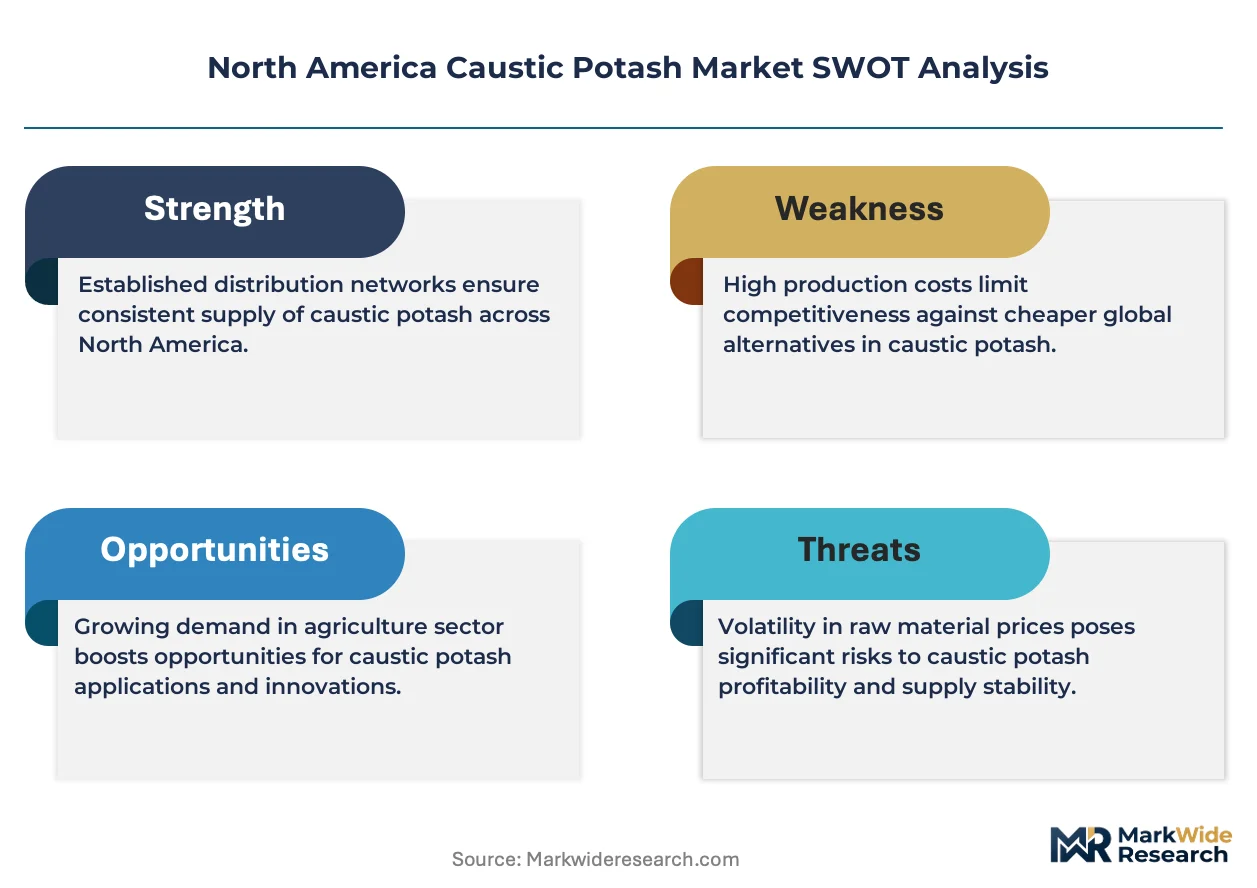
EPA effluent guidelines under the Clean Water Act and OSHA Process Safety Management standards govern handling thresholds and discharge limits for caustic potash facilities across the United States. Health Canada and PMRA oversee import and agricultural application standards in the Canadian market, while state-level Texas Commission on Environmental Quality permits shape operational compliance for Gulf Coast producers. Stakeholders must monitor evolving PFAS remediation protocols, as potassium hydroxide-based treatment systems face competitive displacement from advanced oxidation alternatives.
Market Dynamics
EPA effluent guideline tightening under the Clean Water Act is forcing industrial water treatment operators across the United States to upgrade pH neutralization systems, directly expanding technical-grade caustic potash offtake volumes in the Texas-Louisiana Gulf Coast corridor.
Growth Catalysts
- Clean Water Act enforcement:EPA discharge standard revisions mandate enhanced pH control at municipal and industrial treatment facilities, expanding KOH demand for neutralization protocols.
- Pharmaceutical synthesis expansion:High-purity potassium hydroxide serves as a critical reagent in active pharmaceutical ingredient manufacturing across the United States and Canada.
- Gulf Coast chemical cluster concentration:Chlor-alkali co-production infrastructure in Texas and Louisiana generates feedstock-advantaged supply proximity to bulk consumers.
Market Restraints
- Energy input cost volatility:Electrolytic production of caustic potash ties manufacturing economics directly to regional electricity pricing fluctuations.
- Canadian feedstock concentration:Saskatchewan and Manitoba potash mining dominance creates geographic supply vulnerability for North American KOH producers.
- Advanced oxidation substitution:PFAS remediation protocols increasingly favor peroxone and UV-based treatment systems over alkaline hydrolysis methods.
Strategic Opportunities
- Mexico manufacturing expansion:Nearshoring of chemical processing operations creates new demand nodes for bulk liquid KOH distribution.
- Food-grade certification premiums:FCC and NSF qualification requirements constrain supplier pools, enabling margin expansion for qualified producers.
- Biofuel processing integration:Potassium hydroxide catalyzes transesterification in renewable diesel and sustainable aviation fuel production.
Industry Challenges
- Electrolytic cell maintenance expertise:Chlor-alkali facility operations require specialized technical labor pools that face demographic retirement pressures.
- Multi-jurisdictional compliance timelines:Simultaneous EPA, OSHA Process Safety Management, and state-level TCEQ permitting creates project delay risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Caustic Potash Market |
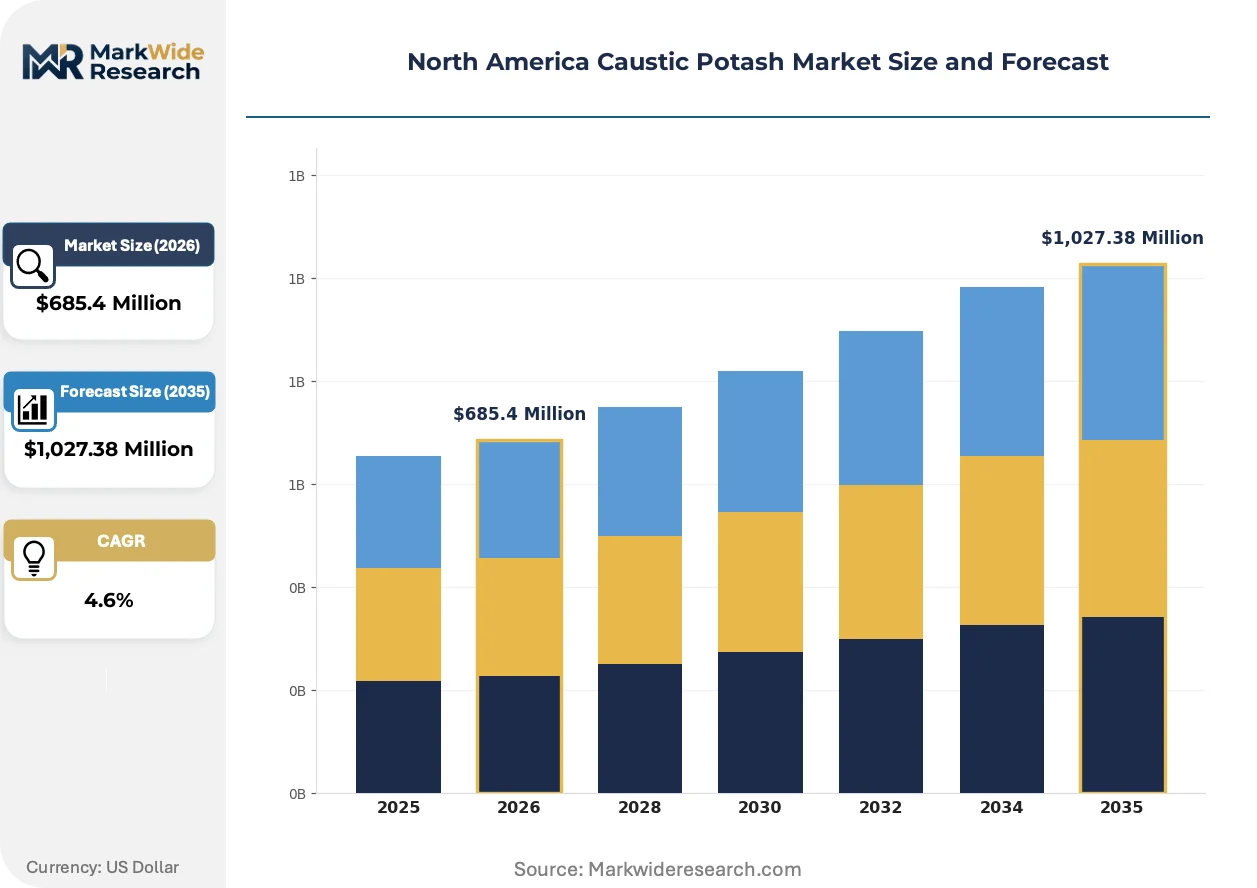
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,027.38 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Pearls, Liquid, Powder End Use Industry: Agriculture, Chemical Manufacturing, Food Processing, Water Treatment Packaging Type: Bags, Drums, Bulk Containers, IBC Totes Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Nutrien Ltd., Occidental Chemical Corporation, The Mosaic Company, FMC Corporation, Tessenderlo Group, ASHTA Chemicals, Erco Worldwide, Armand Products Company, Compass Minerals International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Caustic Potash Market Strategic Shifts & Innovations
Membrane cell electrolysis technology is rewriting production economics across the North American chlor-alkali sector, compressing energy intensity and enabling smaller-scale distributed manufacturing footprints.
Membrane cell electrolysis is rewriting caustic potash manufacturing by replacing mercury and diaphragm cell technologies with ion-exchange membrane systems. Producers in Texas and Louisiana are retrofitting existing chlor-alkali plants to capture energy efficiency gains of 15-25% versus legacy configurations. This technology diffusion is compressing the minimum efficient scale for profitable operation, enabling regional supply point proliferation closer to demand centers.
EPA's emerging PFAS destruction and disposal guidance is reshaping treatment chemical selection criteria for industrial effluent managers. The regulatory framework prioritizes technologies achieving complete mineralization over transfer-based methods, pressuring potassium hydroxide suppliers to demonstrate hydrolysis efficacy data. Water treatment utilities in the Great Lakes region are piloting hybrid alkaline-oxidation systems to preempt compliance exposure.
Long-term offtake contracting is displacing spot market purchasing among large-volume chemical manufacturers. Buyers in the Gulf Coast petrochemical corridor are securing three-to-five-year supply agreements with fixed-price escalation clauses to buffer against energy cost volatility. This procurement pattern shift concentrates volume commitments with integrated producers possessing captive feedstock positions.
North America Caustic Potash Market Segmentation
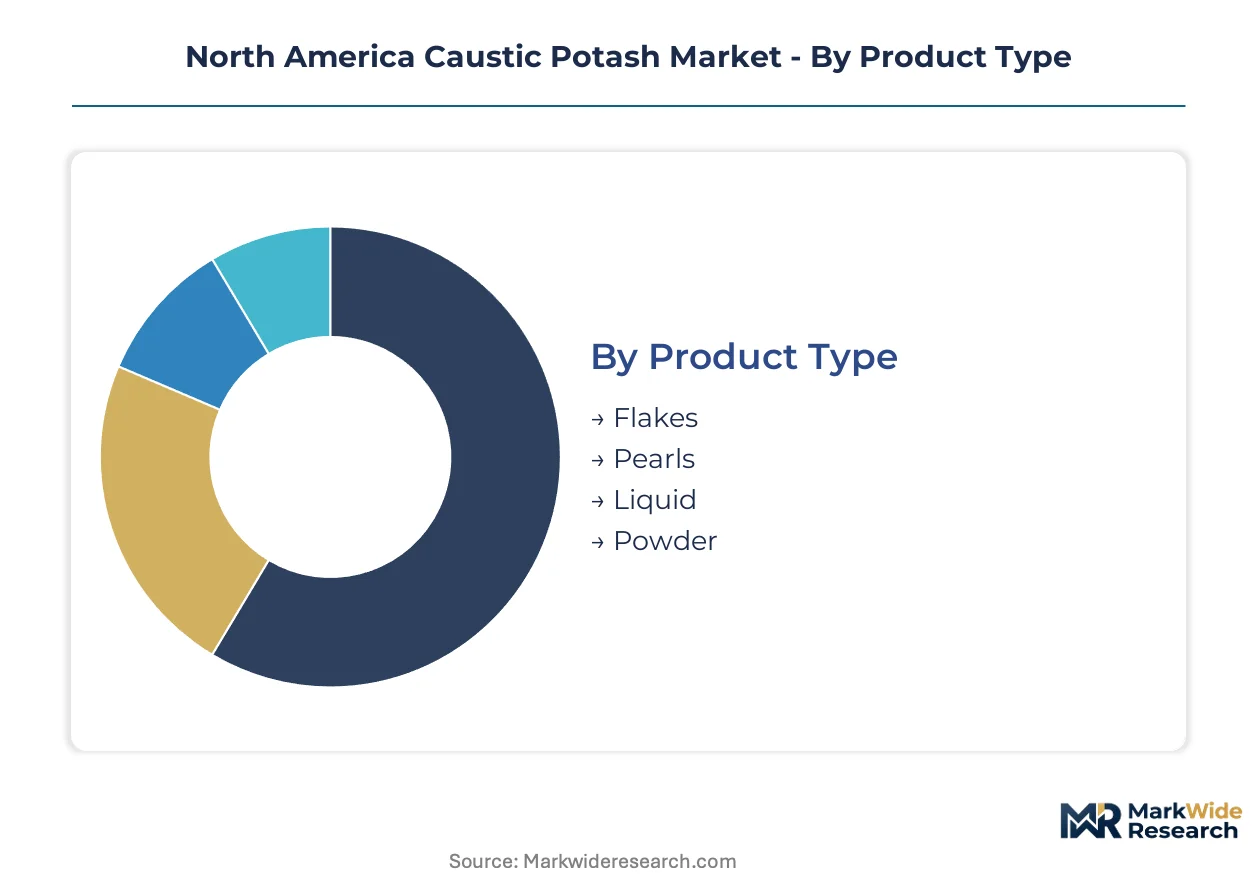
Caustic potash segmentation in North America reflects divergent compliance burdens across product grades and end-use specifications. Certification requirements from FDA, EPA, and FCC standards fragment supplier qualification pools and reshape procurement patterns.
Product Type:
FCC and NSF certifications impose tiered regulatory burdens across physical formats, with food-grade liquid and flake variants facing the most stringent purity thresholds.
- Liquid:Concentrated aqueous solutions of 45-50% KOH by weight dominate bulk chemical manufacturing and water treatment offtake across the Texas-Louisiana Gulf Coast. Tanker truck and railcar logistics favor this format for high-volume neutralization operations at municipal treatment facilities.
- Flakes:Solid potassium hydroxide with 90% minimum purity serves saponification and specialty chemical synthesis where precise dosing control matters. Food-grade flake production requires dedicated packaging lines and HACCP protocols that constrain supplier pools.
- Pearls:Spherical granular form offers reduced dusting and improved flow characteristics for automated handling systems in pharmaceutical manufacturing.
- Powder:Fine particulate grade addresses niche applications in potassium salt production and battery electrolyte formulation.
Liquid sits at the top of the volume ranking, with flakes climbing the fastest.
End Use Industry:
Cost tier stratification separates commodity-grade applications from premium-certified segments, with margin structures diverging by a factor of three or more.
- Water Treatment:Technical-grade KOH neutralizes acidic effluent across municipal and industrial facilities governed by EPA Clean Water Act discharge limits. Texas and Louisiana utilities are expanding capacity to meet tightening pH standard enforcement.
- Chemical Manufacturing:Chlor-alkali co-producers consume substantial volumes for potassium carbonate and phosphate derivative synthesis along the Gulf Coast corridor.
- Food Processing:FCC-certified grades command substantial premiums for pH adjustment in cocoa processing, olive curing, and beverage production under FDA oversight.
- Agriculture:Liquid KOH serves as a potassium source in foliar fertilizers and soil amendments regulated by Health Canada PMRA and state-level EPA equivalents.
Water treatment leads volume absorption, while food processing captures the steepest margin expansion trajectory.
Packaging Type:
Customer type segmentation separates bulk consumers with dedicated handling infrastructure from small-volume buyers requiring shelf-ready formats.
- Bulk Containers:Intermediate bulk containers of 1,000-1,500 liters serve mid-scale chemical processors lacking dedicated tankage but requiring drum-scale economies.
- Drums:Standard 55-gallon steel and polyethylene drums dominate food-grade and pharmaceutical applications where lot traceability and contamination control are paramount.
- IBC Totes:Returnable and single-use tote systems bridge the gap between drum convenience and bulk tanker economics for regional chemical distributors.
- Bags:Multi-wall paper and woven polypropylene sacks package flake and pearl grades for agricultural and industrial customers with lower throughput requirements.
Bulk containers anchor the volume base, with IBC totes gaining share fastest among flexible procurement operations.
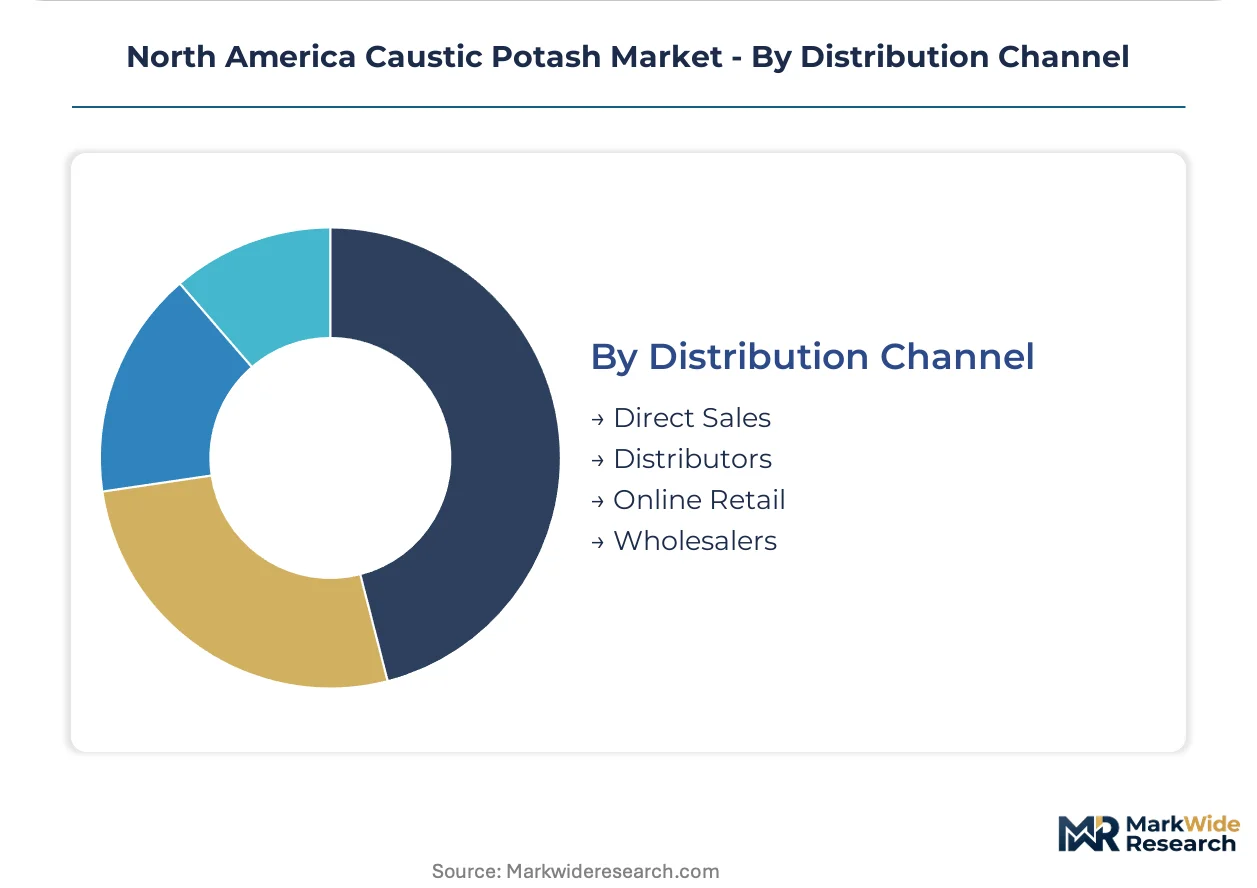
Distribution Channel:
Supply concentration patterns favor direct relationships with integrated producers for large consumers, while fragmented buyers rely on distributor networks for technical support and just-in-time delivery.
- Direct Sales:Integrated chlor-alkali producers negotiate long-term offtake agreements with Gulf Coast petrochemical majors, locking in three-to-five-year supply commitments with energy-linked pricing escalators.
- Distributors:Regional chemical distributors maintain stocked warehouses across the Midwest and Southeast, offering technical-grade product with 24-48 hour delivery windows for water treatment and manufacturing customers.
- Wholesalers:Agricultural supply cooperatives and industrial wholesalers aggregate small-lot demand from farms and municipal utilities lacking direct producer relationships.
- Online Retail:E-commerce platforms address laboratory, artisanal soap-making, and small-scale food processor demand for certified grades in package sizes below distributor minimums.
Direct sales command the largest volume flows, with distributor channels expanding most quickly into secondary markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting caustic potash production investments toward states with streamlined EPA permitting timelines. Chlor-alkali operators evaluate state-level environmental compliance burdens when siting membrane cell retrofits.
United States
Texas and Louisiana host the densest concentration of chlor-alkali co-production facilities serving Gulf Coast petrochemical demand. EPA Clean Water Act enforcement tightens discharge standards for industrial effluent across municipal treatment utilities. The Texas Commission on Environmental Quality permits shape operational compliance timelines for producers in the Houston-Beaumont-Port Arthur chemical corridor.
Canada
Saskatchewan and Manitoba potash mining dominance supplies captive feedstock to integrated KOH producers. Health Canada and PMRA oversee import standards and agricultural application protocols for cross-border chemical shipments. Nutrien Ltd. leverages its Prairie province mining network to secure cost advantages for North American chlor-alkali operations.
Mexico
Nearshoring of chemical processing operations creates emerging demand nodes for bulk liquid KOH distribution. Mexican environmental regulators under SEMARNAT implement discharge standards aligned with EPA frameworks. The Altamira petrochemical complex and emerging manufacturing zones in Nuevo León attract supply chain repositioning from US-based distributors.
North America Caustic Potash Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated chlor-alkali producers commanding bulk chemical offtake while specialty distributors capture food-grade and pharmaceutical premiums. Market structure concentrates around three to five vertically integrated players with captive potash feedstock positions. Two strategic archetypes dominate: mining-integrated chlor-alkali operators and regional specialty chemical distributors with certification expertise. Capacity expansion and long-term offtake contracting represent the dominant competitive moves.
Within the mining-integrated tier, Nutrien Ltd. and Occidental Chemical Corporation exemplify divergent geographic anchoring strategies. Nutrien represents the Saskatchewan feedstock-advantaged model with Prairie province potash mining integration. Occidental Chemical Corporation occupies the US Gulf Coast position with chlor-alkali co-production infrastructure in Texas and Louisiana. FMC Corporation sits within the specialty-grade archetype, differentiated by high-purity production capabilities serving pharmaceutical and food-grade specifications.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Occidental Chemical Corporation |
| The Mosaic Company |
| FMC Corporation |
| Tessenderlo Group |
| ASHTA Chemicals |
| Erco Worldwide |
| Armand Products Company |
| Compass Minerals International |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FCC-qualified food-grade and technical-grade industrial caustic potash generates parallel supply chain configurations across North America. Premium-certified production requires dedicated packaging lines and HACCP protocols that compress supplier pools and amplify pricing power for qualified producers, while commodity-grade volumes flow through bulk tanker logistics optimized for Gulf Coast chemical corridor efficiency.
Pricing Analysis
Distributor margin layers compress as direct-to-OEM long-term offtake agreements displace spot purchasing across the Texas-Louisiana chemical manufacturing belt. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified food processors from municipal water treatment utilities and bulk chemical manufacturers. Cost compression in technical-grade segments intensifies because membrane cell electrolysis retrofits expand regional supply capacity. Municipal water treatment operators exhibit highest price sensitivity due to fixed-rate utility tariff constraints, while pharmaceutical API manufacturers absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Gulf Coast petrochemical majors, while distributor networks serve fragmented water treatment and food processing customers. Geographic supply concentration centers on Canada for potash mining feedstock, the United States for chlor-alkali co-production infrastructure, and emerging Mexican demand nodes near Altamira. Raw material dependencies draw from Saskatchewan potash deposits, regional electricity grids for electrolytic production, and specialized membrane cell components. Single-source vulnerability in Canadian feedstock concentration creates exposure to cross-border logistics disruptions. Distribution runs through integrated producer direct sales for volume accounts and regional chemical distributors for technical support and just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American caustic potash has matured into a late-cycle quality story as EPA effluent guideline tightening redirects procurement toward certified suppliers capable of documenting complete mineralization efficacy for emerging PFAS remediation protocols.
For Market Incumbents: Deepen backward integration into Saskatchewan potash mining assets to secure captive feedstock positions against Canadian supply concentration risks. Expand membrane cell electrolysis capacity in Texas and Louisiana to capture energy efficiency premiums while advanced oxidation substitution threats pressure alkaline hydrolysis market share. Prioritize FCC and NSF certification maintenance as regulatory documentation requirements fragment qualified supplier pools.
For New Entrants and Emerging Players: Membrane cell technology licensing offers entry leverage into smaller-scale distributed production footprints enabled by compressed minimum efficient scale economics. Target Mexico nearshoring corridors as the most penetrable geography, where SEMARNAT-aligned discharge standards create demand nodes without entrenched incumbent relationships. Pursue regional distributor partnerships rather than direct sales infrastructure to bypass Gulf Coast volume commitment barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where electrolytic cell maintenance expertise faces demographic retirement pressures and multi-jurisdictional compliance timelines stretch project returns. Five-to-ten year viability favors integrated chlor-alkali operators with captive feedstock positions over pure-play distributors exposed to margin compression. Watch for EPA PFAS destruction guidance finalization as the signal indicating whether alkaline hydrolysis retains treatment chemical selection relevance or faces accelerated displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Retrofit Investment | Energy efficiency gains of 15-25% versus legacy mercury and diaphragm configurations reshape production economics. |
| Long-term Supply Agreement Expansion | Three-to-five-year fixed-price contracts with energy-linked escalators buffer buyers against electricity cost volatility. |
| FCC Certification Pipeline Development | Food-grade qualification constraints enable margin expansion by compressing supplier pools for premium applications. |
| Mexico Distribution Network Buildout | Nearshoring chemical processing operations in Nuevo León and Altamira creates new bulk liquid KOH demand nodes. |
| Potash Mining Asset Integration | Saskatchewan and Manitoba feedstock control secures cost advantages against geographic supply vulnerability. |
Research Approach
Direct dialogue with chlor-alkali plant managers, downstream chemical procurement leads, water treatment utility operators, and regional distributor principals grounded qualitative assessment in operational reality. Secondary validation drew from EPA effluent guideline filings, SEC 10-K disclosures by integrated producers, ACC chemical industry reports, and customs trade flow data. Bottom-up volume triangulation across product grade, end-use industry, and packaging format segments converged with top-down macroeconomic anchoring.
Segmented outputs across liquid, flake, pearl, and powder physical formats combined with water treatment, chemical manufacturing, food processing, and agriculture end-use splits to generate demand projections across the analysis window. CAGRs derived from electrolytic production capacity expansion schedules, EPA enforcement timeline assumptions, and nearshoring flow estimates. Energy cost volatility scenarios and PFAS remediation technology substitution curves served as sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to membrane cell diffusion rates, Canadian feedstock logistics disruptions, and EPA PFAS guidance finalization. Outputs reflect documented assumptions about regulatory enforcement intensity and technology substitution thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Isopentane Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
Barium Sulphate Market
Bulk Chemicals
Carbon Black Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Methyl Gluceth-10 Market