
 Global Polymer Clay Market | 2026-2036
Global Polymer Clay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymer Clay Market Foresight
Modular kit bundling is rebalancing buyer choice in polymer clay as manufacturers package base clays with specialized tools and color-matched accessories. Polyform Products Company leverages its Sculpey brand architecture to sustain shelf visibility across mass-market craft retailers. Van Aken International anchors the professional segment with Plastalina formulations that dominate stop-motion animation studios. Kato Polyclay differentiates through higher-temperature curing protocols that appeal to jewelry makers seeking durability.
Polymer clay denotes a synthetic modeling material comprising polyvinyl chloride (PVC) particles suspended in plasticizer, cured at 265–275°F to achieve dimensional stability. Its primary commercial purpose spans detailed sculpting, jewelry component fabrication, and educational prototyping where fired ceramics prove impractical. Soft clay variants lead volume shipments through hobbyist channels, while hard clay commands margin pools among professional artists requiring fine detail retention. Bead and sheet material forms attract the fastest-growing application segment in jewelry making, whereas block configurations remain mature in institutional educational procurement.
REACH in Europe restricts phthalate plasticizer content, compelling reformulation toward citrate-based alternatives. ASTM F963 in the United States governs toy safety standards that directly affect polymer clay marketed to children. Japan's METI chemical substance reporting requirements shape import compliance for foreign suppliers. Stakeholders must monitor evolving bioplasticizer certification pathways and regional labeling mandates to secure sustained market access.
Market Dynamics
Reformulation pressure from REACH phthalate restrictions is compressing manufacturer margins while simultaneously opening premium positioning for citrate-based alternatives. This regulatory pivot is reshaping raw material sourcing strategies across the value chain.
Growth Catalysts
- Jewelry fabrication demand:Bead and sheet polymer clay forms attract artisan producers seeking fine-detail alternatives to fired ceramics. This end-use vertical drives volume through craft retail networks.
- Educational procurement mandates:K-12 institutions in Germany and Japan specify non-toxic modeling materials for STEM curricula. ASTM F963 compliance enables shelf placement in school supply channels.
- Stop-motion animation resurgence:Streaming content production is consolidating demand for professional-grade plastalina formulations. Studios in the United Kingdom and South Korea anchor this specialized segment.
Market Restraints
- Plasticizer cost volatility:Epoxidized soybean oil and citrate alternatives trade at premiums to legacy phthalates. Price swings compress formulation economics for mid-tier producers.
- Supply concentration in PVC resin:Base polymer production clusters in China and the United States Gulf Coast. Geographic concentration exposes buyers to shipping disruptions and tariff exposure.
- Curing temperature limitations:Standard home ovens cap operational temperatures at 275°F. This technical ceiling restricts high-performance formulations from reaching jewelry durability targets.
Strategic Opportunities
- Bioplasticizer certification pathways:EU Green Deal bio-based content thresholds create first-mover advantage for compliant suppliers. Certification unlocks public procurement preference in France and Italy.
- Modular kit bundling:Tool-and-accessory packaging expands average transaction value in hobbyist channels. This distribution innovation captures shelf space from unbundled competitors.
- India craft retail expansion:Urban hobbyist communities in Mumbai and Bangalore demonstrate unmet demand for imported polymer clay brands. Local distributor partnerships reduce import friction.
Industry Challenges
- Reformulation timeline compression:REACH substance restriction updates demand 12-18 month product redevelopment cycles. Smaller manufacturers lack toxicology testing infrastructure to match pace.
- Color-matching standardization gaps:No universal Pantone-equivalent system exists across polymer clay brands. This fragmentation frustrates professional artists managing multi-supplier inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymer Clay Market |
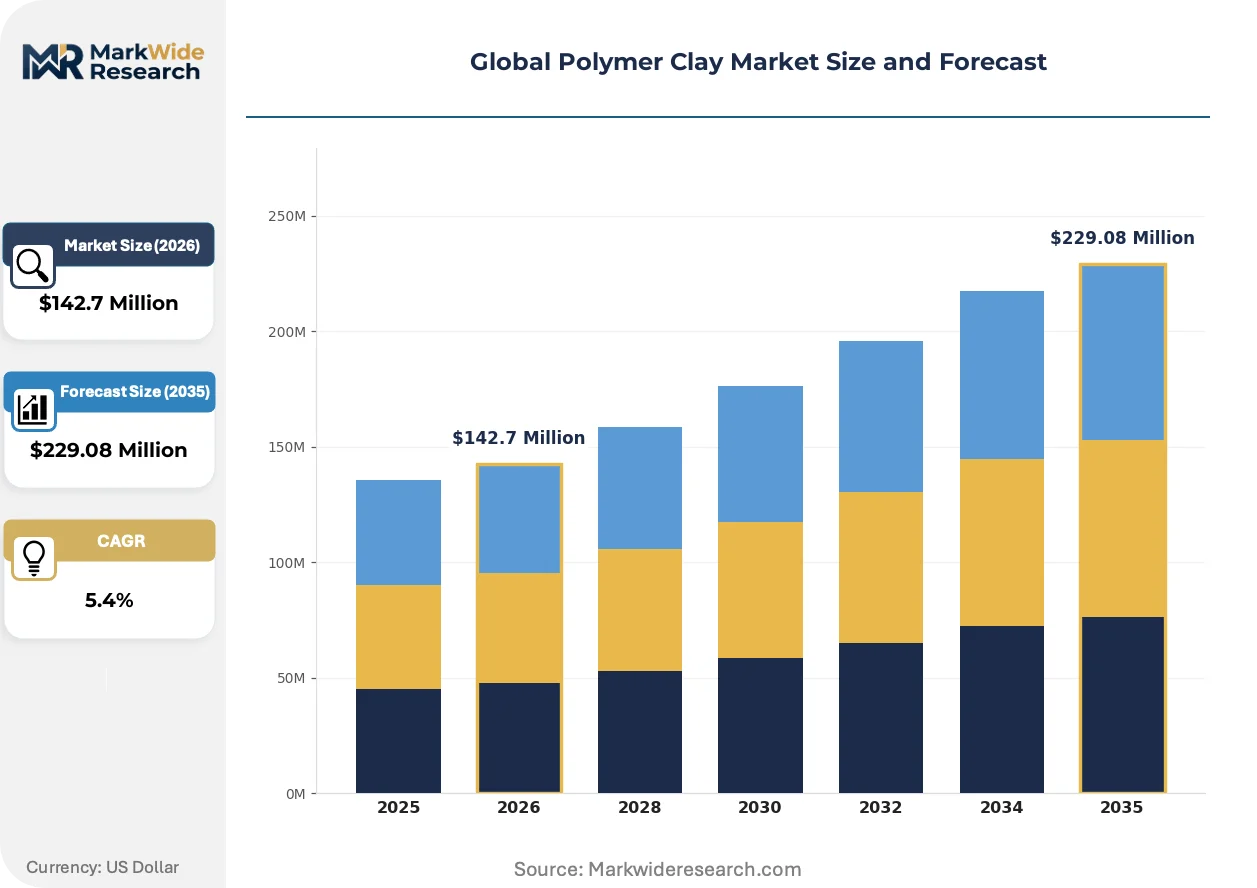
| Market Size in 2026 | $142.7 Million |
| Market Size in 2035 | $229.08 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Clay, Hard Clay, Dough Clay, Air-dry Clay, Self-hardening Clay Material Form: Beads, Sheets, Blocks, Pellets, Powder Application: Arts & Crafts, Jewelry Making, Model Prototyping, Educational Projects, Decorative Items End User: Hobbyists, Educational Institutions, Professional Artists, Craft Stores, Design Studios |
| Companies Covered | Van Aken International, Kato Polyclay, Polyform Products Company, Cernit, Makin's USA, STAEDTLER Mars GmbH & Co. KG, Viva Decor GmbH, Craft Polymers, American Art Clay Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymer Clay Market Shifts & Advancements
Digital content creation tools are reshaping how polymer clay artists prototype designs before physical production. This pre-visualization shift is compressing material waste rates while elevating precision expectations.
Ultraviolet-curable polymer clay formulations are consolidating position in jewelry prototyping workflows. These materials cure under LED exposure in 60-90 seconds versus 15-30 minute oven cycles. Professional studios in Tokyo and Los Angeles are adopting UV systems to compress client turnaround timelines.
REACH Annex XVII phthalate restrictions are forcing systematic plasticizer migrations across European supply chains. ECHA substance evaluation timelines now drive 24-month reformulation roadmaps for affected product lines. German manufacturers are accelerating citrate and bio-based alternative certifications to defend retail placement.
Direct-to-artist subscription models are displacing traditional craft-store purchasing for professional users. Monthly curated color palettes and exclusive tool drops build predictable revenue for suppliers. This channel innovation concentrates in the United States and Australia where established creator-economy infrastructure supports fulfillment at scale.
Global Polymer Clay Market Segmentation
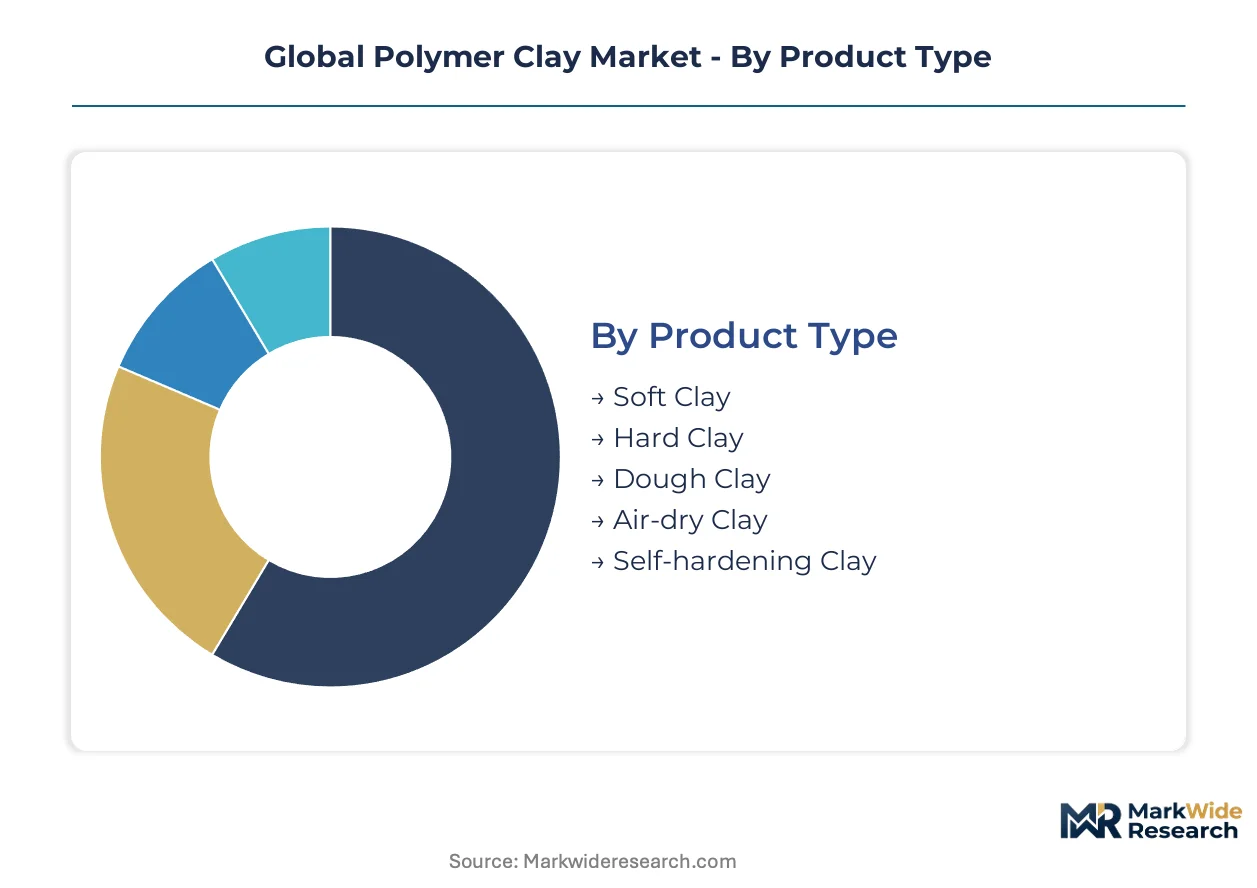
Polymer clay segmentation reveals how formulation chemistry and physical form factor into channel economics. Distinct buyer profiles across hobbyist, educational, and professional verticals demand tailored product architectures.
Product Type:
Supply concentration in soft clay manufacturing dominates volume economics, with formulation expertise clustering among established PVC compounders.
- Soft Clay:PVC-polymer matrix with elevated plasticizer load yields pliable, finger-moldable consistency. Jewelry makers in the United States and Germany drive procurement through craft retail networks, though REACH phthalate restrictions force ongoing reformulation toward citrate-based alternatives.
- Hard Clay:Reduced plasticizer content and higher molecular-weight PVC resins produce firmer bodies that hold fine detail through curing. Professional sculptors and stop-motion animation studios in the United Kingdom and South Korea specify these formulations for precision work.
- Dough Clay:Salt-flour-starch composite formulations target early childhood education with edible-safe positioning. METI chemical reporting requirements in Japan shape import compliance for foreign suppliers.
- Air-dry Clay:Water-evaporation curing eliminates oven requirements, expanding access in institutional settings lacking kiln infrastructure. K-12 procurement in Germany favors these variants for classroom deployment.
- Self-hardening Clay:Modified cellulose binders enable ambient curing with moderate humidity exposure. Hobbyist channels in Australia and Canada stock these for beginner project kits.
Today's leader: Soft Clay. Tomorrow's challenger: Hard Clay.
Material Form:
Form factor selection directly determines tooling requirements and downstream processing economics for end users.
- Beads:Pre-formed spherical and cylindrical shapes accelerate jewelry assembly workflows. Artisan producers in Mumbai and Bangalore import these to bypass hand-rolling labor.
- Sheets:Rolled uniform thickness enables cane-slicing and veneer techniques for complex pattern work. Professional artists managing multi-supplier inventories face color-matching standardization gaps across brands.
- Blocks:Standardized rectangular formats dominate educational procurement for sculpting curricula. ASTM F963 compliance enables shelf placement in United States school supply channels.
- Pellets:Small-diameter extrusions suit injection-molding style presses for high-volume component fabrication. Design studios in Los Angeles and Tokyo deploy these for iterative prototyping.
- Powder:Dehydrated base polymer requires reconstitution with plasticizer, offering extended shelf stability. Specialty distributors stock these for custom formulation laboratories.
Blocks command institutional volume. Beads and sheets are climbing the fastest through artisan channels.
Application:
Application-driven demand fragments across price-insensitive professional workflows and cost-conscious hobbyist experimentation.
- Arts & Crafts:General-purpose sculpting and decorative object creation spans all skill levels. Modular kit bundling is rebalancing buyer choice as manufacturers package base clays with specialized tools.
- Jewelry Making:Bead and sheet forms attract artisan producers seeking fine-detail alternatives to fired ceramics. Ultraviolet-curable formulations are consolidating position in rapid prototyping workflows.
- Model Prototyping:Industrial designers and architectural modelers specify dimensional stability through curing cycles. Digital content creation tools are reshaping how artists prototype designs before physical production.
- Educational Projects:STEM curricula in Germany and Japan specify non-toxic modeling materials with documented safety certifications. Direct-to-artist subscription models are displacing traditional craft-store purchasing for professional users.
- Decorative Items:Home décor and gift applications favor air-dry and self-hardening variants to eliminate oven investment. Urban hobbyist communities in India demonstrate unmet demand for imported polymer clay brands.
Jewelry Making leads margin capture. Educational Projects shows steepest expansion trajectory through procurement mandates.
End User:
End-user category determines pricing tolerance, technical specification complexity, and channel access requirements.
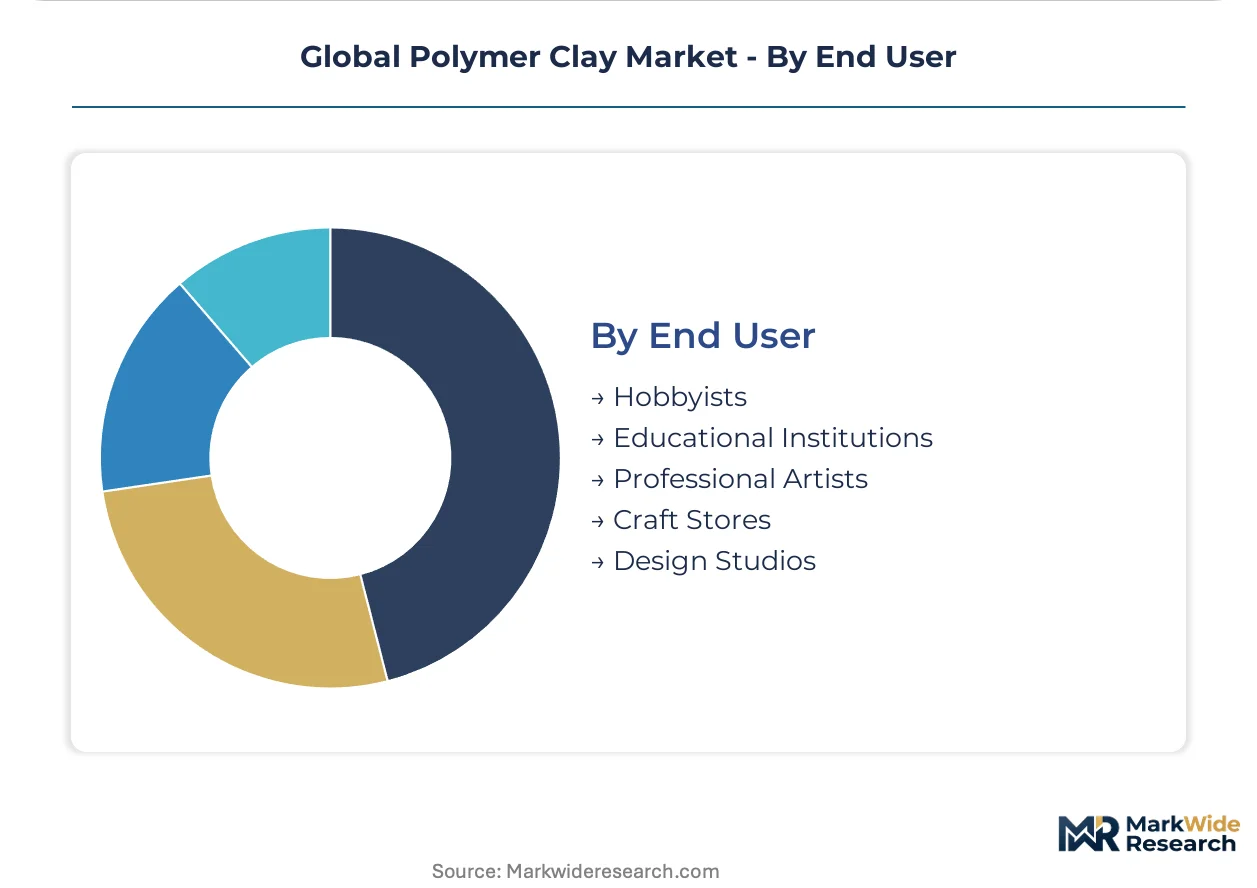
- Hobbyists:Price-sensitive occasional users purchase through mass-market craft retailers. Monthly curated color palettes and exclusive tool drops build predictable supplier revenue in the United States and Australia.
- Educational Institutions:Volume buyers with formal safety documentation requirements and centralized procurement processes. K-12 specifications in Germany and Japan prioritize non-toxic formulations.
- Professional Artists:Technical sophistication demands color consistency, durability, and fine-detail retention. No universal Pantone-equivalent system exists across polymer clay brands, frustrating multi-supplier inventory management.
- Craft Stores:Retail intermediaries curating assortment breadth for local maker communities. Polyform Products Company leverages Sculpey brand architecture to sustain shelf visibility.
- Design Studios:Commercial creative services firms integrating polymer clay into client deliverables. Streaming content production is consolidating demand for professional-grade plastalina formulations.
Hobbyists anchor volume shipments. Professional Artists drive premium tier development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer clay manufacturing originated in Germany during the early 20th century with industrial PVC compounding innovations. The craft material subsequently migrated to the United States through postwar hobbyist channels. Contemporary demand clusters in economies with established maker-culture infrastructure and formalized educational procurement systems.
United States
Mass-market craft retail networks and direct-to-artist subscription models drive procurement volume. ASTM F963 toy safety standards govern shelf placement in educational channels. Los Angeles design studios anchor professional-grade polymer clay consumption for stop-motion animation and jewelry prototyping workflows.
Germany
K-12 STEM curricula specify non-toxic modeling materials with documented REACH compliance. ECHA substance evaluation timelines drive manufacturer reformulation cycles toward citrate-based plasticizers. Bavarian industrial compounders supply base PVC resins to European formulation specialists.
Japan
Professional jewelry makers and artisan producers command premium-tier formulations with fine-detail retention. METI chemical substance reporting requirements shape import compliance for foreign suppliers. Tokyo studios adopt ultraviolet-curable systems to compress client turnaround timelines.
United Kingdom
Stop-motion animation studios consolidate demand for professional-grade plastalina formulations. REACH Annex XVII phthalate restrictions mandate systematic plasticizer migrations across supply chains. London-based craft retailers curate modular kit bundling for hobbyist communities.
India
Urban hobbyist communities in Mumbai and Bangalore demonstrate unmet demand for imported polymer clay brands. Central bank foreign exchange regulations affect distributor import financing. Local craft retail expansion partnerships reduce friction for international suppliers entering the market.
Global Polymer Clay Market Competitive Landscape
The competitive structure tilts toward specialty compounders with formulation expertise in PVC-plasticizer matrices. Tiered positioning separates mass-market hobbyist suppliers from professional-grade specialists serving animation studios and jewelry makers. Three archetypes dominate: heritage craft-material houses, industrial PVC compounders with craft divisions, and boutique formulation laboratories. Capacity expansion and modular kit bundling represent the dominant competitive moves reshaping channel economics.
Within the heritage craft-material tier, Polyform Products Company and Van Aken International occupy established positions across North American distribution channels. STAEDTLER Mars GmbH & Co. KG anchors European supply with German manufacturing pedigree. Kato Polyclay exemplifies the boutique formulation archetype through specialized curing protocols targeting professional jewelry makers.
| Leading Market Players |
|---|
| Van Aken International |
| Kato Polyclay |
| Polyform Products Company |
| Cernit |
| Makin's USA |
| STAEDTLER Mars GmbH & Co. KG |
| Viva Decor GmbH |
| Craft Polymers |
| American Art Clay Co. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap compounders in Germany and the United States Gulf Coast anchor polymer clay production, their conservative capital structures enabling patient pricing discipline even as phthalate reformulation costs surge. This ownership pattern concentrates supply-side bargaining power among legacy PVC specialists while forcing downstream buyers to absorb citrate-based plasticizer premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates professional-grade formulations from hobbyist SKUs. Price differentiation hinges on REACH compliance certification and volume procurement scale, with German educational institutions least sensitive and Indian hobbyist importers most price-responsive. Cost compression in mid-tier segments is intensifying because citrate plasticizers trade at persistent premiums to legacy phthalates.
Supply Chain Analysis
PVC resin supply rests on production clusters in China, the United States, and Germany, with epoxidized soybean oil and citrate plasticizers drawing from specialty chemical producers in Japan and the Netherlands. Geographic concentration exposes buyers to shipping disruptions and tariff exposure across trans-Pacific routes. Distribution runs through craft retail networks in North America and Europe, with direct-to-artist subscription channels gaining share in Australia and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer clay manufacturing arbitrage opportunities sit between REACH-compliant European production and cost-optimized Asian compounding, with regulatory compliance costs in Germany running substantially above export-oriented Chinese PVC processing.
For Market Incumbents: Acquire toxicology testing infrastructure to compress 12-18 month reformulation cycles. Secure backward integration into citrate plasticizer supply to defend margin position against mid-tier competitors lacking scale. Channel control through modular kit bundling protects shelf visibility from unbundled rivals. For New Entrants and Emerging Players: Capture white-space demand in Indian urban hobbyist communities through local distributor partnerships. Target ultraviolet-curable formulations for jewelry prototyping studios in Tokyo and Los Angeles. A direct-to-artist subscription go-to-market model bypasses entrenched craft retail gatekeepers. For Investors and Strategic Acquirers: Valuations sit cheapest among boutique formulation laboratories with specialized curing protocols. Long-term viability favors suppliers with demonstrated bioplasticizer certification pathways under EU Green Deal thresholds. Watch ECHA substance evaluation timelines as the key inflection signal for reformulation-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Bioplasticizer Certification Investment | Unlocks public procurement preference in France and Italy under EU Green Deal thresholds. |
| Modular Kit Bundling Expansion | Captures shelf space from unbundled competitors in United States mass-market craft retail. |
| India Distribution Partnership | Reduces import friction for international suppliers targeting Mumbai and Bangalore hobbyists. |
| Direct-to-Artist Subscription Launch | Builds predictable revenue through monthly curated palettes in creator-economy markets. |
| UV-Curable Formulation Scale-Up | Compresses client turnaround timelines for jewelry prototyping studios in Tokyo and Los Angeles. |
Research Methodology
Direct dialogue with polymer clay plant managers, craft retail category buyers, educational procurement officers, and jewelry studio technical directors grounded qualitative insights. Secondary validation drew from ECHA substance evaluation databases, ASTM F963 compliance filings, customs trade records, and SEC disclosures from listed chemical compounders. Bottom-up demand modeling across hobbyist, educational, and professional end-use segments triangulated against top-down PVC resin consumption trends.
Bottom-up volume builds aggregated demand across soft clay, hard clay, dough clay, air-dry, and self-hardening product types, with cross-segment calibration against bead, sheet, block, pellet, and powder form factors. CAGRs derived from regression analysis of historical procurement patterns and forward projection of jewelry fabrication demand, educational procurement mandates, and stop-motion animation resurgence. Industry-specific inputs included REACH Annex XVII phthalate restriction timelines and METI chemical reporting requirement changes.
Regulatory enforcement variance, plasticizer cost volatility, and PVC resin supply disruption are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions about citrate alternative adoption rates and regional procurement mandate expansion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Sodium Stannate Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Putty Fillers Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Solketal Market