
 Superacids Market | 2026-2036
Superacids Market Size, Share, and Industry Trends Forecast 2026-2036
Superacids Market Analytics
A shortage of fluorine chemists is collapsing near-term capacity expansion plans across specialty acid producers. Solvay leverages its integrated fluorochemical supply chain to sustain European production of fluoroantimonic acid. Honeywell International Inc. anchors North American availability through captive HF feedstock and dedicated logistics infrastructure. Daikin Industries, Ltd. competes on fluorinated precursor cost positions tied to its refrigerant manufacturing base.
Superacids are acids with acidity exceeding that of 100% sulfuric acid, typically quantified by Hammett acidity functions below minus twelve, with fluoroantimonic acid representing the strongest known superacid through its protonating ability. These substances serve primarily as non-oxidizing proton donors in hydrocarbon isomerization, alkylation, and cracking operations where conventional mineral acids prove insufficiently active. Fluoroantimonic acid and triflic acid command premium positioning due to irreplaceable roles in fine chemical synthesis and pharmaceutical intermediate manufacturing. Petrochemical refining applications exhibit structural momentum as refiners seek higher-octane outputs from lighter feedstocks.
EPA hazardous waste regulations and OSHA process safety management standards govern superacid handling, storage, and worker exposure thresholds across United States facilities. The EU REACH framework mandates registration and risk assessment for fluorinated superacid imports, constraining non-European supplier market access. Stakeholders must monitor evolving fluorochemical feedstock availability and assess backward integration into hydrogen fluoride supply as a decisive competitive variable.
Market Dynamics
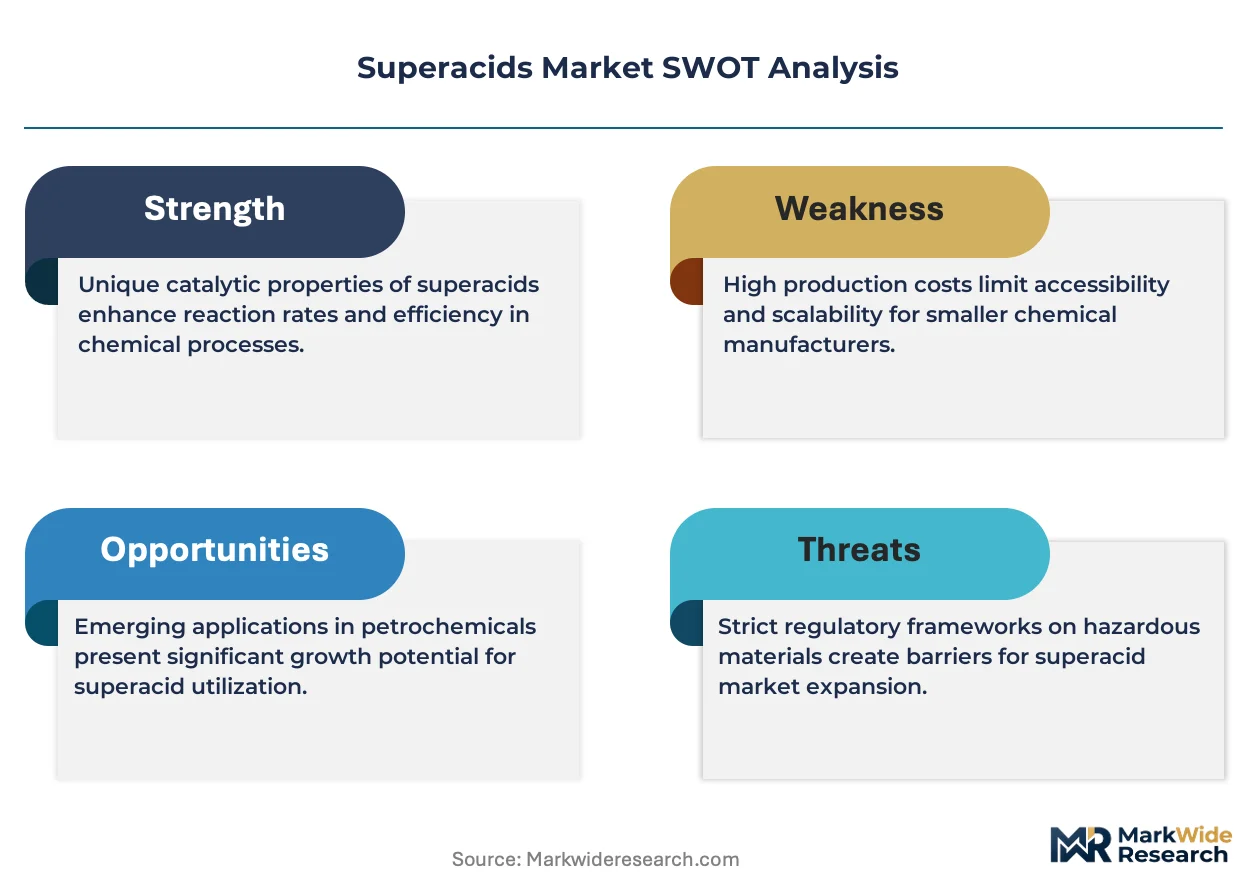
Fluorochemical feedstock concentration and specialty chemist scarcity are compressing capacity expansion timelines across superacid manufacturing. Refiners seeking higher-octane outputs from lighter shale-derived streams are intensifying catalyst consumption patterns.
Growth Catalysts
- REACH Registration Requirements:The EU framework mandates rigorous risk assessment for fluorinated superacid imports, creating compliance-driven demand for registered European suppliers with established dossiers.
- Shale Feedstock Abundance:United States petrochemical complexes leverage domestically sourced light hydrocarbons, sustaining acid catalyst consumption for isomerization and alkylation units.
- Pharmaceutical Intermediate Synthesis:Fine chemical manufacturers deploy fluoroantimonic acid and triflic acid for protonation reactions where conventional mineral acids fail.
Market Restraints
- Hydrogen Fluoride Supply Concentration:Captive HF production anchors competitive positioning, leaving non-integrated producers exposed to feedstock volatility and transport restrictions.
- OSHA Process Safety Management:Stringent worker exposure thresholds and containment protocols elevate capital requirements for new facility construction.
- Sulfuric Acid Substitution:Conventional mineral acids retain cost advantages in less demanding cracking applications, capping superacid penetration.
Strategic Opportunities
- India Petrochemical Expansion:Downstream capacity additions under PLI scheme incentives create untapped demand for alkylation catalysts in refinery upgrades.
- Continuous Flow Reactor Integration:Pharmaceutical manufacturers combine superacid catalysis with microreactor engineering to enhance selectivity and reduce waste.
- EU F-Gas Regulation Phase-Down:Fluorochemical recovery and recycling mandates incentivize backward integration into HF supply chains for acid producers.
Industry Challenges
- Fluorine Chemist Talent Pipeline:Academic programs produce insufficient specialists to staff process development and safety engineering roles.
- Legacy Equipment Compatibility:Existing refinery infrastructure requires costly metallurgical upgrades to handle superacid corrosion profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superacids Market |
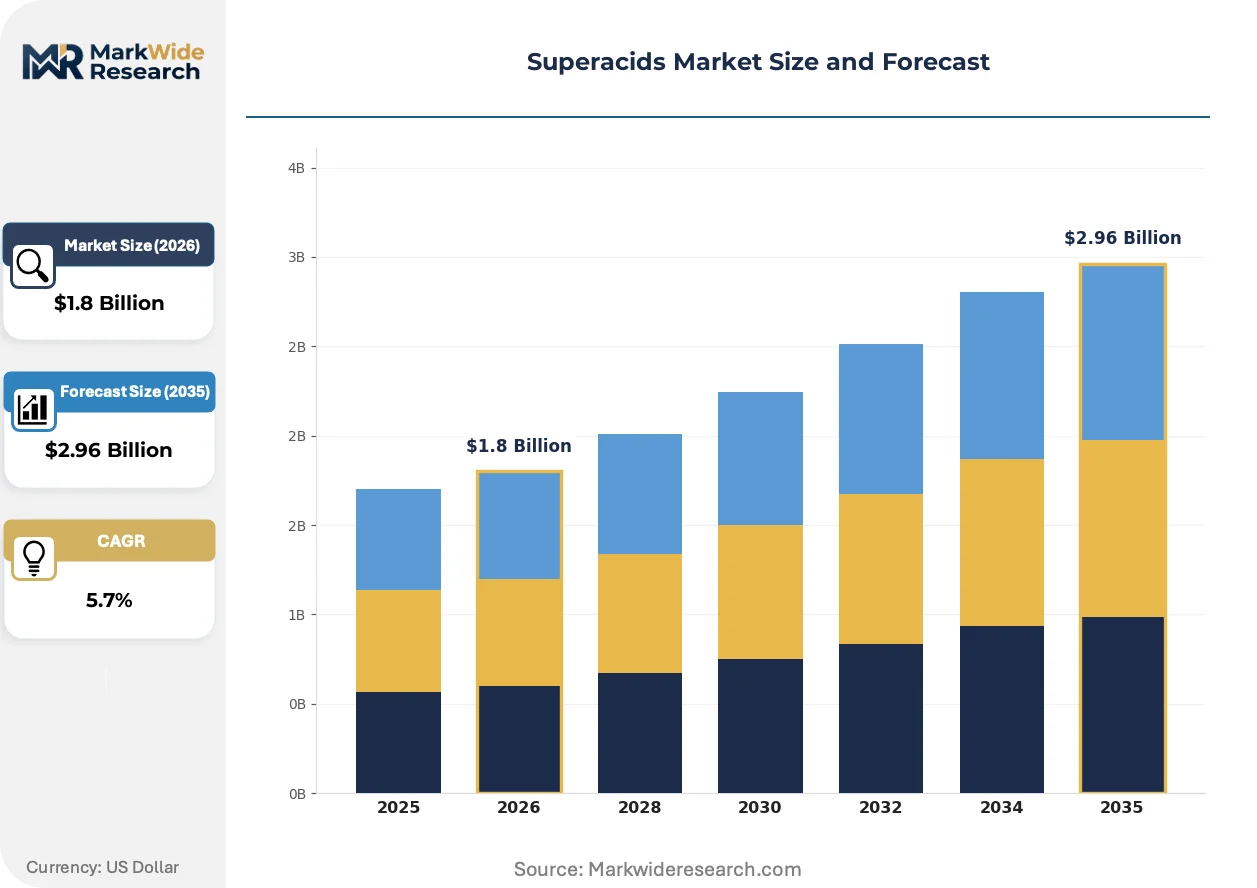
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fluoroantimonic Acid, Triflic Acid, Magic Acid, Fuming Sulfuric Acid Application: Catalysis, Organic Synthesis, Chemical Production, Petrochemical Refining End User: Chemical Industry, Pharmaceutical Sector, Petrochemical Firms, Research Institutions Packaging Type: Cylinders, Bottles, Tanks, Pails |
| Companies Covered | Solvay, Honeywell International Inc., BASF SE, DuPont de Nemours, Inc., Merck KGaA, The Chemours Company, Arkema Group, Daikin Industries, Ltd., TCI Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superacids Market Evolving Landscape
Process intensification and regulatory stringency are fragmenting production methodologies across the superacid value chain. Manufacturers are reconfiguring supply architectures to balance feedstock security with emission containment.
Modular superacid generation systems are bifurcating the traditional centralized production model. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting containerized on-site units to eliminate hazardous transport. This technology is compressing logistics costs while expanding addressable demand among mid-volume fine chemical synthesizers previously excluded by minimum order constraints.
EPA hazardous waste regulations under RCRA subtitle C are tightening manifest requirements for spent acid disposal. Refiners in Texas and Louisiana face elevated compliance costs for tracking cradle-to-grave liability. Alkylation unit operators are responding by investing in acid regeneration technologies that reduce external waste volumes.
Buyer consolidation among North American refiners is compressing procurement cycles and demanding multi-year supply commitments. Integrated energy companies in the Gulf Coast region are unbundling catalyst procurement from engineering services, forcing superacid suppliers to compete on standalone chemical pricing rather than bundled technical support.
Superacids Market Segmentation
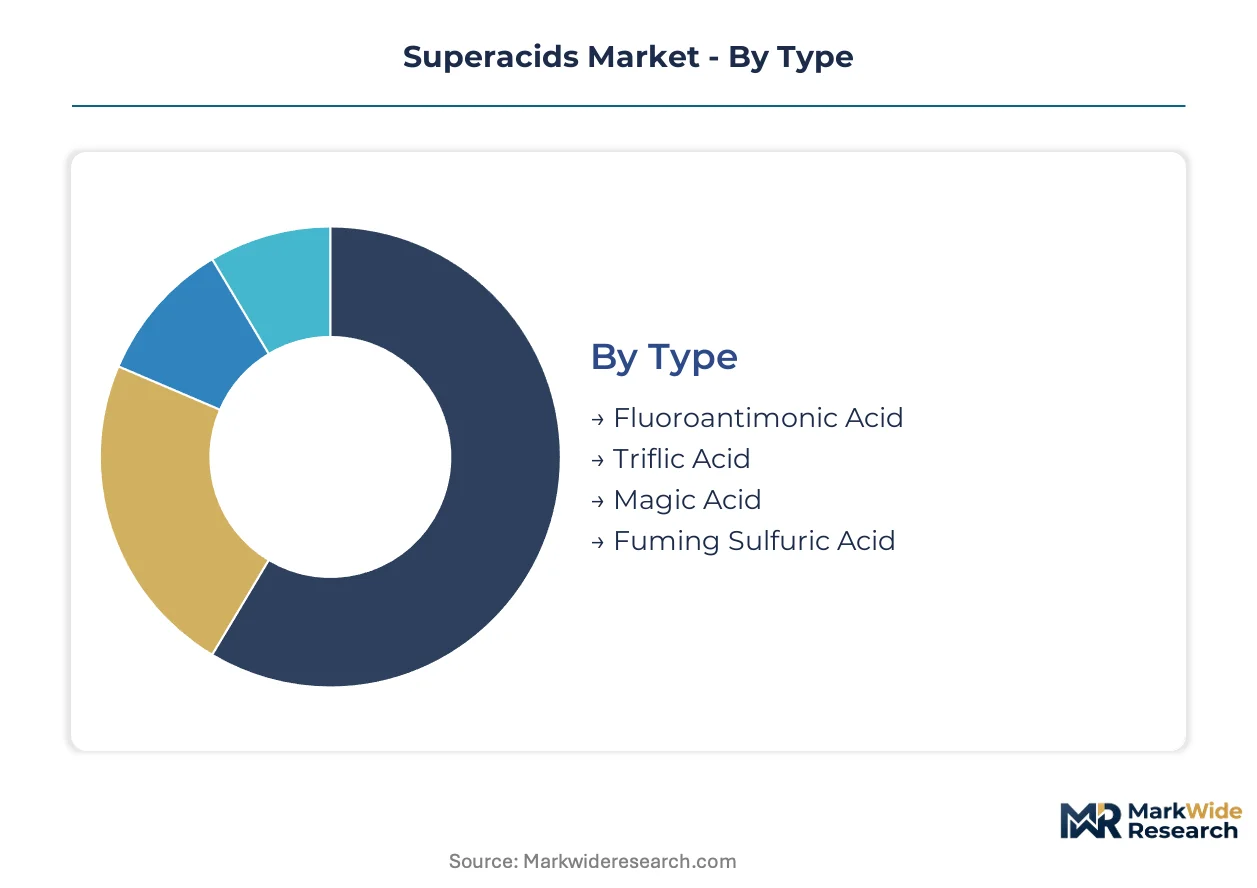
Superacid demand fragments across distinct technical specifications and handling requirements. Each segment carries unique regulatory burdens and supply chain constraints that reshape competitive positioning.
Type:
Domestic production concentrates on commodity-grade acids, while fluoroantimonic and triflic variants flow through specialized export channels tied to pharmaceutical and fine chemical demand.
- Fluoroantimonic Acid:This compound, formed from hydrogen fluoride and antimony pentafluoride, achieves Hammett acidity functions below minus twenty-five. United States Gulf Coast refiners consume volumes for hydrocarbon isomerization where conventional catalysts fail.
- Triflic Acid:Trifluoromethanesulfonic acid offers non-oxidizing proton donation with superior thermal stability. Swiss and German pharmaceutical contract manufacturers deploy it for peptide synthesis and carbohydrate modification reactions.
- Magic Acid:The antimony pentafluoride-fluorosulfonic acid blend serves niche research applications requiring extreme protonating power.
- Fuming Sulfuric Acid:Oleum variants with elevated SO3 content bridge mineral and superacid classifications for sulfuric acid upgrading operations.
Fuming sulfuric acid commands the established base. The steepest expansion runs through fluoroantimonic acid.
Application:
Cost tier differentiation separates high-value fine chemical synthesis from volume-driven refinery operations, with pricing spreads reflecting purity grades and technical service bundling.
- Catalysis:Acid-catalyzed hydrocarbon transformations in alkylation units demand continuous catalyst regeneration. Texas and Louisiana refiners invest in on-site acid recovery systems to reduce disposal liabilities under RCRA subtitle C.
- Organic Synthesis:Pharmaceutical intermediate manufacturers require anhydrous conditions and sub-ppm impurity profiles. Microreactor integration in Basel and Frankfurt sites enables continuous flow protonation with enhanced selectivity.
- Chemical Production:Specialty fluorochemical manufacturing consumes superacids as both catalysts and fluorinating agents.
- Petrochemical Refining:Isomerization and alkylation units processing light shale-derived feedstocks sustain acid consumption patterns.
Petrochemical refining commands the established base. Organic synthesis shows the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with integrated energy companies demanding multi-year supply commitments and research institutions accepting spot pricing.
- Chemical Industry:Fluorochemical producers and specialty chemical manufacturers anchor volume consumption. Captive hydrogen fluoride supply distinguishes integrated producers from merchant market dependents.
- Pharmaceutical Sector:cGMP compliance requirements and FDA validation protocols elevate supplier qualification barriers. Swissmedic and EMA inspections drive documentation burdens for European manufacturing sites.
- Petrochemical Firms:Alkylation unit operators in the United States prioritize logistics reliability and emergency response capabilities over unit pricing.
- Research Institutions:Academic and government laboratories generate fragmented demand with stringent small-volume handling requirements.
Chemical industry demand commands the established base. The pharmaceutical sector is expanding most quickly.
Packaging Type:
Supply concentration in hazardous materials logistics favors regional packaging hubs over distributed filling operations, with transport regulations constraining cross-border cylinder movements.
- Cylinders:High-pressure containers serve fluoroantimonic acid and gaseous precursors requiring inert atmosphere maintenance. DOT specification cylinders dominate United States interstate commerce.
- Bottles:Borosilicate glass and fluoropolymer-lined vessels handle laboratory-scale triflic acid distribution. Swiss pharmaceutical clusters specify UN-certified packaging with tamper-evident sealing.
- Tanks:Bulk stationary and transport tanks support refinery alkylation unit supply with dedicated fleet requirements.
- Pails:Polyethylene and fluoropolymer containers bridge mid-volume industrial applications with drum-handling infrastructure compatibility.
Tanks command the established base. Bottles show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss and German pharmaceutical clusters where cGMP compliance elevates supplier margins, while United States Gulf Coast refiners extract volume discounts through consolidated procurement. This asymmetry reshapes regional investment priorities across the superacid value chain.
United States
Shale-derived light hydrocarbon abundance sustains alkylation and isomerization unit demand along the Texas and Louisiana Gulf Coast. EPA RCRA subtitle C regulations tighten cradle-to-grave tracking for spent acid disposal, elevating on-site regeneration investments. Houston-area refiners unbundle catalyst procurement from engineering services, forcing standalone chemical pricing competition.
Germany
Pharmaceutical contract manufacturers in Frankfurt and Ludwigshafen drive anhydrous triflic acid consumption for peptide synthesis. ECHA REACH registration requirements constrain non-European supplier market access, favoring established dossier holders. The BASF SE manufacturing complex anchors fluoroantimonic acid availability for European fine chemical synthesis.
Switzerland
Basel's pharmaceutical cluster demands sub-ppm impurity profiles and continuous flow microreactor integration. Swissmedic inspection protocols elevate documentation burdens beyond standard EMA requirements. Lonza and Novartis supplier qualification programs compress approved vendor lists to three-to-five superacid sources per molecule.
China
Fluorochemical feedstock expansion in Zhejiang and Jiangsu provinces supports domestic acid catalyst manufacturing. NMPA oversight of pharmaceutical intermediates intensifies import substitution for triflic acid used in API synthesis. Yangtze River Delta chemical parks consolidate hydrogen fluoride supply through state-backed enterprise integration.
India
Petrochemical capacity additions under PLI scheme incentives create alkylation catalyst demand for refinery upgrades in Gujarat and Maharashtra. CDSCO pharmaceutical regulations align with ICH Q7 guidelines for superacid-handling API facilities. Reliance Industries' Jamnagar complex represents the largest single-site acid catalyst procurement opportunity in South Asia.
Superacids Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated fluorochemical producers commanding feedstock security and pharmaceutical specialists capturing purity premiums. The vendor base stratifies into three tiers: captive HF-integrated refiners, European REACH-registered dossier holders, and Asian cost-optimized merchant suppliers. Consolidation pressure intensifies as buyer procurement centralization eliminates mid-scale regional distributors. Dominant competitive moves include backward integration into hydrogen fluoride supply and modular on-site generation system deployment.
Among integrated fluorochemical producers, Solvay exemplifies the European REACH-registered archetype through its Belgian manufacturing base, while Honeywell International Inc. occupies the North American captive-feedstock position. Daikin Industries, Ltd. represents the Asian refrigerant-to-acid vertical integration model. These three anchors illustrate how feedstock control, regulatory dossier depth, and geographic proximity to demand clusters determine sustainable competitive position.
| Leading Market Players |
|---|
| Solvay |
| Honeywell International Inc. |
| BASF SE |
| DuPont de Nemours, Inc. |
| Merck KGaA |
| The Chemours Company |
| Arkema Group |
| Daikin Industries, Ltd. |
| TCI Chemicals |
| Others |
Value Network & Pricing Analysis
EU REACH registration requirements gate both supply qualification and price differentiation simultaneously, as non-registered producers face exclusion while dossier holders command certification premiums across pharmaceutical and refinery segments. This regulatory threshold compresses merchant market participation and amplifies spreads between compliant and non-compliant supply tiers.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade fluoroantimonic acid and triflic acid commands spreads of 40-60% above standard refinery-grade contracts. Three-tier pricing structure across pharmaceutical certification, industrial grade, and spot commodity levels reflects purity thresholds and documentation burdens. Cost compression in refinery alkylation catalysts is intensifying because Gulf Coast buyers unbundle engineering services from chemical supply. Petrochemical firms exhibit highest price sensitivity, while Swiss pharmaceutical contract manufacturers prioritize impurity profile compliance over unit cost.
Supply Chain Analysis
Extended lead times for DOT specification cylinders and UN-certified fluoropolymer bottles constrain just-in-time fulfillment across North American and European pharmaceutical clusters. Supply concentrates in Belgium, the United States, and Japan, with hydrogen fluoride feedstock drawing from Chinese and Mexican mining operations. Single-source vulnerability runs through captive HF production at integrated fluorochemical majors. Distribution runs through regional hazardous materials hubs rather than direct-to-customer fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against solid acid catalysts and ionic liquid alternatives that threaten superacid positions in refinery alkylation units. Incumbents must navigate this displacement pressure while securing feedstock control.
For Market Incumbents: Consolidate backward integration into hydrogen fluoride supply to neutralize feedstock volatility exposure. Anchor captive production in United States Gulf Coast and Belgian Antwerp corridors to maintain REACH-registered and EPA-compliant supply positions against emerging solid acid substitution threats. For New Entrants and Emerging Players: Anchor in India's Gujarat refinery corridor under PLI scheme incentives, where Reliance Industries' Jamnagar complex generates uncontracted alkylation catalyst demand. Target modular on-site generation systems for mid-volume Swiss pharmaceutical contract manufacturers seeking to eliminate hazardous transport liabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized fluorochemical assets and stranded REACH dossiers. Five-to-ten year viability hinges on feedstock security rather than purity technology alone. Monitor hydrogen fluoride spot price divergence from contract indices as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HF Supply | Captive hydrogen fluoride production neutralizes feedstock volatility for Belgian and United States manufacturing bases. |
| Modular On-Site Generation Deployment | Containerized units eliminate cross-border cylinder transport restrictions for Basel pharmaceutical clusters. |
| REACH Dossier Acquisition | Registration transfer accelerates European market access without multi-year substance evaluation timelines. |
| Acid Regeneration Technology Investment | On-site recovery systems reduce RCRA subtitle C disposal liabilities for Texas and Louisiana refiners. |
| Fluorine Chemist Talent Pipeline Development | University partnerships address specialty workforce scarcity constraining process development capacity. |
Research Methodology
Initial hypotheses were tested against primary input from fluorochemical plant managers, refinery procurement leads, pharmaceutical regulatory affairs directors, and hazardous materials logistics coordinators and refined through secondary validation. Trade data from customs authorities, ECHA registration databases, SEC 10-K filings from integrated chemical producers, and ACC industry reports anchored supply-side quantification. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level estimates.
Variance decomposition across type, application, end user, and packaging format dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-specific volume trajectories weighted by purity-adjusted pricing tiers. Hydrogen fluoride feedstock availability curves and pharmaceutical cGMP compliance adoption rates served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained shale feedstock abundance and stable REACH enforcement intensity; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Acrylic Pad Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Silicone Potting Compounds Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market