
 United States Hydroxypropyl Methylcellulose (HPMC) Market | 2026-2036
United States Hydroxypropyl Methylcellulose (HPMC) Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hydroxypropyl Methylcellulose (HPMC) Market Intelligence
Ethyl cellulose is restructuring competitive economics in controlled-release applications, pressuring HPMC suppliers to demonstrate superior film-forming efficiency and batch-to-batch consistency. Ashland Global Holdings Inc. leverages its integrated supply chain from raw cotton linter to finished excipient to sustain margin control across pharmaceutical accounts. Dow Chemical Company anchors industrial-grade HPMC production for construction adhesives and tile mortars, competing on scale and regional distribution density. Colorcon Inc. specializes in co-processed excipient systems that combine HPMC with functional polymers, differentiating through formulation science rather than commodity supply.
Hydroxypropyl methylcellulose is a semi-synthetic polymer derived from cellulose etherification with propylene oxide and methyl chloride, yielding a water-soluble polymer with tunable viscosity grades from 3 to 100,000 mPa·s and methoxy/hydroxypropoxy substitution ratios that govern gelation temperature and film permeability. Its primary commercial purpose centers on controlled drug release, tablet binding, and moisture barrier coatings in oral dosage forms, plus cement hydration control and workability retention in construction materials. Pharmaceutical-grade HPMC carries the highest margin pool due to FDA-mandated excipient master files and GMP compliance burdens that limit new entrants, while industrial-grade volumes dominate tonnage through construction sector offtake in commercial flooring and exterior insulation finish systems. Food-grade adoption is accelerating in plant-based meat analogs where HPMC provides thermal gelation mimicking animal protein texture.
FDA excipient guidance and USP-NF monograph standards govern HPMC purity, substitution uniformity, and microbial limits for pharmaceutical applications, creating compliance barriers that favor established manufacturers with Drug Master File registrations. OSHA Process Safety Management and EPA Clean Air Act requirements on etherification reactor emissions shape production economics at Texas and Louisiana manufacturing sites. State-level California Proposition 65 disclosure obligations and emerging PFAS contamination scrutiny are pressing suppliers to certify cellulose feedstock sourcing and validate absence of fluorinated process aids. Stakeholders must monitor how FDA quality-by-design initiatives and construction sector green building certifications will recalibrate specification thresholds across grade categories.
Market Dynamics
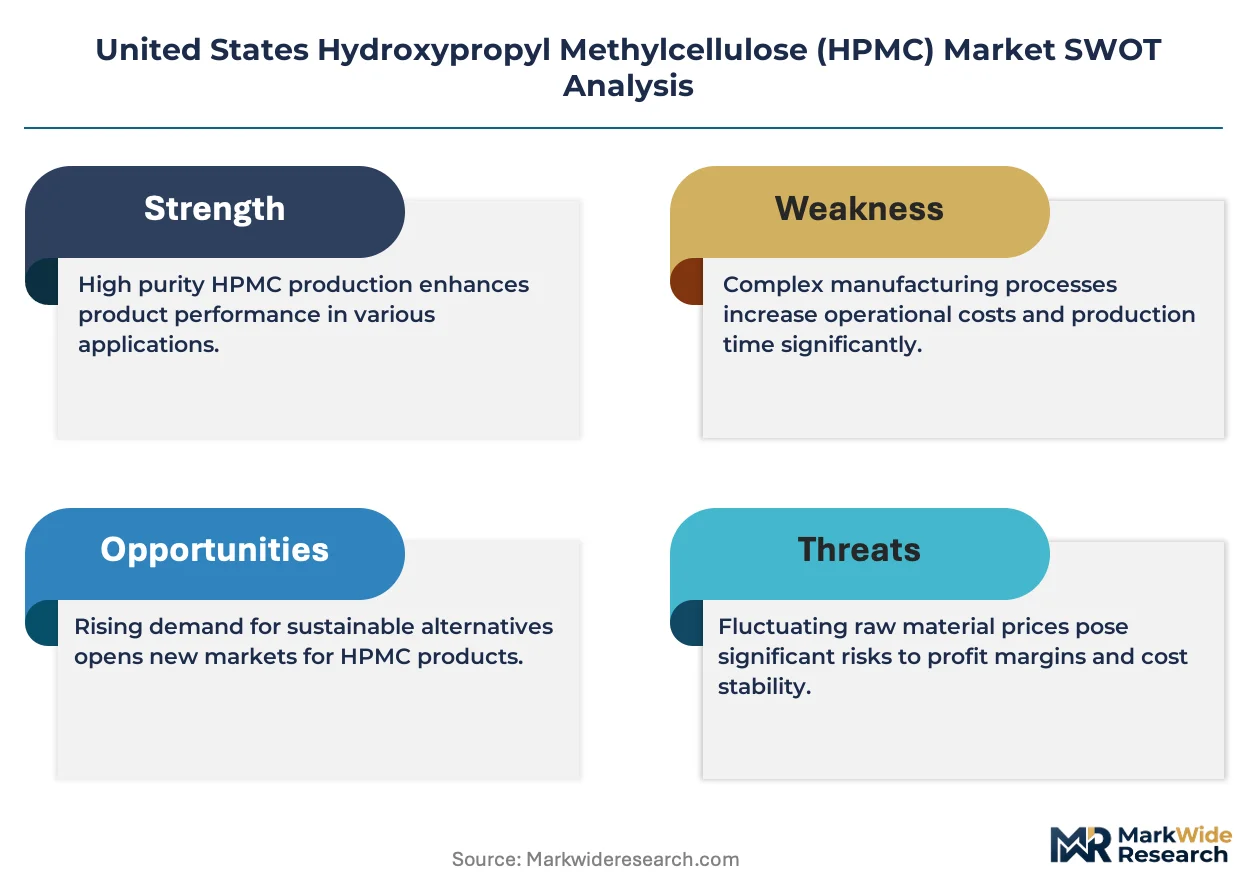
Ethyl cellulose substitution pressure is compressing HPMC margins in controlled-release applications, forcing suppliers to revalidate film-forming performance through tighter batch-to-batch consistency protocols.
Growth Catalysts
- Oral solid dosage expansion:Pharmaceutical tablet coatings and controlled-release formulations are expanding HPMC consumption as chronic disease prevalence rises.
- FDA excipient quality emphasis:The FDA's continued focus on excipient quality and documentation under IPEC guidelines is tightening supplier qualification requirements, favoring established registrants.
- Plant-based protein gelation:Food-grade adoption is accelerating in plant-based meat analogs where HPMC provides thermal gelation mimicking animal protein texture.
Market Restraints
- Propylene oxide feedstock volatility:Etherification chemistry exposes producers to petrochemical input cost swings that compress margin predictability.
- Northeast corridor supply concentration:Demand concentrates in the New Jersey-Pennsylvania pharmaceutical corridor, creating geographic dependency risk for contract manufacturing offtake.
- Ethyl cellulose functional equivalence:Ethyl cellulose is restructuring competitive economics in controlled-release applications through comparable barrier properties at lower substitution cost.
Strategic Opportunities
- Texas-Louisiana production expansion:OSHA Process Safety Management and EPA Clean Air Act compliance investments at existing etherification reactor sites create barrier-protected capacity for qualified operators.
- Co-processed excipient systems:Formulation science combining HPMC with functional polymers offers differentiation beyond commodity supply through tailored release profiles.
- California Proposition 65 certification:Emerging PFAS contamination scrutiny and disclosure obligations are pressing suppliers to certify cellulose feedstock sourcing, creating first-mover advantage for validated supply chains.
Industry Challenges
- GMP compliance talent scarcity:FDA-mandated excipient master files and pharmaceutical-grade production require specialized quality assurance personnel that command premium compensation.
- Drug Master File registration timelines:New entrants face extended FDA review periods for Type IV excipient submissions that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hydroxypropyl Methylcellulose (HPMC) Market |
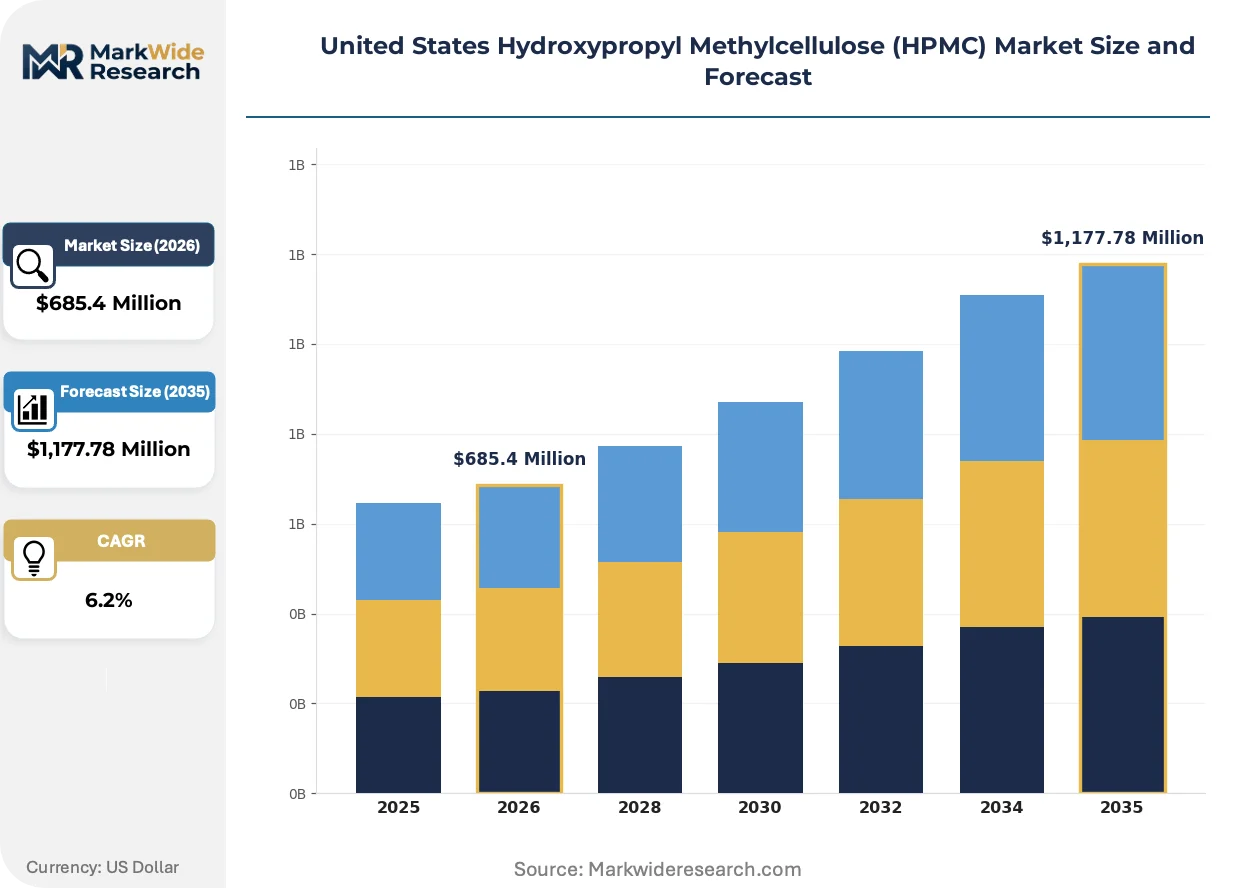
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Industrial Grade, Cosmetic Grade End User: Pharmaceuticals, Food & Beverages, Cosmetics, Construction Application: Film Forming, Thickening, Stabilizing, Binding Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Colorcon Inc., Sigma-Aldrich (Merck KGaA), Ashland Global Holdings Inc., Bright Pharmacaps Inc., Capsugel, Inc., Dow Chemical Company, CP Kelco U.S., Inc., Hercules-Tianpu, DuPont de Nemours, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hydroxypropyl Methylcellulose (HPMC) Market Strategic Shifts & Innovations
Formulation science and regulatory quality mandates are reshaping how HPMC suppliers compete, with differentiation shifting from base polymer supply toward integrated performance systems.
Hot-melt extrusion technology is converging with HPMC-based amorphous solid dispersion formulations to enhance bioavailability of poorly soluble APIs. Generic manufacturers and specialty pharma firms are adopting this combination at accelerating pace to extend patent cliffed molecules. The technology convergence is compressing traditional wet granulation equipment demand while expanding high-shear twin-screw extruder procurement.
USP-NF monograph standards for HPMC purity, substitution uniformity, and microbial limits are tightening testing protocols for pharmaceutical applications. Industrial consequence includes expanded analytical chemistry capacity investments and third-party certification requirements. The Northeast pharmaceutical corridor spanning New Jersey and Pennsylvania is most affected, with contract manufacturing organizations demanding supplier documentation that exceeds baseline monograph requirements.
Direct-to-formulator distribution is displacing traditional chemical distributor intermediation for pharmaceutical-grade HPMC. Large oral dosage form manufacturers are consolidating supplier relationships and demanding technical service integration that regional distributors cannot provide. This channel compression is most visible among New Jersey-based contract manufacturing organizations clustered near API production hubs.
United States Hydroxypropyl Methylcellulose (HPMC) Market Segmentation
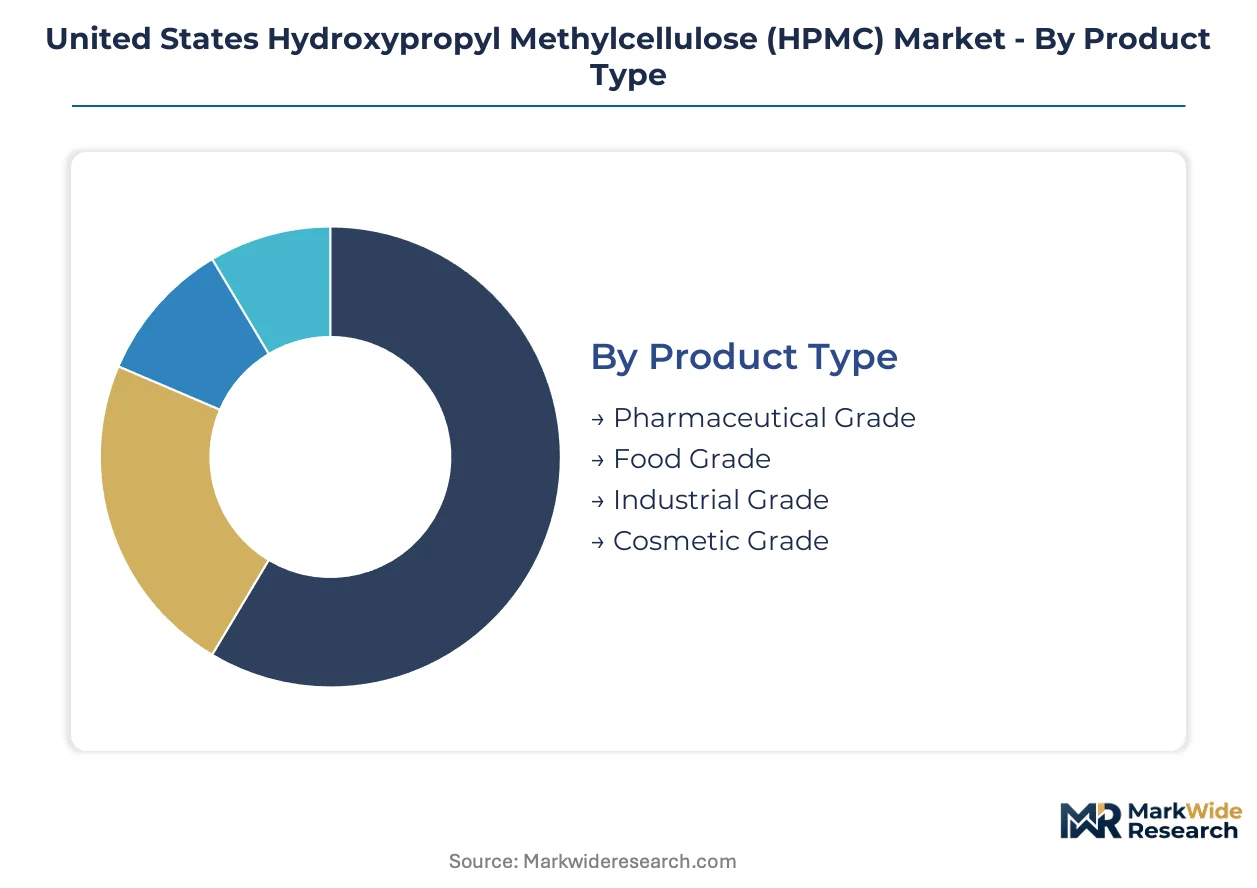
HPMC grade differentiation determines regulatory burden, margin structure, and customer qualification requirements across the United States market. Substitution ratios and viscosity specifications create distinct performance envelopes that align with end-use certification standards.
Product Type:
Upgrade cycles in pharmaceutical manufacturing are pushing formulators toward higher-substitution HPMC grades that deliver tighter batch-to-batch release kinetics.
- Pharmaceutical Grade:Methoxy and hydroxypropoxy substitution ratios between 19-24% and 4-12% respectively govern gelation temperature and film permeability in controlled-release tablets. FDA Drug Master File registrations and USP-NF monograph compliance create supplier qualification barriers that concentrate demand among New Jersey and Pennsylvania contract manufacturing organizations.
- Industrial Grade:Lower purity specifications with viscosity grades from 3 to 100,000 mPa·s serve cement hydration control and tile adhesive workability retention. Dow Chemical Company anchors production for construction sector offtake, competing on regional distribution density rather than certification depth.
- Food Grade:Thermal gelation properties between 50-70°C enable plant-based meat analog texture mimicry. FSSAI-aligned importers and domestic processors are validating supply chains for clean-label applications.
- Cosmetic Grade:Film-forming and emulsion stabilization in personal care formulations with lower microbial limit requirements than pharmaceutical standards.
Industrial Grade sits at the top of the volume ranking, with Pharmaceutical Grade climbing the fastest.
End User:
Cost tier stratification separates excipient purchasers seeking technical service integration from commodity buyers prioritizing price per kilogram.
- Pharmaceuticals:Oral solid dosage manufacturers demand co-processed excipient systems combining HPMC with functional polymers for tailored release profiles. Direct-to-formulator distribution is displacing traditional chemical distributor intermediation as large manufacturers consolidate supplier relationships.
- Construction:Commercial flooring and exterior insulation finish systems consume tonnage-dominant industrial-grade volumes. Etherification reactor sites in Texas and Louisiana serve regional cement and adhesive formulators.
- Food & Beverages:Plant-based protein processors specify food-grade HPMC for thermal gelation applications replacing animal-derived binders.
- Cosmetics:Personal care formulators utilize lower-certification grades for topical film formation and rheology modification.
Construction commands the largest volume share, though Pharmaceuticals generates the steepest margin expansion trajectory.
Application:
Functional performance requirements dictate substitution chemistry and viscosity selection across dosage form and material processing applications.
- Film Forming:Moisture barrier coatings for oral tablets require precise methoxy substitution to control permeability. Hot-melt extrusion technology convergence with amorphous solid dispersion formulations is expanding demand for high-performance grades among generic manufacturers.
- Binding:Tablet compression aids depend on particle size distribution and hydration kinetics. The Northeast pharmaceutical corridor demands documentation exceeding baseline USP-NF monograph requirements.
- Thickening:Construction adhesives and personal care emulsions utilize viscosity-building properties across industrial and cosmetic grades.
- Stabilizing:Freeze-thaw stability and emulsion persistence in food and cosmetic applications.
Film Forming leads application volume, with Binding gaining share fastest among specialty pharma formulators.
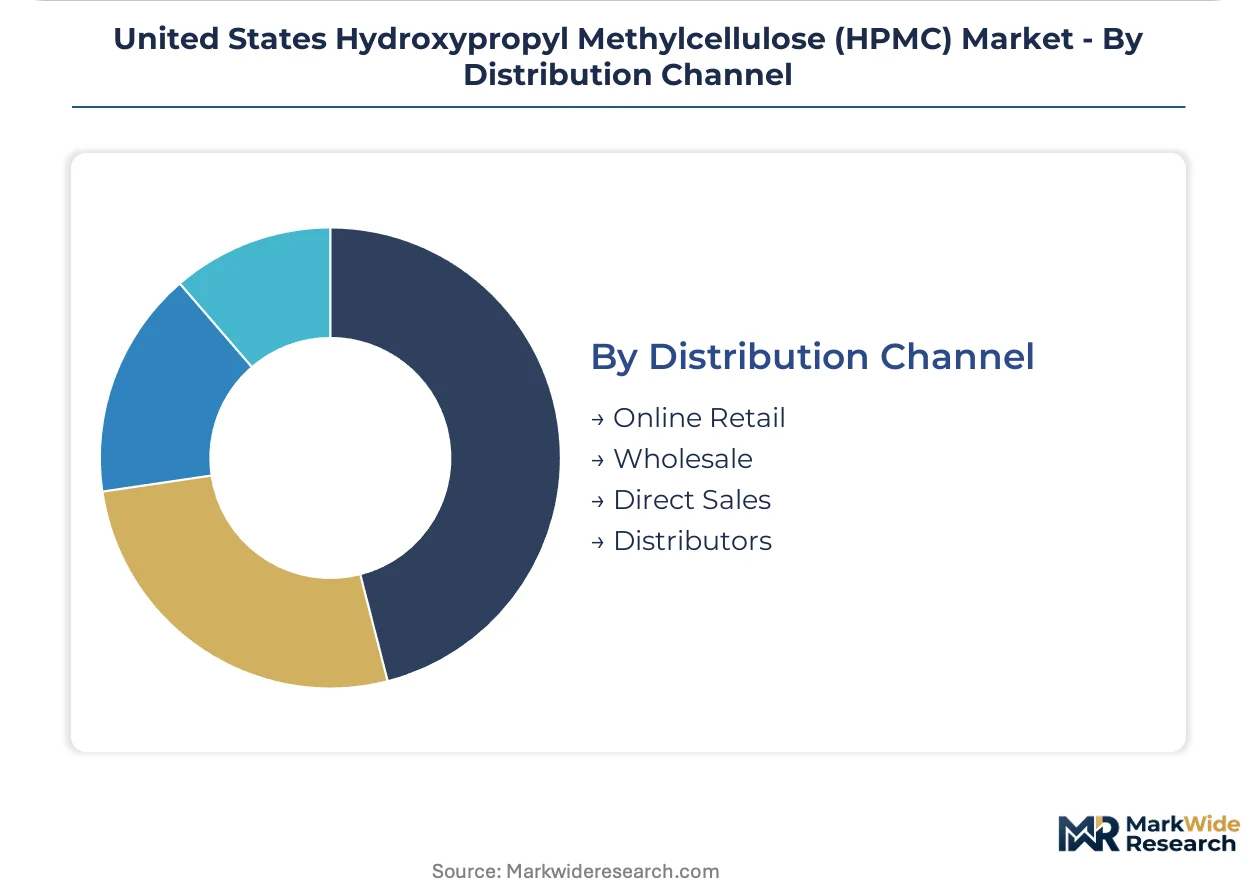
Distribution Channel:
Customer type segmentation separates technical service-intensive pharmaceutical accounts from price-sensitive construction material distributors.
- Direct Sales:Large oral dosage form manufacturers demand technical service integration for formulation development that regional distributors cannot provide. Ashland Global Holdings leverages integrated supply chain control to sustain direct relationships.
- Distributors:Industrial-grade construction sector offtake flows through regional chemical distributors serving cement and adhesive formulators.
- Wholesale:Volume aggregation for mid-tier food and cosmetic processors without direct supplier qualification resources.
- Online Retail:Small-batch cosmetic and research-grade procurement through specialty chemical platforms.
Direct Sales captures the highest value per kilogram, while Distributors handle the greatest tonnage throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New Jersey-Pennsylvania pharmaceutical corridor anchors domestic HPMC demand through concentrated contract manufacturing and API production clusters.
Northeast Corridor
Oral solid dosage manufacturers and excipient formulators drive pharmaceutical-grade consumption across New Jersey and Pennsylvania. FDA Drug Master File registrations and USP-NF monograph compliance create supplier qualification barriers that concentrate purchasing power among established registrants. Contract manufacturing organizations near Princeton and Philadelphia demand documentation exceeding baseline regulatory requirements.
Texas Gulf Coast
Etherification reactor sites in Texas and Louisiana serve industrial-grade construction sector offtake for cement hydration control and tile adhesive applications. OSHA Process Safety Management and EPA Clean Air Act requirements on reactor emissions shape production economics at Beaumont and Lake Charles manufacturing facilities. Regional distribution networks supply commercial flooring and exterior insulation finish systems across the South Central states.
California
Food-grade HPMC adoption accelerates among plant-based protein processors seeking thermal gelation properties for meat analog texture mimicry. California Proposition 65 disclosure obligations and emerging PFAS contamination scrutiny press suppliers to certify cellulose feedstock sourcing and validate absence of fluorinated process aids. Clean-label validation creates first-mover advantage for qualified supply chains serving Los Angeles and Bay Area food technology firms.
Midwest Manufacturing Belt
Industrial-grade volumes flow through regional chemical distributors serving cement and adhesive formulators across Illinois, Ohio, and Michigan. Construction sector green building certifications recalibrate specification thresholds for commercial flooring applications. Dow Chemical Company anchors regional distribution density through established supply relationships with building materials manufacturers.
United States Hydroxypropyl Methylcellulose (HPMC) Market Key Industry Players
Global majors compete with regional champions across excipient qualification depth and construction sector scale. The supplier base tiers between pharmaceutical-grade registrants with Drug Master File portfolios and industrial-grade volume players competing on regional distribution density. Three archetypes dominate: integrated cellulose ether producers controlling raw linter supply, formulation science specialists delivering co-processed excipient systems, and commodity-scale chemical manufacturers serving construction adhesives. Capacity expansion at qualified etherification reactor sites and strategic partnerships for co-processed excipient development represent the dominant competitive vectors.
Among integrated supply chain operators, Ashland Global Holdings Inc. exemplifies backward integration from raw cotton linter through finished excipient production. Dow Chemical Company occupies a position as the scale-driven anchor for industrial-grade construction applications. Colorcon Inc. sits within the formulation science specialist tier, representing differentiation through co-processed excipient systems rather than commodity polymer supply.
| Leading Market Players |
|---|
| Colorcon Inc. |
| Sigma-Aldrich (Merck KGaA) |
| Ashland Global Holdings Inc. |
| Bright Pharmacaps Inc. |
| Capsugel, Inc. |
| Dow Chemical Company |
| CP Kelco U.S., Inc. |
| Hercules-Tianpu |
| DuPont de Nemours, Inc. |
| Others |
Cost & Logistics Intelligence
Backward integration from raw cotton linter through finished excipient production anchors both supply security and margin control for pharmaceutical-grade HPMC manufacturers. This integration choice insulates Ashland Global Holdings from propylene oxide feedstock volatility while concentrating pricing power among Drug Master File registrants serving FDA-regulated tablet coating applications.
Pricing Analysis
Propylene oxide and methyl chloride etherification chemistry drives input-cost pass-through into finished HPMC pricing, with petrochemical volatility compressing margin predictability for non-integrated producers. Three-tier pricing structure across pharmaceutical, industrial, and food-grade levels separates FDA-certified excipients from construction adhesives and clean-label protein binders. Pricing pressure stems from ethyl cellulose substitution in controlled-release tablets, where comparable barrier properties undercut HPMC film-forming premiums. Construction sector buyers exhibit highest price sensitivity, while pharmaceutical formulators prioritize batch-to-batch consistency over per-kilogram cost.
Supply Chain Analysis
Specialized chemical process operators face workforce-availability constraints at etherification reactor sites in Texas and Louisiana, where OSHA Process Safety Management certification requirements limit qualified labor pools. Domestic manufacturing draws from cotton linter feedstocks sourced through southern agricultural belts, with propylene oxide supply tethered to Gulf Coast petrochemical infrastructure. Single-source vulnerability concentrates in Northeast pharmaceutical corridor offtake, where New Jersey and Pennsylvania contract manufacturing organizations depend on qualified excipient registrants. Distribution runs through direct-to-formulator channels for pharmaceutical grades and regional chemical distributors for industrial construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's quality-by-design initiatives compound regulatory barriers around excipient master files, transforming compliance depth into a demand driver that favors incumbent registrants with established Type IV submissions.
For Market Incumbents: Acquire co-processed excipient formulation capabilities to defend against ethyl cellulose substitution pressure in controlled-release applications. Expand etherification reactor capacity at Texas-Louisiana sites where EPA Clean Air Act compliance investments already create barrier-protected production. Deepen technical service integration with New Jersey-based contract manufacturing organizations to lock in direct distribution relationships. For New Entrants and Emerging Players: Food technology distributors represent the most accessible channel partner type for penetrating California's plant-based protein processing cluster. Target thermal gelation applications in meat analog formulations where FSSAI-aligned certification requirements remain less stringent than pharmaceutical Drug Master File barriers. Pursue clean-label validation partnerships with Los Angeles and Bay Area food technology firms seeking PFAS-free cellulose sourcing. For Investors and Strategic Acquirers: Consolidation pressure builds where GMP compliance talent scarcity and extended FDA review timelines prevent new excipient registrants from achieving revenue recognition. Pharmaceutical-grade HPMC manufacturers with captive cotton linter supply and established Northeast corridor relationships offer strongest five-to-ten-year viability within cellulose ether portfolios. Monitor ethyl cellulose pricing spreads as the inflection indicator for HPMC margin compression in controlled-release tablet segments.| Strategic Initiative | Industry Significance |
|---|---|
| Drug Master File Registration | FDA Type IV excipient submissions create multi-year qualification barriers protecting incumbent revenue streams. |
| Backward Integration into Cotton Linter | Captive raw material supply insulates Ashland Global Holdings from agricultural commodity volatility. |
| Co-Processed Excipient Development | Colorcon's formulation science differentiation commands premium pricing beyond commodity polymer supply. |
| Texas-Louisiana Capacity Expansion | Existing OSHA and EPA compliance investments protect qualified operators from new entrant competition. |
| California Proposition 65 Certification | PFAS-free supply chain validation creates first-mover advantage among Los Angeles food technology firms. |
Research Approach
Direct dialogue with pharmaceutical procurement directors, construction materials formulators, food technology R&D leads, and excipient regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from FDA Drug Master File databases, USP-NF monograph standards, SEC 10-K filings of listed chemical manufacturers, and EPA Clean Air Act enforcement records. Bottom-up demand modeling across tablet coating, cement hydration, and protein gelation applications triangulated against top-down petrochemical feedstock flow analysis.
Segment-level value and volume trajectories emerged from simultaneous modeling of pharmaceutical grade tier penetration, industrial construction cycle timing, and food-grade clean-label adoption curves. CAGRs derived from substitution ratio upgrade rates in oral solid dosage formulations and thermal gelation specification expansion in plant-based meat processing. Propylene oxide price elasticity and FDA review period distributions served as industry-specific forecast inputs.
Revisions become necessary when FDA excipient guidance shifts, ethyl cellulose functional equivalence claims achieve regulatory recognition, or PFAS contamination scrutiny expands beyond California disclosure obligations. Material deviation in these named triggers warrants pause and re-evaluation of demand assumptions across the projection horizon.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
US Non-Commercial Acrylic Paints Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
Acrylic Pad Market