
 Global Zinc Acetylacetonate Market | 2026-2036
Global Zinc Acetylacetonate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zinc Acetylacetonate Market Foresight
The capital-intensity divergence between integrated acetylacetonate producers and merchant chemical specialists is unwinding as purity thresholds rise. Lorad Chemical Corporation leverages captive synthesis capabilities to sustain pharmaceutical-grade output. Multi-tech (Tianjin) Specialty Chemicals anchors regional supply networks through backward integration into ligand precursors. Nihon Kagaku Sangyo Co., Ltd. differentiates via JIS-standard process discipline for electronics-grade material.
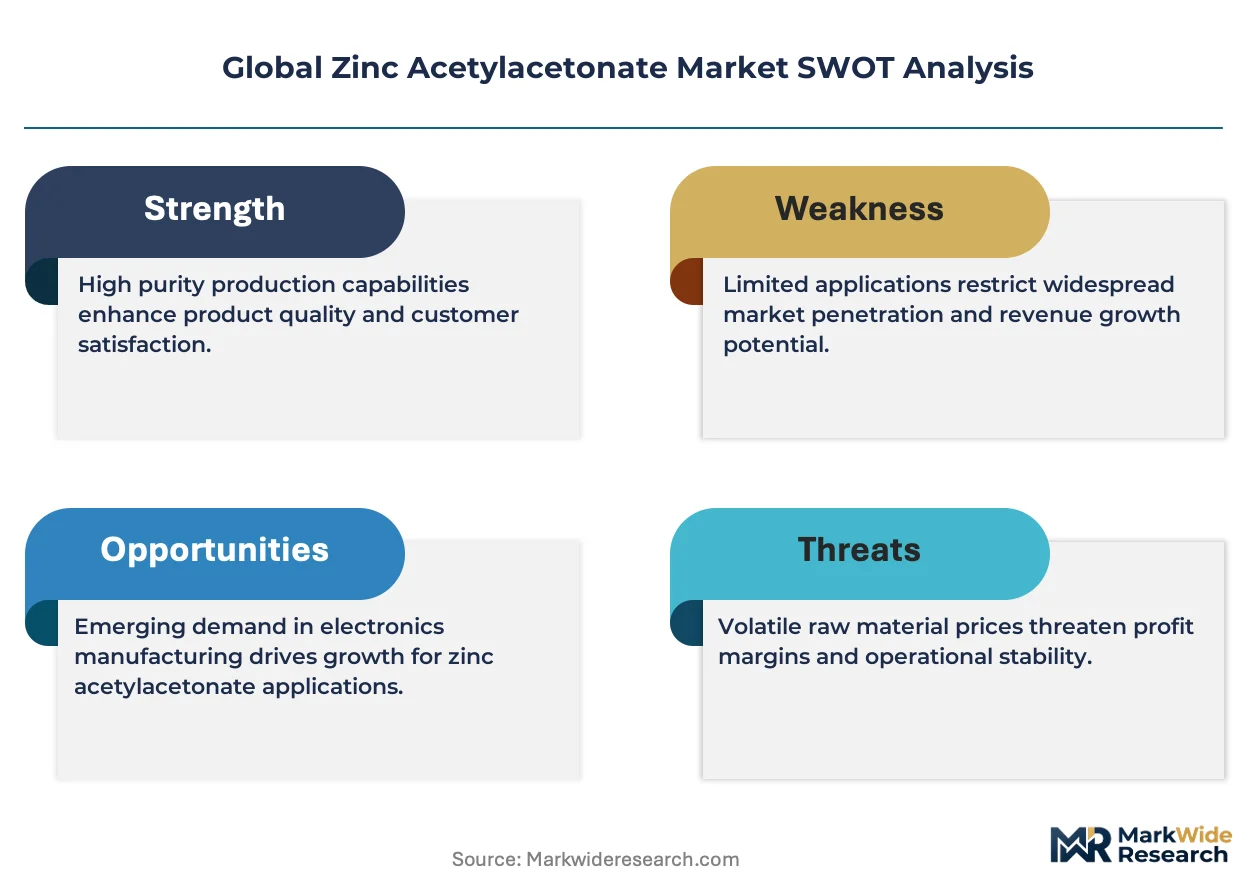
Zinc acetylacetonate, a zinc(II) coordination compound with two acetylacetonate ligands, functions primarily as a cross-linking catalyst and polymerization activator in industrial resin systems. The monohydrate form dominates volume flows into coatings and pigment manufacturing, where moisture-tolerant handling offsets marginal purity premiums. Electronics manufacturing applications represent the fastest-expanding demand pool, driven by high-purity specifications for thin-film deposition precursors. Polymer additives remain the most mature segment, with margin compression pushing producers toward specialized zinc complex formulations.
REACH registration requirements in the European Union, EPA chemical data reporting in the United States, and GB standards enforcement under China's SAMR collectively elevate compliance costs for non-integrated suppliers. ECHA substance evaluation protocols specifically scrutinize metal-organic compound environmental fate, redirecting R&D investment toward closed-loop synthesis methods. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and qualification timelines.
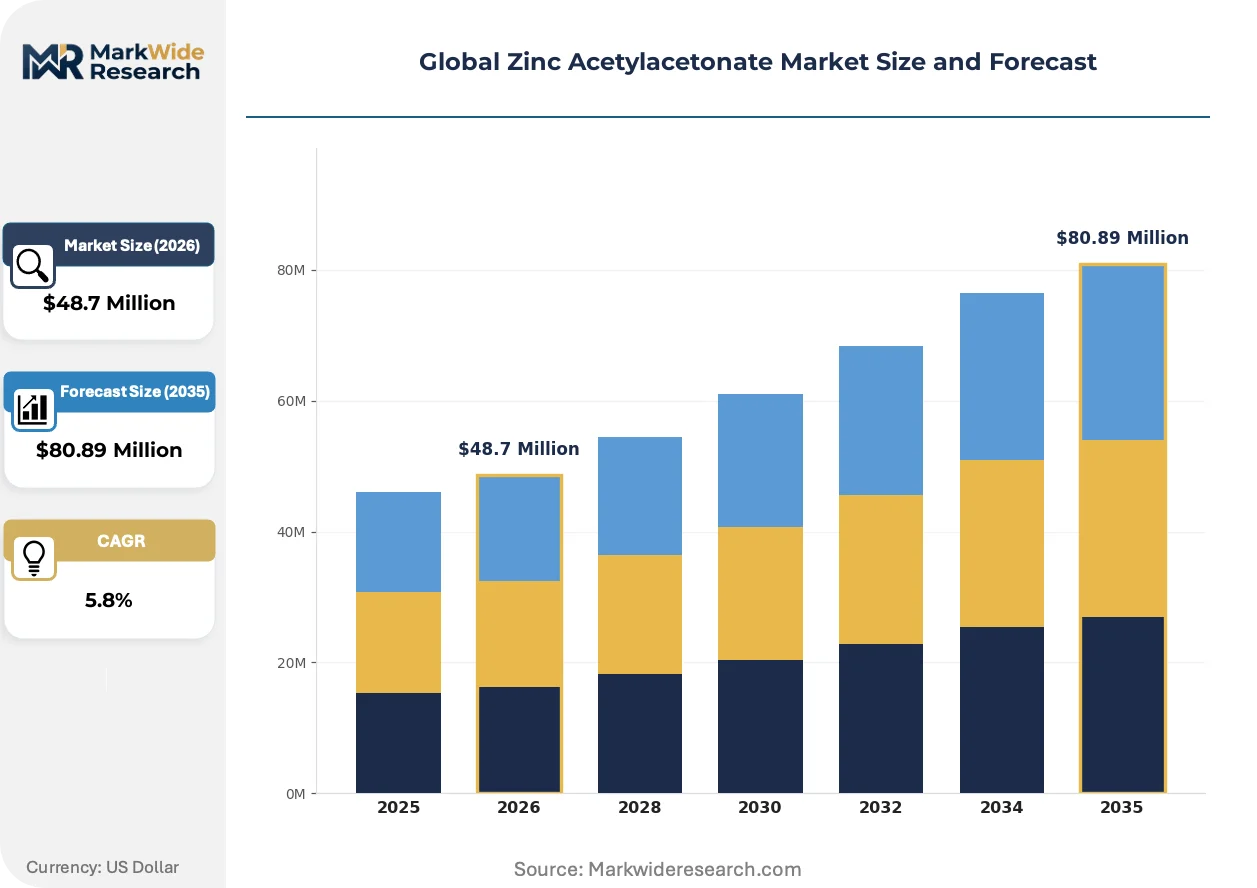
Market Dynamics
Purity thresholds for metal-organic compounds are hardening across jurisdictions, forcing acetylacetonate producers to retool synthesis infrastructure or exit pharmaceutical and electronics grades entirely.
Growth Catalysts
- REACH substance evaluation protocols:ECHA scrutiny of metal-organic environmental fate is redirecting R&D investment toward closed-loop synthesis methods, creating first-mover advantages for compliant suppliers.
- Thin-film deposition precursors:Electronics manufacturers are qualifying high-purity zinc acetylacetonate for atomic layer deposition processes in semiconductor fabrication.
- China's eastern manufacturing corridor:Acetylacetonate derivative output from Jiangsu and Zhejiang provinces feeds domestic catalyst and electronics sectors with minimal logistics friction.
Market Restraints
- Acetylacetone feedstock volatility:diketone precursor prices fluctuate with acetone and ethyl acetate commodity cycles, compressing margin visibility for non-integrated formulators.
- Merchant supplier concentration:Specialty chemical specialists lacking captive ligand synthesis face qualification barriers as OEMs consolidate approved vendor lists.
- Monohydrate-anhydrous substitution:Moisture-tolerant coatings applications accept lower-cost monohydrate grades, limiting premium pricing power for anhydrous variants.
Strategic Opportunities
- India's specialty chemicals expansion:PLI scheme incentives for advanced materials manufacturing are drawing acetylacetonate investment toward Gujarat and Maharashtra industrial zones.
- SAMR GB standards enforcement:China's tightened metal-organic purity mandates are disqualifying informal producers, opening volume share for certified importers and domestic upgraders.
- Closed-loop solvent recovery:Converging pressure from ECHA environmental fate rules and MEE dual carbon goals is creating technical service revenue streams for engineering partners.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA validation protocols for metal-organic excipients extend qualification cycles beyond standard chemical registration.
- Cross-jurisdictional formulation drift:Diverging REACH, EPA, and SAMR substance restrictions force parallel product line maintenance, inflating inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zinc Acetylacetonate Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $80.89 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monohydrate, Anhydrous, Dihydrate, Zinc Complex, High Purity Application: Catalysts, Coatings, Pigments, Polymer Additives, Electronics Manufacturing Industry End Use: Pharmaceuticals, Agriculture Chemicals, Paints & Inks, Electronic Components, Textile Processing Packaging Type: Drums, Bags, Bulk Containers, Bottles, Foil Packs |
| Companies Covered | Lorad Chemical Corporation, Multi-tech (Tianjin) Specialty Chemicals, Nanjing Lepuz Chemical, Liaocheng JunHang Biotech, Nihon Kagaku Sangyo Co., Ltd., Huzhou Xinaote Pharmaceutical & Chemical, SACHEM, Inc., Amspec Chemical Corporation, Nanjing Lanya Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zinc Acetylacetonate Market Shifts & Advancements
Process intensification and regulatory harmonization pressures are reshaping how acetylacetonate producers configure synthesis assets and qualify customer applications.
Continuous flow reactor technology is fragmenting traditional batch-process economics in acetylacetonate manufacturing. Pharmaceutical and electronics-grade buyers in Germany and Japan are auditing suppliers for flow-chemistry capability during vendor qualification. This technology compression is enabling integrated producers to capture specification-premium tiers previously held by dedicated fine-chemical houses.
RoHS recast directives in the European Union are tightening heavy-metal thresholds in polymer additives containing zinc compounds. Coating formulators serving automotive OEMs must document acetylacetonate provenance and impurity profiles through full supply chains. Electronics-grade material from Japanese suppliers with JIS-standard process discipline is capturing displaced volume from non-compliant European merchant sources.
Specification-driven procurement is compressing supplier switching cycles in thin-film deposition markets. Semiconductor equipment manufacturers in South Korea and Taiwan are consolidating precursor purchasing through qualified chemical management partnerships rather than spot transactions. This channel consolidation is most visible in the logic and memory fabrication clusters around Hsinchu and Pyeongtaek, where dual-source requirements still favor incumbents with proven track records.
Global Zinc Acetylacetonate Market Segmentation
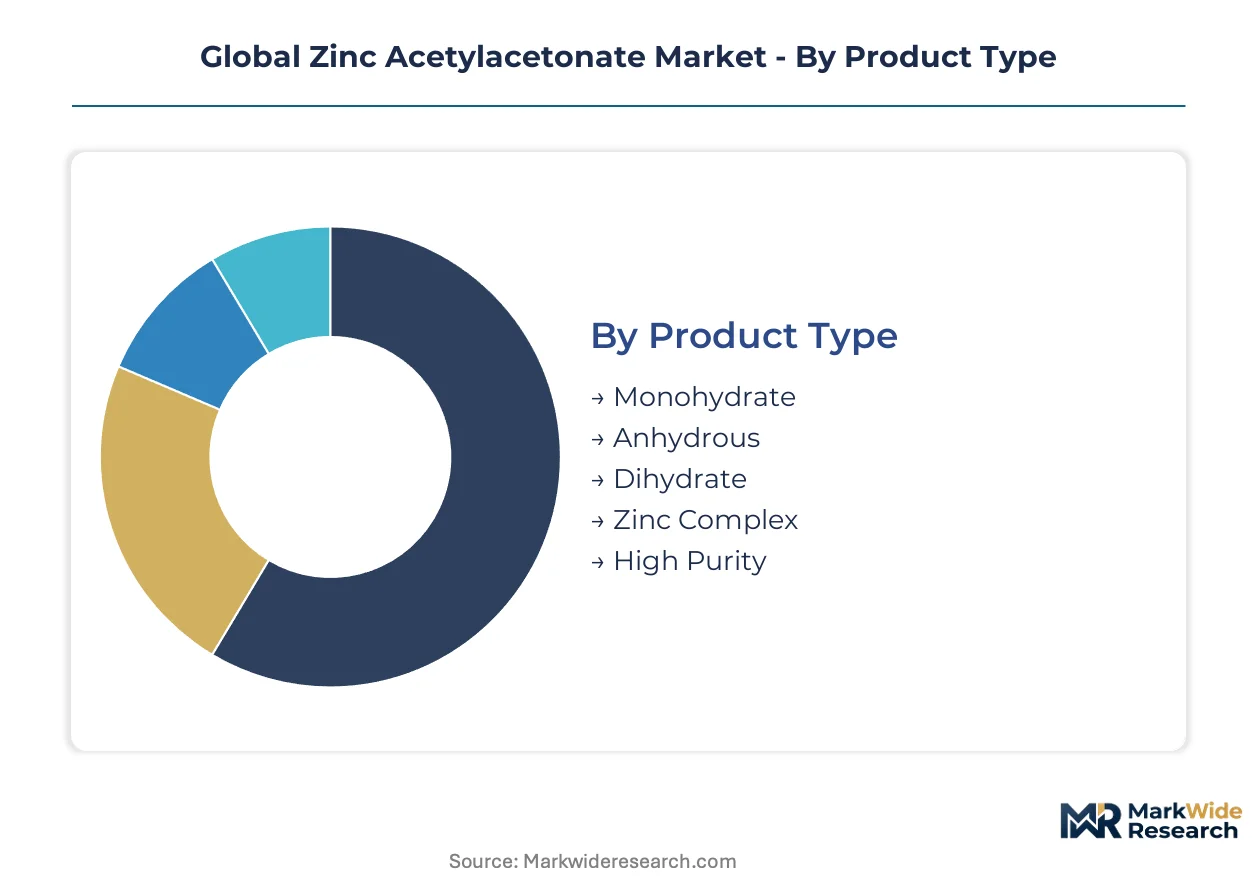
Specification divergence across zinc acetylacetonate grades creates distinct commercial battlegrounds where moisture tolerance, purity thresholds, and regulatory compliance reshape procurement patterns. Segmentation strategy determines whether producers compete on volume throughput or qualification premiums.
Product Type:
Substitution pressure intensifies where lower-purity grades satisfy functional requirements without triggering reformulation costs.
- Monohydrate:The zinc(II) coordination compound retains one water molecule per formula unit, delivering cost-efficient cross-linking catalysis. Coatings manufacturers in China's Jiangsu province specify monohydrate for moisture-tolerant resin systems where marginal purity gains do not justify price premiums.
- Anhydrous:Water-free zinc acetylacetonate meets electronics-grade specifications for atomic layer deposition precursors. Semiconductor fabrication clusters in Hsinchu and Pyeongtaek qualify anhydrous material from Japanese suppliers with JIS-standard process discipline.
- Dihydrate:Two water molecules per formula unit serve niche pharmaceutical applications where controlled hydration stability matters.
- Zinc Complex:Modified ligand environments target specialized polymerization activator functions in custom resin formulations.
- High Purity:Sub-ppm metal contamination levels satisfy thin-film deposition requirements for advanced logic fabrication.
Monohydrate retains volume leadership; high purity holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity catalyst demand from qualification-intensive electronics precursors.
- Catalysts:Zinc acetylacetonate accelerates cross-linking reactions in industrial resin systems. Polymer producers in Germany's Ruhr industrial region source catalyst-grade material through qualified chemical management partnerships rather than spot markets.
- Coatings:Automotive OEMs in Stuttgart and Wolfsburg mandate REACH-compliant acetylacetonate provenance documentation through full supply chains.
- Pigments:Metal-organic coordination compounds enhance color stability in high-performance ceramic pigments.
- Polymer Additives:RoHS recast directives tighten heavy-metal thresholds, forcing coating formulators to validate zinc compound sourcing.
- Electronics Manufacturing:Atomic layer deposition processes in South Korean fabrication plants consume high-purity precursors under dual-source supply agreements.
Catalysts dominate tonnage flows; electronics manufacturing generates the highest value per kilogram.
Industry End Use:
Customer type fragmentation separates price-sensitive agricultural formulators from validation-extended pharmaceutical buyers.
- Pharmaceuticals:FDA and EMA validation protocols for metal-organic excipients extend qualification cycles beyond standard chemical registration timelines.
- Agriculture Chemicals:Zinc complex derivatives function as trace nutrient carriers in controlled-release fertilizer systems.
- Paints & Inks:REACH substance evaluation protocols scrutinize environmental fate, redirecting procurement toward closed-loop synthesis suppliers.
- Electronic Components:Thin-film deposition precursors for semiconductor fabrication require sub-ppm contamination specifications.
- Textile Processing:Cross-linking catalysts stabilize synthetic fiber finishes against thermal degradation.
Paints and inks anchor volume demand; electronic components command specification premiums.
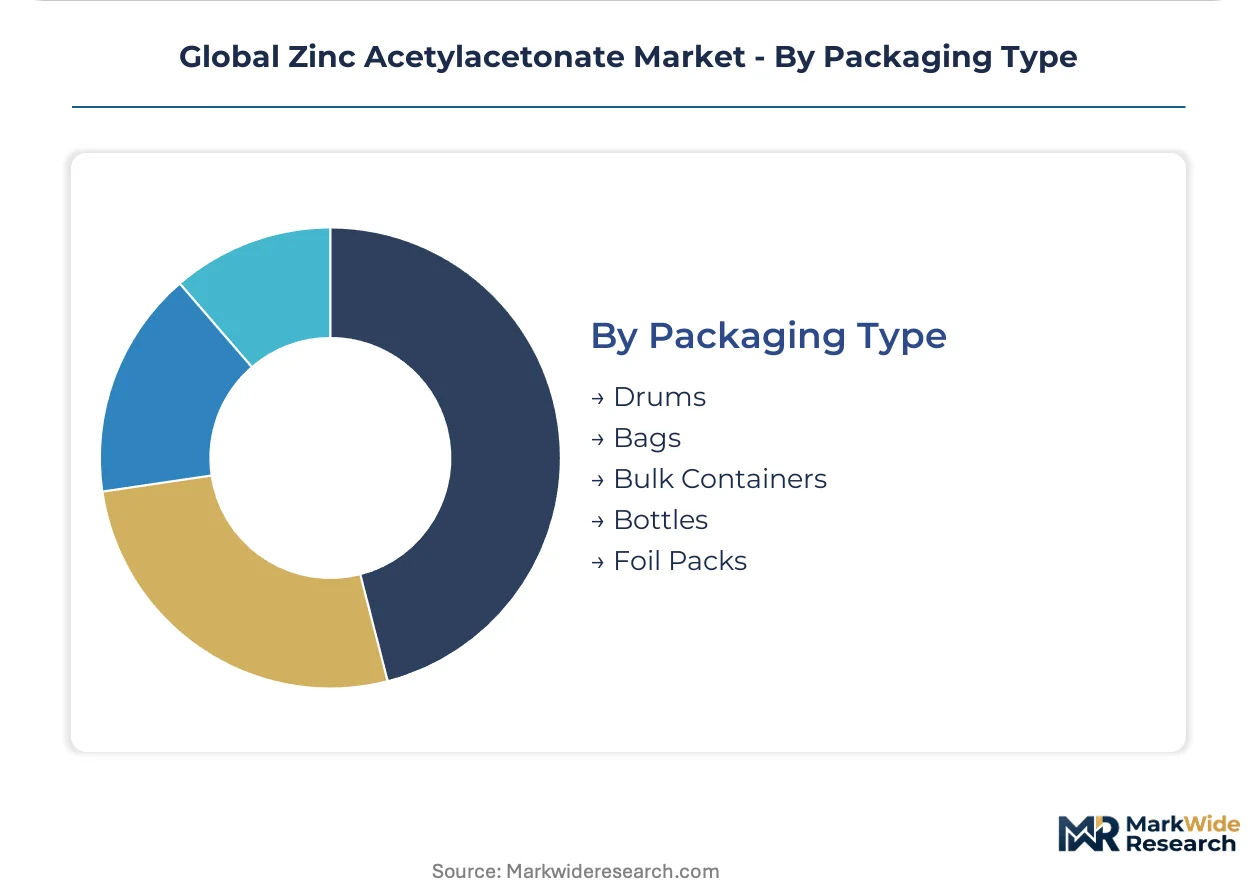
Packaging Type:
Supply concentration in drum and bulk formats reflects logistics optimization for industrial-scale consumption patterns.
- Drums:Standard 200-liter steel containers serve mid-volume coatings and catalyst customers with established handling infrastructure.
- Bags:Multi-layer polymer sacks protect moisture-sensitive grades during regional distribution.
- Bulk Containers:Intermediate bulk containers reduce per-kilogram handling costs for integrated polymer producers with captive consumption.
- Bottles:Laboratory-scale packaging supports pharmaceutical and electronics R&D qualification workflows.
- Foil Packs:Hermetic sealing preserves anhydrous specifications for air-sensitive high-purity grades.
Drums and bulk containers split industrial volume; foil packs capture the highest packaging-value ratio.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German electronics-grade supply corridors while Chinese bulk producers compete on throughput scale. REACH compliance costs in the European Union widen the premium gap between qualified and merchant suppliers. Regional divergence in acetylacetonate purity mandates is fragmenting procurement strategies across major consumption centers.
China
Jiangsu and Zhejiang provinces generate the majority of global acetylacetonate derivative volume for domestic catalyst and electronics sectors. SAMR enforcement of tightened GB standards for metal-organic purity is disqualifying informal producers and consolidating share among certified domestic upgraders. The Yangtze River Delta manufacturing corridor feeds thin-film deposition demand from semiconductor fabrication clusters in Shanghai and Suzhou.
Japan
Electronics-grade material from JIS-standard process discipline captures displaced volume from non-compliant European merchant sources. METI industrial policy supports advanced materials R&D for atomic layer deposition precursors in the semiconductor supply chain. The Kanto region around Tokyo anchors qualification workflows for high-purity metal-organic compounds serving South Korean and Taiwanese chip fabricators.
Germany
Automotive OEMs in Stuttgart and Wolfsburg mandate REACH-compliant acetylacetonate provenance documentation through full supply chains for polymer additive applications. ECHA substance evaluation protocols scrutinize environmental fate of metal-organic compounds, redirecting procurement toward closed-loop synthesis suppliers. The Ruhr industrial region hosts polymer producers sourcing catalyst-grade material through qualified chemical management partnerships.
United States
EPA chemical data reporting requirements elevate compliance costs for non-integrated acetylacetonate suppliers serving pharmaceutical and coatings markets. FDA validation protocols for metal-organic excipients extend qualification cycles beyond standard chemical registration timelines. The Gulf Coast petrochemical corridor provides diketone feedstock integration opportunities for domestic formulators.
South Korea
Semiconductor equipment manufacturers in Pyeongtaek and the Seoul Capital Area consolidate precursor purchasing through qualified chemical management partnerships rather than spot transactions. MFDS pharmaceutical-grade certification requirements create entry barriers for non-qualified metal-organic suppliers. Logic and memory fabrication clusters maintain dual-source supply agreements favoring incumbents with proven track records in high-purity material.
Global Zinc Acetylacetonate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated producers commanding specification premiums while merchant specialists face margin compression. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive ligand synthesis, regional specialists with backward integration into acetylacetonate precursors, and non-integrated formulators dependent on spot feedstock markets. Dominant competitive moves include capacity expansion in China's eastern manufacturing corridor and strategic partnerships for closed-loop solvent recovery systems.
Within the integrated producer tier, Lorad Chemical Corporation and Nihon Kagaku Sangyo Co., Ltd. exemplify archetypes sustaining pharmaceutical-grade and electronics-grade output respectively. Multi-tech (Tianjin) Specialty Chemicals occupies a position among regional specialists leveraging proximity to Jiangsu and Zhejiang derivative demand. These three anchors illustrate how geographic positioning and process discipline separate qualified suppliers from merchant competitors facing consolidation pressure.
| Leading Market Players |
|---|
| Lorad Chemical Corporation |
| Multi-tech (Tianjin) Specialty Chemicals |
| Nanjing Lepuz Chemical |
| Liaocheng JunHang Biotech |
| Nihon Kagaku Sangyo Co., Ltd. |
| Huzhou Xinaote Pharmaceutical & Chemical |
| SACHEM, Inc. |
| Amspec Chemical Corporation |
| Nanjing Lanya Chemical |
| Others |
Supply & Pricing Matrix
Capacity utilization in Jiangsu and Zhejiang acetylacetonate plants shapes both supply concentration and price floors for global buyers. High-purity electronics-grade output from Japanese JIS-standard producers commands substantial premiums over monohydrate catalyst grades sourced through China's eastern manufacturing corridor.
Pricing Analysis
The customization-premium spread between configured-to-order pharmaceutical-grade material and standard monohydrate catalyst shipments defines competitive positioning. Three-tier pricing structure across premium, standard, and economy levels separates sub-ppm electronics specifications from coatings-grade monohydrate and agricultural-complex variants. Cost compression in standard catalyst tiers stems from acetylacetone feedstock volatility and merchant supplier consolidation. Polymer additive buyers in Germany's Ruhr region exhibit highest price sensitivity through qualified chemical management partnerships, while semiconductor fabricators in Hsinchu maintain lowest sensitivity due to dual-source qualification requirements.
Supply Chain Analysis
China and Japan anchor global acetylacetonate derivative output, with Jiangsu province feeding domestic catalyst demand and Kanto-region suppliers qualifying high-purity precursors for South Korean chip fabricators. Synthesis draws from diketone precursors, metal oxide feedstocks, and solvent recovery systems. Single-source vulnerability concentrates in electronics-grade anhydrous material qualified for atomic layer deposition processes. Distribution runs through qualified chemical management partnerships for semiconductor precursors and spot-market procurement for coatings catalysts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification divergence across pharmaceutical, electronics, and coatings grades fragments procurement patterns into defendable niches. Thin-film deposition precursor qualification creates sticky supplier relationships resistant to pure price competition.
For Market Incumbents: Compound qualification advantages by deepening backward integration into acetylacetone synthesis and securing closed-loop solvent recovery partnerships. Electronics-grade incumbents face substitution pressure from emerging flow-chemistry specialists in Germany and Japan. Priority lever rests on JIS-standard process discipline investments that sustain premium positioning against REACH-compliant European merchant sources.
For New Entrants and Emerging Players: Technical service gaps in closed-loop synthesis audit support create entry points for engineering-focused challengers. India's Gujarat and Maharashtra industrial zones under PLI scheme incentives represent the most penetrable geography for pharmaceutical-grade investment. Go-to-market angle centers on SAMR GB standards compliance consulting bundled with certified material supply.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive ligand synthesis and long-term supply agreements to semiconductor fabricators. Five-to-ten year viability favors backward-integrated specialists over merchant formulators exposed to feedstock volatility. Acquisition target archetype: regional Chinese upgraders with SAMR certification and proximity to Yangtze River Delta demand. Signal to watch: ECHA substance evaluation protocol expansion into additional metal-organic compound categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylacetone | Captive diketone supply insulates margin visibility from acetone commodity cycles for integrated producers. |
| Flow-Chemistry Process Conversion | Continuous reactor technology enables pharmaceutical-grade output with lower batch-to-batch variability for German and Japanese buyers. |
| Closed-Loop Solvent Recovery Partnership | ECHA environmental fate compliance creates technical service revenue streams alongside material sales. |
| SAMR GB Standards Certification | China's tightened purity mandates disqualify informal producers, consolidating volume share among certified upgraders. |
| Dual-Source Supply Agreement with Semiconductor Fabricators | Logic and memory clusters in Pyeongtaek and Hsinchu favor incumbents with proven track records in high-purity precursors. |
Research Methodology
Operator-level perspectives from plant managers at acetylacetonate synthesis facilities, procurement leads at coatings and electronics OEMs, distribution channel partners in China's eastern corridor, and technical R&D directors at metal-organic compound specialists anchored the qualitative base. Primary interview insights combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from disclosed chemical producers, and SAMR regulatory bulletins. Bottom-up capacity and utilization estimates triangulated against top-down end-use demand segmentation.
Sensitivity analysis tested forecast robustness across feedstock price scenarios, regulatory enforcement intensity variations, and substitution elasticity assumptions. Segmentation dimensions modeled include product grade tier, end-use industry application, packaging format, and regional production hub classification. CAGRs derived from slope-log regression across the projection horizon, with semiconductor fabrication capacity expansion and automotive coatings formulation shifts as key industry-specific demand drivers.
Forecasts assume regulatory continuity in REACH substance evaluation protocols, SAMR GB standards enforcement, and EPA chemical data reporting requirements; material policy shifts would require re-modeling. Specific risks include ECHA environmental fate rule expansion, acetylacetone supply disruptions, and semiconductor capital expenditure cycle downturns. Recalibration cycles align with material shifts in precursor qualification timelines and purity mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
Polyoxin Market
Specialty Compounds
Nonene (Propylene Trimer) and Tetramer Market
Specialty Compounds
Silicone Potting Compounds Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
N-Propyl Propionate Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Lithopone Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market