
 Pharmaceutical Propellants Market | 2026-2036
Pharmaceutical Propellants Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Propellants Market Analytics
Aftermarket propellant recycling and reclamation services is reconfiguring margin distribution across the value chain. SRF leverages its fluorochemical expertise to anchor supply security for HFA-134a and HFA-227ea grades. Solvay competes through backward integration into hydrogen fluoride feedstocks, while Honeywell controls intellectual property around next-generation low-global-warming-potential propellant molecules.
Pharmaceutical propellants are liquefied or compressed gases that generate metered, atomized spray force within pressurized drug delivery devices, typically formulated at 99.5% minimum purity with moisture content below 10 ppm to prevent hydrolytic degradation of active pharmaceutical ingredients. Hydrofluoroalkane variants dominate current volume given their zero-ozone-depletion credentials, while compressed gas formulations such as CO2 and N2 are gaining fastest in nasal spray and nebulizer platforms where thermal stability requirements differ. Liquefied gas formulations still occupy the deepest margin pools due to the technical complexity of achieving consistent vapor pressure across temperature ranges.
The FDA enforces strict purity and toxicity thresholds through its inhalation drug guidance, while the EMA's F-Gas Regulation restricts high-global-warming-potential propellants and accelerates transition timelines for European manufacturers. China's NMPA implements GB standards for pharmaceutical excipients that increasingly reference ISO quality management protocols for imported propellant supplies. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation lock-in that limits cross-border product registration.
Market Dynamics
The pharmaceutical propellants sector is undergoing forced formulation turnover as Montreal Protocol-aligned phaseouts of chlorofluorocarbon inhalers compel manufacturers to rebuild supply chains around hydrofluoroalkane alternatives. This regulatory compression is redistributing margin pools toward fluorochemical specialists with backward-integrated hydrogen fluoride access.
Growth Catalysts
- F-Gas Regulation acceleration:The European framework tightens quotas on high-global-warming-potential propellants, forcing metered dose inhaler manufacturers toward HFA-134a and HFA-227ea grades with certified low-carbon footprints.
- Respiratory therapy volumes:Rising asthma and COPD prevalence in the United States, Germany, and China expands the installed base of pressurized drug delivery devices requiring pharmaceutical-grade propellant refills.
- Domestic production mandates:China's NMPA references ISO quality management protocols for imported excipients, incentivizing local fluorochemical capacity expansion to bypass cross-border certification delays.
Market Restraints
- Hydrogen fluoride feedstock volatility:Concentrated mining and processing of fluorspar in select geographies exposes propellant manufacturers to input cost swings and export restriction risks.
- Technical purity thresholds:The FDA's inhalation drug guidance mandates 99.5% minimum propellant purity with moisture below 10 ppm, requiring capital-intensive distillation infrastructure that excludes smaller chemical processors.
- Compressed gas substitution:Carbon dioxide and nitrogen formulations for nasal spray platforms threaten liquefied gas margins in segments where thermal stability requirements permit simpler chemistries.
Strategic Opportunities
- Aftermarket reclamation services:Propellant recycling infrastructure remains underdeveloped, creating first-mover advantages for service providers capable of certifying reclaimed HFA grades to pharmaceutical standards.
- Low-global-warming-potential molecules:Honeywell's intellectual property position in next-generation propellant chemistry offers licensing pathways as the EMA and EPA tighten climate-impact thresholds.
- India's CDSCO pathway:The country's respiratory device market remains propellant-undersupplied relative to patient volumes, creating import substitution openings for certified excipient manufacturers.
Industry Challenges
- Cross-jurisdictional formulation lock-in:Divergent FDA, EMA, and NMPA certification timelines force manufacturers to maintain parallel product variants, complicating inventory and registration strategies.
- Analytical chemistry talent scarcity:The specialized skill set for propellant purity testing and stability validation concentrates in legacy fluorochemical hubs, constraining quality control scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Propellants Market |
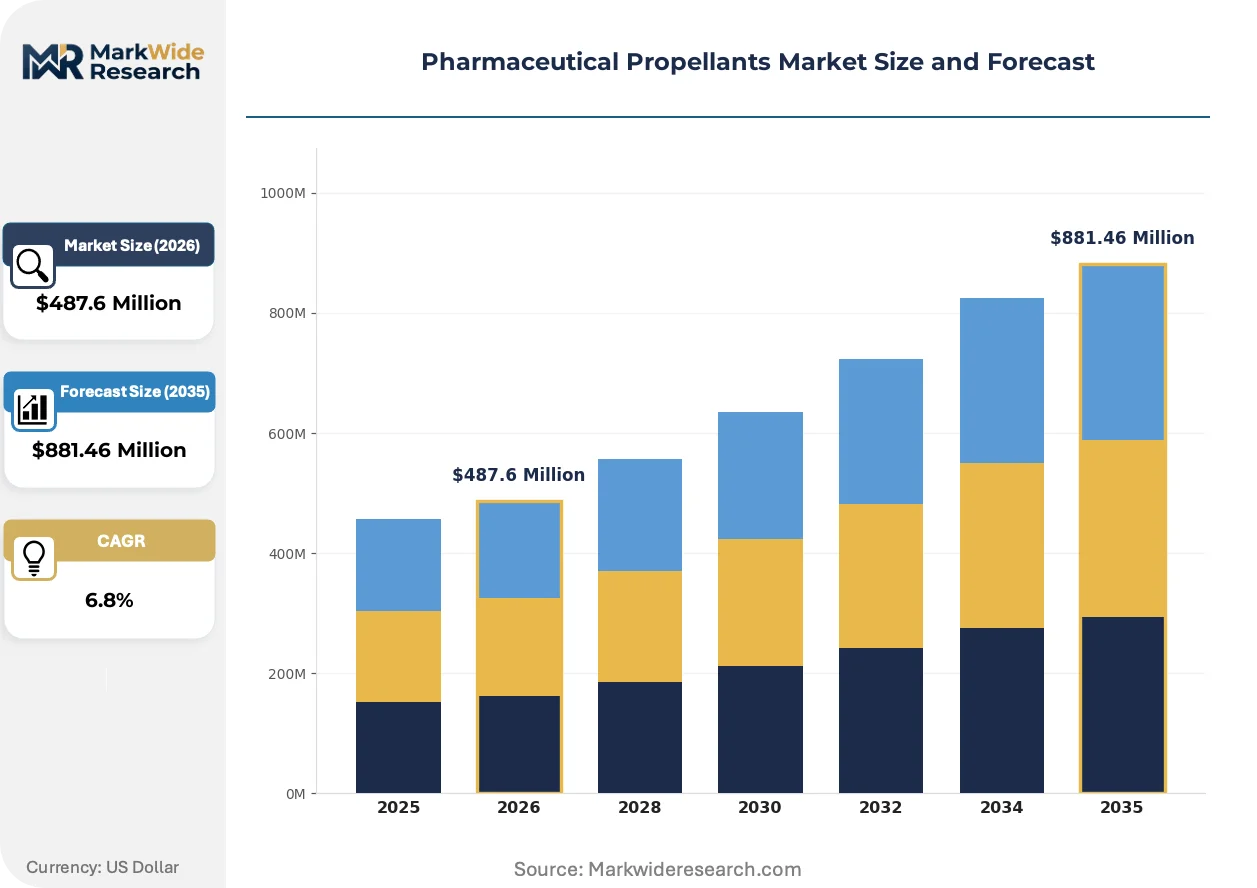
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HFA, CFC, CO2, N2 Application: Aerosol Inhalers, Metered Dose Inhalers, Nebulizers, Nasal Sprays Therapy Area: Respiratory Disorders, Allergy Treatment, Anesthesia, Pharmaceuticals Formulation: Liquefied Gas, Compressed Gas, Solvent-Based, Others |
| Companies Covered | SRF, Yara International, Solvay, AlzChem, DAIKIN Chemical, Orbia Advance Corporation (Fluor & Energy Materials), Akzo Nobel, Honeywell, The Linde Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Propellants Market Evolving Landscape
Formulation science and delivery device engineering are converging to redefine performance benchmarks for pressurized respiratory therapies. Three interconnected developments are compressing development cycles and rewiring competitive positioning.
Next-generation propellant chemistry is migrating from laboratory-scale synthesis toward commercial validation. Low-global-warming-potential molecules with thermal stability profiles matching HFA-134a are attracting development funding from metered dose inhaler manufacturers facing 2030 climate-compliance deadlines. This migration is compressing the window for incumbent hydrofluoroalkane suppliers to recover capital invested in legacy production trains.
The EMA's F-Gas Regulation and the EPA's Significant New Alternatives Policy are tightening in parallel, creating synchronized compliance pressure across transatlantic supply chains. European manufacturers must now document lifecycle carbon intensity for propellant procurement decisions, while US-based suppliers face parallel scrutiny under evolving SNAP listings. Inhaler device makers in Germany and the United States are responding by consolidating supplier audits and demanding certified chain-of-custody documentation.
Hospital procurement departments are consolidating propellant sourcing through single-source contracts with integrated chemical-pharmaceutical distributors. This channel compression displaces fragmented spot-market purchasing that previously characterized smaller respiratory therapy clinics. The shift is most visible in the United States, where group purchasing organizations now specify excipient certification grades in master agreements covering multiple hospital systems.
Pharmaceutical Propellants Market Segmentation
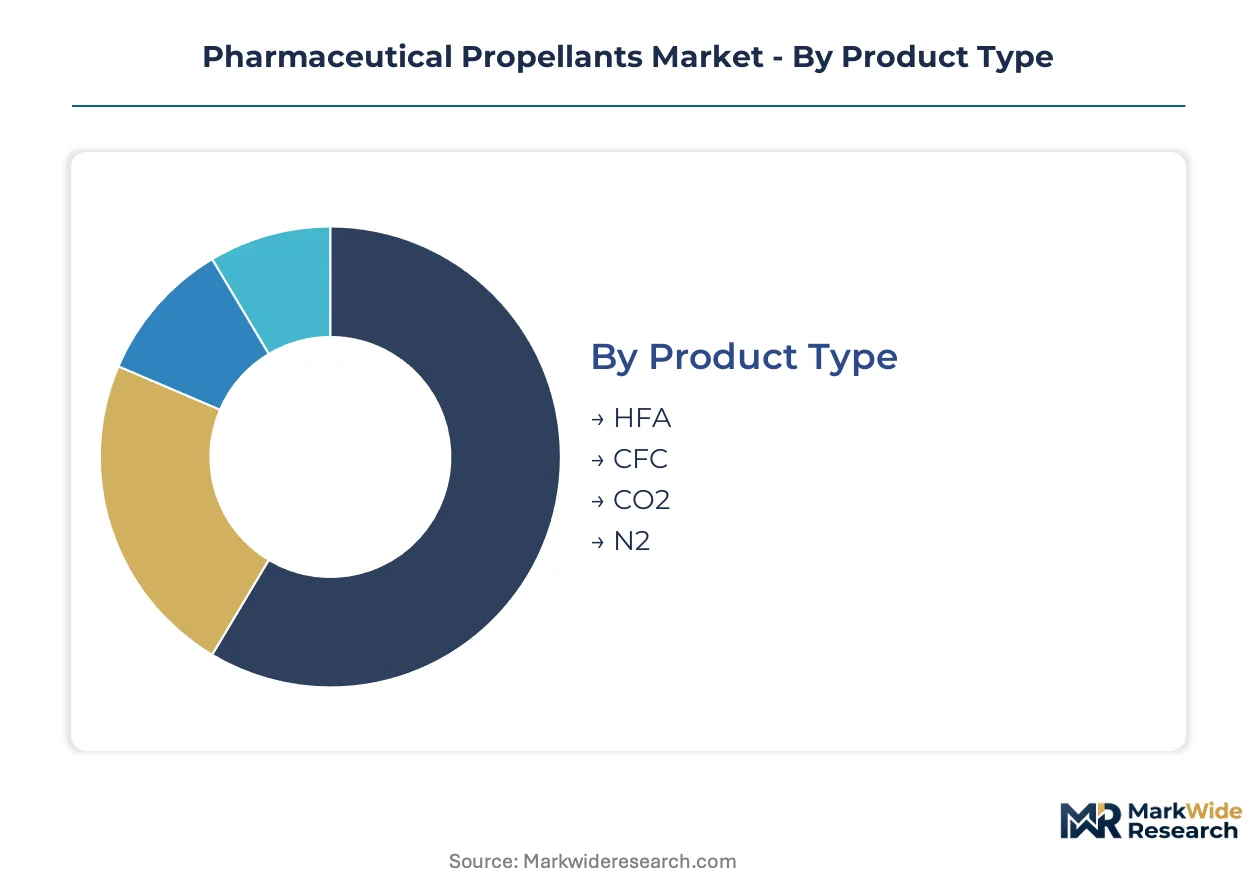
Propellant selection in pharmaceutical delivery devices hinges on regulatory compliance timelines, thermal stability requirements, and purity thresholds that vary sharply across respiratory and nasal platforms. Segmentation reveals how formulation chemistry and therapy area demands are fragmenting procurement strategies among metered dose inhaler manufacturers.
Product Type:
Mature hydrofluoroalkane grades dominate current procurement volumes while compressed gas alternatives emerge fastest in device categories with relaxed vapor pressure specifications.
- HFA:Hydrofluoroalkane variants HFA-134a and HFA-227ea constitute the primary replacement chemistry for phased-out chlorofluorocarbon propellants, with demand concentrating in United States and German metered dose inhaler production lines as FDA and EMA purity mandates tighten. Manufacturers prize these grades for zero-ozone-depletion credentials and consistent vapor pressure curves across clinical temperature ranges.
- CO2:Carbon dioxide propellant formulations are gaining fastest in nasal spray devices where thermal stability requirements permit simpler compressed gas mechanics rather than liquefied gas vapor pressure management. The segment climbs fastest in Chinese manufacturing hubs where NMPA excipient standards for non-resiratory delivery create regulatory headroom.
- CFC:Chlorofluorocarbon propellants persist only in limited grandfathered inhaler formulations under Montreal Protocol exemption timelines, with residual demand isolated to specific therapeutic categories awaiting full HFA transition.
- N2:Nitrogen propellant systems serve nebulizer and specialty aerosol platforms requiring inert gas displacement without liquefied gas thermal loading, finding niche adoption in anesthesia delivery devices.
HFA retains volume leadership; CO2 holds the steepest expansion curve.
Application:
Device engineering specifications create divergent propellant purity and pressure requirements across respiratory and nasal delivery platforms.
- Metered Dose Inhalers:MDI platforms command the most stringent propellant specifications, requiring 99.5% minimum purity with sub-10 ppm moisture content to prevent hydrolytic degradation of active pharmaceutical ingredients in asthma and COPD therapies.
- Aerosol Inhalers:Pressurized aerosol devices for bronchodilator delivery concentrate demand in United States manufacturing facilities where FDA inhalation drug guidance enforces batch-level certification protocols.
- Nebulizers:Compressor-driven nebulizer systems permit compressed gas propellant alternatives, with procurement shifting toward CO2 and N2 formulations in German hospital procurement contracts.
- Nasal Sprays:Intranasal delivery devices leverage simpler propellant chemistries where thermal stability requirements differ from deep lung deposition targets, expanding fastest in Chinese domestic pharmaceutical production.
Metered dose inhalers anchor revenue concentration; nasal sprays expand most quickly.
Therapy Area:
Clinical indication severity dictates propellant performance margins and regulatory scrutiny intensity across therapeutic categories.
- Respiratory Disorders:Asthma and COPD treatment platforms drive the bulk of hydrofluoroalkane propellant consumption, with patient volume growth in United States and China expanding the installed base of pressurized delivery devices.
- Allergy Treatment:Antihistamine and corticosteroid nasal spray formulations permit compressed gas propellant substitution, with demand clustering in seasonal allergy markets across German and Chinese distribution channels.
- Anesthesia:Surgical inhalation anesthetics require specialized propellant inertness profiles, with procurement concentrated in tertiary hospital systems maintaining captive pharmaceutical supply chains.
- Pharmaceuticals:General excipient-grade propellant applications span topical aerosols and veterinary delivery devices, serving fragmented demand across regional pharmaceutical packaging specialists.
Respiratory disorders command the deepest margin pools; allergy treatment permits the fastest formulation substitution.
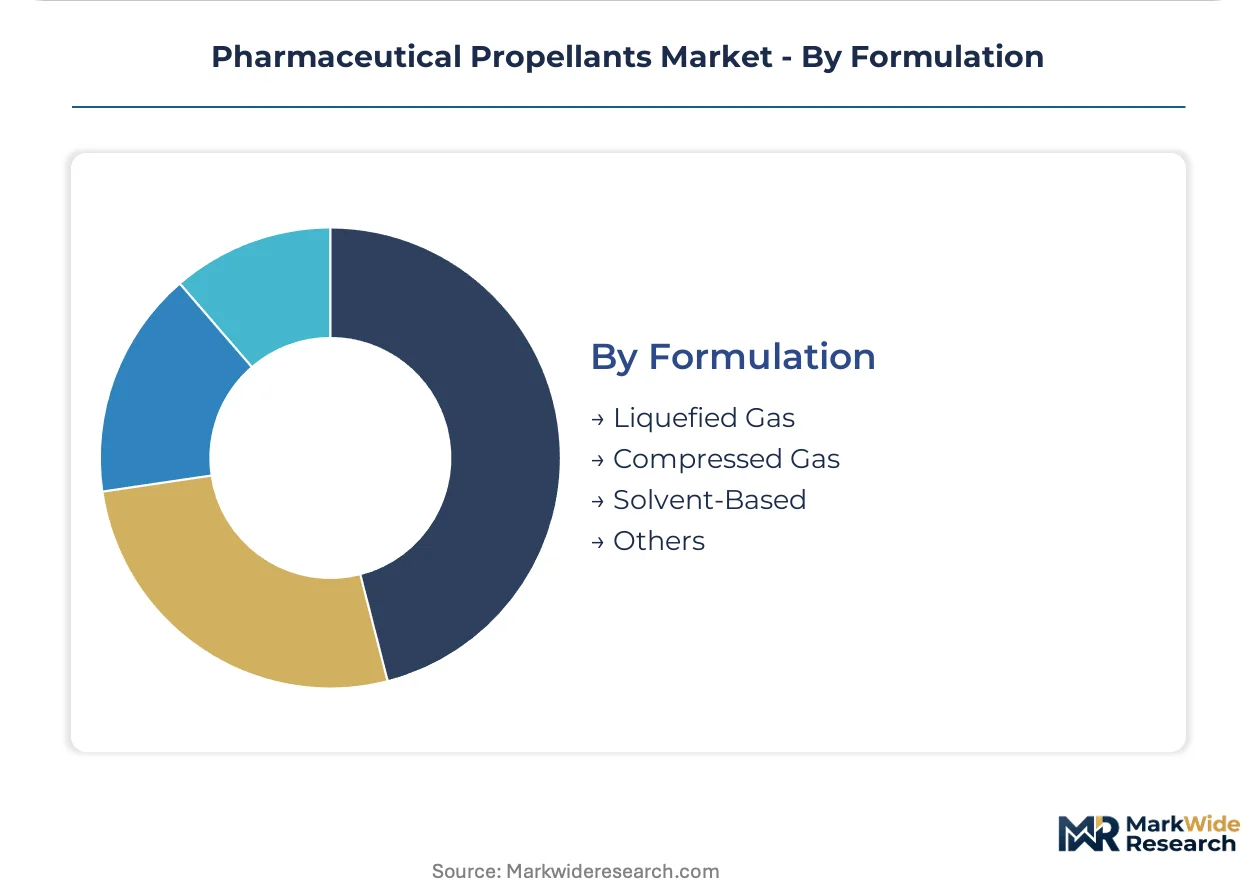
Formulation:
Physical state at dispensing pressure determines capital intensity and purity validation requirements across manufacturing infrastructure.
- Liquefied Gas:Liquefied gas formulations occupy the deepest margin pools due to technical complexity in achieving consistent vapor pressure across temperature ranges, with HFA-134a and HFA-227ea production requiring distillation infrastructure that excludes smaller chemical processors.
- Compressed Gas:Carbon dioxide and nitrogen compressed gas formulations threaten liquefied gas margins in segments where thermal stability requirements permit simpler chemistries, gaining fastest in nasal spray and nebulizer platforms.
- Solvent-Based:Co-solvent propellant systems for specialized drug solubility requirements serve niche inhalation therapies where active ingredient stability demands modified vapor pressure profiles.
- Others:Emerging propellant formulations including low-global-warming-potential molecules remain in pre-commercial validation phases, attracting development funding from device manufacturers facing climate-compliance deadlines.
Liquefied gas formulations retain manufacturing margin leadership; compressed gas alternatives gain share fastest in device categories with relaxed specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb premium pricing for certified HFA grades with minimal demand elasticity, while Chinese and Indian procurement departments enforce aggressive cost compression on standard propellant formulations.
United States
FDA inhalation drug guidance mandates 99.5% purity with sub-10 ppm moisture, forcing MDI manufacturers toward validated HFA-134a and HFA-227ea suppliers. The EPA's SNAP program tightens climate-compliance timelines for propellant chemistry transitions. North Carolina's Research Triangle anchors fluorochemical R&D clusters where Honeywell and specialized contractors validate next-generation low-global-warming-potential molecules.
Germany
EMA F-Gas Regulation quotas compress high-global-warming-potential propellant availability, redirecting pharmaceutical procurement toward certified low-carbon-footprint HFA grades. The EU Green Deal accelerates lifecycle carbon intensity documentation requirements across excipient supply chains. Bavaria's chemical manufacturing belt concentrates distillation infrastructure serving metered dose inhaler producers across the Rhine-Ruhr and Frankfurt corridors.
China
NMPA GB standards for pharmaceutical excipients increasingly reference ISO quality management protocols, incentivizing domestic fluorochemical capacity expansion. The country's dual carbon goals pressure provincial regulators to scrutinize propellant manufacturing emissions. Yangtze River Delta pharmaceutical clusters in Jiangsu and Zhejiang provinces scale HFA production lines to bypass cross-border certification delays for respiratory device exports.
India
CDSCO regulatory pathways for respiratory devices remain propellant-undersupplied relative to asthma and COPD patient volumes, creating import substitution openings. The PLI scheme for pharmaceuticals incentivizes domestic excipient manufacturing capacity. Gujarat's specialty chemical belt and Maharashtra's Mumbai-Pune industrial corridor attract fluorochemical investments targeting metered dose inhaler formulation gaps.
Japan
PMDA maintains stringent inhalation drug purity benchmarks aligned with FDA and EMA precedents, limiting propellant supplier qualification to established fluorochemical specialists. METI industrial policy supports domestic hydrogen fluoride feedstock security for pharmaceutical-grade HFA production. Osaka-Kobe chemical manufacturing clusters sustain captive propellant supply chains serving domestic MDI device makers.
Pharmaceutical Propellants Market Competitive Landscape
Backward-integrated fluorochemical specialists and diversified industrial gas suppliers split the market into distinct capability tiers. The vendor base concentrates around hydrogen fluoride access and pharmaceutical-grade distillation infrastructure. Three archetypes dominate: legacy fluorochemical majors with captive feedstock, industrial gas multinationals leveraging distribution scale, and regional chemical processors serving cost-sensitive generics markets. Competitive moves center on capacity expansion in low-carbon-footprint HFA grades and strategic partnerships with MDI device manufacturers seeking supply security.
Among legacy fluorochemical majors, SRF, Solvay, and Honeywell occupy positions reflecting distinct strategic postures. SRF exemplifies the backward-integrated specialist archetype, anchoring supply security through in-house fluorochemical expertise. Solvay represents the hydrogen-fluoride-feedstock-integrated model, while Honeywell sits within the intellectual-property-licensing tier for next-generation propellant chemistry. The Linde Group and Air Liquide equivalents among industrial gas suppliers compete through distribution density rather than molecular development.
| Leading Market Players |
|---|
| SRF |
| Yara International |
| Solvay |
| AlzChem |
| DAIKIN Chemical |
| Orbia Advance Corporation (Fluor & Energy Materials) |
| Akzo Nobel |
| Honeywell |
| The Linde Group |
| Others |
Value Network & Pricing Analysis
Hydrogen fluoride feedstock volatility determines both the premium spread for pharmaceutical-grade HFA grades and the geographic clustering of distillation infrastructure. Manufacturers with captive fluorspar processing in India and China command pricing power over spot-market dependent competitors in Europe and North America.
Pricing Analysis
Aftermarket reclamation service contracts now drive lifetime value for propellant suppliers, with three-tier pricing structure across pharmaceutical-certified, technical-grade, and reclaimed HFA tiers. Certification to FDA sub-10 ppm moisture standards separates premium from standard tiers, while volume scale discounts compress margins for generic MDI manufacturers. Pricing pressure stems from compressed gas substitution in nasal spray segments where NMPA standards permit CO2 alternatives. Hospital procurement departments in Germany show least price sensitivity; Indian CDSCO pathway applicants absorb greatest cost compression.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize supplier relationships with German and United States MDI manufacturers, straining working capital for mid-tier fluorochemical processors. Hydrogen fluoride feedstock draws from Chinese and Mexican fluorspar mining concentration, with HFA-134a and HFA-227ea distillation anchored in Bavaria, Jiangsu, and Gujarat chemical belts. Single-source vulnerability concentrates around Honeywell's intellectual property position for next-generation low-global-warming-potential molecules. Distribution runs through integrated chemical-pharmaceutical distributors consolidating hospital procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical propellants sector sits at a platform-economics inflection where MDI device interoperability with reusable canister systems threatens single-use propellant consumption models.
For Market Incumbents: Harden supply security through backward integration into hydrogen fluoride feedstocks before fluorspar export restrictions tighten. Lock in multi-year offtake agreements with German and United States MDI manufacturers facing synchronized EPA SNAP and EMA F-Gas compliance deadlines. Anchor certification investment in ISO-referenced NMPA pathways for Chinese market access. For New Entrants and Emerging Players: Pursue India's CDSCO regulatory pathway where propellant supply gaps relative to asthma and COPD patient volumes create import substitution openings. Target nasal spray CO2 formulation segments where NMPA excipient standards permit compressed gas alternatives to liquefied gas complexity. Lead with reclamation service capabilities certifying reclaimed HFA grades to pharmaceutical standards. For Investors and Strategic Acquirers: EMA F-Gas Regulation quota tightening reshapes the acquisition landscape toward low-global-warming-potential molecule licensing positions and certified low-carbon-footprint HFA production trains. Five-to-ten year viability favors backward-integrated fluorochemical specialists over distribution-scale industrial gas suppliers. Watch EPA SNAP listing updates for next-generation propellant chemistry validation milestones as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Fluoride | Captive fluorspar processing insulates margins from export restriction shocks in China and Mexico. |
| Low-GWP Molecule Licensing | Honeywell's intellectual property position offers royalty pathways as EMA and EPA climate deadlines synchronize. |
| Aftermarket Reclamation Infrastructure | First-mover certification of reclaimed HFA grades to FDA purity standards captures service revenue pools. |
| CDSCO Pathway Market Entry | India's propellant-undersupplied respiratory device market permits import substitution at compressed margins. |
| Single-Source Hospital Contracts | Group purchasing organization consolidation in the United States displaces fragmented spot-market purchasing. |
Research Methodology
Cross-validation between primary interviews with fluorochemical plant managers, MDI device procurement leads, regulatory affairs specialists, and hospital GPO contracts managers anchors the qualitative findings against secondary validation from FDA inhalation drug guidance filings, EMA F-Gas Regulation quota documentation, NMPA GB standard publications, and customs trade data on hydrogen fluoride feedstock flows. Bottom-up propellant volume modeling triangulates against top-down MDI device production estimates.
Calibration against historical CFC-to-HFA transition patterns and observed EMA quota compression effects informs the analytical framework across the analysis window. Segmentation dimensions span propellant chemistry grade, device platform specification, therapy area severity, and regional regulatory cluster. CAGRs derive from installed base expansion of pressurized delivery devices and formulation substitution elasticities. Forecast inputs incorporate fluorspar mining capacity utilization and MDI manufacturer inventory cycle data.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed fluorochemical ventures or accelerated EPA SNAP approvals for next-generation molecules would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Global Sugar-Based Excipients Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Mrna Synthesis Raw Materials Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Silica Gel Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
Metformin Hydrochloride API Market