
 Air-Laid Product Market | 2026-2036
Air-Laid Product Market Size, Share, and Industry Trends Forecast 2026-2036
Air-Laid Product Market Analysis
Scandinavian pulp suppliers are decoupling from traditional fluff pulp contracts to serve dedicated air-laid lines. Glatfelter leverages its Ohio-based specialty fiber capacity to anchor North American medical material supply. Georgia-Pacific sustains cost leadership through captive wood pulp integration across its southeastern US mill network. McAirlaid's Vliesstoffe GmbH dominates European hygiene substrate production with precision-dispersion forming technology.
Air-laid products are non-woven structures formed by dispersing fibers in air and bonding them with latex or thermal binders, typically achieving densities of 0.03–0.3 g/cm³ with high bulk and rapid fluid acquisition. The manufacturing process employs drum formers or multi-former lines to distribute synthetic, natural, or biodegradable fibers into uniform webs for absorbent cores, wipes, and filtration media. Non-woven fabrics and absorbent pads lead product type output, with absorbent pads capturing expanding margin pools in adult incontinence applications. Hygiene products and filtration applications are diverging in material specifications, as filtration grades require finer synthetic fiber blends while hygiene grades pivot toward biodegradable pulp formulations.
The US EPA regulates pulp sourcing under Clean Water Act discharge permits, while the EU F-Gas Regulation and REACH framework constrain synthetic binder chemistries in European manufacturing. FDA device classification rules for sterilization wraps and surgical drapes shape product validation requirements for healthcare entrants. ISO 10993 biocompatibility standards increasingly determine market access for medical-grade air-laid materials across OECD jurisdictions. Stakeholders must monitor evolving biodegradability certification schemes in Germany and Japan, as these will determine which material platforms qualify for premium positioning in hygiene and food service segments.
Market Dynamics
Material substitution mandates under the EU Single-Use Plastics Directive are compressing synthetic fiber demand while accelerating biodegradable pulp blend qualification timelines across hygiene substrate supply chains.
Growth Catalysts
- Adult Incontinence Absorbent Core Demand:Hygiene manufacturers in Germany, Japan, and the United States are expanding order volumes for high-bulk air-laid cores as demographic aging intensifies product throughput requirements.
- REACH-Driven Binder Reformulation:European formulators are qualifying plant-based latex alternatives to comply with restricted substance annexes, opening specification windows for bio-based thermal bonding systems.
- Hospital-Acquired Infection Protocol Elevation:The US healthcare sector is mandating single-use medical wipes and sterilization wraps with validated bioburden control, pulling premium-grade air-laid material through FDA device classification pathways.
Market Restraints
- Fluff Pulp Supply Concentration:Scandinavian pulp suppliers are decoupling from long-term contracts to serve dedicated air-laid lines, creating allocation risk for non-integrated converters.
- Biodegradability Certification Cost Burden:Germany's DIN CERTCO and Japan's JBPA certification schemes impose extended validation timelines and testing fees that compress margins on commodity hygiene grades.
- Synthetic Fiber Substitution Pressure:Polypropylene and polyester fiber blends face displacement risk from cellulose alternatives, stranding capital in legacy multi-former lines optimized for thermoplastic processing.
Strategic Opportunities
- Filtration Media Specification Divergence:Industrial air filtration and HVAC applications are demanding finer synthetic fiber blends with engineered density gradients, creating margin pools distinct from hygiene commodity cycles.
- Captive Pulp Integration:Southeastern US mill networks with in-house wood pulp production can anchor cost structures against Scandinavian supply volatility.
- ISO 10993 Biocompatibility Positioning:Medical-grade material platforms validated to OECD-wide standards can capture sterilization wrap and surgical drape specifications ahead of general hygiene competitors.
Industry Challenges
- Precision-Dispersion Technical Talent Scarcity:Drum former optimization and multi-former line calibration require specialized process engineers in short supply across North American and European manufacturing bases.
- Legacy Latex Binder System Retrofit Complexity:Converters with thermal bonding infrastructure face capital-intensive reconfiguration to handle biodegradable pulp blends with altered moisture management profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-Laid Product Market |
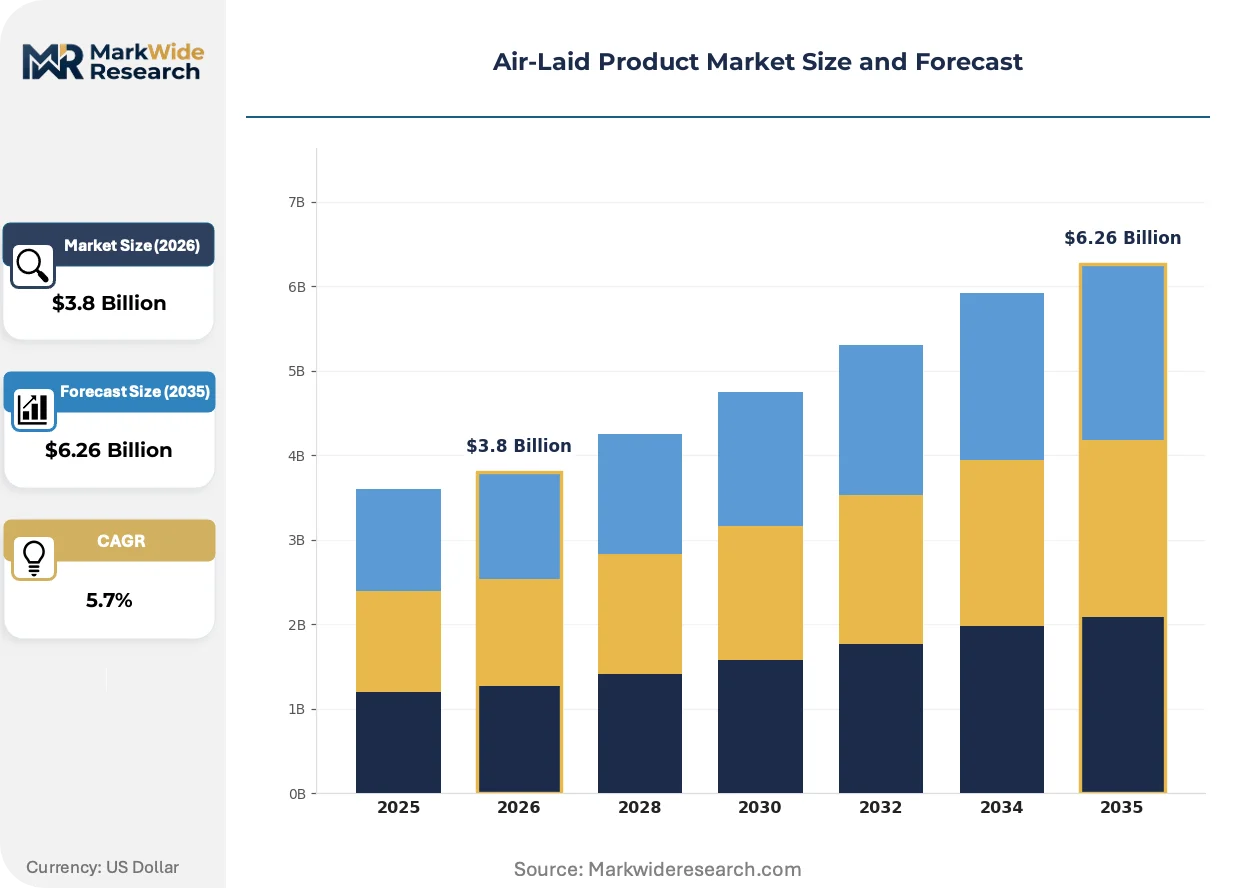
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Woven Fabrics, Absorbent Pads, Wipes, Medical Materials End User: Healthcare, Personal Care, Industrial, Food Service Application: Hygiene Products, Packaging, Filtration, Cleaning Material: Pulp, Synthetic Fibers, Biodegradable Materials, Wood Pulp |
| Companies Covered | Glatfelter, Georgia-Pacific, EAM Corporation, McAirlaid's Vliesstoffe GmbH, Duni AB, Main S.P.A., M&J Airlaid Products, Fitesa, Oji Kinocloth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-Laid Product Market Emerging Trajectories
Active fiber dispersion control and binder chemistry reformulation are compressing traditional process boundaries, while regulatory material mandates and healthcare procurement centralization reshape competitive positioning.
Precision-dispersion forming technology is integrating real-time basis weight control with multi-component fiber blending to achieve sub-gram density uniformity across absorbent pad webs. Adult incontinence manufacturers in Germany are adopting these systems at replacement cycle pace to meet OEM specification tightening. The technology is integrating formerly separate forming and bonding stages, reducing line footprint while elevating fluid acquisition speed thresholds.
The EU F-Gas Regulation and REACH restricted substance annexes are constraining fluorinated and formaldehyde-based binder chemistries in European air-laid manufacturing. Industrial consequences include accelerated qualification of carboxymethyl cellulose and starch-based thermal binders with comparable wet strength profiles. Hygiene grades targeting German retail channels are most affected, with converters absorbing reformulation costs to maintain shelf placement under private-label sustainability scorecards.
Centralized procurement by US hospital systems and long-term care chains is consolidating absorbent product specification authority away from brand marketing teams. Group purchasing organizations are unbundling after-sales technical service from material supply contracts, compressing converter margin contribution from application engineering. This concentration is most visible in the North American healthcare sector, where IDN consolidation has reduced the number of independent purchasing decision points by half over the past decade.
Air-Laid Product Market Segmentation
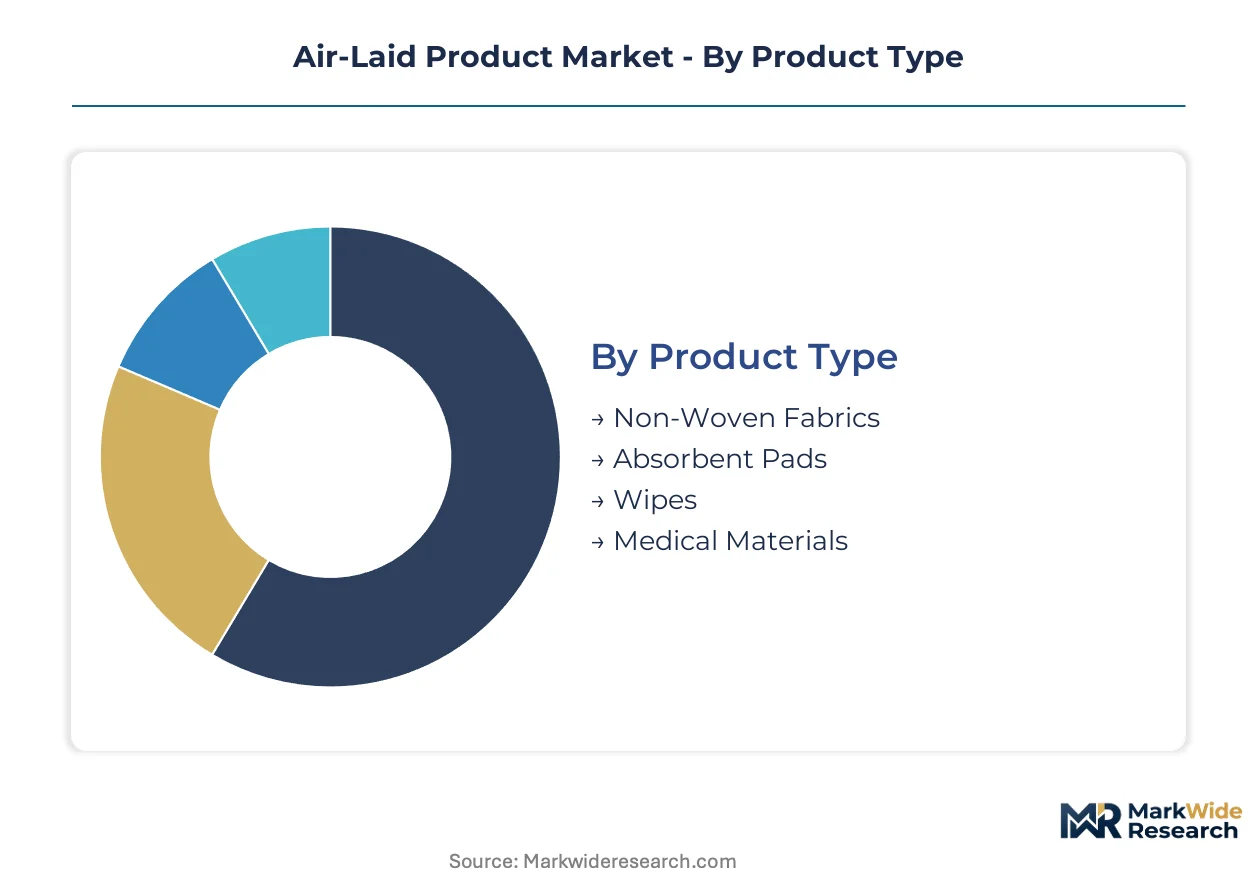
Air-laid product specifications diverge sharply across end-use applications, with hygiene substrates demanding biodegradable pulp compliance while filtration media prioritize synthetic fiber precision. Material selection and bonding chemistry now determine qualification timelines more than line speed or basis weight uniformity.
Product Type:
Replacement cycles for forming and bonding equipment are accelerating as converters reconfigure lines to handle pulp blend reformulations mandated by EU and Japanese regulators.
- Non-Woven Fabrics:These structures achieve densities of 0.03–0.3 g/cm³ through air-dispersed fiber webs bonded with latex or thermal systems. Demand concentrates in German and Japanese hygiene manufacturing where OEMs are tightening fluid acquisition speed specifications for adult incontinence cores.
- Absorbent Pads:High-bulk cores engineered for rapid fluid acquisition dominate order volumes from North American healthcare and European personal care channels. Margin pools are expanding most visibly in adult incontinence applications as demographic aging intensifies throughput requirements across Germany, Japan, and the United States.
- Wipes:Single-use medical wipes with validated bioburden control are pulling premium-grade material through FDA device classification pathways in the US healthcare sector.
- Medical Materials:Sterilization wraps and surgical drapes require ISO 10993 biocompatibility validation to access OECD-wide hospital procurement networks.
Volume placements concentrate in Absorbent Pads; the faster expansion belongs to Medical Materials.
End User:
Procurement centralization by large buyers is compressing converter margins while elevating technical service requirements.
- Healthcare:Hospital-acquired infection protocols mandate single-use medical wipes and sterilization wraps with validated bioburden control. US group purchasing organizations have consolidated specification authority, reducing independent purchasing decision points by half over the past decade.
- Personal Care:Adult incontinence and feminine care manufacturers in Germany and Japan are expanding order volumes for high-bulk air-laid cores.
- Industrial:HVAC and air filtration applications demand finer synthetic fiber blends with engineered density gradients, creating margin pools distinct from hygiene commodity cycles.
- Food Service:Biodegradability certification schemes in Germany and Japan determine material platform qualification for premium positioning.
Healthcare commands the largest volume commitments; Industrial filtration is climbing the fastest as synthetic fiber specifications diverge from hygiene grades.
Application:
Material substitution mandates under the EU Single-Use Plastics Directive are compressing synthetic fiber demand while accelerating biodegradable pulp blend qualification timelines.
- Hygiene Products:Absorbent cores for adult incontinence and feminine care represent the dominant volume application. REACH-driven binder reformulation is forcing qualification of plant-based latex alternatives and bio-based thermal bonding systems.
- Packaging:Food service segments require biodegradable pulp formulations certified under Germany's DIN CERTCO and Japan's JBPA schemes.
- Filtration:Industrial air filtration demands finer synthetic fiber blends with engineered density gradients, creating specification divergence from hygiene grades.
- Cleaning:Single-use wipes for healthcare and institutional channels require validated bioburden control under FDA device classification rules.
Hygiene Products anchor current volume; Filtration is gaining share fastest as synthetic fiber specifications diverge from biodegradable pulp trends.
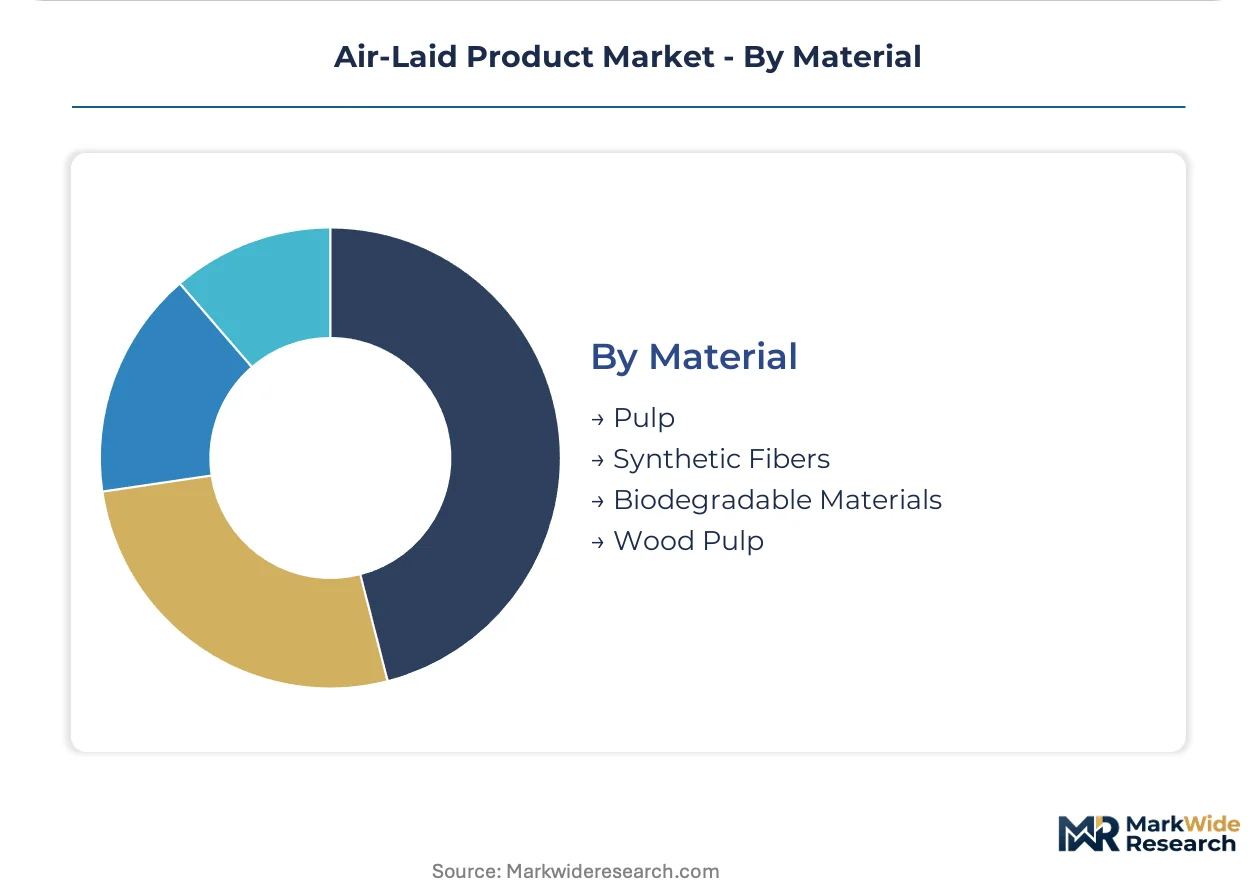
Material:
Supply concentration in Scandinavian pulp is creating allocation risk for non-integrated converters while captive wood pulp integration anchors cost structures.
- Pulp:Scandinavian suppliers are decoupling from long-term fluff pulp contracts to serve dedicated air-laid lines, creating supply volatility for non-integrated converters.
- Synthetic Fibers:Polypropylene and polyester blends face displacement pressure from cellulose alternatives, stranding capital in legacy multi-former lines optimized for thermoplastic processing.
- Biodegradable Materials:Carboxymethyl cellulose and starch-based thermal binders are qualifying as REACH-compliant alternatives to fluorinated and formaldehyde-based chemistries.
- Wood Pulp:Southeastern US mill networks with in-house production are anchoring cost structures against Scandinavian supply volatility.
Wood Pulp and conventional Pulp dominate current placements; Biodegradable Materials are expanding most quickly as certification schemes proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian fluff pulp forests anchor supply security for air-laid substrate manufacturers, while demand gravity concentrates in Germany, Japan, and the United States where demographic aging and infection control protocols drive specification tightening.
United States
Hospital-acquired infection protocols mandate single-use medical wipes and sterilization wraps with validated bioburden control. FDA device classification rules shape product validation requirements for healthcare entrants. Ohio-based specialty fiber capacity anchors North American medical material supply.
Germany
Adult incontinence manufacturers expand order volumes for high-bulk absorbent cores as demographic aging intensifies throughput requirements. REACH restricted substance annexes accelerate qualification of plant-based latex alternatives. McAirlaid's Vliesstoffe GmbH dominates European hygiene substrate production with precision-dispersion forming technology.
Japan
Feminine care and adult incontinence segments drive specification tightening for rapid fluid acquisition cores. JBPA certification schemes impose extended validation timelines for biodegradable material platforms. Industrial clusters around Nagoya and Osaka concentrate precision-forming equipment deployment.
Sweden
Pulp suppliers decouple from traditional fluff pulp contracts to serve dedicated air-laid lines, creating allocation risk for non-integrated converters. EU F-Gas Regulation constrains synthetic binder chemistries in adjacent manufacturing. Forest product clusters in Västra Götaland and Norrland redirect fiber flows toward air-laid substrate qualification.
China
Domestic hygiene manufacturers expand captive air-laid capacity to reduce import dependence for absorbent core materials. GB standards and MIIT industrial policy guide equipment localization programs. Yangtze River Delta manufacturing bases integrate drum former technology for regional supply chain security.
Air-Laid Product Market Vendor Landscape
Global majors compete with regional champions across pulp integration and forming technology dimensions. The vendor base separates into captive pulp-integrated conglomerates, precision-forming specialists, and regional hygiene substrate suppliers. Three archetypes dominate: Scandinavian pulp-integrated multinationals with southeastern US mill networks, German precision-dispersion technology specialists, and Asian hygiene-focused converters. Competitive moves concentrate on captive pulp integration and multi-former line reconfiguration for biodegradable blend handling.
Among North American pulp-integrated players, Glatfelter and Georgia-Pacific exemplify the scale-driven archetype through captive wood fiber control. McAirlaid's Vliesstoffe GmbH represents the European precision-forming specialist tier with dedicated air-laid line concentration. These three anchors illustrate how geographic proximity to pulp supply and regulatory stringency shape competitive positioning across hygiene and medical grade segments.
| Leading Market Players |
|---|
| Glatfelter |
| Georgia-Pacific |
| EAM Corporation |
| McAirlaid's Vliesstoffe GmbH |
| Duni AB |
| Main S.P.A. |
| M&J Airlaid Products |
| Fitesa |
| Oji Kinocloth |
| Others |
Supply Flow & Price Mechanics
Precision-dispersion process engineers concentrated in Germany's Baden-Württemberg industrial corridor command wage premiums that widen pricing-tier spreads between ISO 10993-validated medical grades and commodity hygiene substrates. Labor-cost differentials between European specialists and southeastern US mill operators translate directly into three-tier pricing stratification across absorbent pad and sterilization wrap categories.
Pricing Analysis
Warranty and technical service bundling separates premium medical-grade supply contracts from unbundled commodity hygiene transactions. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility certification, captive pulp integration status, and after-sales application engineering depth. Cost compression in standard-tier hygiene grades is intensifying because REACH-driven binder reformulation expenses are absorbing converter margins without corresponding price recovery. Brand-name OEMs in German adult incontinence manufacturing exhibit lowest price sensitivity; private-label distributors in food service segments demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Scandinavian fluff pulp suppliers decoupling from long-term contracts to serve dedicated air-laid lines. Raw material flows draw from Sweden, Finland, and the southeastern United States, with synthetic fiber inputs resting on polypropylene and polyester feedstocks from German and Japanese chemical producers. Tariff exposure on pulp imports into China and the United States threatens cost structures for non-integrated converters. Distribution runs through hygiene substrate converters, medical device OEMs, and group purchasing organizations in healthcare procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
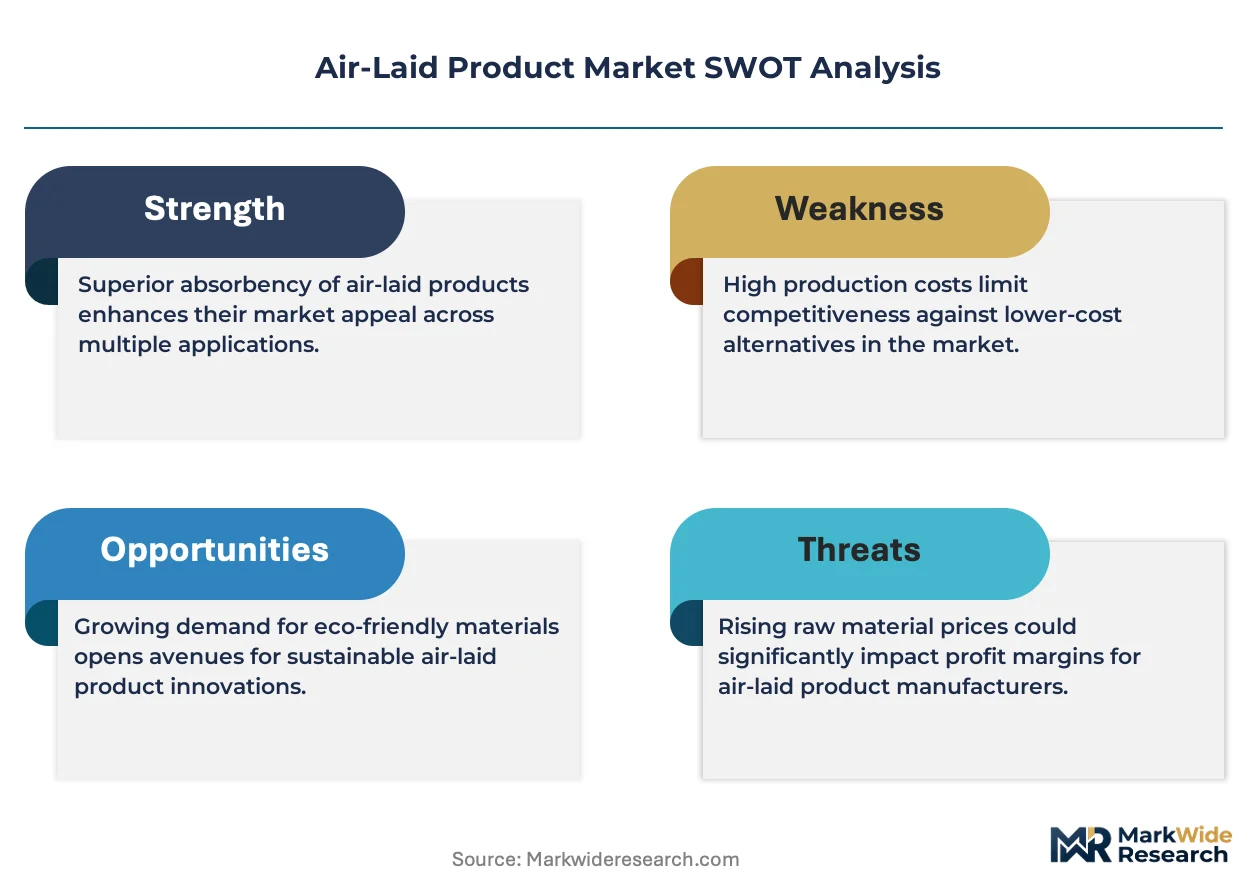
This market reads as a cost-of-compliance story where the EU Single-Use Plastics Directive erects barrier-to-entry moats favoring players with pre-qualified biodegradable pulp platforms and DIN CERTCO certification infrastructure.
For Market Incumbents: Extend captive pulp integration into southeastern US mill networks to anchor cost structures against Scandinavian supply volatility. Deepen ISO 10993 validation infrastructure to capture sterilization wrap specifications ahead of general hygiene competitors facing REACH-driven reformulation costs. Defend against emerging Asian hygiene-focused converters by locking multi-year absorbent core supply agreements with German and Japanese OEMs before their domestic capacity ramps. For New Entrants and Emerging Players: Launch via direct supply contracts with US hospital systems and long-term care chains bypassing consolidated group purchasing organization channels. Target industrial filtration applications demanding finer synthetic fiber blends with engineered density gradients, where specification divergence from hygiene commodity cycles creates margin pools with less incumbent concentration. Exploit precision-dispersion technical talent scarcity by recruiting former McAirlaid process engineers and deploying real-time basis weight control systems as technical differentiation. For Investors and Strategic Acquirers: Re-rating potential sits with captive pulp-integrated mid-caps given sustained Scandinavian supply volatility and REACH compliance cost absorption. Long-term viability hinges on backward integration into wood pulp production and multi-former line reconfiguration for biodegradable blend handling. Watch Japanese JBPA certification timeline acceleration as the inflection signal indicating which material platforms secure premium positioning in feminine care and food service segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wood Pulp Production | Southeastern US mill networks anchor cost structures against Scandinavian supply allocation risk. |
| ISO 10993 Biocompatibility Validation Investment | Medical-grade platforms access OECD-wide hospital procurement networks ahead of hygiene competitors. |
| Multi-Former Line Reconfiguration for Biodegradable Blends | REACH-compliant carboxymethyl cellulose binder systems qualify for German retail sustainability scorecards. |
| Precision-Dispersion Technology Licensing | Real-time basis weight control systems differentiate fluid acquisition speed specifications for adult incontinence OEMs. |
| Long-Term Supply Agreement with Hospital Systems | Direct contracts with US IDNs bypass GPO consolidation compressing converter margin contribution. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drum former operators, hygiene substrate procurement managers, biomedical engineers at hospital purchasing committees, and REACH compliance officers at European converters. FDA 510(k) submissions, ECHA restricted substance annex updates, DIN CERTCO certification databases, and Japanese JBPA biodegradability registries provided validation anchors. Bottom-up capacity assessments across German, US, and Chinese manufacturing bases triangulated against top-down demand modeling from demographic aging projections and infection control protocol adoption curves.
Segment-level granularity modeled product type, end user, application, and material composition dimensions across the analysis window, with absorbent pad and medical material categories receiving separate fluid acquisition speed and biocompatibility validation treatment. CAGRs derived from equipment replacement cycle analysis, pulp supply contract renegotiation patterns, and regulatory compliance timeline acceleration. Industry-specific inputs incorporated precision-dispersion forming technology deployment rates and REACH-driven binder reformulation cost pass-through elasticity.
Scandinavian pulp supply contract decoupling, REACH annex expansion scope, and JBPA certification timeline acceleration are the dominant revision risks to modeled outputs. Deviation in EU Single-Use Plastics Directive enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
Carbon Black for Packaging Market