
 Specialty Sorbents Market | 2026-2036
Specialty Sorbents Market Size, Share, and Industry Trends Forecast 2026-2036
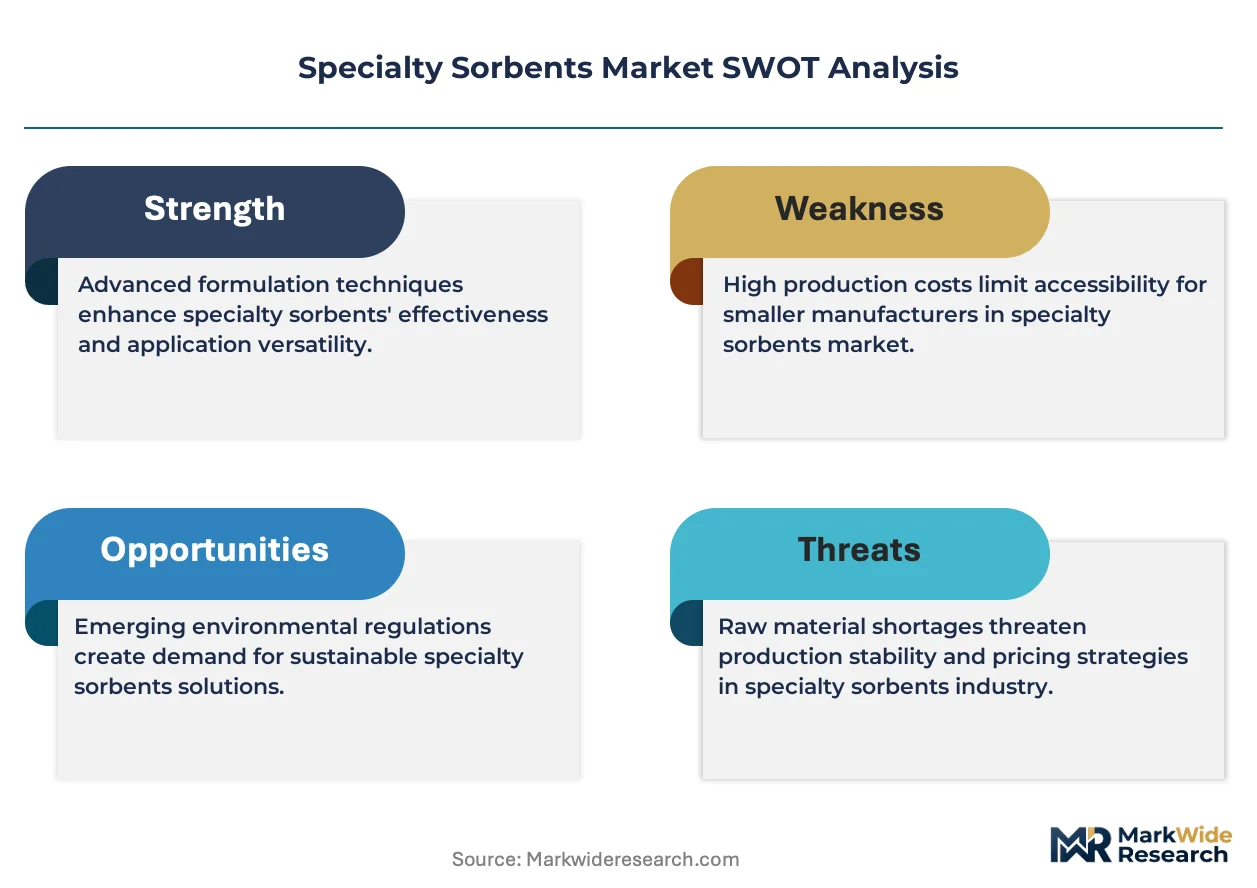
Specialty Sorbents Market Analysis
Activated carbon is consolidating its position across industrial gas purification as manufacturers phase out older peat-based alternatives. BASF SE leverages its Ludwigshafen integrated production complex to sustain captive supply of polymer-grade sorbent precursors. Clariant AG anchors its specialty chemicals portfolio with high-performance zeolite catalysts for petrochemical clients. Evonik Industries AG differentiates through controlled-pore silica architectures targeting pharmaceutical moisture management.
Specialty sorbents are engineered materials with defined pore structures, surface areas typically exceeding 300 square meters per gram, and selective affinity for target molecules; they function to remove contaminants, control humidity, or recover valuable substances in process streams. Granular formats dominate bulk water treatment installations where flow rates and bed longevity determine operating economics, while fiber configurations capture margin in aerospace and defense dehumidification systems requiring conformable geometries. Activated carbon retains the largest material share due to its universal adsorption profile, though zeolite demand accelerates in natural gas dehydration where molecular sieving precision reduces energy intensity.
EPA effluent limitation guidelines and REACH substance restrictions compel manufacturers to validate sorbent regeneration cycles and document secondary waste disposal pathways. China's MEE enforces stricter volatile organic compound capture mandates at chemical parks, directly expanding activated carbon and carbon molecular sieve procurement. Japan's METI circular economy roadmaps incentivize spent sorbent thermal reactivation infrastructure investments. Stakeholders must weigh capital allocation between bio-based precursor development and regeneration service networks as regulatory compliance costs diverge across jurisdictions.
Market Dynamics
Water treatment utilities in Germany and Japan are accelerating procurement of high-performance sorbent systems as EPA and MEE discharge limits tighten, compressing replacement cycles for legacy peat-based installations and redirecting capital toward regeneration-capable infrastructure.
Growth Catalysts
- EPA Effluent Limitation Guidelines:US manufacturing facilities must upgrade to activated carbon systems with documented secondary waste pathways, expanding replacement demand across chemical processing and metal finishing plants.
- Silica gel formulations:Precision electronics manufacturers in Taiwan and South Korea are displacing conventional clay desiccants with controlled-pore architectures for moisture-sensitive semiconductor packaging.
- China's Yangtze River Delta:Chemical park clusters are consolidating volatile organic compound capture procurement, driving carbon molecular sieve adoption at integrated petrochemical complexes.
Market Restraints
- Petroleum-based precursor volatility:Activated carbon production depends on coal tar pitch and coconut shell supply from Southeast Asian processing hubs, exposing margin structures to energy market swings.
- Zeolite supply concentration:Synthetic zeolite capacity clusters in select US and German production corridors, creating vulnerability for natural gas dehydration project timelines.
- REACH substance restrictions:ECHA documentation requirements for sorbent regeneration cycles add compliance overhead that disadvantages smaller service providers.
Strategic Opportunities
- India's industrial water sector:Central Pollution Control Board mandates for zero liquid discharge at textile and pharmaceutical clusters create first-mover potential for modular activated carbon systems.
- Bio-based precursor development:Agricultural residue conversion to activated carbon feedstock aligns with EU Green Deal circular economy procurement criteria for public infrastructure projects.
- Pharmaceutical moisture management:Controlled-pore silica architectures are penetrating oral solid dosage packaging as FDA stability testing protocols tighten water vapor transmission specifications.
Industry Challenges
- Thermal reactivation engineering talent:Spent sorbent regeneration facilities require specialized kiln operators and emissions control technicians, with skill shortages constraining service network expansion in Japan and Germany.
- Legacy system integration:Water treatment utilities face friction retrofitting continuous regeneration loops into batch-operated legacy infrastructure without disrupting throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Sorbents Market |
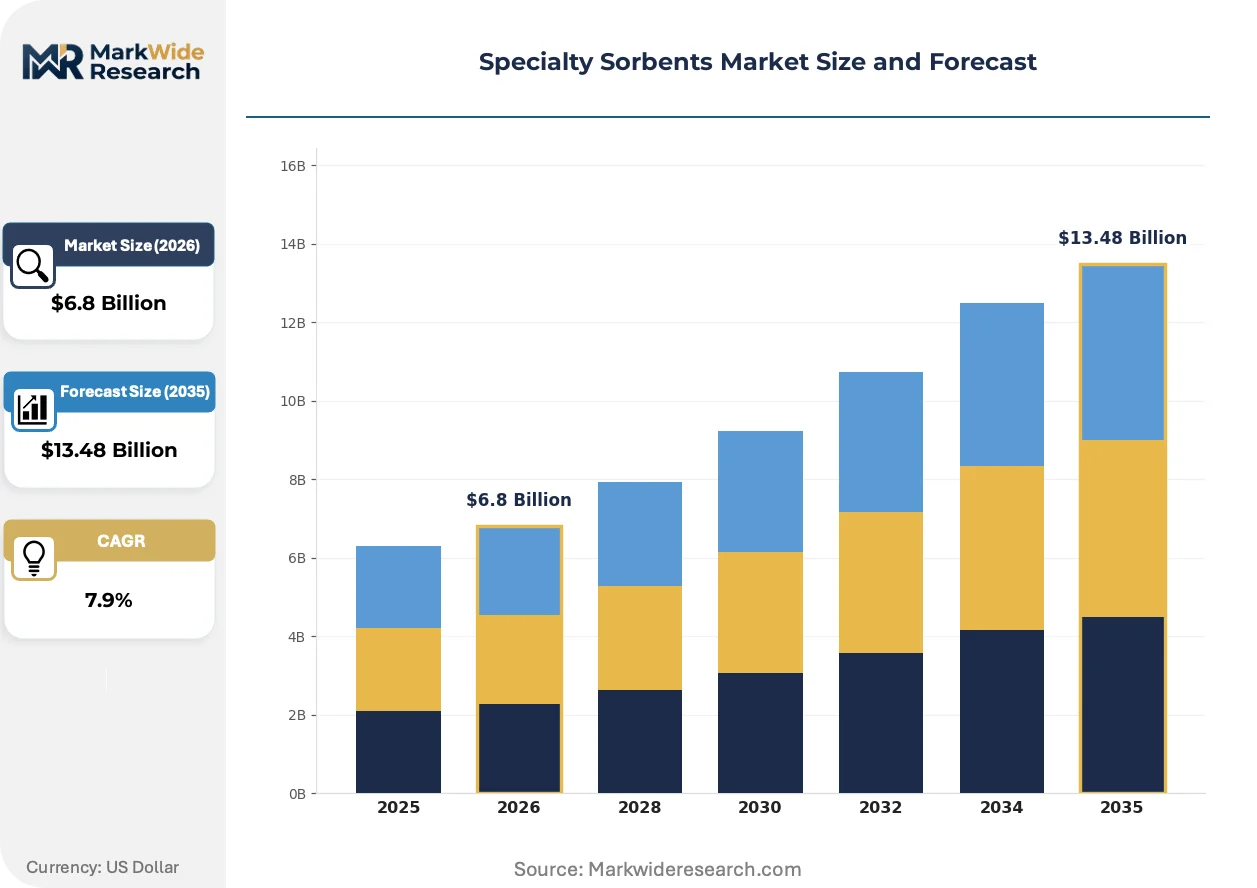
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Fiber, Sheet Application: Water Treatment, Oil Spill Cleanup, Air Purification, Food Processing Material: Activated Carbon, Silica Gel, Zeolite, Clay End User: Industrial, Agricultural, Environmental, Household |
| Companies Covered | Mitsubishi Chemical Holdings Corporation, Honeywell, BASF SE, Sumitomo Chemical, Kolon Industries, Arkema SA, Clariant AG, Tosoh Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Sorbents Market Emerging Trajectories
Material science advances and regulatory documentation requirements are compressing product development cycles while expanding the performance envelope of engineered sorbent architectures across industrial gas and liquid treatment applications.
Surface-functionalized activated carbon is absorbing targeted contaminants with enhanced selectivity for per- and polyfluoroalkyl substances in groundwater remediation. Environmental engineering firms in the US and Netherlands are specifying these materials for Department of Defense site cleanup contracts. The technology is absorbing premium pricing power previously captured by ion exchange resin systems in specialized remediation verticals.
REACH substance restrictions are compelling manufacturers to validate closed-loop regeneration cycles and document waste disposal pathways across European operations. Chemical processors in Germany's Ruhr region are investing in captive thermal reactivation infrastructure to maintain material handling compliance. This regulatory pressure is compressing procurement timelines as buyers prioritize vendors with established regeneration service networks over spot suppliers.
Service-based contracting is displacing traditional equipment purchase models in municipal water treatment procurement. French and Japanese utilities are contracting full-service sorbent management including delivery, installation, monitoring, and spent material recovery under multi-year agreements. This shift concentrates purchasing authority among integrated solution providers and compresses margins for pure material suppliers in Western European markets.
Specialty Sorbents Market Segmentation
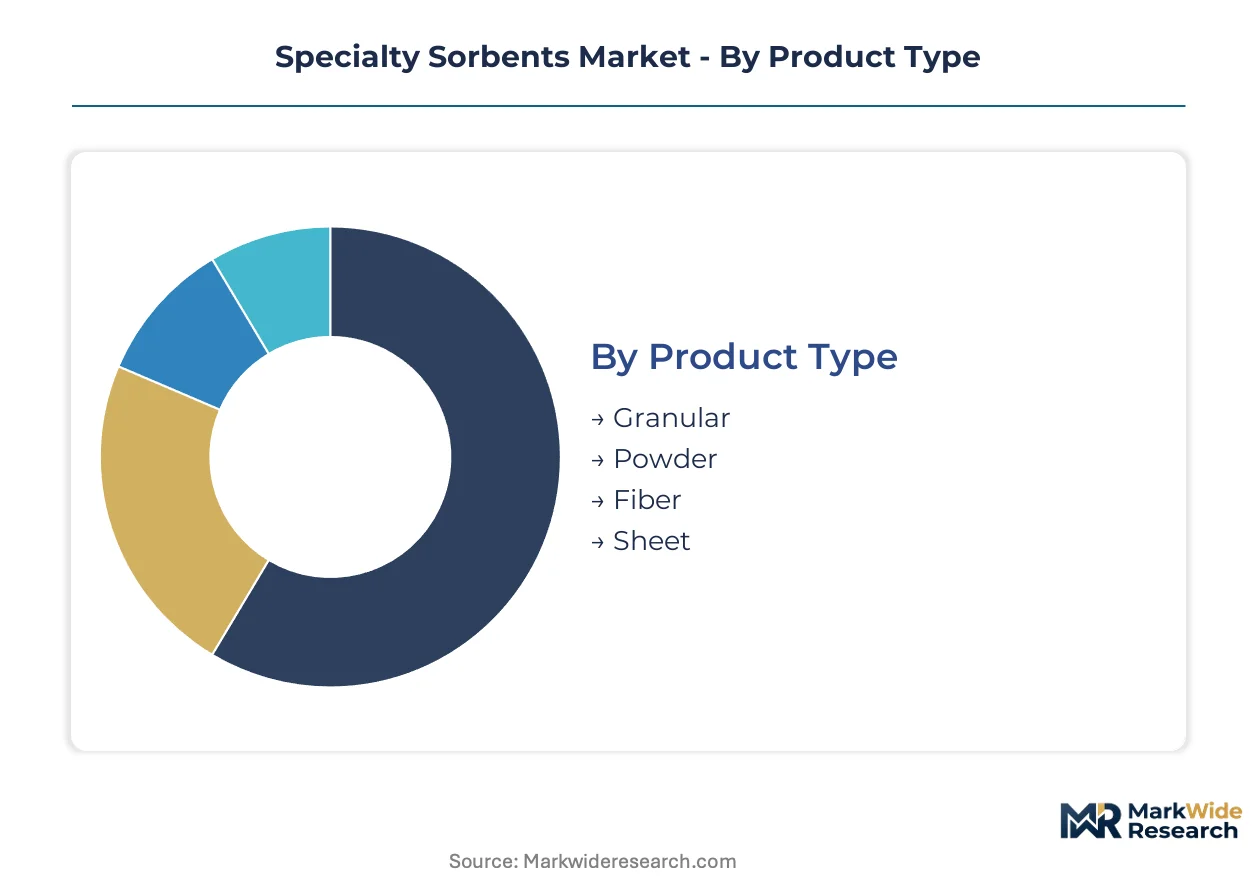
Specialty sorbent procurement patterns diverge sharply across physical formats, target contaminants, and regulatory environments. Manufacturers configure product portfolios around these divisions to align production assets with margin structures and compliance documentation requirements.
Product Type:
Granular production concentrates in captive kiln operations serving municipal water utilities, while fiber manufacturing requires specialized spinning infrastructure concentrated among aerospace suppliers.
- Granular:Irregular particles sized 0.2-5.0 mm dominate fixed-bed adsorption systems. German and Japanese water treatment utilities specify this format for EPA and MEE-compliant effluent polishing, prioritizing hydraulic conductivity and attrition resistance over unit surface area.
- Fiber:Woven or non-woven configurations enable conformable geometries in aerospace dehumidification and protective packaging. Taiwan semiconductor manufacturers specify controlled-pore fiber architectures for cleanroom humidity management, displacing rigid canister designs.
- Powder:Pulverized activated carbon serves batch treatment processes and rapid-response oil spill remediation where dispersion speed outweighs recovery economics.
- Sheet:Laminated composites integrate sorbent particles into flexible substrates for consumer electronics desiccant cards and pharmaceutical blister packaging.
Granular formats absorb the bulk of installed capacity; fiber configurations are expanding most quickly.
Application:
End-use specifications determine regeneration service requirements and documentation burdens, with water treatment commanding the most rigorous compliance protocols.
- Water Treatment:Municipal and industrial facilities deploy activated carbon and zeolite systems for EPA effluent limitation compliance. China's Yangtze River Delta chemical clusters consolidate procurement of carbon molecular sieves for volatile organic compound capture.
- Air Purification:HVAC and industrial gas treatment applications specify activated carbon for broad-spectrum contaminant removal. REACH documentation requirements for spent material handling favor vendors with established European reactivation networks.
- Oil Spill Cleanup:Hydrophobic sorbent booms and loose particulates serve maritime and pipeline emergency response, with procurement concentrated among coast guard agencies and oil terminal operators.
- Food Processing:Edible oil decolorization and beverage purification drive demand for acid-washed activated carbon grades meeting FDA food-contact specifications.
Water treatment commands the dominant share of procurement volume; air purification is climbing the fastest as indoor air quality regulations tighten.
Material:
Precursor supply geography and thermal reactivation infrastructure availability constrain material selection for large-scale deployments.
- Activated Carbon:Coal tar pitch and coconut shell precursors yield universal adsorption profiles. Southeast Asian shell processing hubs expose margin structures to agricultural commodity swings and energy market volatility.
- Zeolite:Synthetic molecular sieves enable precise pore-size selectivity for natural gas dehydration. Capacity concentrates in US and German production corridors, creating project timeline vulnerability for international buyers.
- Silica Gel:Controlled-pore architectures target pharmaceutical moisture management and precision electronics packaging. Evonik Industries AG differentiates through architectural precision in oral solid dosage applications.
- Clay:Conventional desiccant grades face displacement by silica gel in semiconductor packaging, though low-cost mineral sorbents retain share in bulk industrial drying.
Activated carbon retains the largest material position; zeolite is gaining share fastest on natural gas processing demand.
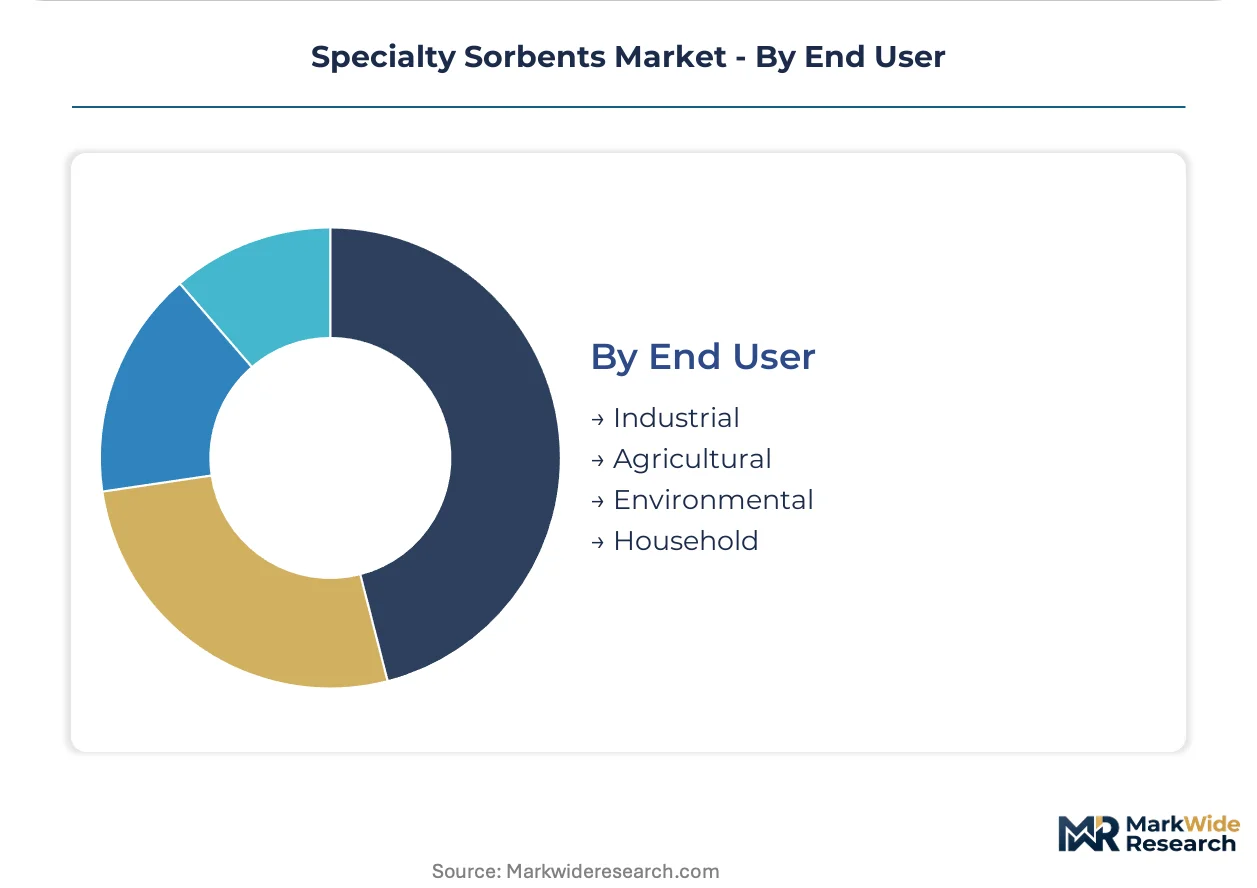
End User:
Customer scale and technical sophistication determine contracting structure, with industrial buyers shifting toward service-based models.
- Industrial:Chemical processors and manufacturers specify sorbent systems for process stream purification and environmental compliance. French and Japanese utilities are contracting full-service sorbent management under multi-year agreements.
- Environmental:Remediation contractors and government agencies procure surface-functionalized activated carbon for per- and polyfluoroalkyl substance groundwater cleanup, absorbing premium pricing in specialized verticals.
- Agricultural:Grain storage and livestock operations deploy low-cost clay and silica gel desiccants for moisture control in bulk commodity handling.
- Household:Consumer packaging and appliance manufacturers integrate desiccant cards and canisters at specification levels below industrial grades.
Industrial end users absorb the bulk of procurement value; environmental remediation is expanding most quickly on contamination liability drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentrates in chemical manufacturing corridors and water treatment infrastructure hubs across Germany, Japan, China, the United States, and India. EPA and MEE discharge mandates compress replacement cycles for legacy installations. Regeneration service networks determine vendor selection in mature markets.
Germany
Ruhr region chemical processors invest in captive thermal reactivation infrastructure to maintain REACH compliance. ECHA documentation requirements for spent sorbent handling favor vendors with established regeneration networks. BASF SE leverages its Ludwigshafen integrated complex to sustain captive supply of polymer-grade precursors.
Japan
Water treatment utilities accelerate procurement of high-performance systems as METI circular economy roadmaps incentivize spent sorbent infrastructure. Municipal buyers contract full-service sorbent management under multi-year agreements. Kanto region facilities prioritize vendors with documented regeneration capabilities.
China
Yangtze River Delta chemical clusters consolidate volatile organic compound capture procurement. MEE enforces stricter mandates at chemical parks, expanding activated carbon and carbon molecular sieve procurement. Integrated petrochemical complexes drive carbon molecular sieve adoption for natural gas dehydration.
United States
Department of Defense site cleanup contracts absorb surface-functionalized activated carbon for per- and polyfluoroalkyl substance groundwater remediation. EPA effluent limitation guidelines compel manufacturing facilities to upgrade to systems with documented secondary waste pathways. Chemical processing and metal finishing plants expand replacement demand.
India
Central Pollution Control Board mandates for zero liquid discharge at textile and pharmaceutical clusters create procurement opportunities. Textile hubs in Gujarat and pharmaceutical corridors near Hyderabad specify modular activated carbon systems. First-mover vendors establish regeneration service partnerships to meet compliance documentation requirements.
Specialty Sorbents Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers add kiln operations to capture regeneration service revenue. The vendor base separates into integrated chemical conglomerates with captive precursor supply, specialized sorbent manufacturers with architectural precision capabilities, and regional service providers focused on thermal reactivation. Strategic archetypes include full-service solution providers, material science specialists, and regeneration network operators. M&A activity concentrates on acquiring thermal reactivation assets, while portfolio diversification moves target bio-based precursor development.
Among diversified chemical conglomerates, Mitsubishi Chemical Holdings Corporation and BASF SE exemplify integrated production strategies with captive supply chains. Evonik Industries AG occupies a position within the specialty materials tier, differentiating through controlled-pore architectures. These three entities represent distinct competitive vectors: conglomerate scale, integrated production, and architectural precision.
| Leading Market Players |
|---|
| Mitsubishi Chemical Holdings Corporation |
| Honeywell |
| BASF SE |
| Sumitomo Chemical |
| Kolon Industries |
| Arkema SA |
| Clariant AG |
| Tosoh Corporation |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Premium-regeneration-capable sorbent tiers command three-to-five-fold markups over commodity spot grades, bifurcating procurement between municipal utilities with multi-year service contracts and industrial buyers transacting on volume. This tier divergence maps directly onto supply chain configurations: high-margin tiers source from integrated German and Japanese producers with captive thermal reactivation infrastructure, while economy grades flow through Southeast Asian coconut shell processing hubs exposed to agricultural commodity swings.
Pricing Analysis
Volume-driven granular activated carbon for municipal water treatment operates on thin margins, while architectural-precision silica gel for pharmaceutical packaging sustains premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates vendors with documented regeneration networks from spot suppliers lacking compliance documentation. Cost compression in economy tiers is intensifying because coconut shell supply volatility from Philippine and Indonesian processing hubs feeds into precursor costs. Municipal utilities in Germany and Japan exhibit lowest price sensitivity due to regulatory compliance imperatives, while Indian textile processors negotiating zero-liquid-discharge installations demonstrate acute cost consciousness.
Supply Chain Analysis
Domestic-content mandates in India's Central Pollution Control Board procurement guidelines are reshaping sourcing patterns toward local kiln partnerships. Activated carbon production draws from coal tar pitch feedstock concentrated in German and US petrochemical corridors, coconut shell char from Southeast Asian agricultural processing hubs, and synthetic zeolite precursors clustered in select US and German production facilities. Single-source vulnerability concentrates in coconut shell supply from Philippine and Indonesian processing centers exposed to typhoon disruption and energy price volatility. Distribution runs through integrated solution providers delivering full-service sorbent management, displacing pure material suppliers in Western European and Japanese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as REACH documentation burdens and thermal reactivation infrastructure requirements force smaller service providers toward exit or acquisition. Regulatory compliance costs are accelerating this consolidation by advantaging integrated vendors with established regeneration networks.
For Market Incumbents: Extend regeneration service footprints into India's textile and pharmaceutical corridors before local competitors establish captive kiln partnerships. BASF SE and Clariant AG should deepen backward integration into bio-based precursor development to preempt EU Green Deal circular economy procurement criteria, while defending against emerging Chinese carbon molecular sieve producers through architectural precision investments in pharmaceutical-grade silica gel.
For New Entrants and Emerging Players: Modular activated carbon system buyers in India's Gujarat textile hubs represent the most penetrable white-space target, with Central Pollution Control Board zero-liquid-discharge mandates creating compliance-driven procurement urgency. First-mover advantage accrues to vendors establishing regeneration service partnerships with local industrial park operators, bypassing capital-intensive kiln ownership through contractual service arrangements.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking thermal reactivation assets and regional service networks. Long-term viability favors vendors with demonstrated regeneration capabilities and documented compliance pathways across multiple regulatory jurisdictions. The signal to watch is MEE enforcement intensity at China's Yangtze River Delta chemical parks, which would accelerate carbon molecular sieve procurement and validate premium pricing for molecular-sieving precision.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Precursors | Agricultural residue conversion aligns with EU Green Deal procurement criteria for public infrastructure. |
| Thermal Reactivation Asset Acquisition | Captive kiln infrastructure secures REACH compliance and captures recurring service revenue from municipal utilities. |
| Modular System Deployment in India | Zero-liquid-discharge mandates at textile clusters create first-mover positioning before local competition consolidates. |
| Pharmaceutical-Grade Silica Gel Capacity Expansion | FDA stability testing protocol tightening drives moisture management specification upgrades in oral solid dosage packaging. |
| Multi-Year Service Contract Structuring | French and Japanese utility procurement shifts concentrate purchasing authority among integrated solution providers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at German and Japanese water treatment utilities, procurement leads at Yangtze River Delta chemical parks, technical R&D directors at pharmaceutical packaging manufacturers, and distribution channel partners across European reactivation networks. EPA effluent limitation guidelines, ECHA REACH documentation requirements, and MEE volatile organic compound mandates provided regulatory calibration. Bottom-up sizing of granular, fiber, powder, and sheet format demand was cross-referenced against top-down chemical industry production indices.
Data-stream reconciliation across import-export statistics, kiln capacity registries, and municipal procurement databases established volume baselines. Segmentation modeling spanned physical format, target contaminant application, precursor material type, and end-user industry vertical across the projection horizon. CAGRs were derived from regression analysis of historical replacement cycle compression and regulatory mandate implementation timelines, with specific weighting for natural gas dehydration demand and pharmaceutical moisture management specification tightening.
Revisions become necessary when coconut shell agricultural yields collapse, REACH substance restrictions expand to additional chemical categories, or MEE enforcement intensity at Chinese chemical parks accelerates beyond modeled scenarios. Forecasts reflect assumptions regarding regulatory implementation timelines and regeneration infrastructure buildout rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Acetyl Tyrosine Market
Specialty Compounds
Compounds Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market