
 Aluminium Potassium Sulphate Market | 2026-2036
Aluminium Potassium Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Potassium Sulphate Market Outlook
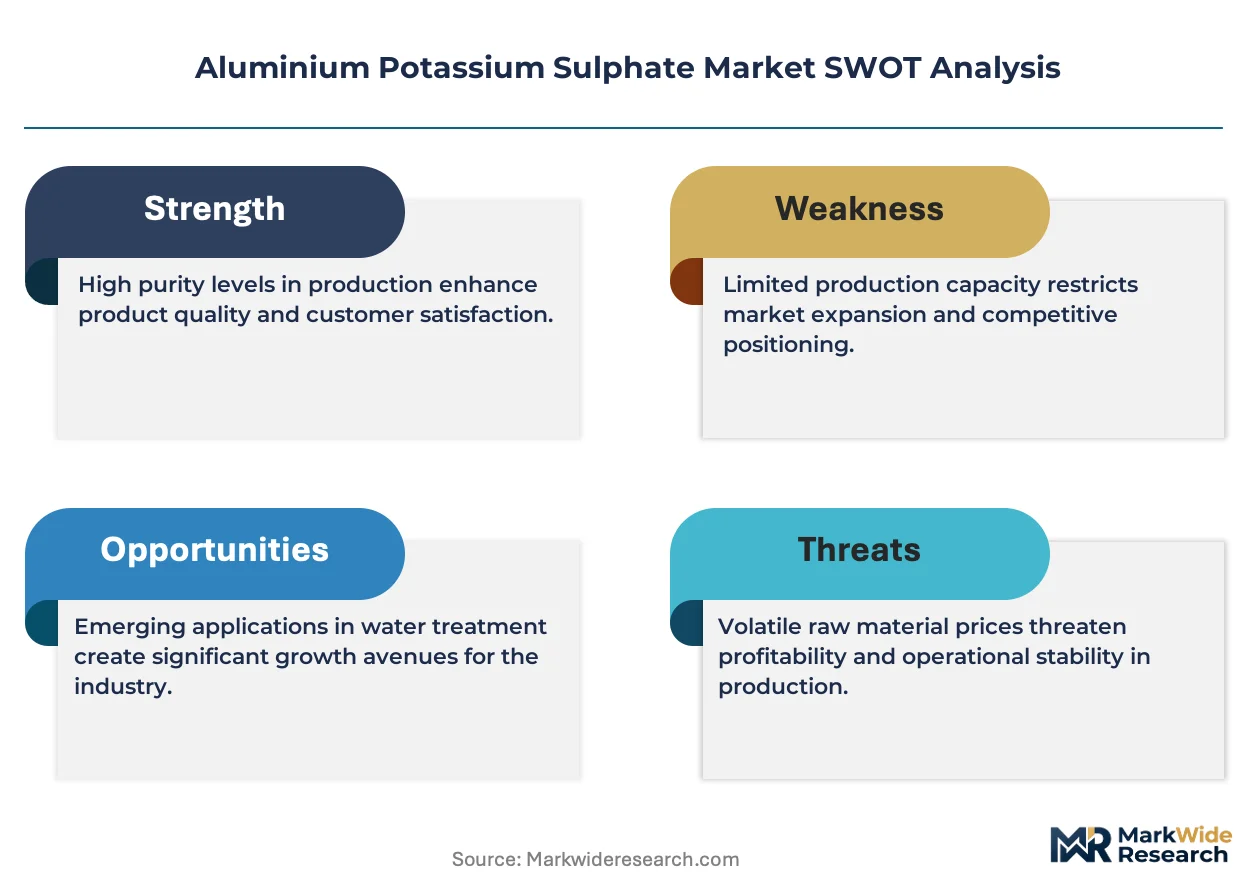
Modular dosing-unit packaging is rebalancing procurement patterns among municipal water authorities and food processors. Tata Chemicals Ltd leverages its integrated soda ash-alumina supply chain to dominate bulk powder contracts across South Asian utilities. Merck KGaA differentiates through pharmaceutical-grade certification and controls high-purity channels for laboratory reagents in European markets.
Aluminium potassium sulphate is a double salt with the formula KAl(SO4)2·12H2O, manufactured through alumina dissolution in sulfuric acid followed by potassium sulfate crystallization at controlled temperatures between 60–80°C; it functions primarily as a coagulating agent, pH buffer, and astringent across industrial and consumer applications. Powder formulations occupy the largest volume share due to ease of dissolution in water treatment basins, while liquid concentrates represent the fastest-expanding configuration as automated dosing systems displace manual bag-handling at municipal plants. Agriculture applications anchor steady offtake through fertilizer manufacturers seeking sulfur and potassium enrichment for alkaline soil correction.
EPA drinking water standards and MEE discharge limits in China are tightening permissible turbidity thresholds, directly expanding alum consumption at upgrade-lagging treatment facilities. REACH registration requirements in Europe and BIS certification mandates in India are raising formulation purity barriers that filter out unqualified regional blenders. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory as compliance specifications harden.
Market Dynamics
Municipal water utilities across Southeast Asia and industrial discharge facilities in China are accelerating alum-based coagulation upgrades as turbidity standards tighten, forcing chemical procurement toward certified high-purity formulations and automated dosing infrastructure.
Growth Catalysts
- EPA turbidity mandates:US drinking water facilities must achieve sub-0.3 NTU clarity thresholds, expanding alum consumption at aging treatment plants lacking advanced filtration.
- Soil health programs:India's state-sponsored potassium-sulfur enrichment initiatives in the northern agricultural belt are concentrating fertilizer-grade offtake among regional blending cooperatives.
- Automated dosing systems:Liquid concentrate configurations are capturing share from manual bag-handling as municipal plants modernize chemical feed infrastructure.
Market Restraints
- Sulfuric acid price volatility:Feedstock cost swings constrain margin stability for alumina-dissolution processors dependent on spot sulfur markets.
- REACH registration barriers:European formulation purity requirements filter out unqualified regional blenders, consolidating supply among certified chemical majors.
- Polyaluminum chloride substitution:PAC coagulants offer lower sludge volumes at comparable dosing efficiency, pressuring alum in high-throughput industrial applications.
Strategic Opportunities
- Philippines municipal expansion:Metro Manila water authority capex programs for new treatment capacity create first-mover openings for certified bulk suppliers.
- Pharmaceutical-grade channels:Laboratory reagent certification unlocks premium pricing in European life-science procurement networks.
- Modular dosing-unit packaging:Pre-calibrated concentrate pods reduce on-site handling labor, aligning with food processor hygiene protocols.
Industry Challenges
- BIS certification timelines:Indian purity testing protocols extend product approval cycles, stranding inventory for exporters lacking pre-qualified formulations.
- Legacy basin retrofit compatibility:Automated liquid feed systems require concrete infrastructure modifications that delay upgrade decisions at budget-constrained utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Potassium Sulphate Market |
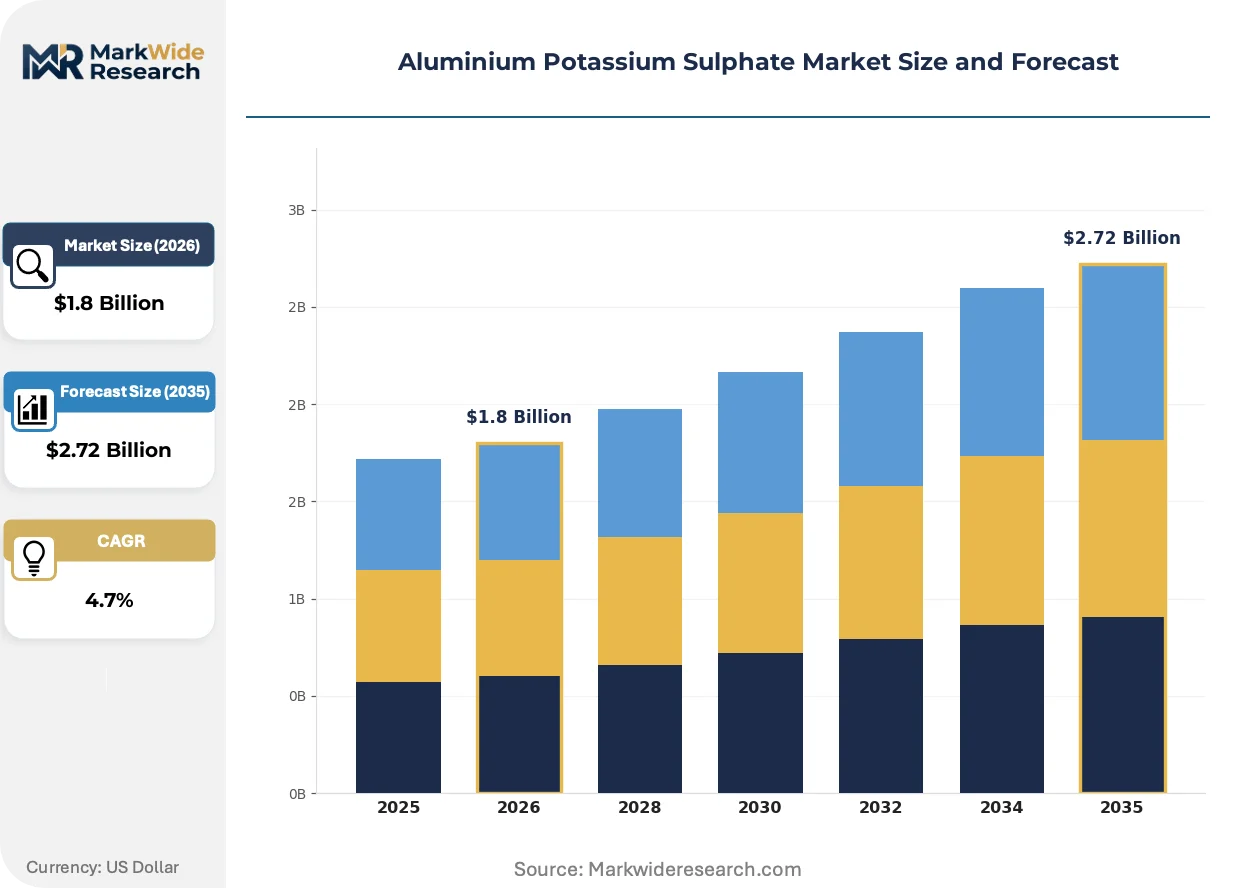
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Block, Liquid Application: Water Treatment, Food Industry, Pharmaceuticals, Agriculture End User: Municipalities, Food Processing Plants, Labs, Fertilizer Manufacturers Packaging Type: Bags, Drums, Bulk, Containers |
| Companies Covered | Tata Chemicals Ltd, Aluminium Corporation of China Ltd, Merck KGaA, Sigma-Aldrich, Thermo Fisher Scientific, Holland Company, Baslini SpA, Nanjing Jiayi Sunway Chemical, Zibo Dazhong Edible Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Potassium Sulphate Market Strategic Shifts
Formulation standardization and feed-system automation are compressing procurement cycles while regulatory divergence between jurisdictions is fragmenting compliance specifications.
Continuous crystallization control technology is integrating real-time temperature and saturation monitoring into alumina-dissolution processes. Municipal utilities in Thailand and Vietnam are piloting these systems to reduce batch-to-batch purity variance. The technology is integrating quality assurance directly into production workflows, compressing third-party testing costs for bulk contractors.
China's MEE discharge limit revisions are forcing industrial plants to upgrade chemical dosing precision or face operating suspensions. The regulations mandate continuous effluent turbidity monitoring with automated alum feed adjustment. Steel and textile processors in the Yangtze River basin are most exposed, accelerating capital commitments to liquid concentrate infrastructure.
Volume-commitment contracting is displacing spot purchasing among Southeast Asian water authorities seeking price predictability across multi-year infrastructure cycles. Bulk powder suppliers are responding with tiered pricing structures tied to minimum offtake guarantees. This shift is most visible in Indonesia's provincial utility consolidation programs.
Aluminium Potassium Sulphate Market Segmentation
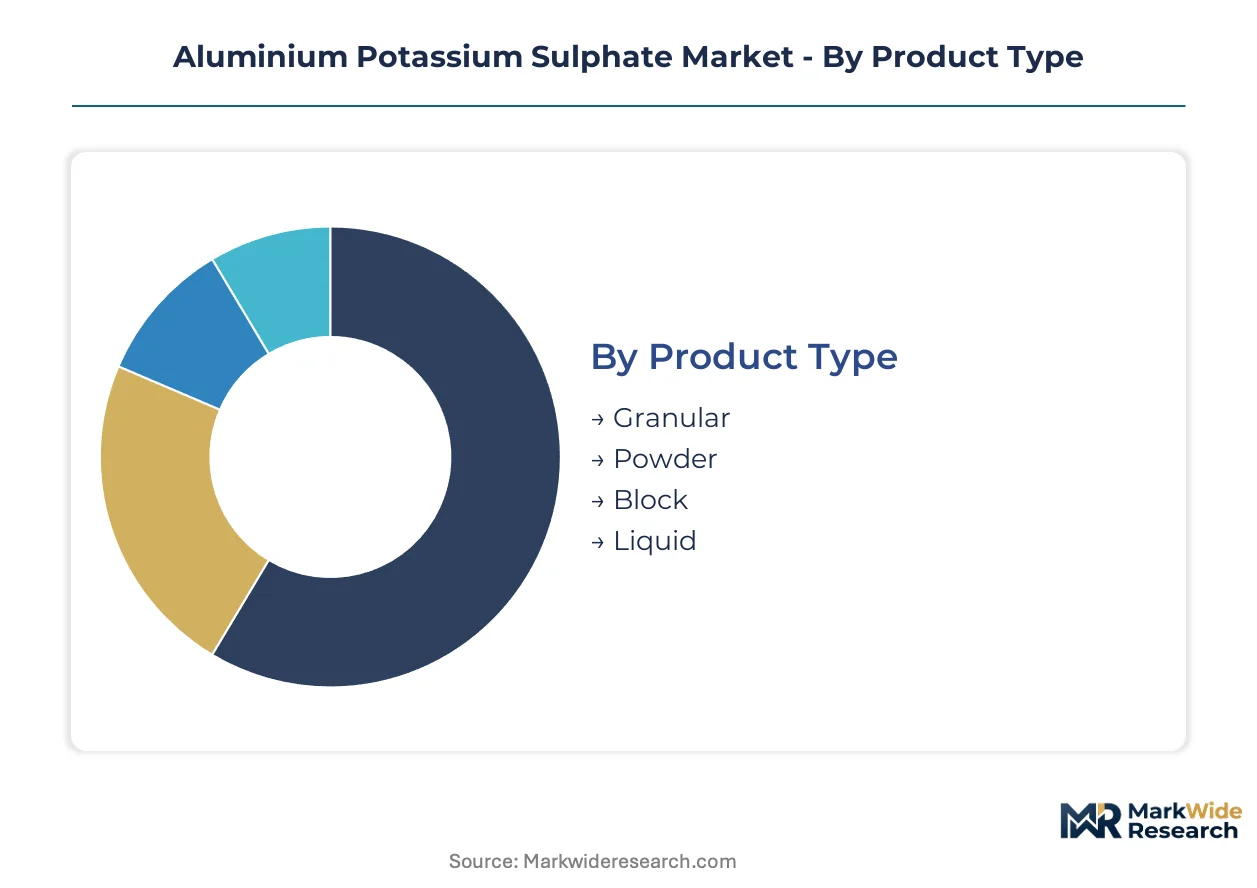
Aluminium potassium sulphate procurement patterns diverge sharply between bulk commodity buyers and precision-dosing end users. Each segment category reflects distinct technical specifications, handling requirements, and regulatory compliance thresholds that reshape supplier positioning.
Product Type:
Powder and granular formulations dominate standalone coagulation applications, while liquid concentrates embed directly into automated feed systems requiring minimal on-site preparation.
- Powder:Fine crystalline particles dissolve rapidly in water treatment basins, supporting manual bag-handling operations at aging municipal facilities. Demand concentrates across Southeast Asian utilities where infrastructure budgets constrain automated system upgrades.
- Granular:Larger crystal structures reduce dust exposure during handling and enable precise volumetric dosing in agricultural blending operations. Indian fertilizer cooperatives in the northern agricultural belt favor this format for soil amendment programs.
- Liquid:Pre-dissolved concentrates integrate with automated chemical feed infrastructure, eliminating dissolution tanks and reducing labor exposure. China's MEE-mandated turbidity monitoring systems accelerate uptake at industrial discharge plants.
- Block:Compressed solid forms serve niche applications requiring extended dissolution control, primarily in small-scale food processing and traditional water purification methods.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
Application:
Water treatment applications anchor baseline demand through regulatory-mandated turbidity compliance, while pharmaceutical and food segments command premium pricing through purity certification requirements.
- Water Treatment:Coagulating agent for turbidity removal at municipal and industrial facilities, with EPA-mandated sub-0.3 NTU thresholds expanding consumption at upgrade-lagging plants. Southeast Asian utilities drive procurement concentration as drinking water standards tighten.
- Agriculture:Potassium-sulfur fertilizer component for alkaline soil correction, with India's state-sponsored soil health programs concentrating offtake among regional blending cooperatives.
- Food Industry:pH buffer and firming agent in pickling and baking applications, requiring food-grade certification under FSSAI and FDA protocols.
- Pharmaceuticals:Astringent and laboratory reagent applications demanding pharmaceutical-grade purity under REACH and BIS certification mandates.
Water Treatment captures the largest volume commitment; Agriculture maintains the steadiest replacement-cycle demand.
End User:
Municipal procurement operates through multi-year volume contracts, while laboratory and food processing buyers prioritize certified purity over unit economics.
- Municipalities:Bulk water treatment authorities across Thailand, Vietnam, and Indonesia consolidate purchasing through provincial utility programs, favoring powder formats with tiered pricing tied to minimum offtake guarantees.
- Fertilizer Manufacturers:Regional blending cooperatives in India's northern states procure granular grades for potassium-enhanced fertilizer production under government soil health initiatives.
- Food Processing Plants:Hygiene-protocol-driven facilities in Europe and North America specify pre-calibrated concentrate pods to reduce on-site handling labor and contamination risk.
- Labs:European life-science procurement networks demand pharmaceutical-grade certification, unlocking premium pricing channels for high-purity reagent suppliers.
Municipalities dominate absolute tonnage; Labs command the highest purity premiums per kilogram.
Packaging Type:
Bulk and bag formats serve high-volume, low-frequency procurement patterns, while drum and container configurations align with precision-dosing and hygiene-sensitive applications.
- Bulk:Tanker and silo deliveries support continuous-feed operations at large municipal treatment plants and fertilizer manufacturing facilities, minimizing per-unit handling costs.
- Bags:25-50 kg woven polypropylene sacks remain standard for manual handling at budget-constrained utilities, though labor costs and dust exposure drive gradual displacement.
- Drums:Sealed steel or plastic containers protect liquid concentrate integrity during transport and storage, meeting food processor and pharmaceutical distributor hygiene protocols.
- Containers:Intermediate bulk containers and modular dosing-unit pods reduce on-site preparation labor, aligning with automated feed system requirements at modernized treatment facilities.
Bags retain the widest installed base; Containers are climbing the fastest as automation investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates alumina feedstock production while India and Southeast Asian nations drive consumption through water infrastructure and agricultural programs. The production-consumption divide creates trade flows from mineral-rich suppliers to processing and application markets.
China
Industrial discharge facilities in the Yangtze River basin face MEE-mandated turbidity monitoring with automated alum feed adjustment. Steel and textile processors accelerate capital commitments to liquid concentrate infrastructure under revised environmental compliance protocols. Zibo and Nanjing chemical clusters concentrate alumina-dissolution capacity serving domestic and export markets.
India
State-sponsored soil health programs in the northern agricultural belt concentrate fertilizer-grade offtake among regional blending cooperatives. BIS certification mandates extend product approval cycles for exporters lacking pre-qualified formulations. Gujarat and Maharashtra host integrated soda ash-alumina supply chains supporting bulk powder contracts.
Thailand
Municipal water authorities pilot continuous crystallization control technology to reduce batch-to-batch purity variance. Provincial utility consolidation programs shift procurement toward volume-commitment contracting with tiered pricing tied to minimum offtake guarantees. Bangkok metropolitan treatment facilities drive automated dosing system adoption.
Vietnam
Municipal utilities integrate real-time temperature and saturation monitoring into alumina-dissolution processes under quality assurance modernization. Drinking water standard tightening expands alum consumption at upgrade-lagging treatment plants. Ho Chi Minh City and Hanoi water authorities lead powder-to-liquid configuration transitions.
Indonesia
Provincial utility consolidation programs concentrate purchasing through multi-year volume contracts favoring certified bulk suppliers. Infrastructure budget constraints sustain manual bag-handling operations at aging municipal facilities. Java-based treatment plants anchor procurement concentration as turbidity standards tighten.
Aluminium Potassium Sulphate Market Competitive Environment
The competitive structure tilts toward integrated chemical majors with captive alumina supply and certified high-purity specialists serving regulated channels. Tiered concentration separates bulk commodity suppliers from precision-dosing formulators. Strategic archetypes include backward-integrated soda ash producers, pharmaceutical-grade certification holders, and regional blending cooperatives. Dominant competitive moves encompass capacity expansion in alumina-dissolution clusters and geographic licensing partnerships for automated dosing technology.
Among Asia-Pacific integrated producers, Tata Chemicals Ltd and Aluminium Corporation of China Ltd exemplify scale-driven archetypes with upstream control over critical feedstocks. Merck KGaA occupies a position within the premium-tier certification vector, representing pharmaceutical-grade specialists that unlock pricing power through REACH-compliant reagent channels. These three anchors illustrate how supply chain configuration and regulatory certification stratify competitive positioning across commodity and precision market segments.
| Leading Market Players |
|---|
| Tata Chemicals Ltd |
| Aluminium Corporation of China Ltd |
| Merck KGaA |
| Sigma-Aldrich |
| Thermo Fisher Scientific |
| Holland Company |
| Baslini SpA |
| Nanjing Jiayi Sunway Chemical |
| Zibo Dazhong Edible Chemical |
| Others |
Value Chain & Pricing Dynamics
Specialized crystallization technicians in Gujarat and Zibo command wage premiums that compress margin spreads between pharmaceutical-grade and industrial-grade alum tiers. Labor-cost differentials between automated liquid-concentrate facilities and manual powder-handling operations drive pricing stratification across Southeast Asian procurement contracts.
Pricing Analysis
Margin tightening in industrial-grade powder reflects sulfuric acid spot-market volatility and feedstock cost pass-through limitations. Three-tier pricing structure across pharmaceutical-grade, water-treatment-certified, and agricultural-grade levels separates purity-premium channels from commodity spot transactions. Pricing pressure intensifies in bulk municipal contracts as volume-commitment contracting displaces spot purchasing. Fertilizer cooperatives in India's northern belt exhibit highest price sensitivity; European laboratory reagent buyers show least elasticity due to REACH-mandated certification barriers.
Supply Chain Analysis
REACH and BIS certification requirements filter unqualified blenders from pharmaceutical and food-grade channels, consolidating supply among pre-qualified chemical majors. Production concentrates in China, India, and Germany, with alumina dissolution capacity clustering around Zibo, Nanjing, and Gujarat chemical parks. Feedstock supply draws from bauxite refining, sulfuric acid spot markets, and potassium sulfate producers. Single-source vulnerability in alumina feedstock creates exposure to mineral export restrictions. Distribution runs through bulk tanker deliveries to municipal utilities, drum shipments to food processors, and sealed-container channels to pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alumina dissolution capacity constraints in certified facilities prop pricing premiums, as MEE-mandated turbidity monitoring and REACH registration timelines limit rapid supply expansion.
For Market Incumbents: Cement backward integration into captive alumina supply to defend against sulfuric acid price volatility and polyaluminum chloride substitution threats. Expand automated liquid-concentrate capacity in Thailand and Vietnam to capture municipal automation upgrade cycles. Secure BIS pre-certification for Indian export formulations to compress approval timelines. For New Entrants and Emerging Players: Begin with modular dosing-unit packaging for European food processors seeking hygiene-protocol compliance and labor-cost reduction. Target Philippines municipal expansion programs where Metro Manila capex creates first-mover openings for certified bulk suppliers. Pursue pharmaceutical-grade certification as the primary go-to-market angle to unlock premium pricing in life-science procurement networks. For Investors and Strategic Acquirers: Re-rating potential sits with integrated soda ash-alumina producers given potassium-sulfur fertilizer demand acceleration under India's soil health programs. Long-term viability favors backward-integrated chemical majors with captive feedstock and multi-jurisdiction certification portfolios. Watch for MEE enforcement actions against Yangtze River basin discharge facilities as inflection signal for liquid-concentrate infrastructure investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Supply | Captive bauxite refining insulates margin from sulfuric acid spot volatility. |
| Automated Liquid Concentrate Capacity Expansion | Thailand and Vietnam municipal automation upgrades drive configuration shift from powder. |
| Pharmaceutical-Grade Certification Investment | REACH compliance unlocks premium laboratory reagent channels in European life-science networks. |
| Long-term Volume Commitment Contracting | Indonesian provincial utility consolidation programs favor tiered pricing with minimum offtake guarantees. |
| Joint Venture for Modular Dosing Technology | Pre-calibrated concentrate pods align with European food processor hygiene protocols and labor reduction targets. |
Study Parameters
Trade databases, chemical industry association publications, and regulatory filing repositories formed the secondary backbone for supply-side capacity mapping. Primary interviews with alumina dissolution plant managers, municipal water authority procurement leads, fertilizer cooperative blending directors, and pharmaceutical reagent distributors combined with secondary validation through customs records and MEE discharge monitoring disclosures. Bottom-up facility capacity tallies and top-down end-use consumption estimates underwent cross-triangulation.
Historical trendline analysis of alum consumption against turbidity standard tightening episodes informed projection elasticity assumptions across the analysis window. Segmentation modeling incorporated product type, application grade, end-user procurement pattern, and regional regulatory cluster dimensions. CAGRs derived from slope-consistency checks against infrastructure investment cycle timing and certification pipeline backlogs. Sulfuric acid price volatility bands and MEE enforcement intensity scenarios served as sensitivity inputs.
Feedstock cost spikes, regulatory enforcement acceleration, and polyaluminum chloride substitution adoption are the dominant revision risks to alum demand trajectories. Forecasts reflect documented assumptions on infrastructure upgrade lag times and certification approval durations. A model refresh is warranted upon material change in MEE discharge limit revision timelines or REACH registration requirement amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Talc Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Asia Pacific Bentonite Market
Industrial Minerals
Europe Frac Sand Market